
 Global Automotive Oem Market | 2026-2036
Global Automotive Oem Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Oem Market Analysis
Direct sales channels is reconfiguring how automakers engage end buyers and manage pricing authority. Volkswagen Group leverages its ID platform to sustain vertical control over battery supply and software stacks. Toyota Motor Corporation anchors hybrid system dominance through in-house production of power-split devices and thermal management components. Hyundai Motor Company competes on manufacturing scale across its Ulsan and Georgia plants, balancing cost discipline with flexible architecture.
Automotive OEM denotes original equipment manufacturers that design, engineer, and assemble complete vehicles or major subsystems for commercial sale, typically operating stamping presses with tolerances of 0.1 millimeters and robotic welding lines exceeding 90 percent automation. These entities supply transportation assets to fleet operators, rental networks, and retail consumers while adhering to crash-test protocols and emissions certification regimes. The electrification segment is capturing disproportionate capital allocation as lithium-ion cell integration and thermal runaway prevention become core engineering competencies, while connected vehicles generates recurring software revenue streams that alter traditional hardware-centric margin structures. Hybrid systems retains volume leadership in markets where charging infrastructure remains sparse and grid reliability varies.
The EPA enforces Corporate Average Fuel Economy standards that mandate fleet-wide efficiency improvements, compelling Detroit and European transplants to reallocate engineering resources toward zero-emission architectures. NHTSA crashworthiness protocols and the EU AI Act's algorithmic transparency requirements for autonomous functions are creating dual compliance burdens for software-defined vehicle programs. EMA and REACH chemical restrictions on interior materials further constrain supplier selection across European assembly networks. Stakeholders must monitor how battery passport traceability rules and divergent national subsidy schemes reshape sourcing geography and capital deployment priorities.
Market Dynamics
Powertrain electrification is compressing engineering timelines across assembly networks, forcing OEMs to retool stamping lines and recalibrate supplier contracts around cell chemistry specifications rather than mechanical component tolerances.
Growth Catalysts
- EU Green Deal mandates:Binding CO2 fleet targets are accelerating zero-emission platform development across Stuttgart, Wolfsburg, and Turin engineering centers.
- Lithium-ion cost curves:Cell pack economics below $100 per kilowatt-hour are unlocking fleet procurement contracts from Southeast Asian logistics operators.
- Yangtze River Delta clustering:Co-located battery gigafactories and stamping facilities are compressing logistics spend for domestic and joint-venture OEMs.
Market Restraints
- Chokepoint concentration in cathode precursors:Indonesian nickel and DRC cobalt refining bottlenecks expose OEMs to geopolitical supply interruptions.
- REACH chemical compliance:ECHA restrictions on interior adhesives and flame retardants are forcing supplier switches with 18-month requalification cycles.
- Grid reliability variance:Intermittent power infrastructure in secondary Indian and Brazilian markets caps pure-electric penetration rates.
Strategic Opportunities
- Software-defined vehicle architectures:Over-the-air update revenue streams are displacing traditional three-year model cycles with continuous monetization.
- Thai and Vietnamese fleet electrification:Government incentive schemes are opening procurement channels for regional assembly joint ventures.
- Battery passport traceability:EU regulatory requirements are creating first-mover advantages for OEMs with integrated cell-to-vehicle data systems.
Industry Challenges
- Power electronics talent scarcity:SiC inverter design and thermal runaway simulation expertise commands premium wages across Munich, Detroit, and Shanghai.
- Dual-homologation burdens:Simultaneous NHTSA FMVSS and EU AI Act compliance for autonomous functions is stretching validation budgets.
- Legacy powertrain decommissioning:Tooling amortization on internal combustion lines conflicts with accelerated EV capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Oem Market |
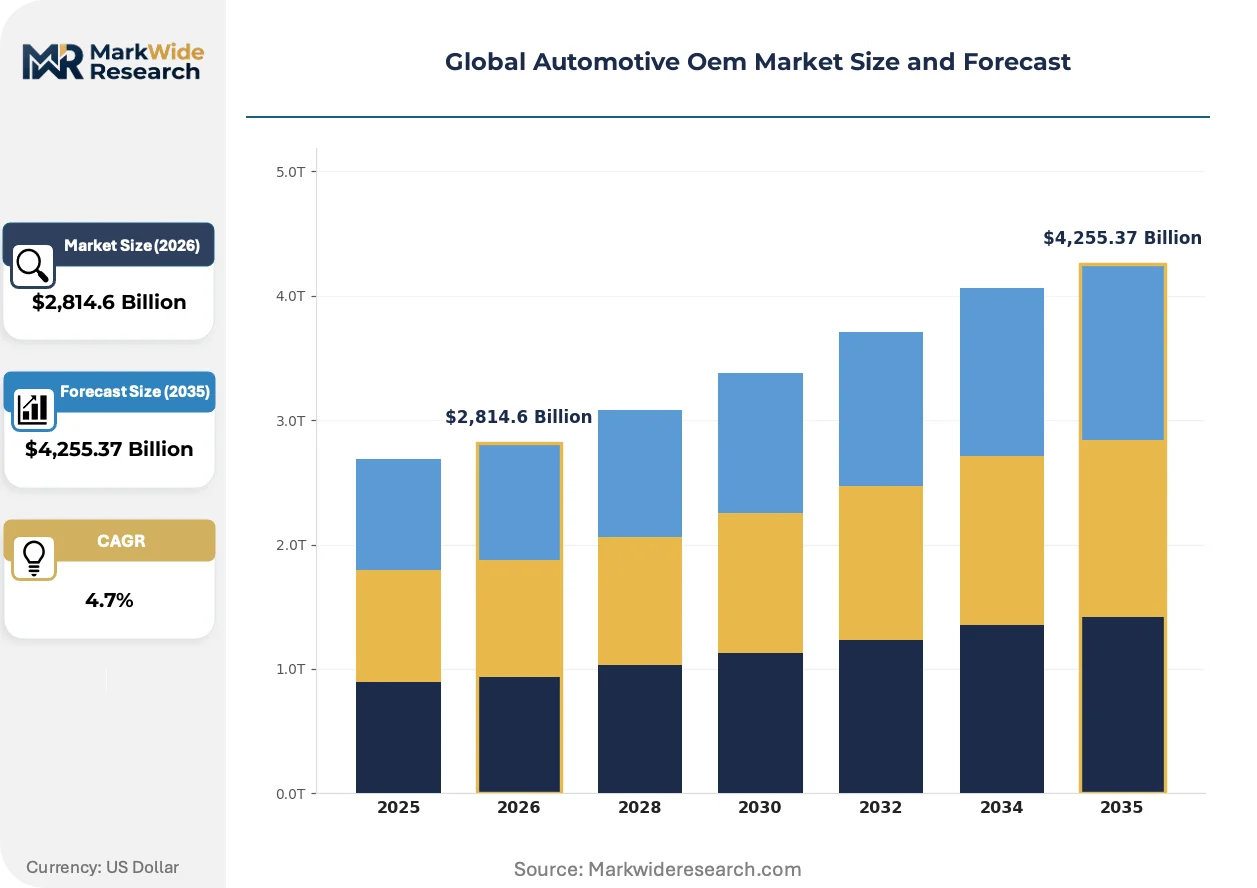
| Market Size in 2026 | $2,814.6 Billion |
| Market Size in 2035 | $4,255.37 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vehicles, Parts, Accessories, Systems End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: Electrification, Autonomous Driving, Connected Vehicles, Hybrid Systems Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Toyota Motor Corporation, Volkswagen Group, Mercedes-Benz Group AG, General Motors, Stellantis, Hyundai Motor Company, Ford Motor Company, Honda Motor Co., Ltd., BMW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Oem Market Emerging Trajectories
Software integration is redefining vehicle architecture boundaries, merging powertrain control with infotainment stacks and collapsing traditional tiered supplier hierarchies into direct OEM-component relationships.
Solid-state electrolyte research is hybridizing conventional lithium-ion manufacturing with ceramic deposition techniques. Korean and Japanese cell producers are piloting sulfide-based prototypes for 2028 platform integration. This convergence is hybridizing safety margins and energy density targets previously treated as trade-offs.
The EU AI Act's algorithmic transparency requirements are mandating explainability documentation for autonomous emergency braking and lane-keeping systems. German KBA type-approval procedures now incorporate third-party audit trails for neural network decision paths. Premium segment vehicles face the heaviest documentation burdens, compressing development timelines by four to six months.
Fleet procurement departments are consolidating vehicle sourcing through direct OEM relationships, bypassing traditional dealer networks for volume electrified van and truck contracts. Subscription-based maintenance bundles are displacing per-service billing in German and Dutch logistics markets. This channel compression is most visible in last-mile delivery verticals where total cost of ownership calculations dominate specification sheets.
Global Automotive Oem Market Segmentation
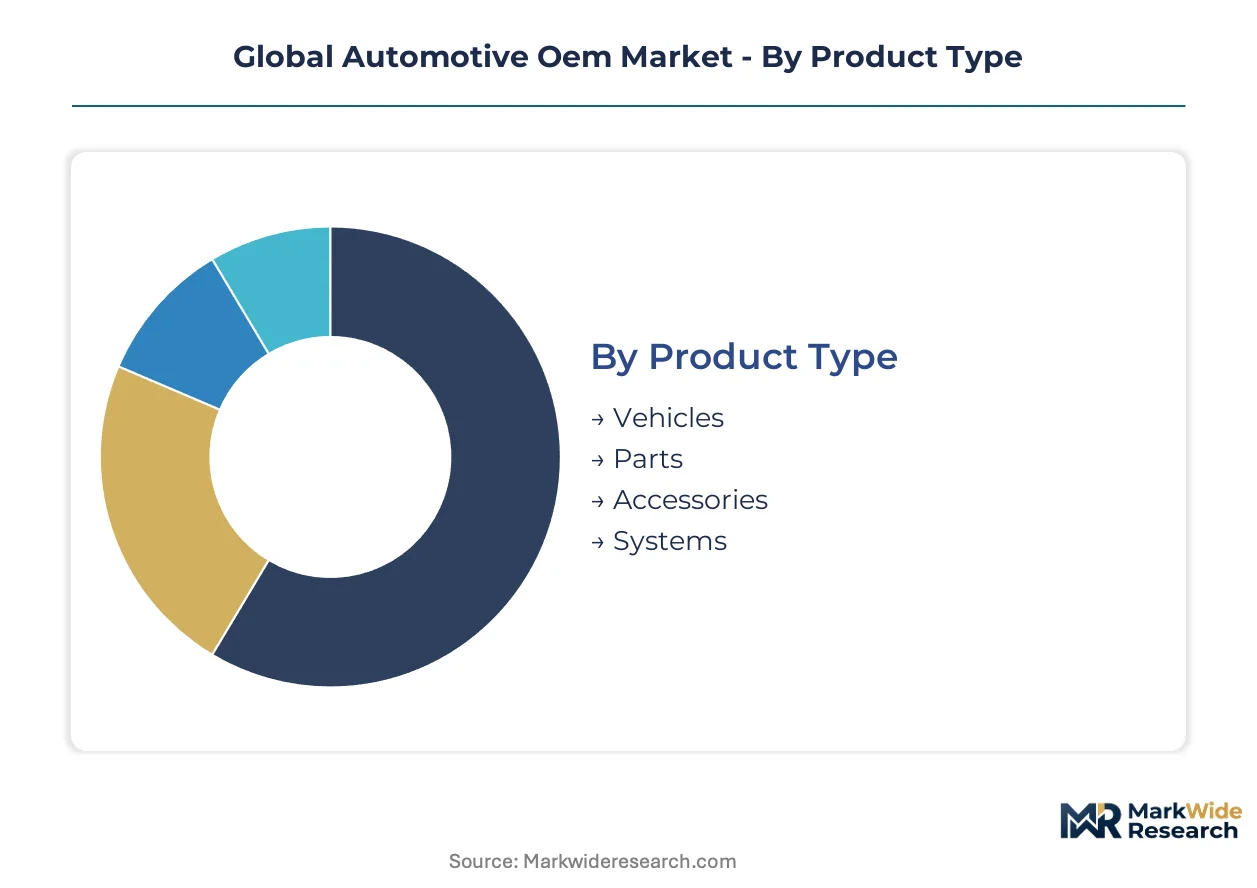
Segmentation in automotive OEM markets reveals how capital allocation, regulatory pressure, and supply chain configuration concentrate across distinct product and technology boundaries. Understanding these divisions exposes where margin pools are shifting and which channels are capturing pricing authority.
Product Type:
Mature stamped-metal assemblies coexist with emerging software-integrated systems as engineering priorities diverge across legacy and electrified platforms.
- Vehicles:Complete assembled automobiles, light trucks, and commercial vehicles carrying powertrain, body-in-white, and electronic architectures from factory gates to fleet operators. Demand concentrates in China's Yangtze River Delta cluster where domestic OEMs and foreign joint ventures co-locate assembly with battery gigafactories, compressing logistics spend as cell pack economics fall below critical thresholds.
- Parts:Stamped body panels, cast powertrain components, and injection-molded interior modules produced to OEM specification with 0.1-millimeter tolerances on robotic press lines. Procurement is shifting toward modular subassemblies as Volkswagen Group and Hyundai Motor Company consolidate supplier tiers around integrated battery housings and thermal management units.
- Accessories:Dealer-fit and port-installed add-ons including infotainment upgrades, exterior styling packages, and connected service subscriptions.
- Systems:Integrated functional modules spanning braking, steering, and thermal management delivered as pre-tested assemblies.
Vehicles handles the majority of throughput; Systems is gaining share fastest as OEMs outsource integrated module development to capture electrification speed-to-market.
End User:
Customer type determines contract structure, with direct OEM relationships commanding volume pricing and aftermarket channels capturing margin through fragmented service networks.
- OEMs:Original equipment manufacturers that design, engineer, and assemble complete vehicles for commercial sale, operating stamping presses and robotic welding lines exceeding 90 percent automation. These entities anchor demand for high-volume contracts with multi-year tooling amortization schedules and direct supplier engineering integration.
- Aftermarket Providers:Independent repair networks, parts distributors, and remanufacturing specialists serving vehicles post-warranty. Demand clusters in markets with aging fleet populations where EPA emissions certification and NHTSA safety protocols create replacement part requirements independent of new vehicle sales cycles.
- Tier-1 Suppliers:Direct component and system providers shipping to OEM assembly lines under just-in-sequence contracts.
- Dealerships:Franchise and independent retail networks handling final customer delivery and service capture.
OEMs command the dominant procurement volume; Aftermarket Providers expand most quickly as average vehicle age extends across North American and European parc.
Technology:
Technology segmentation tracks where engineering talent and capital deployment concentrate as powertrain architectures diverge from mechanical to electrochemical and software-defined systems.
- Electrification:Battery-electric and fuel-cell platforms integrating lithium-ion cells, thermal runaway prevention systems, and power electronics. Development timelines compress as EU Green Deal mandates force Stuttgart, Wolfsburg, and Turin engineering centers toward zero-emission architectures, while Southeast Asian fleet operators expand procurement with declining battery costs.
- Autonomous Driving:Sensor fusion, neural network perception stacks, and redundant actuation systems for SAE Level 2 through Level 4 functionality. EU AI Act algorithmic transparency requirements and German KBA third-party audit trails for neural network decision paths extend validation timelines by four to six months for premium segment programs.
- Connected Vehicles:Over-the-air update architectures, telematics gateways, and subscription-based feature monetization.
- Hybrid Systems:Power-split devices, thermal management components, and dual-powertrain integration retaining volume leadership in markets with sparse charging infrastructure.
Electrification absorbs the largest capital allocation; Connected Vehicles climbs fastest on recurring software revenue streams displacing traditional hardware-centric margin structures.
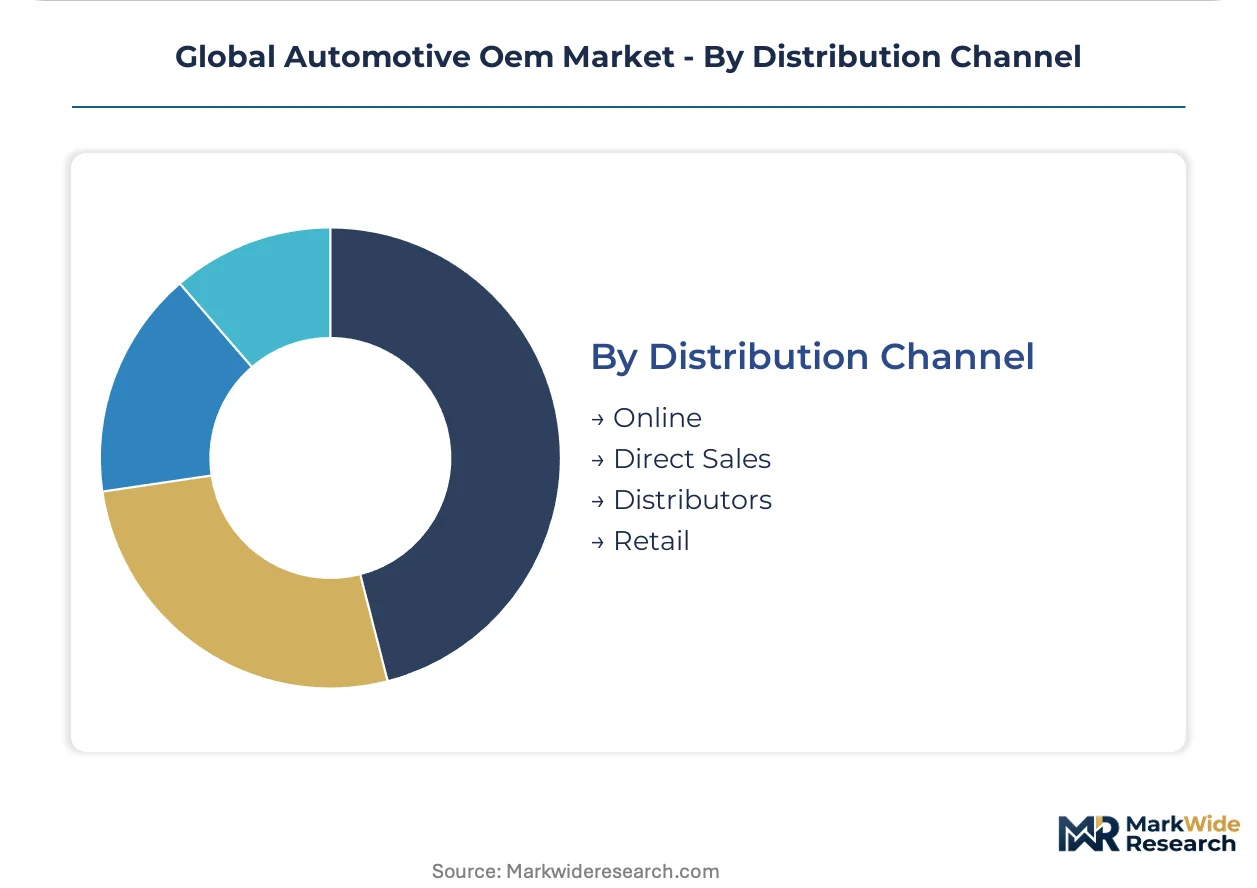
Distribution Channel:
Channel structure determines pricing authority and customer data ownership, with direct sales eroding traditional dealer network intermediation.
- Direct Sales:Manufacturer-owned channels including brand stores, online configurators, and fleet account management bypassing independent dealers. Volkswagen Group leverages its ID platform to sustain vertical control over battery supply and software stacks, capturing end-buyer relationships and pricing authority previously fragmented through franchise networks.
- Online:Digital-first purchase journeys with home delivery or pickup-point fulfillment, accelerated by fleet procurement departments consolidating sourcing through direct OEM relationships for volume electrified van and truck contracts.
- Distributors:Regional wholesalers holding inventory for independent repair shops and smaller dealers.
- Retail:Traditional franchise dealership networks with physical showrooms and service bays.
Direct Sales commands expanding share in electrified segments; Online shows the steepest trajectory as last-mile delivery fleets prioritize total cost of ownership calculations over physical inspection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's engineering centers while procurement volume gravitates toward China's Yangtze River Delta cluster, creating a geographic asymmetry that shapes capital allocation and supplier contract terms across the forecast window.
China
Domestic OEMs and foreign joint ventures co-locate assembly with battery gigafactories in the Yangtze River Delta cluster, compressing logistics spend as cell pack economics fall below critical procurement thresholds. MIIT dual carbon goals and GB standards enforcement accelerate zero-emission platform development timelines. Shanghai and Suzhou house the densest concentration of stamping facilities and power electronics module suppliers serving both export and domestic fleet contracts.
Germany
Stuttgart, Wolfsburg, and Munich engineering centers anchor powertrain redesign efforts driven by EU Green Deal CO2 fleet mandates and KBA type-approval protocols. The EU AI Act's algorithmic transparency requirements extend validation timelines for autonomous functions by four to six months. Bavaria and Baden-Württemberg concentrate SiC inverter design talent and thermal runaway simulation expertise commanding premium wages across the supplier base.
United States
Detroit transplants and domestic OEMs reallocate engineering resources toward zero-emission architectures under EPA Corporate Average Fuel Economy enforcement and NHTSA FMVSS crashworthiness protocols. Michigan and Ohio retain stamping press clusters with 0.1-millimeter tolerances, though Georgia and Tennessee gain assembly capacity as Southeast Asian battery supply chains extend into North American logistics networks.
Japan
Toyota City and Nagoya engineering centers sustain hybrid system dominance through in-house production of power-split devices, while METI industrial policy directs capital toward solid-state electrolyte research. Osaka and Kyoto prefectures host sulfide-based cell prototyping facilities targeting 2028 platform integration. JIS standards compliance and domestic supplier keiretsu relationships insulate procurement from cathode precursor chokepoint exposure.
South Korea
Ulsan and Gyeonggi-do assembly complexes balance manufacturing scale with flexible architecture deployment across electrified and hybrid platforms. MFDS regulatory alignment with EU battery passport traceability requirements positions domestic OEMs for first-mover advantage in integrated cell-to-vehicle data systems. Seoul Capital Area concentrates connected vehicle software development and over-the-air update architecture engineering.
Global Automotive Oem Market Vendor Landscape
Scale-driven conglomerates and technology-integrated specialists split the market into distinct competitive spheres with divergent margin capture mechanisms. Consolidation pressures concentrate around battery supply security and software stack ownership, while fragmentation persists in regional assembly joint ventures serving fleet procurement. Three archetypes dominate: vertically integrated platform owners controlling cell chemistry and thermal management, manufacturing-scale operators balancing cost discipline with flexible architecture, and hybrid-system specialists retaining volume leadership in charging-constrained markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with OEMs securing cathode precursor offtake agreements and forming cross-border joint ventures for Southeast Asian market access.
Among Germany-based platform owners, Mercedes-Benz Group AG and BMW Group occupy positions emphasizing engineering integration and premium-tier pricing authority. Volkswagen Group exemplifies the vertically integrated archetype through captive control over battery supply chains and software-defined vehicle architectures. Toyota Motor Corporation anchors the hybrid-system specialist tier, while Hyundai Motor Company and General Motors represent manufacturing-scale operators with multi-continental assembly footprints. Ford Motor Company and Stellantis sit within the transitional archetype straddling legacy powertrain decommissioning and accelerated EV capital redeployment. Honda Motor Co., Ltd. occupies a specialized position in power electronics and thermal management component sourcing.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volkswagen Group |
| Mercedes-Benz Group AG |
| General Motors |
| Stellantis |
| Hyundai Motor Company |
| Ford Motor Company |
| Honda Motor Co., Ltd. |
| BMW Group |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta maritime corridor compresses inbound cathode precursor freight costs while amplifying price differentiation between configured-to-order electric platforms and standard internal combustion trims. Battery pack cost curves below critical procurement thresholds enable OEMs to sustain margin capture on customized electrified variants even as base-model pricing faces compression from Southeast Asian fleet aggregation.
Pricing Analysis
Configured-to-order electrified platforms command substantial premiums over standard internal combustion trims, with differentiation driven by battery capacity tier and EU AI Act compliance certification level. Three-tier pricing structure across premium, standard, and economy levels stratifies according to thermal management sophistication and over-the-air update capability. Pricing pressure stems from Southeast Asian logistics operators consolidating procurement through direct OEM fleet contracts. Fleet buyers exhibit highest price sensitivity, while retail consumers in German and Dutch markets accept premium positioning for autonomous feature bundles.
Supply Chain Analysis
Contract manufacturing capacity concentrates at Hyundai Motor Company's Ulsan complex, Volkswagen Group's Wolfsburg assembly network, and Toyota Motor Corporation's Nagoya-area keiretsu facilities. Geographic supply concentration centers on China, South Korea, and Germany for cell chemistry integration, with Indonesia and DRC anchoring nickel and cobalt precursor refining. Raw material dependencies rest on lithium carbonate, cathode active materials, and silicon carbide wafers for power electronics. Single-source vulnerability in DRC cobalt refining exposes OEMs to geopolitical interruption. Distribution runs through direct OEM fleet channels and traditional franchise networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Automotive Oem Market sits in a cyclical recovery phase as battery cost curves and EU Green Deal enforcement compress replacement demand timelines for legacy powertrain fleets.
For Market Incumbents: Insulate cell supply security through captive offtake agreements with Indonesian nickel and Australian lithium producers, while accelerating software-defined vehicle architecture investment to defend against Chinese OEM subscription revenue capture. Decommission internal combustion tooling on accelerated schedules to free capital for zero-emission platform redeployment. Prioritize backward integration into thermal management component production. For New Entrants and Emerging Players: Mid-market commercial fleet electrification in Thailand and Vietnam represents the most penetrable entry point, where government incentive schemes and sparse incumbent direct-sales presence create procurement channel white space. Battery-swapping infrastructure for last-mile delivery vans offers differentiated positioning against established OEM fast-charging dependencies. Pursue joint venture structures with regional assembly operators to bypass capital-intensive greenfield stamping investments. For Investors and Strategic Acquirers: Solid-state electrolyte research specialists with sulfide-based prototyping capabilities and Korean or Japanese regulatory alignment offer asymmetric upside as 2028 platform integration timelines firm. Long-term viability hinges on differentiation in thermal runaway prevention and power electronics module design rather than assembly scale alone. Monitor EU battery passport traceability rule implementation cadence as inflection indicator for first-mover data system advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode precursor offtake from Indonesian nickel refiners amid DRC concentration risk. |
| Software-Defined Vehicle Investment | Enables over-the-air revenue streams that displace three-year hardware replacement cycles. |
| Geographic Manufacturing Footprint | Georgia and Tennessee capacity captures Southeast Asian cell supply chain extension into North America. |
| Platform Standardization | Compresses engineering timelines across Volkswagen Group ID architecture and derivative models. |
| Charging Infrastructure Partnership | Addresses grid reliability variance caps on pure-electric penetration in Brazilian and Indian secondary markets. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution operators, and fleet procurement managers, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC automotive division filings, and EU regulatory submission repositories. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from elasticity-adjusted volume projections incorporating battery cost curve trajectories and regulatory enforcement intensity assumptions. Forecast inputs included EU Green Deal CO2 fleet mandate compliance schedules and Southeast Asian government incentive scheme durability.
Macroeconomic conditions sit as an overlay; deviation in lithium spot price volatility, euro-dollar exchange rate movements, or Chinese domestic demand intensity would shift the trajectory. Forecasts reflect documented assumptions on cell chemistry cost reduction rates and autonomous function regulatory approval timelines. Quarterly review of cathode precursor inventory levels, EU battery passport implementation progress, and fleet operator electrification procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Roof Rack Market