
 Automotive Side Impact Assembly Market | 2026-2036
Automotive Side Impact Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Side Impact Assembly Market Analytics
Steel stamping capacity in the U.S. Midwest is shifting toward hot-formed door beam production for next-generation vehicle platforms. Autoliv leverages its airbag integration expertise to bundle sensor-triggered side curtain systems. ZF Friedrichshafen anchors European supply through its crash-active structures division. Magna International competes on aluminum-intensive door assemblies that reduce mass while preserving intrusion resistance.
Automotive side impact assemblies comprise energy-absorbing structural reinforcements, deployable restraints, and electronic detection modules engineered to manage lateral collision forces and protect occupants during broadside impacts. Door beams typically employ press-hardened boron steel grades achieving tensile strengths above 1500 MPa to maintain cabin integrity within severe offset-barrier scenarios. Steel formulations still dominate OEM specifications for cost-critical platforms, though aluminum door structures gain share in electric vehicle architectures where mass reduction extends range. Composites occupy niche applications in premium segments where tooling amortization supports higher per-vehicle material costs.
FMVSS 214, Euro NCAP lateral impact protocols, and ECE R95 collectively mandate measurable thorax and pelvis protection thresholds that OEMs must certify before market entry. IIHS side crashworthiness ratings now influence consumer purchase decisions in the United States, pressuring assemblers to exceed baseline regulatory compliance. Stakeholders must monitor how battery pack placement in electric skateboard platforms alters load paths and demands redesigned side-impact load distribution strategies.
Market Dynamics
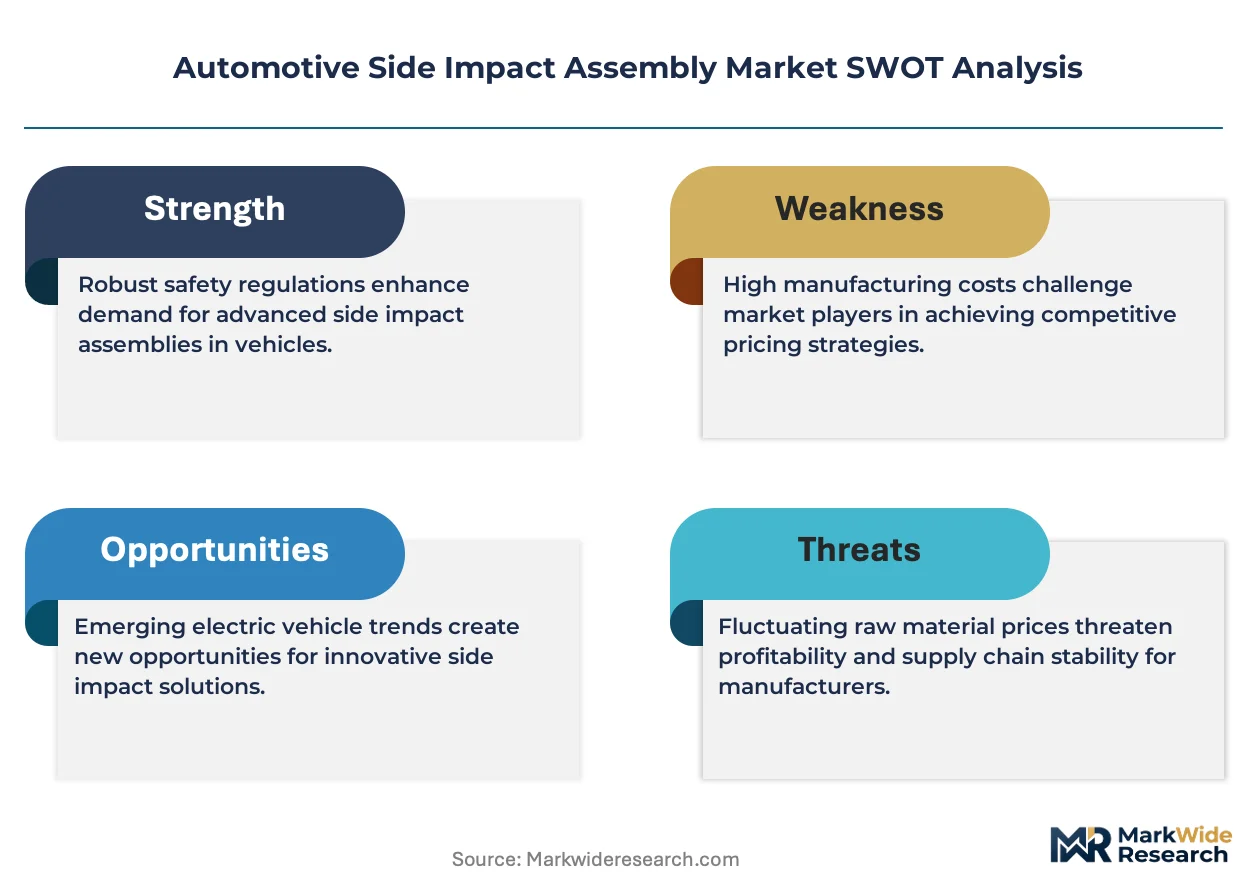
Press-hardened boron steel door beams are displacing conventional high-strength steel grades as OEMs chase FMVSS 214 and Euro NCAP compliance thresholds. Tier-1 stampers must retool Midwest capacity for hot-forming lines while managing aluminum migration in electric vehicle architectures.
Growth Catalysts
- FMVSS 214 Side Impact Protection:NHTSA mandates measurable thorax injury criteria for all light vehicles, forcing structural reinforcement upgrades across passenger car and light truck segments.
- Electric vehicle mass budgets:Battery pack weight penalties compel aluminum-intensive door structures that preserve intrusion resistance while offsetting cell mass.
- Press-hardening process maturation:Die quenching technology achieves 1500 MPa tensile strength in complex geometries, enabling thinner-gauge solutions without sacrificing crash performance.
Market Restraints
- Boron steel input concentration:ArcelorMittal and SSAB control specialized hot-forming blank supply, exposing stampers to alloy surcharge volatility.
- Tooling amortization barriers:Hot-forming dies require 12-18 month lead times and EUR 2-4 million capital commitments, freezing out mid-volume assemblers.
- Aluminum-steel galvanic corrosion:Multi-material door assemblies demand isolation coatings and assembly process controls that inflate manufacturing complexity.
Strategic Opportunities
- India PLI scheme for auto components:Tier-2 stampers can capture export contracts from European OEMs seeking cost-competitive hot-formed beam capacity outside China.
- Sensor-integrated door modules:Convergence of crash detection electronics with structural assemblies creates bundled system revenue streams beyond commodity beam supply.
- Second-life battery enclosure repurposing:Side-impact engineering expertise transfers to skateboard platform battery protection, opening adjacent revenue in electric commercial vehicle segments.
Industry Challenges
- Hot-forming thermal management:Die cooling channel design and press cycle optimization require process engineers scarce in traditional stamping operations.
- Multi-material joining certification:OEM weld specification audits for aluminum-to-steel door assemblies extend qualification timelines by 8-14 months.
- Legacy platform service obligations:Conventional high-strength steel beam supply must continue for 10-15 year model runs while engineering resources pivot to next-generation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Side Impact Assembly Market |
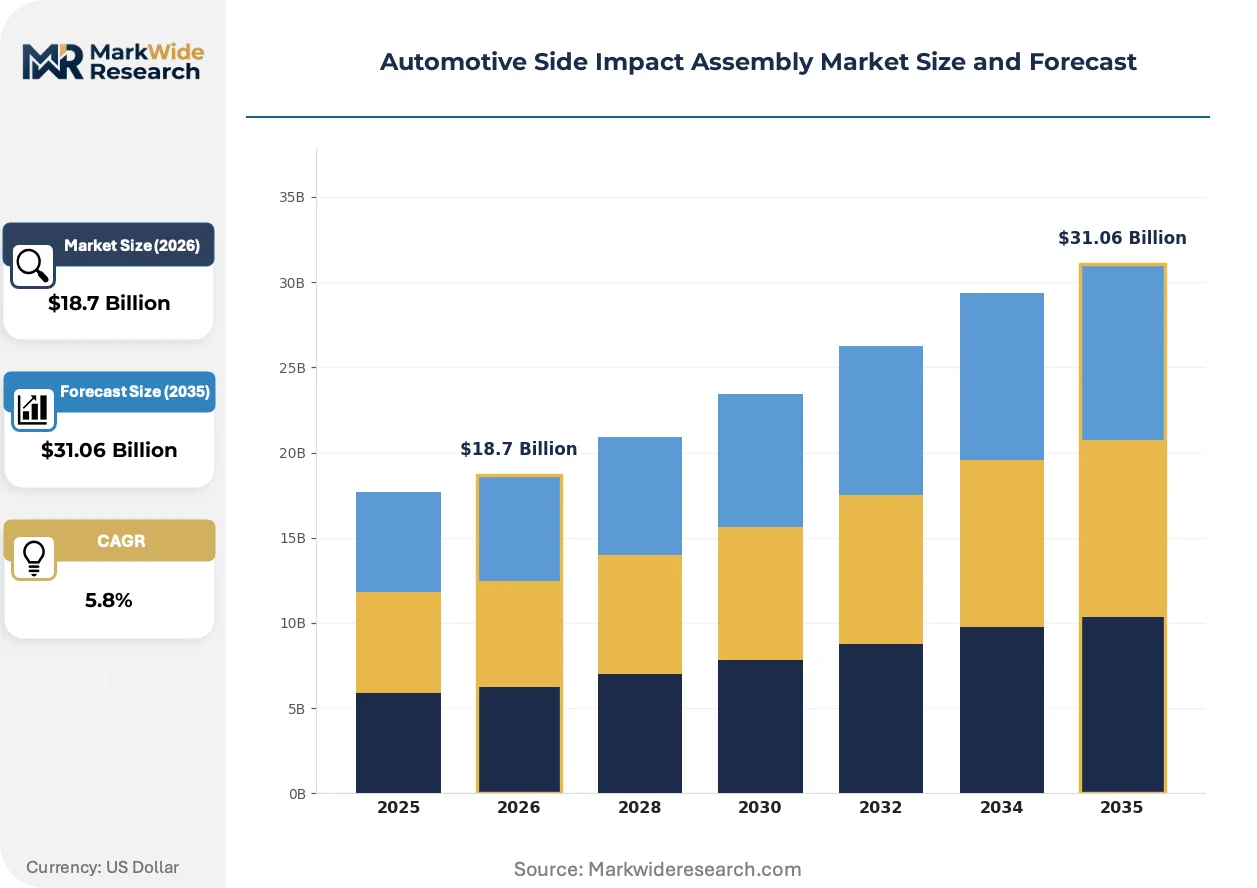
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Door Beams, Airbags, Sensors, Structural Parts Material: Steel, Aluminum, Composites, Fiberglass End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Regulations: FMVSS, Euro NCAP, IIHS, ECE |
| Companies Covered | Autoliv, ZF Friedrichshafen, Robert Bosch, Magna International, Aptiv, Hyundai Mobis, Thyssenkrupp, Gestamp, ArcelorMittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Side Impact Assembly Market Evolving Landscape
Tailored blank technology and in-die quenching are compressing the performance gap between steel and aluminum solutions. Tier-1 suppliers now engineer side-impact systems as integrated sensor-structure packages rather than discrete hardware commodities.
Carbon fiber reinforced polymer inserts are integrating into B-pillar reinforcements for ultra-high-performance electric vehicles. Porsche and Rimac specify these hybrid structures to offset battery mass while maintaining pole-impact rigidity. The technology is compressing the traditional steel-aluminum tradeoff by delivering specific energy absorption metrics unobtainable with metallic solutions alone.
Euro NCAP's 2026 lateral impact protocol revision mandates far-side occupant protection and pole-oblique testing. ECE R95 amendments will extend thorax protection requirements to commercial vehicle categories previously exempt. European OEM engineering centers in Stuttgart and Munich are accelerating development of dual-chamber side airbags and deployable seat bolsters to certify ahead of enforcement deadlines.
Fleet procurement departments now specify IIHS side crashworthiness ratings as mandatory bid criteria for executive vehicle contracts. Rental car aggregators and corporate mobility managers have displaced individual consumer preference as the decisive demand channel for five-star lateral protection. This concentration is most visible in United States commercial fleet segments where liability exposure drives specification rigor beyond baseline FMVSS compliance.
Automotive Side Impact Assembly Market Segmentation
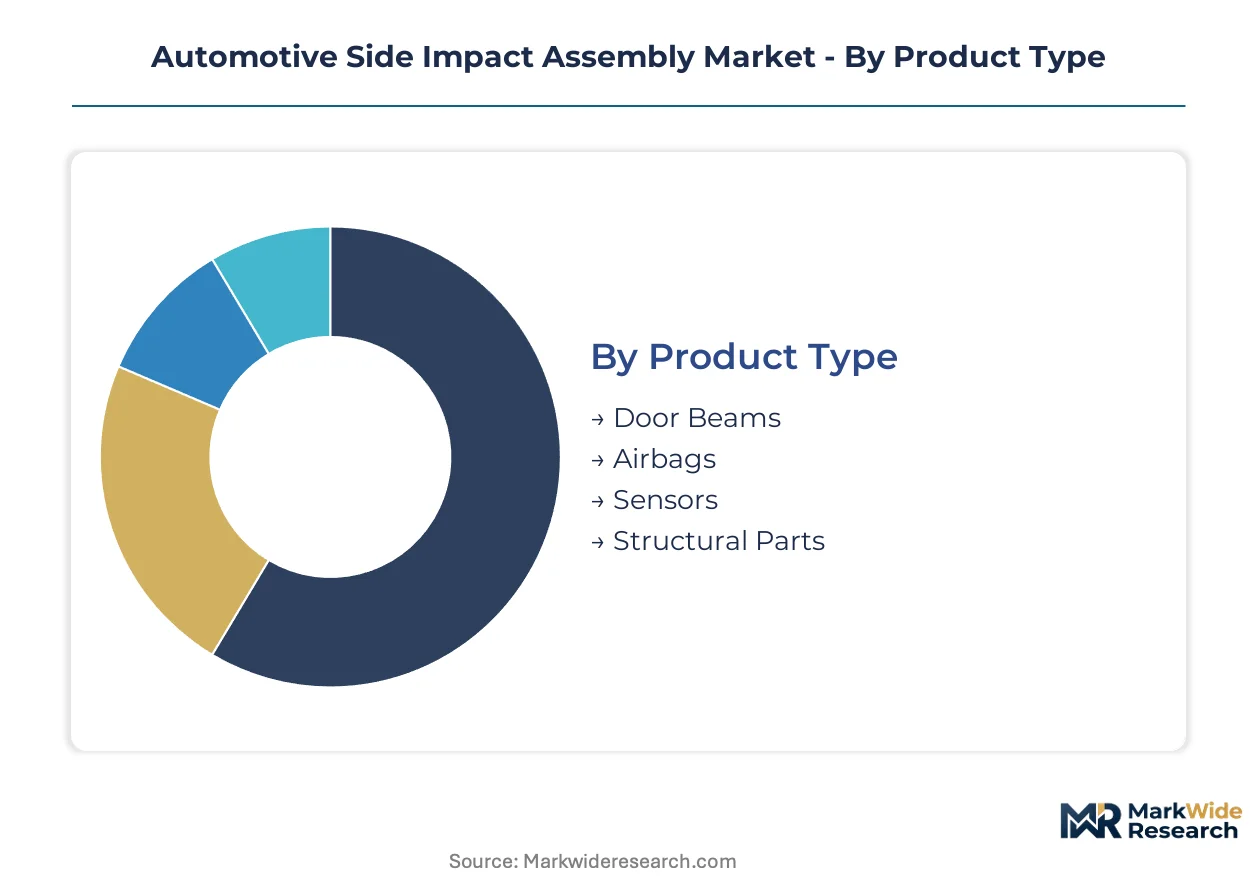
Side-impact assembly procurement varies sharply across product architectures, material specifications, and regulatory compliance tiers. OEM platform strategies determine whether suppliers deliver discrete components or integrated sensor-structure modules.
Product Type:
Structural load-bearing elements dominate engineering resource allocation, while electronic detection layers command expanding system value.
- Door Beams:Press-hardened boron steel or aluminum extrusions form the primary intrusion-resistant barrier. BMW and Volkswagen anchor European demand for hot-formed 1500 MPa solutions that satisfy Euro NCAP pole-impact protocols.
- Airbags:Side curtain and thorax protection systems deploy from seat-mounted or roof-rail positions. Autoliv bundles these with crash sensors to capture integrated system contracts from premium OEMs.
- Sensors:Accelerometer and pressure-based detection modules trigger restraint deployment within milliseconds of lateral impact detection.
- Structural Parts:B-pillar reinforcements, rocker panel inserts, and sill reinforcements complete the energy management pathway.
Mature deployment sits with door beams. Newer deployment is concentrated in sensor-integrated modules.
Material:
Mass reduction imperatives in electric vehicle architectures are fragmenting traditional steel dominance across OEM supply chains.
- Steel:Press-hardened boron grades achieve tensile strengths exceeding 1500 MPa while maintaining cost competitiveness for high-volume platforms. ArcelorMittal and SSAB control specialized blank supply, exposing stampers to alloy surcharge volatility.
- Aluminum:6xxx and 7xxx series extrusions reduce door assembly mass by 30-40% versus steel equivalents. Porsche and Rimac specify aluminum-intensive structures to offset battery pack weight in electric performance vehicles.
- Composites:Carbon fiber reinforced polymer inserts occupy ultra-premium B-pillar applications where tooling amortization supports elevated per-vehicle costs.
- Fiberglass:Sheet molding compound reinforcements serve niche cost-sensitive segments with moderate crash performance requirements.
Steel retains volume leadership in mass-market ICE platforms. Aluminum is expanding most quickly in electric vehicle door structures.
End User:
Supply chain position determines whether procurement emphasizes raw component cost or system integration value.
- OEMs:Volkswagen, BMW, and Ford maintain captive engineering teams that specify side-impact architectures and qualify Tier-1 suppliers against internal performance benchmarks.
- Tier-1 Suppliers:Autoliv, ZF Friedrichshafen, and Magna International consolidate beam stamping, airbag integration, and sensor calibration into module-level deliveries.
- Aftermarket Providers:Collision repair networks source replacement door beams and deployed airbag modules for vehicle life-cycle service.
- Vehicle Assemblers:Contract manufacturers and emerging EV specialists procure pre-validated side-impact subassemblies to compress development timelines.
Direct OEM relationships anchor high-complexity program wins. Aftermarket channels concentrate in insurance-driven collision repair volumes.
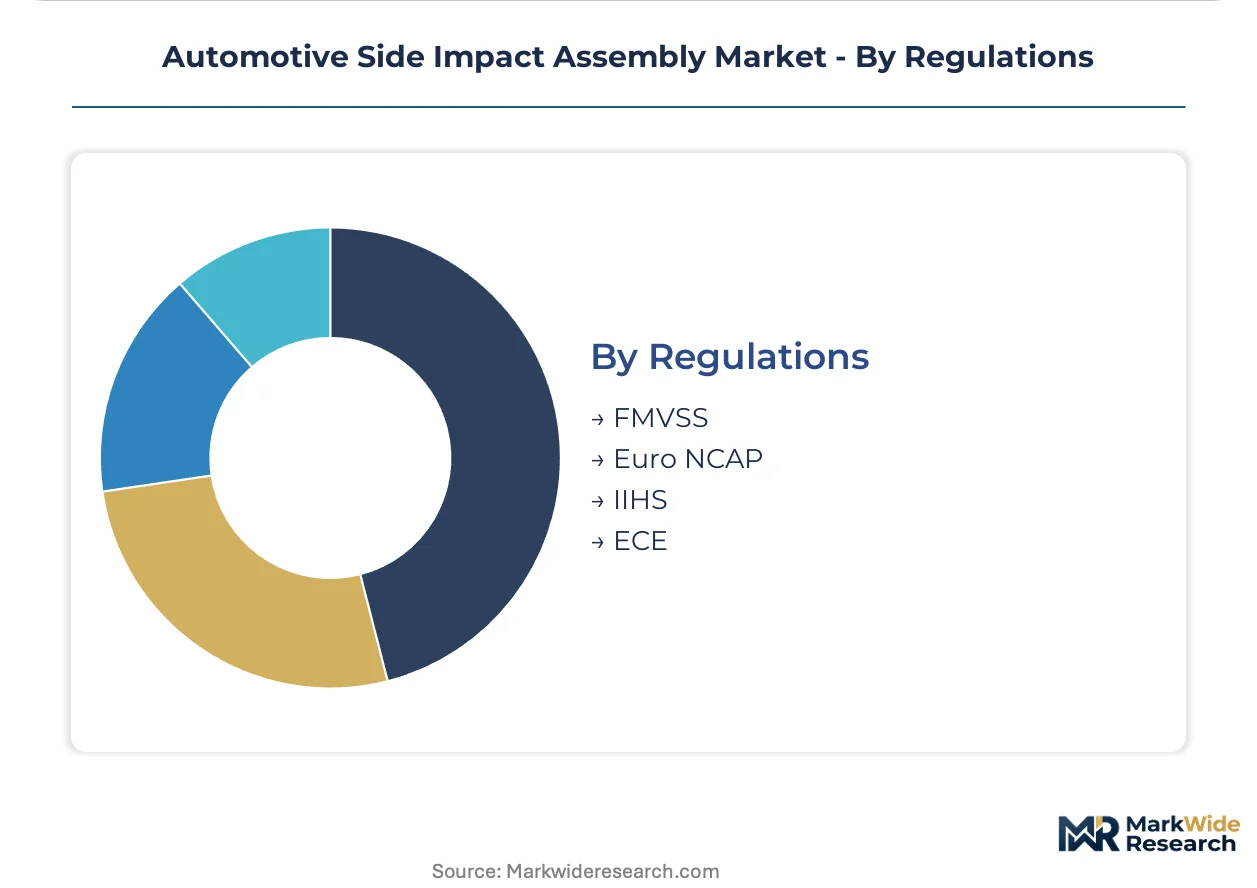
Regulations:
Certification protocols create tiered compliance thresholds that segment supplier capabilities and pricing power.
- FMVSS:NHTSA mandates measurable thorax injury criteria through FMVSS 214, forcing structural reinforcement upgrades across all light vehicle segments sold in the United States.
- Euro NCAP:The 2026 lateral impact protocol revision introduces far-side occupant protection and pole-oblique testing requirements. Stuttgart and Munich engineering centers accelerate dual-chamber airbag development to certify ahead of enforcement.
- IIHS:Side crashworthiness ratings now influence fleet procurement decisions in the United States, with rental car aggregators specifying five-star lateral protection as mandatory bid criteria.
- ECE:ECE R95 amendments extend thorax protection requirements to commercial vehicle categories previously exempt from passenger car mandates.
FMVSS and Euro NCAP drive the steepest engineering investment. ECE compliance opens commercial vehicle adjacent revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boron steel supply from Swedish mills and German engineering centers anchors European side-impact assembly capacity. North American stamping corridors retool for hot-forming lines. Asian manufacturing clusters scale aluminum-intensive architectures for electric vehicle exports.
United States
NHTSA's FMVSS 214 mandates drive structural reinforcement upgrades across light truck and passenger car segments. IIHS side crashworthiness ratings now influence fleet procurement decisions, with rental aggregators specifying five-star lateral protection. Michigan and Ohio stamping corridors retool Midwest capacity for hot-formed door beam production serving next-generation vehicle platforms.
Germany
BMW and Volkswagen anchor advanced side-impact engineering programs demanding 1500 MPa press-hardened solutions. Euro NCAP's 2026 lateral impact protocol revision accelerates development of dual-chamber side airbags in Stuttgart and Munich engineering centers. KBA certification requirements enforce weld specification audits that extend supplier qualification timelines.
China
Domestic OEMs and joint ventures scale aluminum-intensive door structures to offset battery pack mass in electric vehicle architectures. MIIT fuel consumption and new energy vehicle mandates compress development cycles for crash-active structures. Yangtze River Delta manufacturing clusters concentrate hot-forming capacity to serve both domestic demand and export contracts.
India
Tier-2 stampers capture export contracts from European OEMs seeking cost-competitive hot-formed beam capacity outside China. The PLI scheme for auto components subsidizes capital equipment for press-hardening lines. Maharashtra and Gujarat automotive clusters attract foreign direct investment for side-impact subassembly production.
Japan
METI safety standards and domestic OEM engineering specifications drive sensor-integrated door module development. Lightweight aluminum structures gain share in premium electric vehicle platforms from established manufacturers. Kanto and Chubu industrial regions maintain specialized capacity for complex crash management system integration.
Automotive Side Impact Assembly Market Competitive Landscape
Global majors compete with regional champions across hot-forming technology and sensor integration capabilities. The supplier base organizes into three tiers: integrated system providers bundling structural and electronic components, specialized stampers focused on high-strength steel forming, and aluminum-intensive fabricators serving electric vehicle mass reduction requirements. Strategic moves concentrate on capacity expansion for press-hardening lines and technology licensing for multi-material joining processes.
Within the integrated system tier, Autoliv and ZF Friedrichshafen exemplify suppliers consolidating crash detection electronics with structural assemblies. Magna International occupies a position among North American-based fabricators competing on aluminum-intensive door solutions. These three anchors represent distinct competitive vectors: airbag-triggered systems, crash-active structures, and mass-optimized metallic architectures.
| Leading Market Players |
|---|
| Autoliv |
| ZF Friedrichshafen |
| Robert Bosch |
| Magna International |
| Aptiv |
| Hyundai Mobis |
| Thyssenkrupp |
| Gestamp |
| ArcelorMittal |
| Others |
Value Network & Pricing Analysis
Boron steel blank costs cascade through three pricing tiers before reaching OEM assembly plants, with ArcelorMittal and SSAB surcharges compressing margins at the stamper level while fleet procurement departments extract volume discounts downstream.
Pricing Analysis
Warranty coverage for hot-forming die integrity separates premium Tier-1 contracts from commodity beam supply, with Autoliv and ZF bundling sensor calibration services into multi-year service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—Euro NCAP five-star rated assemblies command 15-25% premiums over baseline FMVSS 214 compliance. Pricing pressure stems from aluminum migration in electric vehicle architectures forcing steel stampers to absorb alloy volatility. Aftermarket collision repair channels exhibit highest price sensitivity, while captive OEM engineering programs demonstrate lowest sensitivity due to liability exposure considerations.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for European OEMs seeking cost-competitive hot-formed capacity outside China. Geographic supply concentrates in Germany, China, and India for press-hardening lines and specialized blank production. Raw material dependencies rest on Swedish boron steel, German die-quenching equipment, and Japanese sensor electronics. Single-source vulnerability around ArcelorMittal and SSAB blank supply exposes stampers to alloy surcharge volatility. Distribution runs through Tier-1 module suppliers consolidating structural, electronic, and airbag components into integrated door systems for final OEM assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Euro NCAP's 2026 lateral impact protocol revision erects a barrier-to-entry moat for suppliers lacking dual-chamber airbag and deployable bolster certification capabilities.
For Market Incumbents: Cement qualification timelines at KBA and NHTSA as competitive moats by accelerating dual-chamber side airbag development ahead of enforcement deadlines. Defend against aluminum-intensive fabricators by locking in long-term boron steel offtake agreements with ArcelorMittal before surcharge volatility escalates. Prioritize backward integration into sensor calibration capabilities to capture bundled system revenue streams beyond commodity beam supply.
For New Entrants and Emerging Players: Direct-to-fleet procurement portals offer the most penetrable route for mid-volume stampers lacking OEM engineering relationships. Target rental car aggregator and corporate mobility manager segments where IIHS side crashworthiness ratings have displaced individual consumer preference as decisive demand channels. Pursue white-space in India PLI-subsidized export capacity serving European OEMs seeking China alternatives.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized hot-forming stampers with idle Midwest capacity in the United States. Long-term viability centers on electric vehicle platform share capture as battery pack placement alters side-impact load path engineering requirements. Monitor battery enclosure protection contract awards as inflection indicator for engineering expertise transfer opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Forming Capacity Expansion | Retooled Midwest stamping corridors serve next-generation vehicle platforms from Ford and GM. |
| Sensor-Integrated Module Development | Autoliv bundles accelerometer detection with structural assemblies for premium OEM contracts. |
| Aluminum-Intensive Architecture Migration | Magna International competes on mass-optimized door solutions for electric vehicle range extension. |
| India PLI Scheme Utilization | Tier-2 stampers capture European export contracts subsidized by auto component production incentives. |
| Multi-Material Joining Certification | Extended weld specification audits at KBA create qualification barriers protecting incumbent positions. |
Research Methodology
Independent corroboration across Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations underwrites the qualitative findings. Primary interviews with crash management system directors and hot-forming process engineers combined with secondary validation from NHTSA FMVSS 214 dockets, Euro NCAP technical bulletins, IHS Markit vehicle production databases, and SEC automotive supplier filings. Bottom-up and top-down triangulation reconciles component-level cost build-ups against OEM platform volume projections.
Rate-of-change decomposition separates volume effects from value effects across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression against historical penetration curves adjusted for regulatory enforcement timelines. Industry-specific forecast inputs incorporate battery pack placement geometry impacts on side-impact load path redesign and press-hardening process maturation curves.
The model holds under stable regulatory enforcement schedules and intact boron steel supply; deviation in Euro NCAP protocol implementation timing or ArcelorMittal capacity allocation would shift trajectory. Forecasts reflect documented assumptions regarding electric vehicle platform share evolution and aluminum-steel material substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Tie Rod Assembly Market