
 Global Automotive Odometer Stepping Motor Market | 2026-2036
Global Automotive Odometer Stepping Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Odometer Stepping Motor Market Intelligence
The bundling of stepping motors with driver ICs and control software into pre-calibrated modules is recalibrating the supply chain for instrument cluster manufacturers. Denso Corporation leverages its extensive Tier-1 supplier network to secure large OEM contracts. Robert Bosch GmbH specializes in complete dashboard systems, integrating its own motor components. Nidec Corporation competes on miniaturization and power efficiency, targeting both automotive and adjacent industrial applications.
An automotive odometer stepping motor is an electromechanical actuator that converts electrical pulses into discrete, precise rotational movements. These devices, often featuring step angles of 1.8 or 7.5 degrees, drive the physical needles or digit wheels in vehicle odometers and speedometers. Hybrid motor designs offer the highest torque and precision, making them standard in premium passenger vehicles. The aftermarket segment, however, relies heavily on lower-cost Permanent Magnet motors for repairs and replacements.
Regulations from the NHTSA in the United States mandate strict odometer accuracy and tamper-resistance, influencing motor durability. In Europe, the RoHS directive restricts hazardous materials in electronic components like stepping motors. Future competitive positioning hinges on developing motors that meet the distinct power, size, and reliability profiles for both fully digital displays and cost-effective hybrid clusters.
Market Dynamics
The central dynamic shaping the market is the bifurcation of product development, driven by the simultaneous demand for high-precision hybrid motors in advanced instrument clusters and cost-sensitive permanent magnet motors for budget vehicles and the aftermarket.
Growth Catalysts
- Stricter Data Integrity Mandates:Regulations from bodies like the NHTSA in the United States, which require accurate and tamper-resistant odometer readings, compel the use of higher-grade, more durable stepping motors in new passenger vehicles.
- Hybrid Instrument Cluster Adoption:The continued integration of hybrid digital-analog dashboards in mid-range vehicles sustains demand for physical stepping motors to drive mechanical needles, blending traditional aesthetics with digital information displays.
- Concentrated Vehicle Production:Immense automotive manufacturing output in China provides a scaled and concentrated demand base for odometer stepping motors, anchoring a significant portion of the component supply chain in the region.
Market Restraints
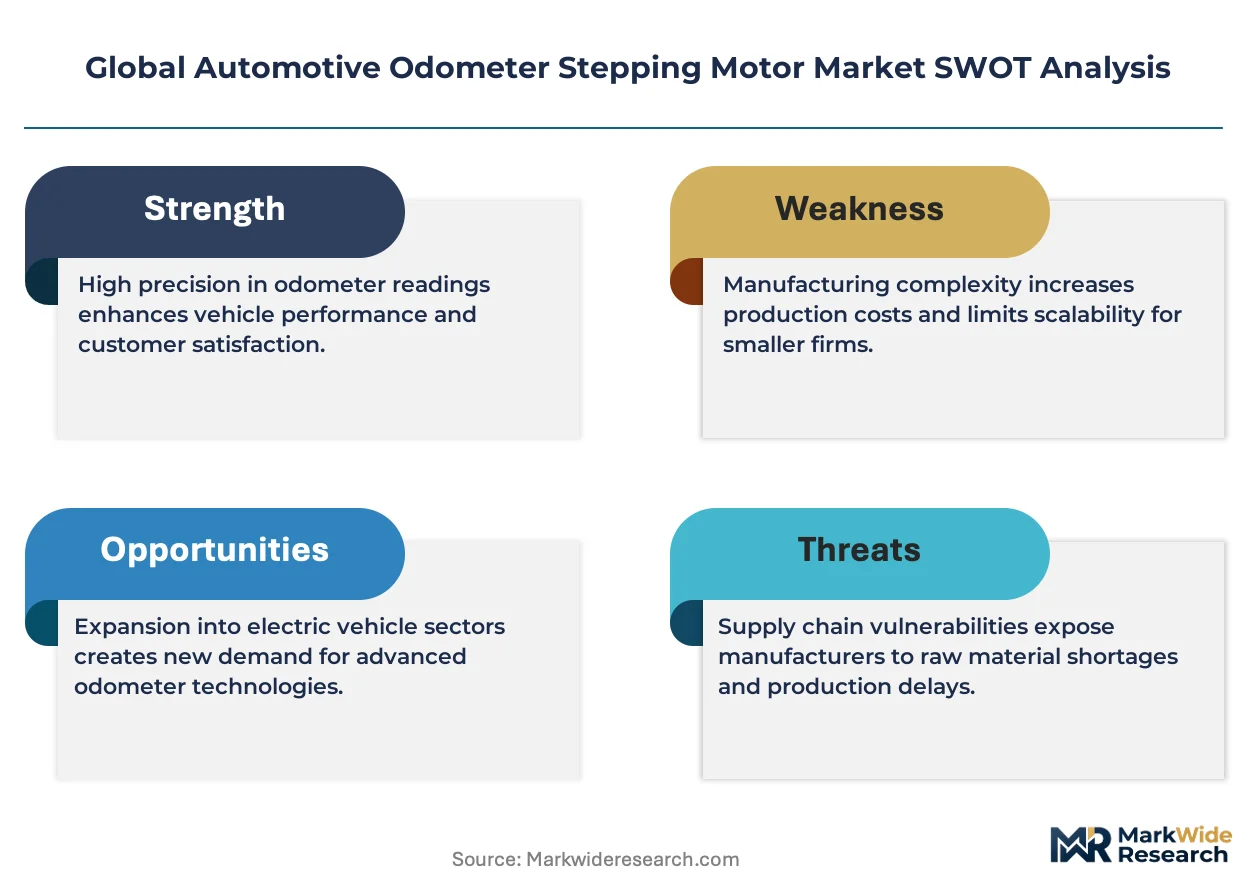
- Substitution by Digital Displays:The long-term migration toward fully digital cockpits and head-up displays in premium and electric vehicles presents a direct substitution threat, as these systems render mechanical stepping motors obsolete.
- Raw Material Price Volatility:The cost of high-performance hybrid stepping motors is sensitive to price fluctuations in rare-earth materials, such as neodymium, which are essential for creating powerful permanent magnets.
- Semiconductor Supply Dependencies:The reliance on a specialized and concentrated group of semiconductor foundries for manufacturing motor driver ICs creates a significant bottleneck risk for the entire stepping motor supply chain.
Strategic Opportunities
- Adjacent Industrial Applications:Miniaturized and power-efficient stepping motors developed for automotive use can be adapted for new applications in industrial automation, medical devices, and robotics that require precise motion control.
- Integrated Module Development:There is a clear opportunity to supply pre-calibrated modules that combine the motor, driver IC, and control firmware, simplifying the design and assembly process for instrument cluster manufacturers.
- Aftermarket Penetration:Targeting the growing vehicle repair and maintenance aftermarket in Brazil and India with cost-effective Permanent Magnet motors offers a distinct revenue stream separate from OEM production cycles.
Industry Challenges
- Regulatory Compliance Fragmentation:Manufacturers must navigate a complex web of differing regional standards, such as Europe's RoHS directive on hazardous materials, which impacts material sourcing and product design for global platforms.
- System Integration Complexity:Ensuring seamless communication and compatibility between the stepping motor module and a vehicle's Controller Area Network (CAN bus) remains a persistent technical hurdle for component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Odometer Stepping Motor Market |
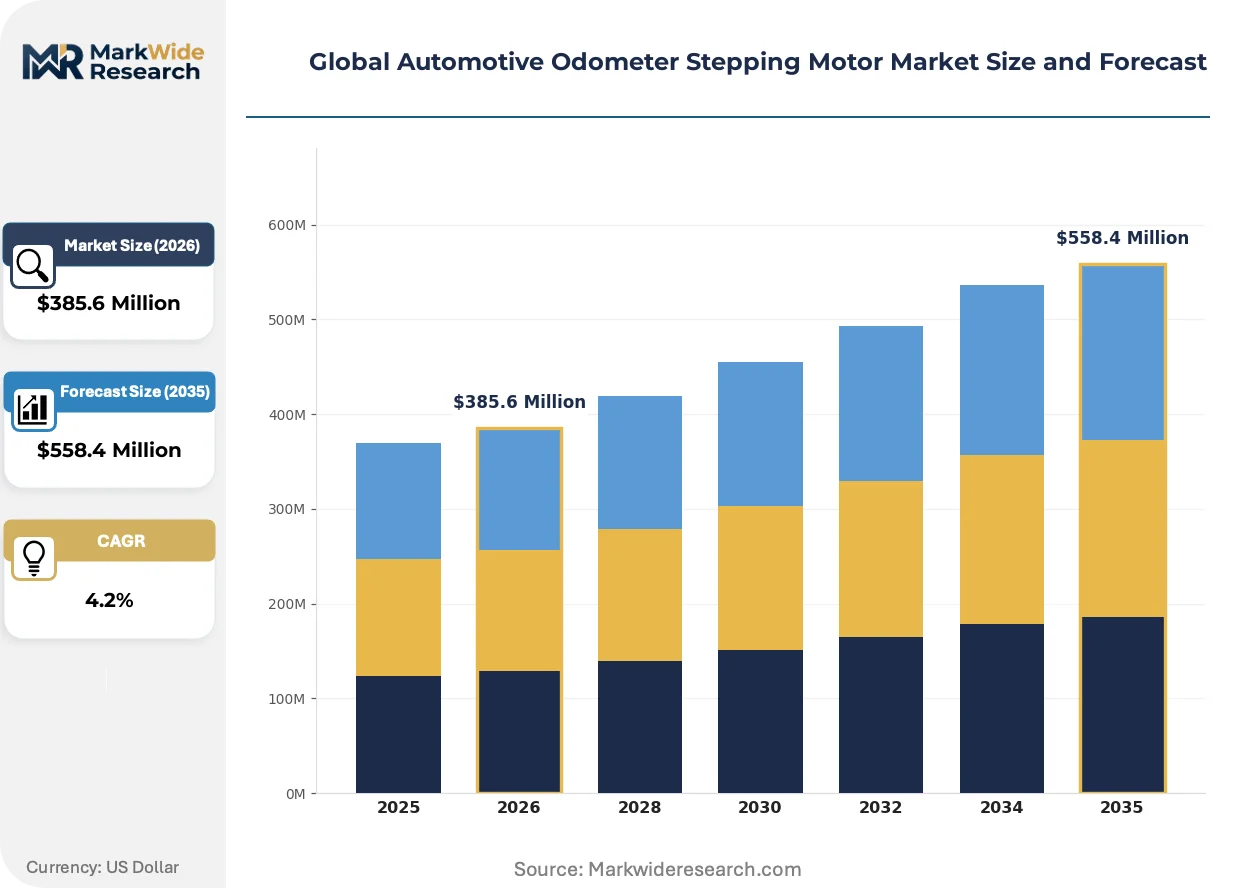
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Permanent Magnet, Variable Reluctance, Hybrid, Unipolar, Bipolar Application: Passenger Vehicles, Commercial Vehicles, Recreational Vehicles, Two-Wheelers, Agricultural Machinery Technology: Brushless, Brushed, Digital Control, Analog Control, Pulse Width Modulation End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Component Manufacturers |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Valeo, MAHLE GmbH, Nidec Corporation, Johnson Electric Holdings Ltd., Mitsuba Corporation, Mabuchi Motor Co., Ltd., Brose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Odometer Stepping Motor Market Strategic Shifts & Innovations
Product evolution is cleaving the market into two distinct segments: high-performance, integrated systems for new vehicles and lower-cost, discrete components for the aftermarket. This bifurcation influences technology roadmaps, supply chain strategies, and regulatory compliance efforts across the industry.
Hybrid stepping motor technology combines permanent magnet and variable reluctance principles to achieve superior torque, step resolution, and quiet operation. Automotive OEMs are adopting these motors as the standard for needle actuation in the instrument clusters of mid-range and premium passenger vehicles. This technology is consolidating its position in the high-performance OEM segment, relegating simpler motor designs to aftermarket repair and entry-level vehicle applications.
Europe's Restriction of Hazardous Substances (RoHS) directive imposes strict limits on materials like lead and cadmium within electronic components. This regulation directly forces stepping motor manufacturers to re-engineer products and re-qualify their supply chains to ensure compliance for components sold into the European Union. The passenger vehicle segment is most impacted, with suppliers investing heavily in compliant material alternatives to maintain market access.
A notable shift in purchasing behavior involves instrument cluster manufacturers sourcing complete, pre-tested modules instead of discrete components. This trend moves procurement from buying individual motors and ICs to acquiring a single, calibrated subsystem, which reduces internal engineering workload for Tier-1 suppliers. This system-level sourcing model is most visible in North American and European automotive supply chains, where speed-to-market is a critical competitive factor.
Global Automotive Odometer Stepping Motor Market Segmentation
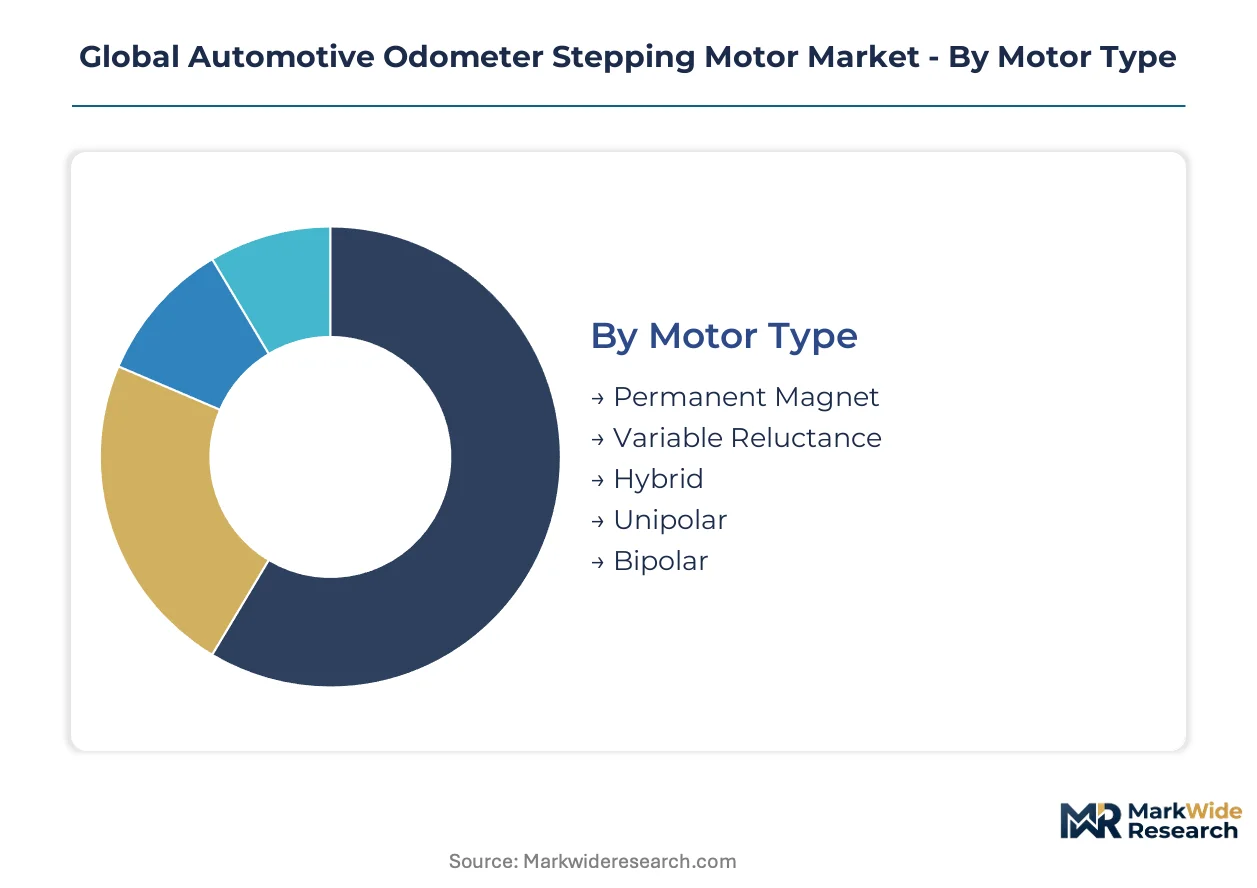
Understanding the varied requirements across different vehicle types and manufacturing processes is critical for navigating the automotive odometer stepping motor market. This segmentation analysis provides a structured view of how specific product attributes and end-user demands shape market dynamics and competitive strategies.
Motor Type:
Buyers of automotive odometer stepping motors prioritize specific performance characteristics and cost efficiencies, directly influencing their choice of motor type.
- Hybrid:These motors combine permanent magnet and variable reluctance principles, delivering superior torque, step resolution, and quiet operation for precise needle actuation. Hybrid motors are standard in premium passenger vehicles, where high accuracy and smooth movement are essential.
- Permanent Magnet:Characterized by their simplicity and cost-effectiveness, permanent magnet motors use a permanent magnet in the rotor to generate motion. The aftermarket segment and budget vehicle manufacturers rely heavily on these lower-cost solutions for repairs and entry-level instrument clusters.
- Variable Reluctance:These motors operate based on the principle of minimizing magnetic reluctance, offering high speeds and robust construction without permanent magnets. Their application is more specialized, often found in industrial settings or specific automotive niche uses where high torque at low speeds is not the primary requirement.
- Unipolar:Unipolar stepping motors utilize a center-tapped winding, simplifying the drive circuitry and reducing cost. These motors are typically found in less demanding applications or older instrument cluster designs due to their lower torque output compared to bipolar variants.
- Bipolar:Bipolar stepping motors offer higher torque and efficiency by reversing the current flow through their windings, requiring more complex driver circuits. Modern instrument cluster designs increasingly incorporate bipolar motors for enhanced performance and finer control.
Volume sits with Permanent Magnet motors; growth tilts toward Hybrid designs.
Application:
The end-use application dictates the required motor specifications and integration complexity within the vehicle's instrument cluster.
- Passenger Vehicles:This segment represents the largest demand base for odometer stepping motors, driven by the widespread adoption of hybrid digital-analog instrument clusters. Stricter data integrity mandates from bodies like the NHTSA compel the use of higher-grade, durable motors in these vehicles.
- Commercial Vehicles:Odometer stepping motors in commercial vehicles must withstand demanding operational conditions, prioritizing durability and reliability over miniaturization. The heavy-duty nature of these vehicles necessitates robust motor components for consistent performance.
- Recreational Vehicles:Stepping motors in recreational vehicles often face intermittent use and require resistance to environmental factors like temperature fluctuations. These applications demand motors that can maintain accuracy despite varied operating conditions.
- Two-Wheelers:Simpler, cost-effective stepping motors are typically employed in two-wheeler instrument clusters due to space constraints and price sensitivity. The focus remains on basic functionality and reliability within a compact form factor.
- Agricultural Machinery:Stepping motors in agricultural machinery are engineered for extreme durability and resistance to dust, moisture, and vibration. These specialized applications require ruggedized components capable of operating in harsh outdoor environments.
Demand concentration remains highest within Passenger Vehicles, with Commercial Vehicles requiring robust solutions.
Technology:
System integration requirements and the desired level of precision drive the selection of underlying motor technology.
- Digital Control:Digital control systems provide precise, programmable control over stepping motor movements, enabling complex needle patterns and integration with advanced vehicle electronics. Modern instrument clusters extensively use digital control for enhanced accuracy and customizable displays.
- Brushless:Brushless motor technology offers superior longevity, efficiency, and quieter operation due to the absence of physical brushes, reducing wear and maintenance. These motors are increasingly adopted in premium automotive applications where extended lifespan and reliability are critical.
- Brushed:Brushed motor technology is a more traditional and cost-effective solution, relying on physical brushes for current commutation. While simpler, brushed motors have a shorter lifespan and are less efficient, primarily used in budget-sensitive or less demanding applications.
- Analog Control:Analog control systems offer a straightforward method for driving stepping motors, often found in older or simpler instrument cluster designs. These systems are less flexible than digital counterparts but remain viable for basic, fixed-function applications.
- Pulse Width Modulation:Pulse Width Modulation (PWM) is a technique used to control the average power delivered to the motor by varying the width of electrical pulses. PWM enhances motor efficiency and allows for finer speed and torque control in various automotive applications.
Modern instrument clusters increasingly favor Digital Control, while Brushless technology offers long-term operational benefits.
End User:
Each end-user segment plays a distinct role in the automotive supply chain, influencing procurement strategies and product specifications.
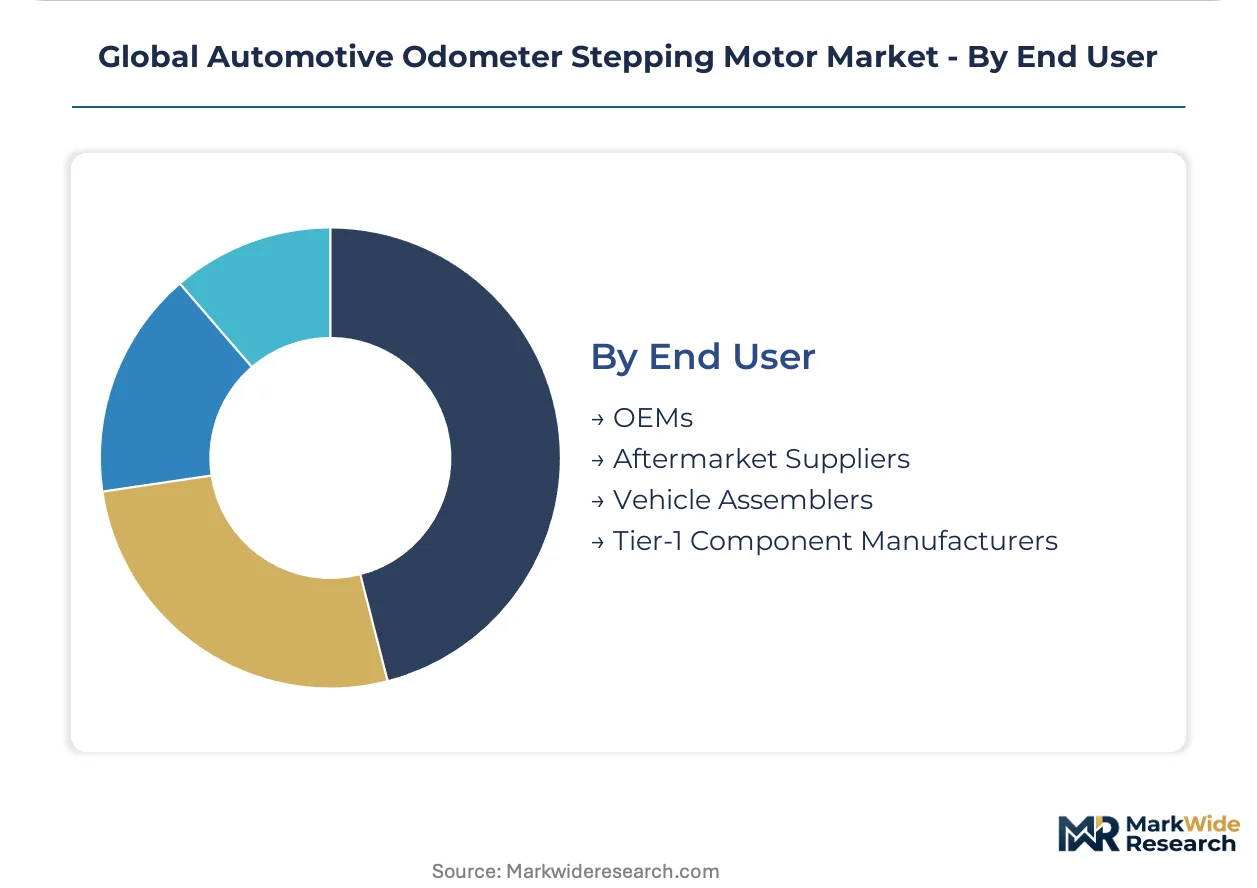
- OEMs:Original Equipment Manufacturers (OEMs) are the primary purchasers for new vehicle production, demanding high-volume, custom-specified stepping motors that meet stringent quality and performance standards. These manufacturers drive innovation in motor design and integration.
- Aftermarket Suppliers:Aftermarket suppliers cater to the vehicle repair and maintenance segment, focusing on cost-effective and readily available stepping motors for replacements. This segment is characterized by a demand for standardized parts compatible with a wide range of older vehicle models.
- Vehicle Assemblers:Vehicle assemblers integrate various components, including odometer stepping motors, into the final vehicle product. Their procurement decisions are often guided by OEM specifications and supply chain efficiency for large-scale production.
- Tier-1 Component Manufacturers:Tier-1 component manufacturers design and produce complete instrument clusters, often sourcing stepping motors as sub-components. They act as intermediaries, integrating motors with driver ICs and software before supplying to OEMs.
OEMs command significant purchasing power, while Aftermarket Suppliers focus on cost-effective replacement solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The immense automotive manufacturing output in China, particularly within its special economic zones like the Yangtze River Delta, drives significant global demand for odometer stepping motors. These zones attract major automotive OEMs and component suppliers, fostering a concentrated production ecosystem. This concentration underpins a substantial portion of the component supply chain for the global market.
China
Demand for stepping motors in China is sustained by its vast passenger vehicle market and the widespread adoption of hybrid digital-analog instrument clusters. The MIIT's policies promoting domestic automotive production and advanced manufacturing incentivize local component sourcing. Manufacturing hubs in Shanghai and Guangzhou are centers for advanced automotive electronics production, integrating high-grade motors into new vehicles.
Germany
Germany's premium automotive sector, with brands like BMW and Mercedes-Benz, requires high-precision hybrid stepping motors for sophisticated instrument clusters. European RoHS directives influence material selection, ensuring compliance in electronic components for the entire supply chain. The Stuttgart region, a key automotive cluster, sees significant investment in motor development for advanced dashboard systems.
United States
The United States market benefits from robust passenger vehicle sales and stringent data integrity mandates for vehicle components. NHTSA regulations, specifically regarding odometer accuracy and tamper-resistance, necessitate durable and reliable stepping motors. Detroit, Michigan, remains a pivotal automotive manufacturing and R&D hub, driving demand for advanced motor integration in new vehicle platforms.
Japan
Japanese automotive manufacturers, known for technological innovation, integrate advanced stepping motors into their vehicle instrument clusters to meet consumer expectations. METI initiatives supporting high-tech manufacturing encourage the development of miniaturized and power-efficient motor solutions. The Aichi Prefecture, home to major automotive OEMs, is a focal point for precision component manufacturing and supply chain coordination.
India
India's expanding automotive market, particularly for entry-level and mid-range passenger vehicles, creates substantial demand for cost-effective permanent magnet motors. The PLI scheme for automotive components aims to boost local manufacturing capabilities and reduce import dependencies. Chennai, a prominent automotive manufacturing center, is witnessing increased production of instrument clusters requiring these motors.
Global Automotive Odometer Stepping Motor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in the global automotive odometer stepping motor sector. The market exhibits a tiered structure, with large Tier-1 suppliers dominating OEM contracts through comprehensive, integrated solutions. Strategic archetypes include global electronics giants offering broad automotive component portfolios and specialized motor manufacturers focusing on precise motion control. Companies are increasingly pursuing strategic partnerships for technology co-development and portfolio diversification to enhance their competitive positioning across different vehicle segments.
On the premium-tier vector, Japan-based Denso Corporation exemplifies a large Tier-1 supplier leveraging its extensive network for OEM contracts and integrated system delivery. Robert Bosch GmbH, a German-based multinational engineering and electronics company, occupies a position specializing in complete dashboard systems, often integrating its own motor components. Japan-based Nidec Corporation represents a specialist in miniaturization and power efficiency, targeting both automotive and adjacent industrial applications with its motor technologies. These companies anchor significant portions of the supply chain for advanced instrument clusters.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Valeo |
| MAHLE GmbH |
| Nidec Corporation |
| Johnson Electric Holdings Ltd. |
| Mitsuba Corporation |
| Mabuchi Motor Co., Ltd. |
| Brose |
| Others |
Cost & Logistics Intelligence
Original Equipment Manufacturers represent the largest buyer archetype in the automotive odometer stepping motor market. Their demand for custom-specified components drives a contract-based pricing model, influencing supply chain stability.
Pricing Analysis
Premium pricing for short lead times characterizes the high-performance hybrid motor segment due to specialized manufacturing. The dominant pricing model is contract-based long-term offtake, particularly for OEM volumes. Price differentiation stems from quality grade and certification level, especially for NHTSA-compliant motors. Pricing pressure stems from raw material price volatility, specifically for rare-earth elements. Aftermarket suppliers represent the most price-sensitive segment, while premium passenger vehicle OEMs are least sensitive.
Supply Chain Analysis
Rare-earth material supply for high-performance hybrid motors primarily rests on China, which also anchors significant automotive component manufacturing. Semiconductor foundries in Taiwan and South Korea are critical for driver ICs. The supply chain risk is single-source vulnerability for specialized ICs, creating bottleneck risks. Distribution runs through Tier-1 component manufacturers, who integrate motors into complete instrument clusters before supplying to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive odometer stepping motor market operates as a supply-constrained story, particularly for advanced components. Specialized semiconductor foundries for driver ICs represent a capacity bottleneck, propping up pricing for integrated modules.
For Market Incumbents: Cement long-term OEM relationships by offering pre-calibrated, integrated motor modules, bundling driver ICs and software. This counters the threat from new entrants offering discrete components and mitigates margin pressure from procurement shifts. Investment in compliant material alternatives for RoHS directives ensures continued market access in Europe. Deepen vertical integration into specialized semiconductor manufacturing to reduce supply chain risk.
For New Entrants and Emerging Players: Cost-sensitive aftermarket suppliers in emerging markets like India and Brazil represent an underserved buyer archetype. Target these regions with robust, cost-effective permanent magnet motors for vehicle repair and maintenance. A direct-to-distributor go-to-market angle allows for rapid penetration and lower overheads. Focus on standardization and broad compatibility with older vehicle models to capture significant market share.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with strong intellectual property in motor miniaturization or power efficiency. Long-term viability for this market remains stable over a 5-10 year window, driven by sustained hybrid cluster demand. Acquire companies with proven expertise in digital control systems or proprietary motor driver ICs. A signal to watch is the sustained growth in hybrid vehicle sales, indicating continued demand for physical gauges.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand manufacturing capacity for hybrid motors in China | This move addresses concentrated demand and leverages existing automotive production ecosystems. |
| License proprietary digital control algorithms for motor precision | This enhances product differentiation and meets the demand for advanced instrument cluster functionality. |
| Establish a manufacturing presence in India for cost-effective PM motors | This captures the growing aftermarket segment and reduces logistics costs for regional supply. |
| Partner with semiconductor foundries for secure driver IC supply | This mitigates critical supply chain bottleneck risks for integrated motor modules. |
| Invest in software integration for fully digital cluster compatibility | This positions the company for the long-term shift towards software-defined vehicle architectures. |
Research Approach
Regulatory filings from the NHTSA, European RoHS directives, and MIIT policy documents formed the secondary backbone for this analysis. This was triangulated with primary interviews involving Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and automotive electronics R&D directors. Bottom-up data on vehicle production volumes and top-down market sizing validated the findings.
A bottom-up approach aggregated demand across vehicle types, motor technologies, and end-user segments throughout the analysis window. This was cross-referenced with a top-down market sizing based on global automotive production forecasts. Segmentation dimensions modeled included motor type, application, technology, end-user, and regional demand clusters. Compound annual growth rates were derived from historical trends and projected technological adoption curves.
Revisions become necessary when significant shifts in vehicle electrification or raw material supply dynamics materialize. Forecasts reflect assumptions documented at publication. Geopolitical events impacting semiconductor supply or new regulatory mandates represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Vibrator Motor Market
Electric Motor
Voice Coil Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Air Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Torque Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Automotive Traction Motor Market