
 Automotive Torque Actuator Motor Market | 2026-2036
Automotive Torque Actuator Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Torque Actuator Motor Market Analysis
OEM direct procurement channels is tilting toward consolidated tier-one supply agreements with embedded electronics specialists. Continental AG leverages its integrated powertrain division to bundle torque actuator motors with transmission control modules. Robert Bosch GmbH sustains manufacturing scale across multiple actuator categories through captive semiconductor sourcing. Denso Corporation anchors its position in electromechanical torque systems via R&D intensity in brushless motor architectures.
An automotive torque actuator motor converts electrical or hydraulic energy into precise rotational or linear force for vehicle subsystem control, typically operating at voltage ranges from 12V to 48V with position feedback resolution below 0.1 degrees. Rotary actuators dominate brake-by-wire and steering applications where angular positioning accuracy determines safety performance. Intelligent Control Systems within the technology dimension command margin premiums as OEMs specify embedded diagnostic protocols and real-time torque ripple compensation. Electromechanical platforms displace hydraulic alternatives in passenger vehicle segments where weight reduction and energy recuperation shape platform architecture decisions.
NHTSA, EPA, and the EU Green Deal collectively mandate CO2 reduction trajectories that force actuator motor efficiency improvements across power steering and transmission control applications. The EU AI Act and emerging UNECE cybersecurity regulations extend compliance burdens to intelligent control systems with embedded software. Stakeholders must monitor regulatory divergence between United States fuel economy standards and European CO2 fleet targets when configuring regional product portfolios.
Market Dynamics
Electric power steering architectures are compressing actuator motor specifications toward 48V platforms with embedded position sensing, forcing suppliers to recalibrate winding densities and thermal management systems across production lines.
Growth Catalysts
- NHTSA Corporate Average Fuel Economy mandates:Tightening efficiency thresholds in the United States accelerate OEM procurement of electromechanical torque systems that recuperate energy during steering maneuvers.
- Brushless DC architectures:Permanent magnet synchronous motors with integrated Hall-effect sensors enable sub-0.1-degree positioning accuracy required for brake-by-wire safety systems.
- Germany's automotive manufacturing corridor:Concentrated OEM final assembly in Baden-Württemberg and Bavaria sustains localized demand for just-in-time actuator motor delivery.
Market Restraints
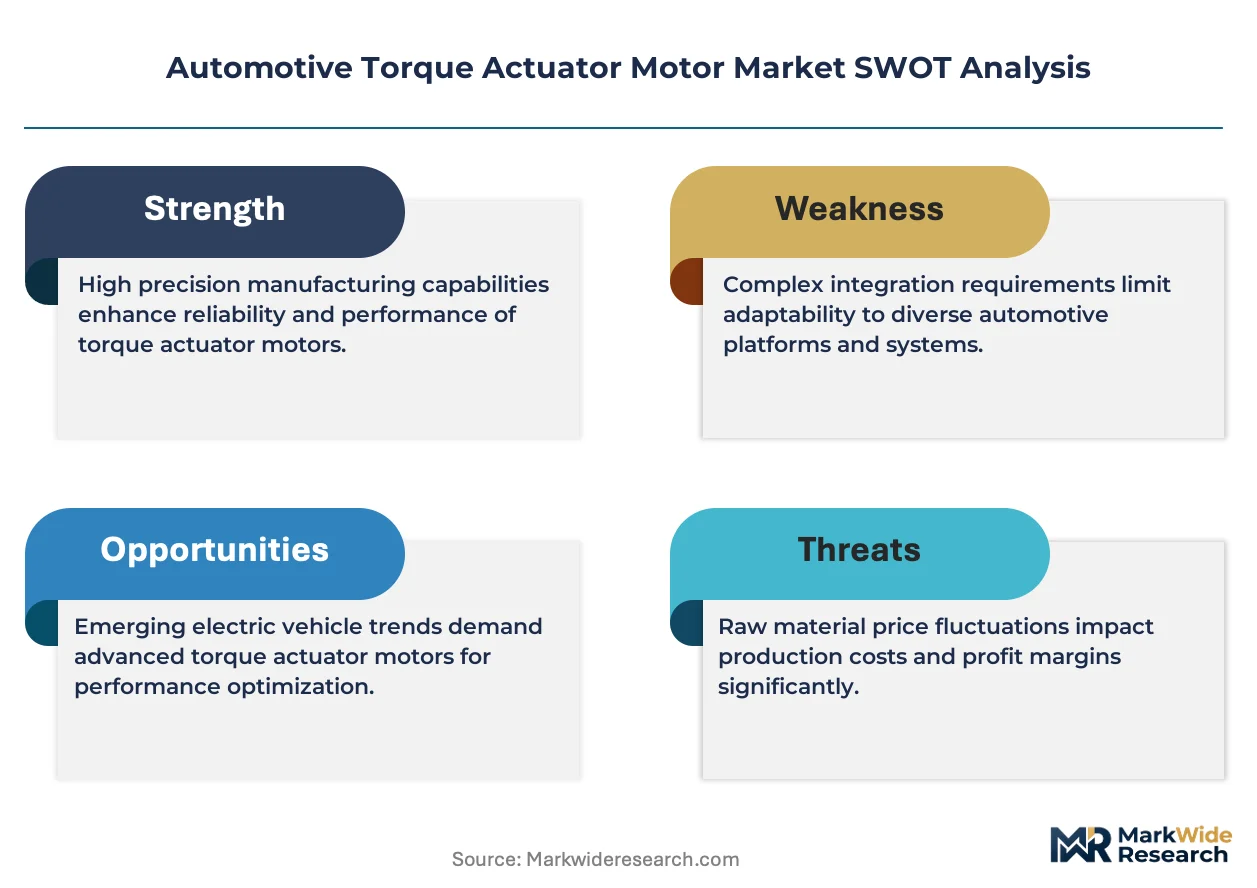
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in rotor assemblies compress margin predictability for motor manufacturers.
- Semiconductor supply concentration:Dependence on Taiwanese foundries for gate driver ICs creates vulnerability in intelligent control system production.
- Hydraulic legacy infrastructure:Existing service networks and technician training for power steering fluid systems slow full electromechanical conversion in commercial vehicle segments.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty truck steer-by-wire adoption in North American long-haul fleets opens volume contracts for high-torque actuator platforms.
- EU AI Act compliance services:Embedded diagnostic protocol certification for intelligent control systems creates recurring revenue streams for software-integrated motor suppliers.
- Transmission control module bundling:Powertrain integration contracts allow actuator specialists to capture value from adjacent electronic control unit procurement decisions.
Industry Challenges
- Embedded software certification timelines:UNECE cybersecurity regulation validation for intelligent control systems extends product launch cycles by 12-18 months.
- Multi-physics simulation expertise:Scarcity of engineers combining electromagnetic, thermal, and control systems modeling restricts R&D throughput at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Torque Actuator Motor Market |
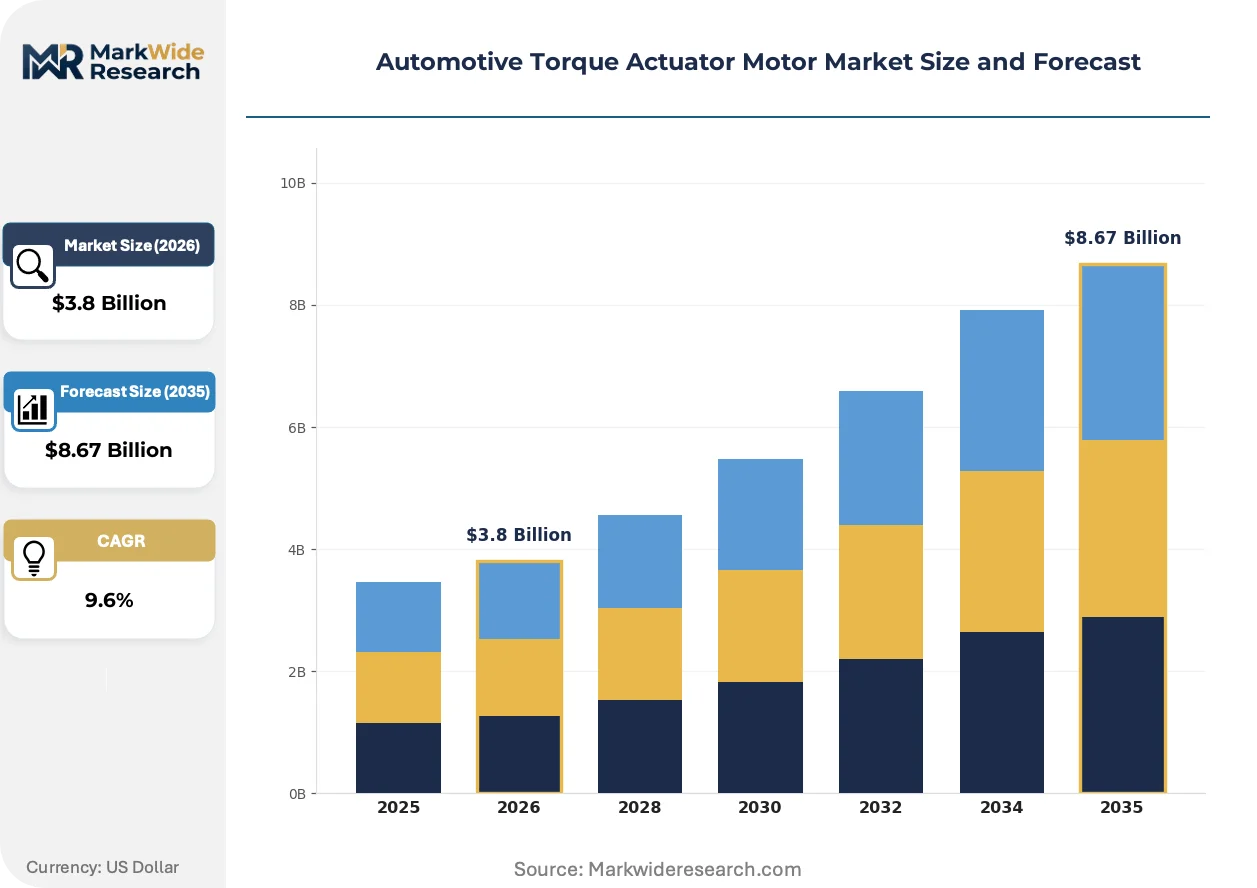
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Electric Motors, Hydraulic Motors Application: Power Steering, Brake Systems, Transmission Control, Suspension Systems End User: OEMs, Aftermarket Suppliers, Commercial Vehicles, Passenger Vehicles Technology: Electromechanical, Hydraulic, Pneumatic, Intelligent Control Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Nidec Corporation, Johnson Electric Holdings Limited, Mitsuba Corporation, CTS Corporation, NSK Ltd., HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Torque Actuator Motor Market Emerging Trajectories
Actuator motor architectures are bifurcating between commodity 12V platforms for economy vehicles and intelligent 48V systems with embedded diagnostics, compressing the viable middle tier of suppliers.
Magnet wire insulation systems are migrating from traditional enamel coatings to high-temperature polyimide films rated above 200°C. Tier-one suppliers in Japan and South Korea are qualifying these materials for 48V mild-hybrid steering applications. The shift is migrating from niche performance segments toward mainstream passenger vehicle platforms as thermal density requirements tighten.
The EU AI Act's risk classification framework for automotive embedded software is forcing torque actuator manufacturers to document algorithmic decision pathways for real-time torque ripple compensation. German regulators at KBA are interpreting these provisions strictly for safety-critical steering functions. OEMs are responding by mandating ISO 26262 ASIL-D certification as a baseline procurement requirement.
Fleet operators in North American commercial vehicle segments are unbundling actuator motor replacement decisions from traditional dealership service contracts. Independent service networks with CAN diagnostic capabilities are capturing aftermarket volume previously controlled by OEM captive channels. This pattern is most visible in long-haul trucking corridors between Michigan and Texas where downtime cost sensitivity exceeds brand loyalty.
Automotive Torque Actuator Motor Market Segmentation
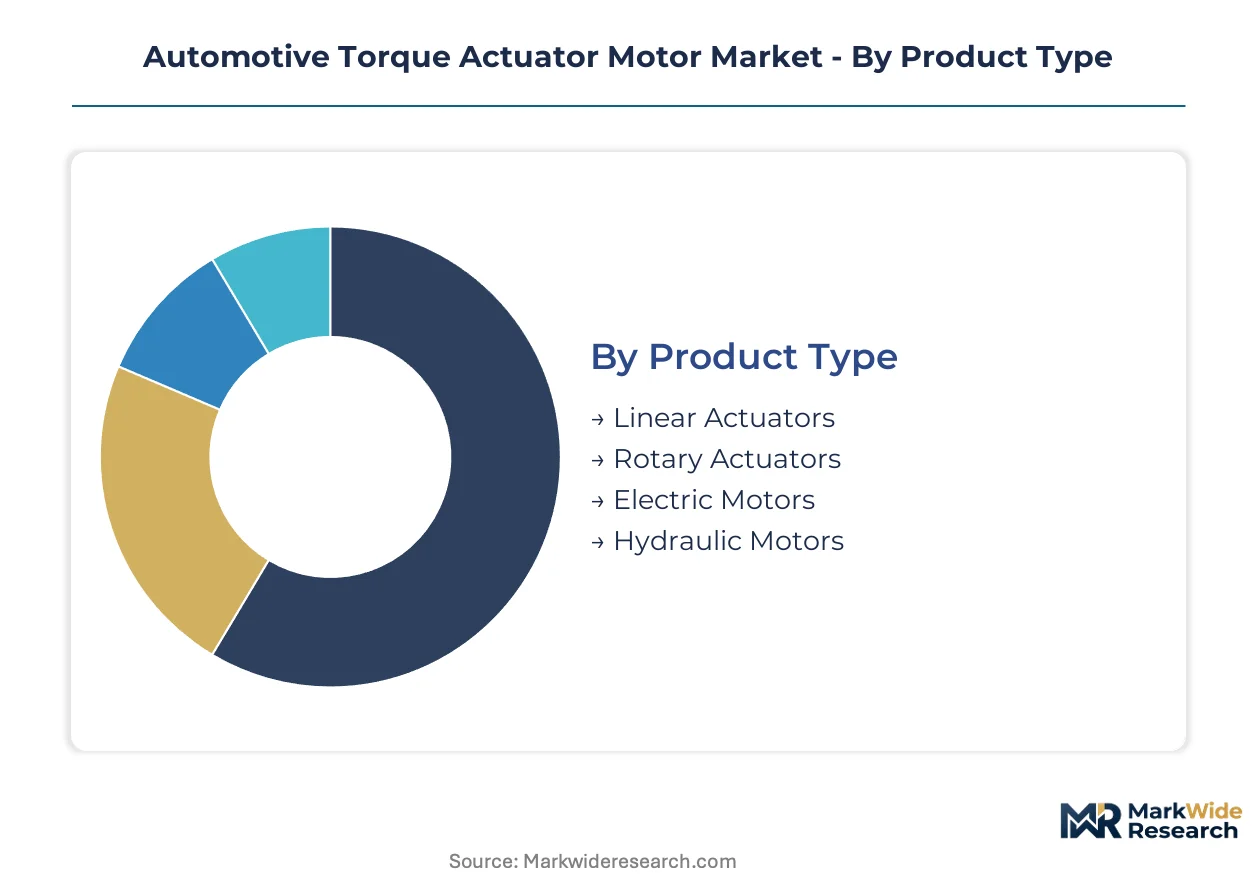
Torque actuator motor procurement patterns diverge sharply between OEM specification cycles and aftermarket replacement intervals. Segment-level profitability depends on matching voltage platform requirements to end-use thermal constraints and regulatory certification burdens.
Product Type:
Aftermarket service networks generate recurring revenue through replacement actuator assemblies, with warranty claim rates varying by motor architecture and vehicle duty cycle intensity.
- Linear Actuators:Convert rotational input to precise linear displacement via ball screw or rack-and-pinion mechanisms. Demand clusters in Germany's premium OEM supply chains where transmission control modules require sub-millimeter shift fork positioning accuracy. NHTSA brake-by-wire mandates are accelerating procurement of fault-tolerant linear designs with redundant position feedback.
- Rotary Actuators:Deliver angular torque output through direct-drive or geared configurations with integrated Hall-effect sensing. Power steering applications in Michigan and Texas manufacturing corridors specify these units for 48V mild-hybrid platforms where energy recuperation during steering maneuvers meets EPA efficiency thresholds.
- Electric Motors:Permanent magnet synchronous and brushless DC architectures dominate passenger vehicle electrification roadmaps.
- Hydraulic Motors:Retain installed base in commercial vehicle power steering where fluid-based torque multiplication handles extreme load cycles.
By volume, Rotary Actuators lead. By growth pace, Electric Motors is ahead.
Application:
Cost tier differentiation separates safety-critical brake systems from comfort-oriented suspension applications, with ISO 26262 ASIL certification requirements determining supplier qualification barriers.
- Power Steering:Electric power steering motors operate at 12V-48V with torque ripple compensation algorithms embedded in gate driver firmware. Bosch and Continental in Baden-Württemberg supply these units to premium German OEMs specifying real-time diagnostic protocols under EU AI Act risk classification frameworks.
- Brake Systems:Brake-by-wire actuators demand sub-0.1-degree position resolution with redundant channel architectures. NHTSA federal motor vehicle safety standards mandate fail-operational performance, concentrating procurement among suppliers with captive semiconductor sourcing and electromagnetic interference testing capabilities.
- Transmission Control:Shift actuator motors integrate with mechatronic control modules for dual-clutch and automated manual architectures.
- Suspension Systems:Active damper actuators adjust damping force in milliseconds based on road surface detection inputs.
Power Steering commands the largest addressable base. Brake Systems is climbing the fastest as safety electrification accelerates.
End User:
Customer type fragmentation creates divergent pricing power, with OEM direct contracts rewarding scale and aftermarket channels privileging diagnostic capability and inventory velocity.
- OEMs:Direct procurement contracts specify embedded software certification, thermal management validation, and just-in-sequence delivery to final assembly plants. Tier-one suppliers in Germany's automotive corridor bundle actuator motors with adjacent electronic control units to capture powertrain integration value.
- Aftermarket Suppliers:Independent service networks with CAN diagnostic tools are unbundling replacement decisions from dealership captives in North American long-haul trucking corridors. Downtime cost sensitivity exceeds brand loyalty where fleet operators prioritize parts availability over OEM provenance.
- Commercial Vehicles:Heavy-duty steer-by-wire adoption in North American fleets opens volume contracts for high-torque platforms.
- Passenger Vehicles:Mass-market platforms drive 12V commodity actuator specifications with cost-down pressures.
OEMs dominate current revenue. Aftermarket Suppliers is gaining share fastest as vehicle age extends and independent service networks expand diagnostic capabilities.
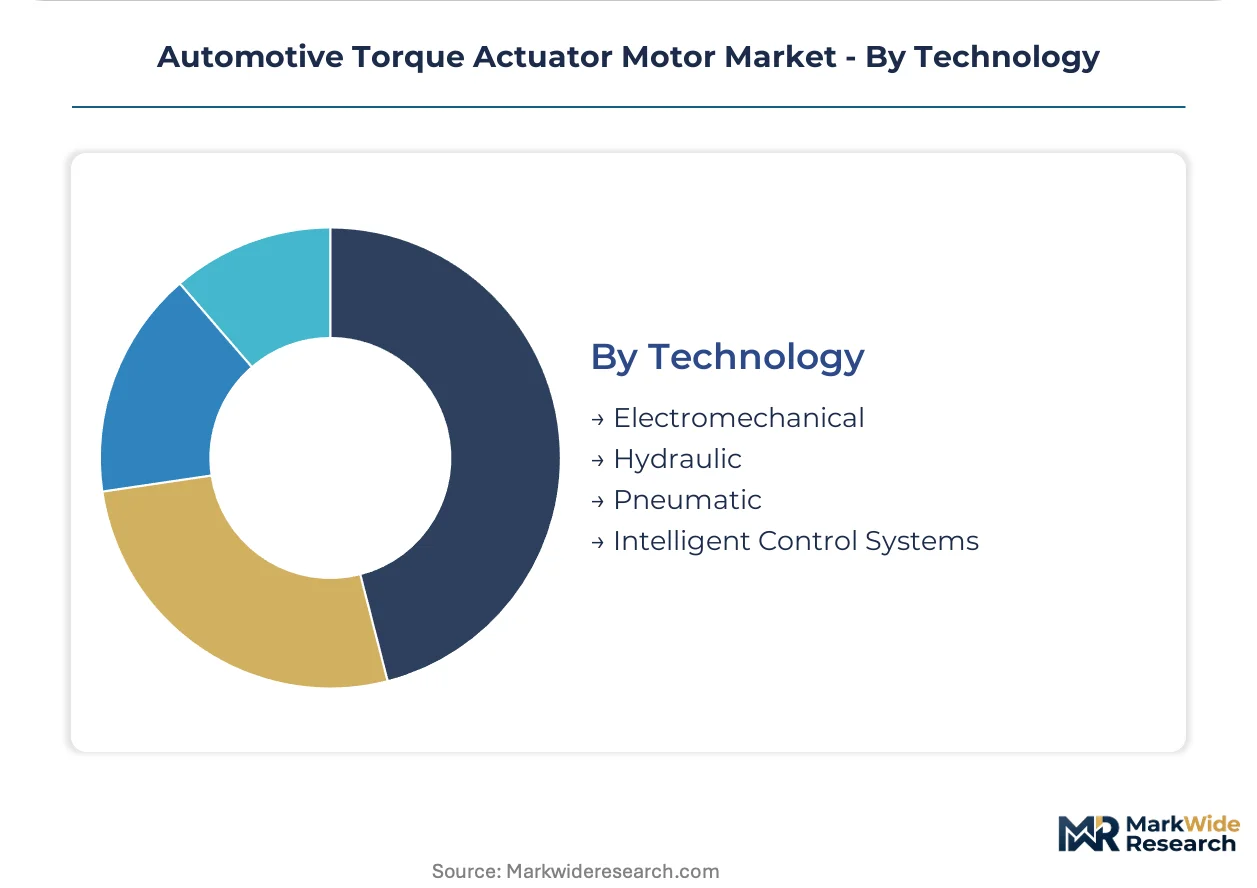
Technology:
Technology maturity curves separate established electromechanical platforms from emerging intelligent control architectures with embedded software certification burdens.
- Electromechanical:Brushless DC and permanent magnet synchronous motors displace hydraulic alternatives in passenger segments where weight reduction and energy recuperation shape platform decisions. Denso Corporation's R&D intensity in winding density optimization and thermal management supports manufacturing scale across multiple actuator categories.
- Intelligent Control Systems:Embedded diagnostic protocols and real-time torque ripple compensation command margin premiums. UNECE cybersecurity regulations and EU AI Act compliance extend validation timelines, creating recurring revenue streams for software-integrated motor suppliers with ISO 26262 ASIL-D certification.
- Hydraulic:Retains commercial vehicle installed base where fluid power density handles extreme duty cycles.
- Pneumatic:Limited to specialty applications requiring explosion-safe operation or rapid exhaust capability.
Electromechanical platforms lead by installed volume. Intelligent Control Systems shows the steepest expansion trajectory as regulatory software mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision actuator exports, while the Detroit-Windsor automotive corridor anchors North American electromechanical procurement. These infrastructure assets shape regional competitive positioning across torque motor supply chains.
United States
NHTSA Corporate Average Fuel Economy mandates compress procurement timelines for 48V steering actuators in Michigan and Texas manufacturing corridors. EPA emissions standards tighten thermal efficiency requirements for powertrain-integrated motors. Detroit's just-in-sequence delivery networks sustain Bosch and Continental supply relationships with domestic OEM final assembly plants.
Germany
KBA interpretation of EU AI Act risk classifications forces ISO 26262 ASIL-D certification for intelligent steering functions across Baden-Württemberg and Bavaria. The EU Green Deal's CO2 fleet targets accelerate electromechanical displacement of hydraulic alternatives. Stuttgart's automotive manufacturing corridor concentrates tier-one supplier engineering centers for torque ripple compensation algorithms.
China
MIIT new energy vehicle production quotas expand domestic demand for brushless DC architectures in Yangtze River Delta manufacturing zones. Dual carbon goals mandate efficiency improvements across power steering and transmission control applications. Shanghai's port infrastructure supports export-oriented actuator motor production for European OEM supply contracts.
Japan
METI technology roadmaps prioritize permanent magnet synchronous motor R&D intensity for next-generation steer-by-wire platforms. JIS standards govern thermal management validation protocols for 48V mild-hybrid applications. Nagoya's industrial corridor anchors Denso Corporation manufacturing scale across multiple electromechanical actuator categories.
South Korea
MFDS automotive safety regulations align with UNECE cybersecurity frameworks for embedded diagnostic protocols in intelligent control systems. Government EV subsidy programs expand procurement of compact torque actuators for domestic OEM electrification roadmaps. Busan-Ulsan manufacturing clusters support high-volume production of magnet wire insulation systems rated above 200°C.
Automotive Torque Actuator Motor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying winding assemblies and position sensors. The vendor base concentrates around tier-one automotive suppliers with captive powertrain divisions, while mid-tier winding houses and semiconductor gate driver specialists occupy fragmented upstream positions. Two strategic archetypes dominate: integrated powertrain bundlers capturing adjacent electronic control unit value, and electromechanical pure-plays defending margin through thermal management specialization. Competitive moves center on transmission control module integration contracts and 48V platform qualification racing.
Among Germany-based platform integrators, Continental AG and Robert Bosch GmbH exemplify the powertrain bundling archetype, anchoring supply relationships through integrated electronics divisions. Denso Corporation represents the electromechanical specialist tier with R&D intensity in brushless motor architectures. These three entities occupy positions that span the voltage platform spectrum from 12V commodity specifications to intelligent 48V systems with embedded diagnostics.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Nidec Corporation |
| Johnson Electric Holdings Limited |
| Mitsuba Corporation |
| CTS Corporation |
| NSK Ltd. |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet cost volatility determines both the spread between premium and economy actuator tiers and the geographic configuration of rotor assembly sourcing. Neodymium and dysprosium price swings embedded in permanent magnet synchronous motors compress margin predictability for manufacturers while pushing procurement toward captive magnet sourcing in China and Japan.
Pricing Analysis
Volume-discount tiering structures separate OEM direct contracts from aftermarket replacement channels. Three-tier pricing stratifies across intelligent 48V systems with embedded diagnostics, standard electromechanical platforms for mid-market passenger vehicles, and commodity 12V units for economy segments. Price differentiation hinges on ISO 26262 ASIL certification grade and volume scale commitments in just-in-sequence delivery contracts. Cost compression in the commodity tier intensifies because Chinese manufacturers are expanding brushless DC winding capacity for domestic OEM electrification roadmaps. Fleet operators in North American long-haul trucking corridors exhibit highest price sensitivity, while premium German OEMs in Baden-Württemberg demonstrate lowest sensitivity due to safety-critical brake-by-wire specification requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for gate driver IC procurement. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while rare earth magnet processing draws from China, Japan, and Australia. Magnet wire insulation systems with high-temperature polyimide films hinge on petrochemical feedstock availability in South Korea and Japan. Single-source vulnerability in Taiwanese foundries for intelligent control system components threatens production continuity. Distribution runs through tier-one supplier engineering centers in Germany's automotive corridor and just-in-sequence delivery networks anchored by Detroit-Windsor manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive torque actuator motor demand follows passenger vehicle production cycles, with NHTSA Corporate Average Fuel Economy mandate tightening accelerating replacement demand for electromechanical steering platforms.
For Market Incumbents: Harden supply chain resilience through backward integration into rare earth magnet sourcing and captive semiconductor gate driver production. Consolidate tier-one supply agreements with embedded electronics specialists to defend against emerging pure-play thermal management competitors. Expand ISO 26262 ASIL-D certification coverage across intelligent control system portfolios to meet KBA interpretation of EU AI Act risk classifications for safety-critical steering functions. For New Entrants and Emerging Players: Build out diagnostic protocol certification services for intelligent control systems as recurring revenue streams. Target aftermarket replacement channels in North American long-haul trucking corridors where independent service networks with CAN capabilities are unbundling decisions from OEM captive channels. Penetrate through fleet operator relationships prioritizing parts availability over brand provenance. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors electromechanical pure-plays with thermal management specialization. Over the medium-term horizon, acquisition targets with R&D intensity in brushless motor architectures and existing 48V platform qualification offer strongest viability. Monitor NHTSA brake-by-wire mandate implementation timelines as the signal to watch for inflection in safety-critical actuator procurement volumes.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Platform Qualification | Captures EPA efficiency threshold compliance in Michigan and Texas manufacturing corridors. |
| Transmission Control Module Bundling | Enables Continental and Bosch to capture adjacent electronic control unit procurement decisions. |
| EU AI Act Compliance Certification | Creates recurring revenue streams for software-integrated motor suppliers with KBA-validated protocols. |
| Rare Earth Magnet Backward Integration | Reduces neodymium price exposure in rotor assembly cost structures. |
| Aftermarket Diagnostic Network Expansion | Captures fleet operator replacement volume in North American long-haul trucking corridors. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and customs records tracking actuator motor trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the quantitative approach throughout the projection horizon. Segmentation dimensions modeled include product type, application, end user, technology, vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from unit shipment trajectories cross-referenced with average selling price movements. Industry-specific forecast inputs incorporated NHTSA fuel economy mandate compliance timelines and EU Green Deal CO2 fleet target trajectories.
Sensitivities concentrate around rare earth magnet price volatility, Taiwanese semiconductor supply disruptions, and regulatory divergence between United States fuel economy standards and European CO2 fleet targets. Forecasts reflect documented assumptions subject to revision based on these vectors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Starter Motor Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
United States AC Motor Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Global Motor Soft Starter Market
Electric Motor
UAE Electric Motor Market
Electric Motor
E-Bike Motor Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Global Automotive Onboard Charger Market