
 Voice Coil Motor Market | 2026-2036
Voice Coil Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Coil Motor Market Analysis
Software-defined precision control subscriptions bundled with hardware is repositioning how voice coil motor vendors monetize capability. Nidec Corporation leverages its manufacturing scale across Asia-Pacific production hubs to anchor high-volume supply for consumer electronics autofocus modules. Parker Hannifin sustains differentiation through hydraulic-pneumatic crossover expertise that extends into precision linear motion systems for semiconductor fabrication.
A voice coil motor converts electrical current directly into mechanical force via a coil suspended within a permanent magnetic field, achieving stroke lengths from millimeters to centimeters with sub-micron positioning accuracy and response times under one millisecond. This electromechanical architecture serves applications requiring rapid, precise linear or rotary actuation without mechanical commutation. Miniature motors dominate unit volume in smartphone camera autofocus and medical device instrumentation where space constraints dictate form factor. High-power variants command margin concentration in semiconductor wafer handling and aerospace gimbal systems where thermal management and continuous duty cycles justify premium positioning. Precision control technology represents the fastest-growing dimension as closed-loop encoder integration and real-time compensation algorithms displace open-loop alternatives in metrology and robotic surgery platforms.
FDA 21 CFR Part 820 quality system requirements shape medical equipment motor qualification timelines in the United States, while the EU MDR and REACH substance restrictions constrain material selection and biocompatibility documentation for European market access. China's GB standards and NMPA registration pathways impose additional electromagnetic compatibility and safety testing burdens on suppliers targeting domestic diagnostic imaging OEMs. Stakeholders must monitor evolving functional safety certifications for autonomous systems as ISO 13849 and IEC 62061 requirements propagate from industrial automation into collaborative robotics and surgical assistant platforms.
Market Dynamics
Precision control software subscriptions bundled with hardware are repositioning vendor-customer relationships across automated manufacturing lines, compressing capital expenditure cycles while extending revenue streams through recurring service agreements.
Growth Catalysts
- EU MDR conformity requirements:Diagnostic imaging OEMs in Germany and France demand higher-performance documentation, pulling upgraded motor specifications into procurement contracts.
- Sub-micron positioning requirements:Precision robotics clusters in Shenzhen, Stuttgart, and Boston specify voice coil motors for wafer handling and surgical platforms.
- Closed-loop encoder integration:Real-time compensation algorithms displace open-loop alternatives in metrology and robotic surgery, expanding addressable applications.
Market Restraints
- Neodymium price volatility:Permanent magnet supply concentration in China creates input cost instability for motor manufacturers.
- FDA 21 CFR Part 820 timelines:Medical equipment motor qualification extends commercialization cycles by 18-24 months in the United States.
- Piezoelectric actuator substitution:Ceramic-based alternatives capture niche positioning applications below 10mm stroke lengths.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Smartphone assembly localization creates captive demand for miniature autofocus motors.
- ISO 13849 functional safety certification:Collaborative robotics and surgical assistant platforms require certified actuators, opening premium positioning.
- Digital twin convergence with predictive maintenance:Motor-embedded sensors enable condition monitoring subscriptions, shifting revenue to service models.
Industry Challenges
- Multi-physics simulation expertise:Thermal-magnetic-mechanical co-design requires scarce electromechanical engineering talent.
- Legacy motion controller integration:New voice coil architectures face friction retrofitting into established PLC ecosystems.
- NMPA electromagnetic compatibility testing:China's expanded safety testing burdens extend registration timelines for diagnostic imaging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Coil Motor Market |
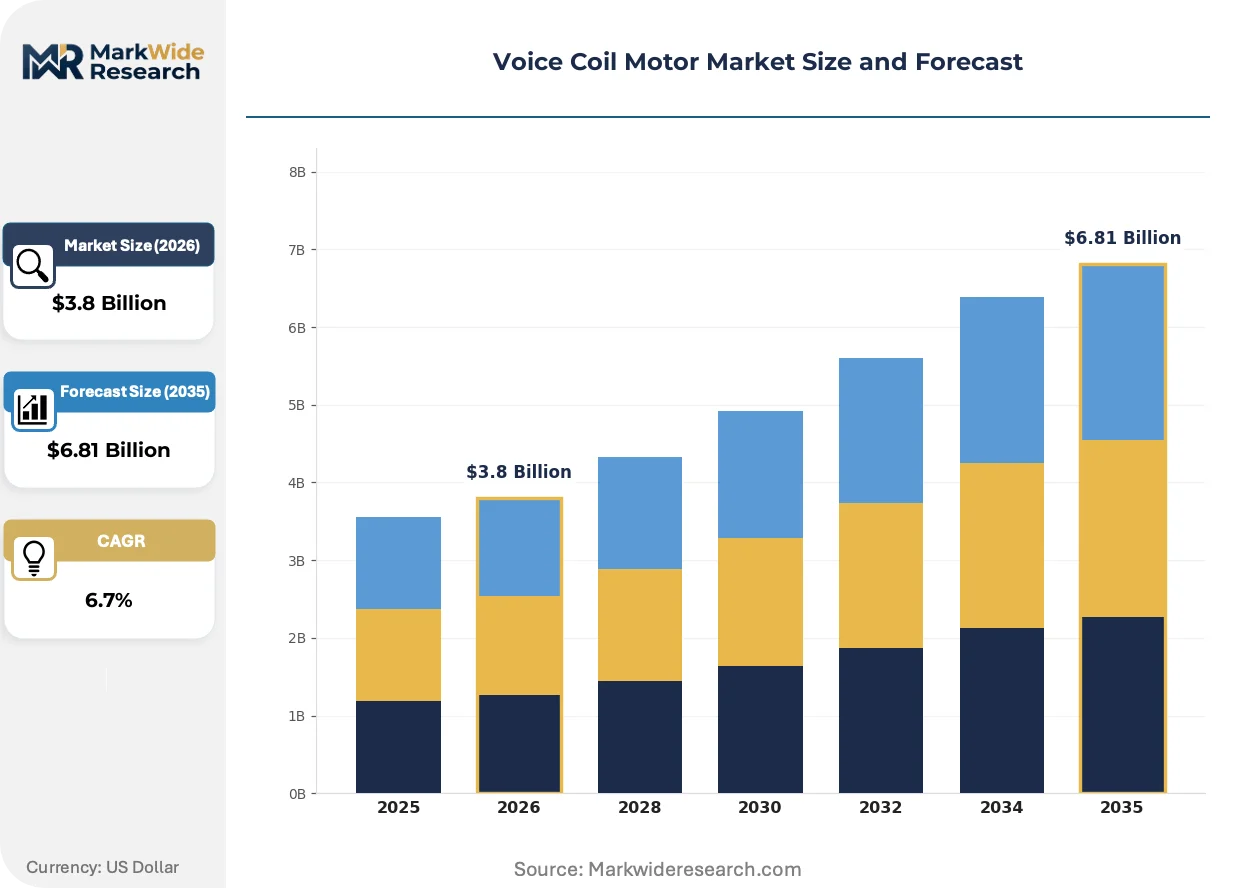
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Motors, Standard Motors, High-Power Motors, Custom Motors Application: Automated Manufacturing, Consumer Electronics, Medical Equipment, Robotics End User: Automotive, Aerospace, Healthcare, Industrial Automation Technology: Linear Motion, Rotary Motion, High-Speed, Precision Control |
| Companies Covered | Nidec Corporation, Parker Hannifin, Mitsubishi Electric, Faulhaber, Texas Instruments, Sensata Technologies, Physik Instrumente, SMAC Corporation, H2W Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Coil Motor Market Emerging Trajectories
Software-defined architectures are displacing fixed-function hardware across precision motion systems, enabling remote parameter adjustment and predictive capability upgrades without physical replacement.
Halbach array magnet configurations concentrate magnetic flux asymmetrically, delivering higher force density per unit volume. Semiconductor wafer handling equipment manufacturers in Japan and the Netherlands adopt these arrays aggressively. This topology is rewriting thermal management constraints, allowing continuous duty cycles previously reserved for hydraulic systems.
REACH substance restrictions on perfluorinated compounds constrain lubricant selection for cleanroom-compatible motors serving EU pharmaceutical automation. Formulators in Switzerland and Germany invest in ionic liquid alternatives. Medical device OEMs now specify material declarations upstream, compressing supplier qualification cycles.
Subscription-based precision control licensing replaces perpetual software purchases in German and US automotive metrology lines. Tier-one suppliers bundle encoder calibration algorithms with hardware leases. Boston-area robotic surgery platforms lead this transition, unbundling after-sales service from initial capital outlays.
Voice Coil Motor Market Segmentation
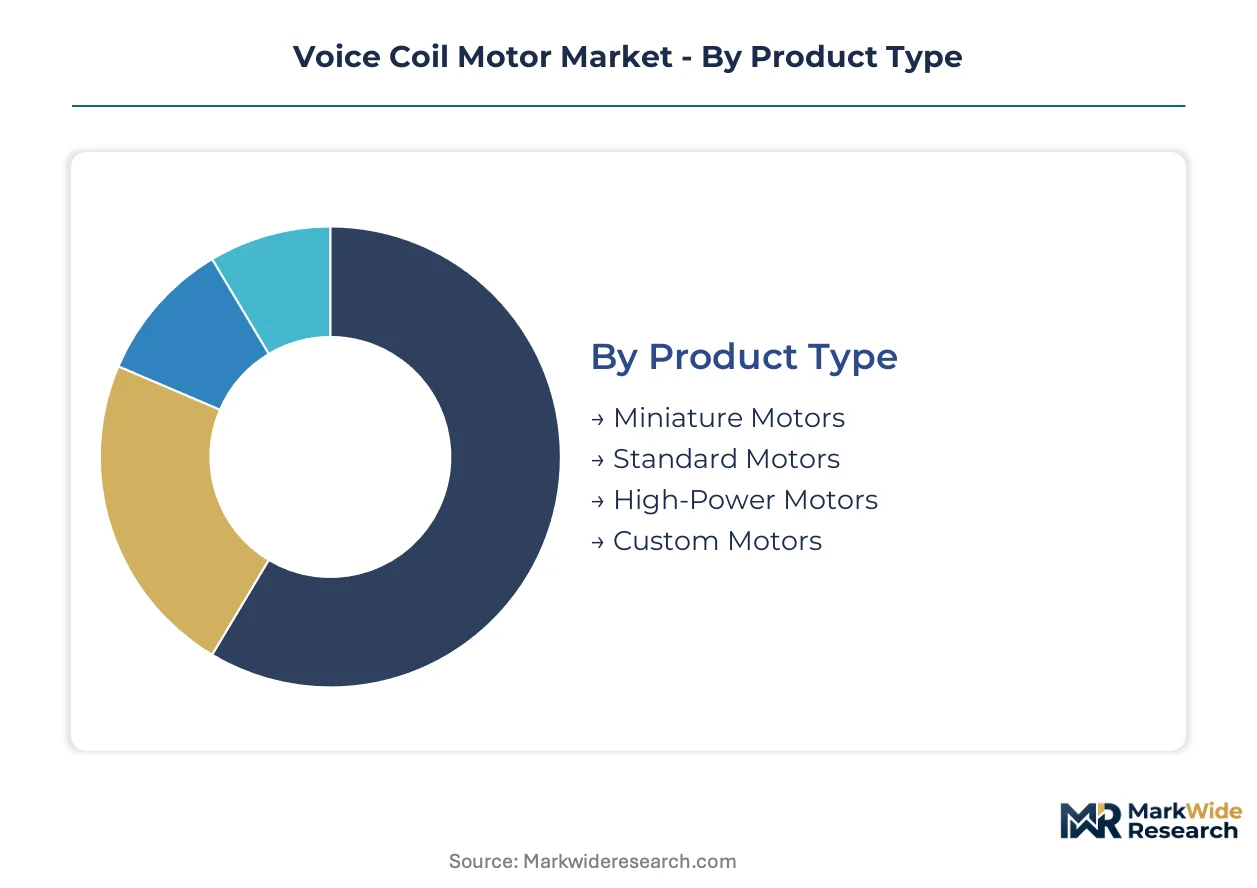
Voice coil motor procurement patterns diverge sharply across product scales and precision tiers. Capital allocation, regulatory exposure, and integration complexity vary by segment in ways that reshape vendor positioning and customer lifetime value.
Product Type:
Capital intensity escalates with magnet volume and thermal management infrastructure. Miniature motors deploy surface-mount manufacturing with minimal tooling changeover. High-power variants demand custom winding equipment and rare-earth magnet stabilization ovens that amortize across lower unit volumes.
- Miniature Motors:These units integrate voice coil actuators with sub-5mm stroke lengths into smartphone camera modules and portable medical devices. Shenzhen's electronics assembly ecosystem consumes the majority of global volume, driven by India's PLI scheme localization requirements for smartphone manufacturing.
- High-Power Motors:Continuous-duty designs handle semiconductor wafer transport and aerospace gimbal positioning with force outputs exceeding 500N. Stuttgart's precision automation cluster and Boston's surgical robotics corridor specify these units for thermal stability under sustained operation.
- Standard Motors:General-purpose linear actuators serve factory automation retrofit projects across German automotive lines.
- Custom Motors:Application-specific designs address cleanroom pharmaceutical handling with REACH-compliant material certifications.
Standard motors absorb the bulk of installed capacity; high-power variants are expanding most quickly.
Application:
Customer integration complexity determines margin capture and service attach rates. Medical equipment demands documentation intensity that extends sales cycles. Consumer electronics rewards velocity and scale over customization depth.
- Medical Equipment:Diagnostic imaging tables and robotic surgery platforms require FDA 21 CFR Part 820 quality system documentation and EU MDR conformity certification. German and French OEMs now specify motor performance envelopes upstream in procurement contracts, compressing supplier qualification timelines.
- Robotics:Collaborative arms and surgical assistants integrate closed-loop encoder feedback with ISO 13849 functional safety certification. Boston-area developers and Shenzhen precision clusters drive specification evolution toward real-time compensation algorithms.
- Automated Manufacturing:Metrology and assembly lines in Stuttgart adopt subscription-based precision control licensing bundled with hardware.
- Consumer Electronics:Smartphone autofocus modules dominate unit volume with minimal customization requirements.
Consumer electronics dominates absolute unit shipments; robotics is climbing the fastest.
End User:
Certification burden and performance specification stringency separate premium positioning from commodity supply. Healthcare and aerospace impose documentation regimes that smaller motor vendors struggle to sustain.
- Healthcare:MRI patient positioning systems and surgical navigation platforms demand NMPA electromagnetic compatibility testing for China market access alongside FDA and EU MDR pathways. The cumulative regulatory burden favors suppliers with dedicated compliance engineering teams.
- Aerospace:Satellite gimbal and flight control surface actuation requires continuous duty cycles and extended temperature range validation. Japanese and Dutch semiconductor equipment manufacturers increasingly specify Halbach array magnet configurations for force density.
- Industrial Automation:German automotive metrology lines lead adoption of software-defined precision control architectures.
- Automotive:Headlamp leveling and active suspension systems consume moderate-precision linear actuators.
Industrial automation holds the largest installed base; healthcare is gaining share fastest.
Technology:
Control architecture sophistication separates replacement demand from greenfield specification. Open-loop designs face displacement as encoder integration costs decline and real-time processing migrates to edge compute.
- Precision Control:Closed-loop systems integrate linear encoders with sub-micron resolution and adaptive compensation algorithms for thermal drift and load variation. Robotic surgery platforms in Boston and wafer handling equipment in Japan specify these architectures exclusively.
- Linear Motion:Direct-drive voice coil actuators achieve stroke lengths from millimeters to centimeters without mechanical transmission. Semiconductor fabrication equipment in the Netherlands and Germany anchors demand for contamination-free linear guidance.
- Rotary Motion:Limited-angle torque motors serve gimbal and scanner applications with direct angular positioning.
- High-Speed:Low-mass coil designs achieve response times under one millisecond for pick-and-place and vibration cancellation.
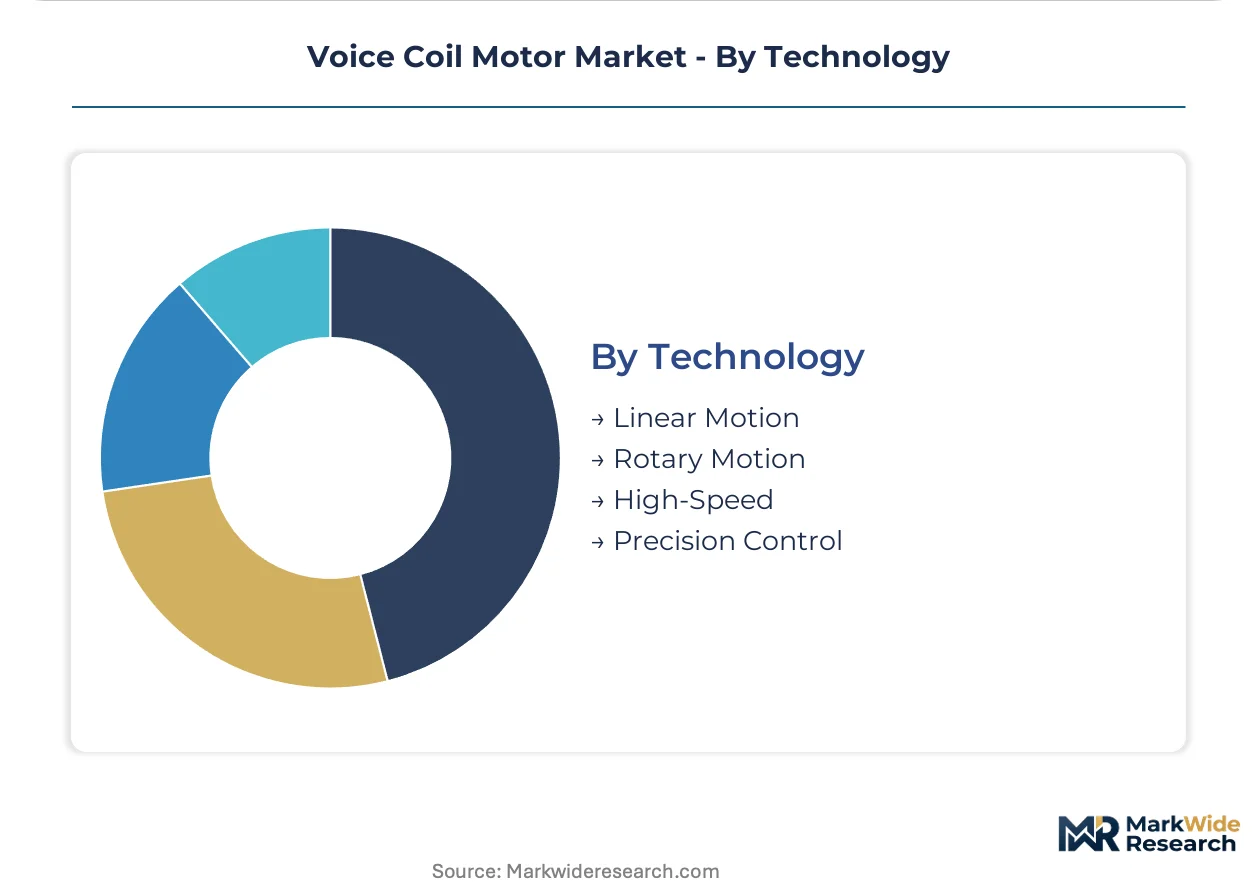
Linear motion carries the majority of legacy installations; precision control is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of rare-earth magnets and miniature motor assemblies while Germany, Japan, and the United States concentrate precision system integration and end-use demand.
China
Shenzhen's precision robotics cluster consumes high volumes of voice coil motors for semiconductor handling equipment. The NMPA's expanded electromagnetic compatibility testing requirements extend registration timelines for diagnostic imaging suppliers. Domestic magnet producers in Inner Mongolia and Jiangxi province supply neodymium raw material, though Japanese and German OEMs still specify imported motors for premium applications.
Germany
Stuttgart's automotive metrology lines lead adoption of subscription-based precision control licensing bundled with hardware. The EU MDR conformity requirements pull upgraded motor specifications into procurement contracts for French and German diagnostic imaging OEMs. Baden-Württemberg's precision automation cluster specifies high-power variants for continuous-duty wafer transport systems.
United States
Boston's surgical robotics corridor drives specification evolution toward real-time compensation algorithms and ISO 13849 functional safety certification. FDA 21 CFR Part 820 quality system requirements extend medical equipment motor qualification timelines by 18-24 months. California's semiconductor equipment designers specify Halbach array configurations for force density in contamination-free environments.
Japan
Tokyo-area semiconductor equipment manufacturers adopt Halbach array magnet configurations aggressively for wafer handling applications. METI's industrial automation initiatives support collaborative robotics development requiring certified precision actuators. Nagoya's precision machinery cluster integrates closed-loop encoder feedback for sub-micron positioning in metrology systems.
India
Tamil Nadu and Karnataka smartphone assembly hubs generate captive demand for miniature autofocus motors under the PLI scheme for electronics manufacturing. The country's national pharmaceutical regulator imposes documentation burdens on medical device motor imports that favor suppliers with dedicated compliance engineering teams. Domestic industrial automation adoption remains nascent, though German and Japanese OEMs establish local assembly for cost-sensitive applications.
Voice Coil Motor Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the voice coil motor landscape. The market structures around three tiers: integrated magnet-motor assemblers with captive rare-earth supply, precision motion specialists bundling control software with hardware, and component suppliers selling coils and magnetic assemblies to system integrators. Dominant competitive moves include backward integration into magnet production and geographic expansion through local assembly partnerships in India and Southeast Asia.
Among Asia-Pacific-based fabricators, Nidec Corporation exemplifies scale-driven manufacturing across consumer electronics and industrial segments. Parker Hannifin occupies a position bridging hydraulic-pneumatic expertise with precision linear motion systems. Physik Instrumente represents the premium-tier precision control archetype, anchoring metrology and semiconductor applications through closed-loop encoder integration.
| Leading Market Players |
|---|
| Nidec Corporation |
| Parker Hannifin |
| Mitsubishi Electric |
| Faulhaber |
| Texas Instruments |
| Sensata Technologies |
| Physik Instrumente |
| SMAC Corporation |
| H2W Technologies |
| Others |
Supply Flow & Price Mechanics
Captive magnet production in China's Inner Mongolia and Jiangxi provinces anchors supply-side positioning for voice coil motor assemblers while compressing margin capture for non-integrated competitors serving German diagnostic imaging and Boston surgical robotics OEMs. This backward integration pattern concentrates pricing power among rare-earth processors who simultaneously control raw material access and finished motor output, forcing dependent suppliers into commodity positioning on coil winding and controller electronics.
Pricing Analysis
Margin tightening in standard motor tiers reflects neodymium price volatility transmitted directly from Chinese magnet producers to German automotive metrology buyers. Three-tier pricing structure across precision control, standard linear, and economy miniature levels separates ISO 13849-certified surgical actuators from open-loop factory automation units. Cost-down pressure on miniature motors accelerates because India's PLI scheme smartphone assembly hubs prioritize volume scale over performance specification. Consumer electronics OEMs exhibit highest price sensitivity; healthcare robotics developers accept premium positioning for FDA 21 CFR Part 820 documentation bundles.
Supply Chain Analysis
EU MDR and REACH certification gating restricts cleanroom-compatible lubricant sourcing to Swiss and German ionic liquid formulators, compressing supplier qualification timelines for pharmaceutical automation motors. Magnet processing concentrates in China, Japan, and Germany; coil winding and encoder integration centers on Taiwan and South Korea. Raw material dependencies span neodymium permanent magnets, copper magnet wire, and linear encoder glass scales. Single-source vulnerability runs through Chinese rare-earth oxide refining. Distribution runs through direct OEM contracts for high-power variants and electronics distributors for miniature motors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory documentation burdens are accelerating consolidation as smaller motor vendors surrender medical equipment qualifications to integrated competitors with dedicated compliance engineering teams. This pressure architecture favors scaled precision control specialists over component assemblers lacking captive magnet supply or software bundling capability.
For Market Incumbents: Hedge neodymium cost exposure through long-term offtake agreements with Jiangxi processors or magnet recycling partnerships in Japan. Deepen software subscription attach rates among Stuttgart automotive metrology lines to offset hardware margin compression from Shenzhen miniature motor producers. Prioritize ISO 13849 certification investment for collaborative robotics positioning against emerging piezoelectric actuator substitutes. For New Entrants and Emerging Players: Launch via precision control software licensing models unbundled from hardware capital sales, targeting Boston-area robotic surgery platforms transitioning from perpetual purchases. India's PLI scheme smartphone assembly creates the most penetrable volume tier for miniature motor specialists lacking legacy medical certification infrastructure. White-space exists in REACH-compliant custom motors for EU pharmaceutical cleanroom handling where established players face lubricant reformulation delays. For Investors and Strategic Acquirers: Exit pathways concentrate in precision control software specialists with installed encoder calibration algorithm bases and recurring revenue streams from German semiconductor equipment OEMs. Long-term viability favors vertically integrated magnet-motor assemblers with demonstrated NMPA electromagnetic compatibility testing completion for China diagnostic imaging access. Watch for neodymium price inflection signals as indicators of margin compression severity forcing distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Captive neodymium supply secures cost stability against Chinese export policy volatility for German OEM contracts. |
| Precision Control Software Subscription Launch | Recurring revenue repositioning captures Stuttgart metrology lines shifting from perpetual hardware purchases. |
| ISO 13849 Functional Safety Certification | Certification gating opens collaborative robotics and surgical assistant platform specifications in Boston and Nagoya. |
| REACH-Compliant Lubricant Formulation Partnership | Ionic liquid alternatives unlock EU pharmaceutical automation procurement blocked by perfluorinated compound restrictions. |
| India PLI Scheme Local Assembly Partnership | Smartphone autofocus motor demand localization captures volume growth under electronics manufacturing incentive programs. |
Methodological Framework
SEC 10-K filings, NMPA registration databases, and EU MDR conformity assessment records formed the secondary backbone for voice coil motor market sizing and competitive positioning. Primary interviews with biomedical engineers at Boston surgical robotics developers, procurement leads at Stuttgart automotive metrology OEMs, and maintenance directors at Shenzhen semiconductor handling facilities validated secondary estimates. Bottom-up unit shipment analysis across miniature, standard, high-power, and custom motor tiers triangulated against top-down rare-earth magnet consumption data from Chinese customs records.
Historical trendline analysis across voice coil motor applications tracked encoder integration cost curves and closed-loop control algorithm adoption rates over the projection horizon. Segmentation modeling incorporated product type, application, end user, and technology dimensions with particular attention to precision control versus open-loop architecture splits. CAGRs derived from regression analysis of medical equipment and robotics application growth trajectories, with neodymium price indices and PLI scheme smartphone assembly forecasts as key industry-specific inputs.
Neodymium supply disruption, NMPA electromagnetic compatibility testing timeline extension, and piezoelectric actuator substitution acceleration are the dominant revision risks for voice coil motor demand projections. Forecasts reflect documented assumptions regarding regulatory pathway stability and rare-earth processing capacity expansion. A model refresh is warranted upon material change in Chinese magnet export policy or FDA 21 CFR Part 820 enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive ABS Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Trolling Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Automotive Hub Motors Market