
 Industrial Smart Motor Market | 2026-2036
Industrial Smart Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Smart Motor Market Foresight
IE4 super-premium efficiency classification is unwinding legacy motor procurement patterns across heavy industry. Rockwell Automation leverages embedded analytics architectures to sustain aftermarket service revenue in North American automotive plants. Siemens AG anchors European demand through integrated drive-motor platforms that compress installation footprints. ABB Ltd. competes on marine and mining applications where ruggedized smart motor designs command specification loyalty.
An industrial smart motor combines electromechanical power conversion with onboard sensing, edge computing, and digital connectivity for condition monitoring and energy optimization. These systems typically incorporate thermal sensors, vibration accelerometers, and encoder feedback loops to enable predictive maintenance protocols while maintaining efficiency ratings above IE3 thresholds. Servo motors and integrated sensor configurations lead technology segmentation due to precision motion requirements in robotics and CNC machining, while energy-efficient variants dominate volume shipments in pumping and HVAC retrofits. Variable frequency drive pairings capture margin pools in oil and gas applications where process control reliability carries premium pricing.
FERC efficiency standards, EU Ecodesign Directive tiers, and China's GB 18613 motor efficiency mandates collectively reshape product qualification requirements and procurement criteria across major economies. Compliance with these frameworks now functions as a market access gate rather than a voluntary differentiator, pushing laggard manufacturers toward redesign cycles or exit. Stakeholders must monitor regulatory harmonization progress between efficiency labeling schemes and cybersecurity certification for connected industrial equipment.
Market Dynamics
IE4 efficiency mandates are compressing procurement cycles across heavy industry as facility operators face simultaneous pressure from energy cost volatility and carbon accounting requirements. This regulatory convergence is rewiring supplier relationships and accelerating replacement demand for legacy motor fleets.
Growth Catalysts
- EU Ecodesign Directive tiers:Mandatory efficiency thresholds are compelling automotive OEMs in Germany and France to retrofit assembly lines with sensor-integrated systems before compliance deadlines.
- Predictive maintenance protocols:Thermal sensing and vibration accelerometer arrays embedded in servo motors are reducing unplanned downtime in robotics-intensive manufacturing clusters.
- China's GB 18613 standards:Domestic motor efficiency mandates are accelerating factory automation investment in Jiangsu and Guangdong provinces.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings are destabilizing permanent magnet motor production economics for high-torque applications.
- Semiconductor supply concentration:Variable frequency drive controller chips remain bottlenecked by Taiwan and South Korea foundry capacity constraints.
- Cybersecurity certification gaps:Absence of harmonized IEC 62443 implementation timelines is delaying connected motor deployments in critical infrastructure.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for industrial automation are opening greenfield smart motor demand in Pune and Chennai automotive corridors.
- Edge-to-cloud architecture convergence:Onboard motor analytics fused with centralized energy management platforms are creating new service revenue pools for system integrators.
- Marine electrification retrofits:IMO decarbonization targets are generating specification demand for ruggedized smart motors in port handling and auxiliary ship systems.
Industry Challenges
- Field technician skill gaps:Shortage of technicians trained in both electromechanical repair and digital diagnostics is extending service response times.
- Legacy SCADA integration complexity:Proprietary communication protocols in existing plant networks are forcing costly gateway deployments for smart motor connectivity.
- Dual certification timelines:Simultaneous pursuit of IE4 efficiency ratings and functional safety SIL certifications is elongating product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Smart Motor Market |
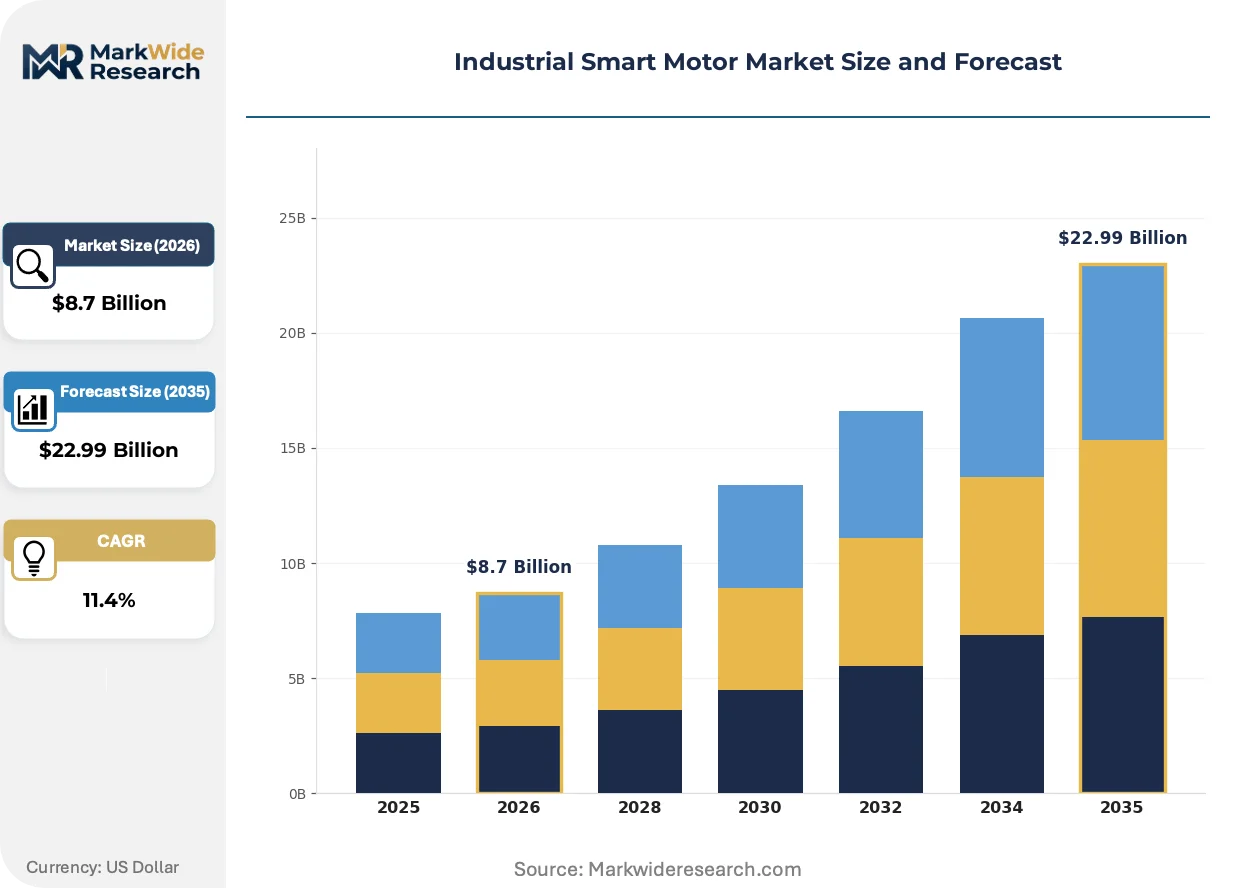
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors Technology: IoT-Enabled, Energy-Efficient, Variable Frequency Drive, Integrated Sensors End User: Automotive, Manufacturing, Oil & Gas, Food Processing Application: Conveyor Systems, Robotics, HVAC, Pumping |
| Companies Covered | Rockwell Automation, Schneider Electric, Yaskawa Electric Corporation, Delta Electronics Inc., FANUC Corporation, Mitsubishi Electric, ABB Ltd., NIDEC Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Smart Motor Market Shifts & Advancements
Digital twin integration is rewiring how motor performance data flows through industrial asset management systems. Three concurrent developments are compressing technology adoption cycles and reshaping competitive positioning.
Integrated motor-drive units with embedded power electronics are miniaturizing installation footprints in space-constrained automotive body shops. BMW and Volkswagen assembly plants in Bavaria and Lower Saxony are specifying these compact configurations for robotic welding cells. The form factor reduction is eliminating separate electrical room requirements and compressing project commissioning timelines.
FERC Order 2222 in the United States is mandating distributed energy resource participation in wholesale electricity markets. Industrial facilities with smart motor-driven pumping and HVAC loads are aggregating demand response capacity through utility programs. Oil refineries along the Gulf Coast are reconfiguring motor control strategies to capture grid services revenue.
Buyers are unbundling aftermarket service contracts from initial equipment procurement. Automotive tier-one suppliers in Stuttgart and Detroit are negotiating predictive maintenance subscriptions separately from hardware acquisition. This behavior is fragmenting vendor revenue streams and forcing motor manufacturers to build standalone software monetization capabilities.
Industrial Smart Motor Market Segmentation
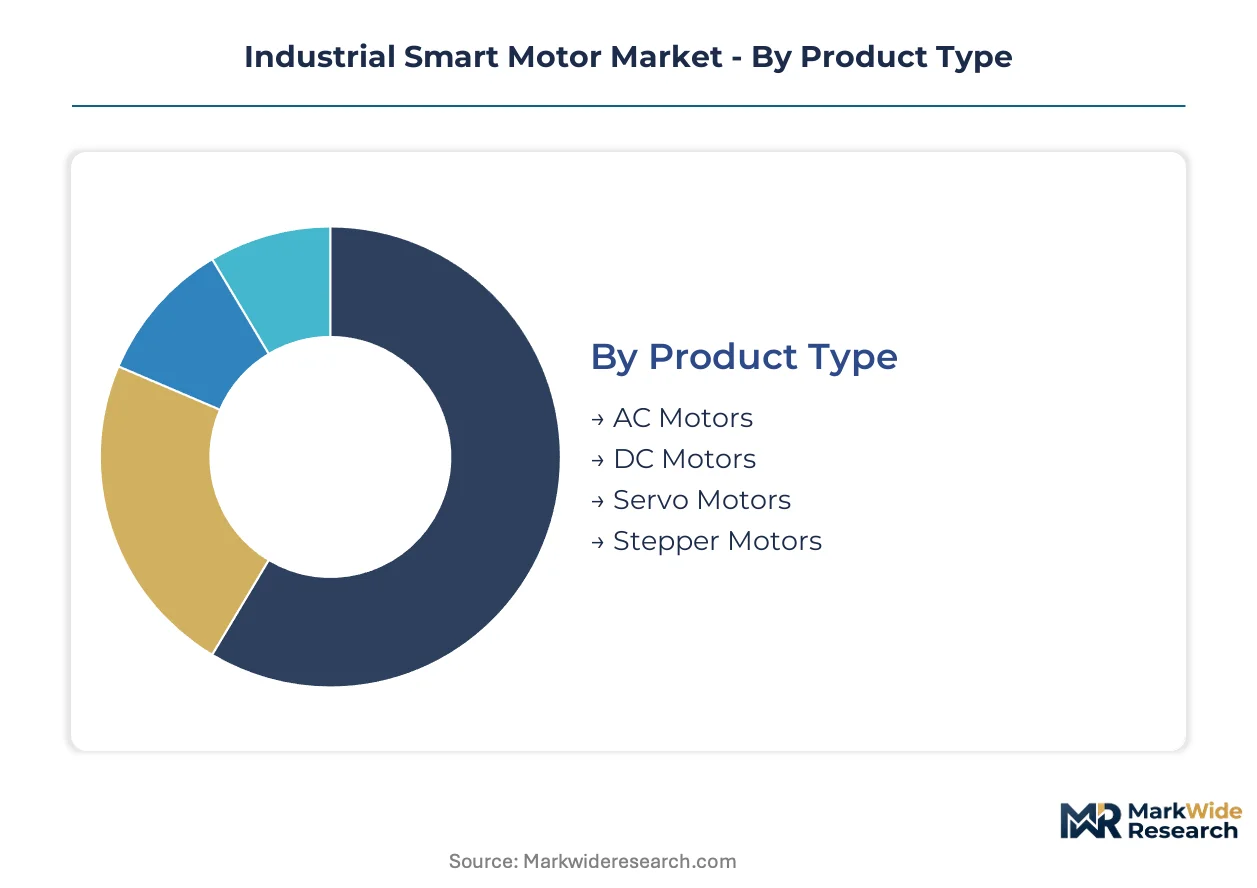
Industrial smart motor procurement patterns diverge sharply across product architectures, connectivity protocols, and duty-cycle requirements. Regulatory efficiency tiers and predictive maintenance capabilities reshape how buyers evaluate specifications across each dimension.
Product Type:
IE4 efficiency mandates in the EU Ecodesign Directive and China's GB 18613 standards create divergent qualification burdens across motor architectures, with permanent magnet designs facing rare earth supply scrutiny while induction alternatives compete on cost.
- AC Motors:Three-phase induction architectures dominate heavy-load industrial environments where continuous duty cycles exceed 8,000 annual operating hours. Demand concentrates in German automotive stamping plants and Chinese steel rolling mills where FERC efficiency standards and GB 18613 compliance deadlines accelerate replacement schedules.
- Servo Motors:Closed-loop feedback systems with embedded resolver or optical encoders deliver positioning accuracy below 0.01 degrees for multi-axis robotics. Automotive body shops in Stuttgart and Detroit specify these for welding cell retrofits as OEMs pursue predictive maintenance protocols to minimize unplanned downtime.
- DC Motors:Brushed and brushless configurations persist in battery-powered mobile equipment and legacy crane systems where simple speed control suffices.
- Stepper Motors:Open-loop positioning drives remain cost-effective for light-load indexing applications in packaging machinery and 3D printing equipment.
AC motors handle the majority of throughput; servo motors are expanding most quickly on share as precision manufacturing requirements intensify.
Technology:
Cost tier differentiation separates premium integrated platforms from retrofit sensor kits, with margin pools concentrating where edge computing and cybersecurity certification converge.
- IoT-Enabled:Embedded wireless modules and MQTT protocol stacks transmit vibration, temperature, and current signatures to cloud analytics platforms. Oil refineries along the US Gulf Coast deploy these for FERC Order 2222 demand response participation, aggregating motor-driven pumping loads into wholesale electricity markets.
- Integrated Sensors:Factory-calibrated accelerometer and thermocouple arrays enable condition-based maintenance without external instrumentation. German automotive tier-one suppliers in Lower Saxony negotiate predictive maintenance subscriptions separately from hardware acquisition, fragmenting traditional bundled revenue models.
- Variable Frequency Drive:Standalone inverter systems retrofit existing motor installations for energy recovery and soft-start functionality.
- Energy-Efficient:IE4 and IE5 rated designs prioritize magnetic material optimization over connectivity for cost-sensitive HVAC and pumping retrofits.
Variable frequency drive retrofits capture the largest installed base; integrated sensors are climbing the fastest as unbundled service contracts reshape vendor economics.
End User:
Application maturity varies by sector cybersecurity tolerance and automation intensity, with food processing lagging automotive in connected motor deployment due to washdown hygiene requirements.
- Automotive:Just-in-time assembly lines demand sub-50-millisecond fault detection to prevent cascade stoppages. BMW and Volkswagen plants in Bavaria specify compact motor-drive units that eliminate separate electrical rooms and compress commissioning timelines for robotic welding cells.
- Manufacturing:Discrete production environments in Jiangsu and Guangdong provinces combine China's GB 18613 efficiency mandates with factory automation investment incentives under national industrial upgrading programs.
- Oil & Gas:Explosion-proof enclosures and SIL-rated safety systems dominate upstream and downstream specifications.
- Food Processing:IP69K washdown ratings and stainless steel housings prioritize hygiene over connectivity in dairy and meat processing plants.
Automotive generates the highest specification intensity; manufacturing offers the steepest expansion trajectory as China's domestic automation investment accelerates.
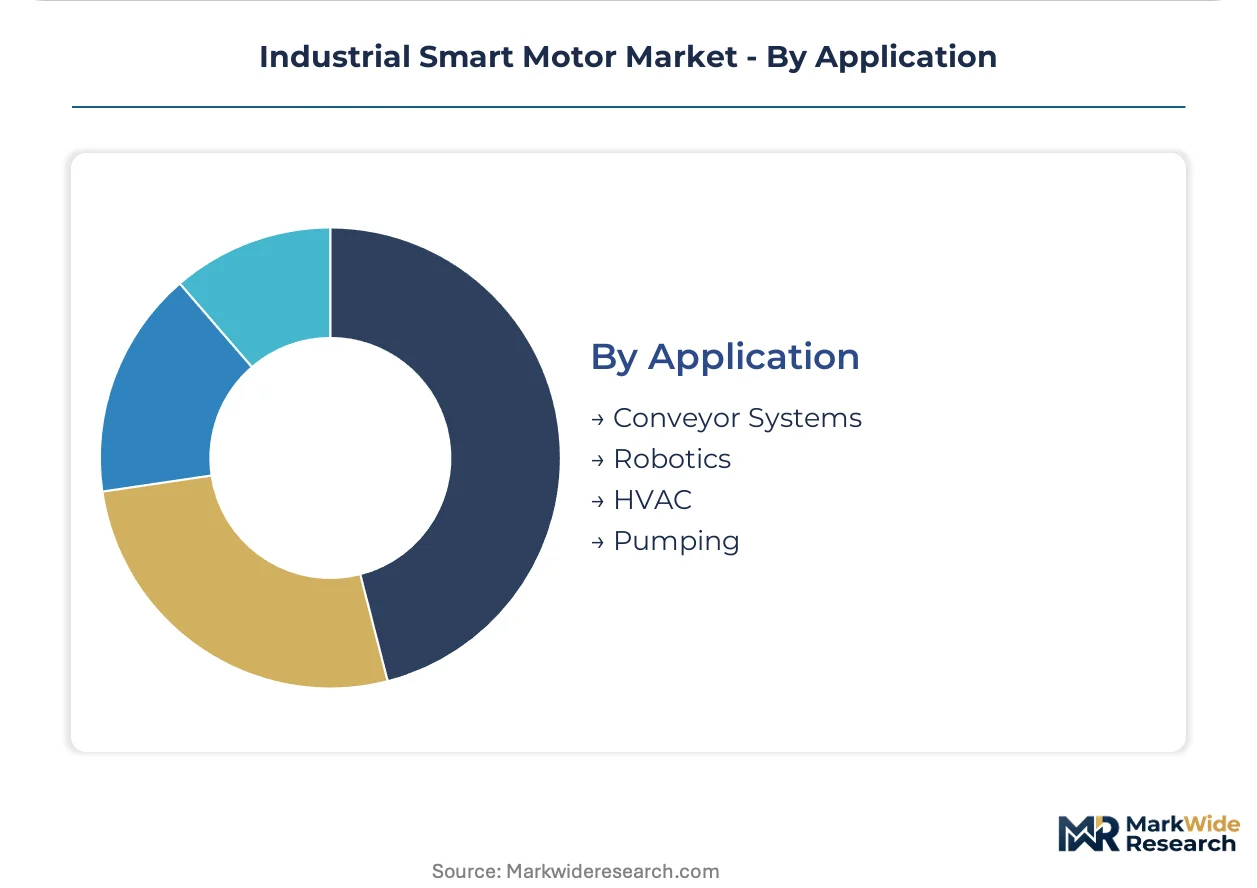
Application:
Volume concentration in pumping and HVAC contrasts with value concentration in robotics, where precision motion commands premium pricing and aftermarket service attachment.
- Robotics:Six-axis articulated arms and SCARA configurations require harmonic drive compatibility and dynamic torque response below 2 milliseconds. Japanese automotive component suppliers in Aichi Prefecture drive specification demand for compact servo motors with integrated safety encoders.
- HVAC:Centrifugal fan and chiller applications prioritize IE4 efficiency ratings and BACnet integration for building energy management. US commercial real estate operators in Texas and California retrofit smart motors to capture utility demand response incentives and comply with state decarbonization mandates.
- Conveyor Systems:Long-run material handling in logistics centers favors modular motor-roller designs with decentralized drive control.
- Pumping:Water treatment and irrigation applications dominate unit shipments with standard induction motor configurations.
Pumping and HVAC together move the greatest unit volume; robotics is gaining share fastest as precision manufacturing and collaborative automation expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing hubs with deep automation supply chains. Germany and China maintain trade surpluses in precision motor-drive systems, while the United States and India absorb volumes through domestic retrofit demand. Facility operators in automotive-heavy regions accelerate procurement to meet efficiency compliance deadlines.
United States
FERC Order 2222 mandates and utility demand response programs drive facility-level motor upgrades. The EPA and Department of Energy coordinate efficiency standards with grid integration incentives. Oil refineries along the Texas Gulf Coast reconfigure pumping loads to capture wholesale electricity market revenue.
Germany
Automotive OEM retrofit cycles and industrial automation density concentrate specification demand. The EU Ecodesign Directive tiers compel Bavarian plants to replace legacy motor fleets before enforcement dates. Stuttgart and Wolfsburg assembly corridors specify compact motor-drive units for robotic welding cells.
China
Factory automation investment incentives and domestic efficiency mandates accelerate replacement demand. GB 18613 standards from MIIT compress procurement timelines for industrial motor fleets. Jiangsu and Guangdong province manufacturing clusters deploy sensor-integrated systems under national industrial upgrading programs.
Japan
Precision robotics manufacturing and automotive component supply chains sustain premium motor demand. METI efficiency guidelines and JIS standards shape product qualification requirements. Aichi Prefecture automotive component suppliers drive specification demand for compact servo configurations with integrated safety encoders.
India
Production-linked incentive schemes and automotive corridor development open greenfield demand. The PLI scheme for manufacturing automation from the Ministry of Heavy Industries redirects capital toward smart motor procurement. Pune and Chennai automotive clusters specify networked motor systems for new assembly line deployments.
Industrial Smart Motor Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, creating a tiered structure where scale advantages meet application-specific agility. The vendor base clusters around three archetypes: diversified industrial conglomerates with integrated drive-motor platforms, automation specialists with embedded analytics architectures, and component-focused manufacturers with magnetic material expertise. Consolidation pressure intensifies as efficiency mandates and cybersecurity certification requirements raise fixed compliance costs. Dominant competitive moves include strategic partnerships for edge-to-cloud architecture development and geographic expansion into India's PLI-subsidized manufacturing corridors.
Within the diversified industrial tier, Siemens AG and ABB Ltd. occupy positions anchored by European manufacturing heritage and integrated platform strategies. Rockwell Automation exemplifies the automation specialist archetype with its embedded analytics focus on North American automotive plant aftermarket service. Japanese manufacturers including Yaskawa Electric Corporation and Mitsubishi Electric sit within the precision motion segment, representing decades of servo motor development for robotics-intensive applications. These three groupings collectively span the technology spectrum from heavy-industry induction motors to closed-loop servo configurations.
| Leading Market Players |
|---|
| Rockwell Automation |
| Schneider Electric |
| Yaskawa Electric Corporation |
| Delta Electronics Inc. |
| FANUC Corporation |
| Mitsubishi Electric |
| ABB Ltd. |
| NIDEC Corporation |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for rare earth magnet procurement concentrate pricing power with Chinese and Vietnamese material processors, compressing margins for permanent magnet motor manufacturers while amplifying cost pass-through leverage for integrated drive-motor platforms.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with IE4 certification tiers and predictive maintenance bundling as the primary differentiation drivers. Cost compression in standard induction motors is intensifying because Chinese manufacturers are absorbing rare earth volatility to maintain share. Tier-one automotive suppliers in Germany and the United States demonstrate the lowest price sensitivity due to unplanned downtime costs, while HVAC retrofit contractors in commercial real estate exhibit the highest sensitivity to upfront capital outlay.
Supply Chain Analysis
China and Vietnam anchor rare earth magnet processing and winding copper supply, while Taiwan and South Korea concentrate variable frequency drive controller fabrication. Smart motor production draws from neodymium-dysprosium permanent magnets, silicon steel laminations, and semiconductor power modules. Single-source vulnerability in Taiwan foundry capacity for insulated-gate bipolar transistor chips creates systemic exposure. Distribution runs through authorized system integrator networks that bundle commissioning services with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
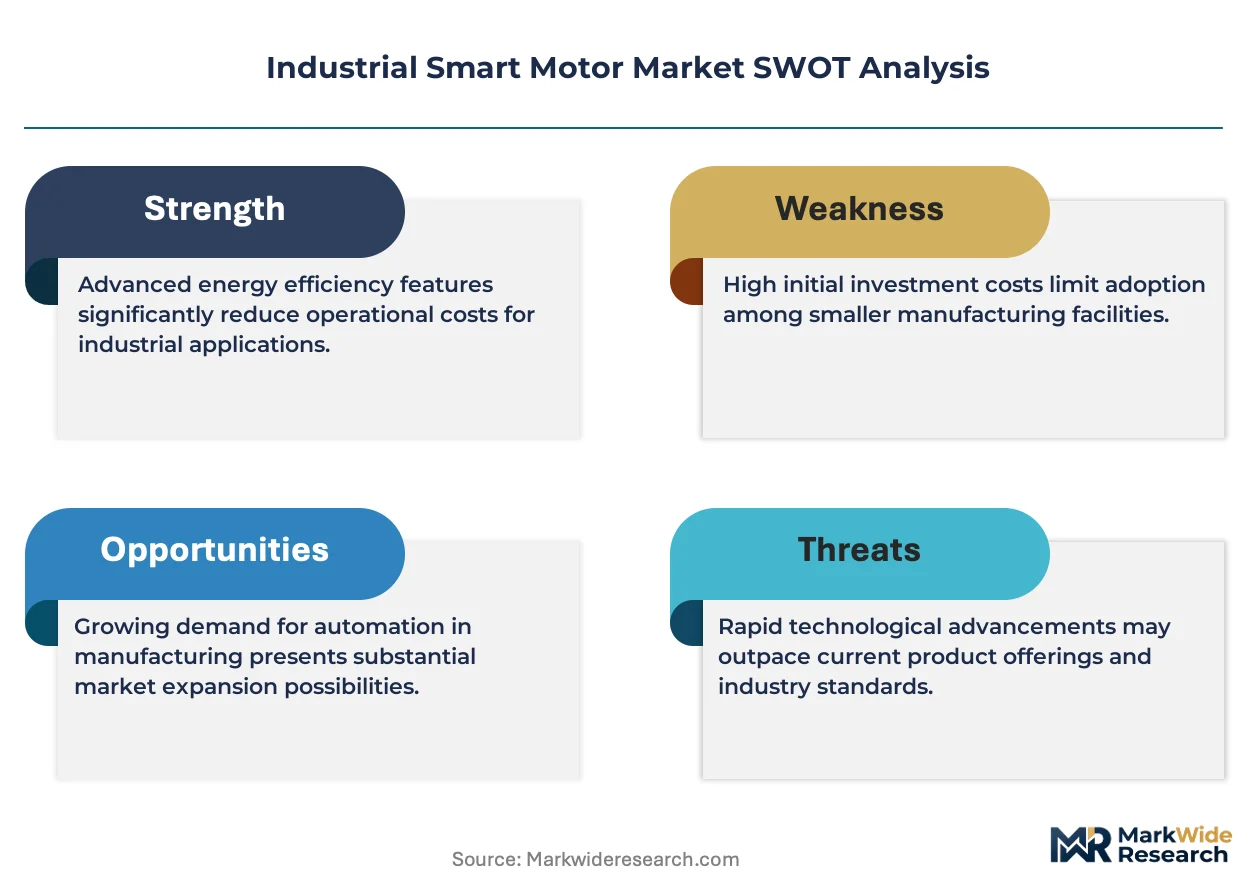
This market functions as a defensive-moat story anchored in regulatory entrenchment, where efficiency mandate compliance creates switching costs that cement incumbent positions across multi-year replacement cycles.
For Market Incumbents: Fortify aftermarket service revenue streams by unbundling predictive maintenance subscriptions from hardware sales, countering margin erosion from Chinese cost competitors. Deepen backward integration into rare earth magnet supply through offtake agreements with Vietnamese processors, securing material access as neodymium price volatility intensifies. For New Entrants and Emerging Players: Differentiate on edge-to-cloud analytics architectures that fuse onboard motor diagnostics with centralized energy management platforms, targeting India's PLI-subsidized automotive corridors in Pune and Chennai where greenfield specification demand lacks entrenched vendor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because efficiency mandate tightening accelerates replacement demand while raising fixed compliance costs that squeeze sub-scale competitors. Acquisition targets should display dual certification capability across IE4 efficiency and IEC 62443 cybersecurity standards. The signal to watch is harmonization progress between EU Ecodesign Directive tiers and North American FERC efficiency standards, which would consolidate qualification burdens and amplify scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Ofhtake agreements with Vietnamese processors insulate permanent magnet motor production from dysprosium price volatility. |
| Edge-to-Cloud Platform Development | Onboard analytics fused with centralized energy management create recurring service revenue pools for system integrators. |
| Dual Certification Investment | Simultaneous IE4 efficiency and IEC 62443 cybersecurity qualification raises barriers against sub-scale competitors. |
| Geographic Expansion into India PLI Corridors | Pune and Chennai automotive clusters offer greenfield specification demand without entrenched vendor relationships. |
| Predictive Maintenance Subscription Unbundling | Separating software monetization from hardware procurement fragments traditional bundled revenue models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and motor efficiency certification databases. Primary interviews engaged plant engineers at German automotive OEMs, aftermarket service heads at North American industrial distributors, procurement teams at Chinese steel rolling mills, and technical directors at Japanese robotics manufacturers. Secondary validation drew from FERC efficiency standard dockets, EU Ecodesign Directive implementation guidance, MIIT GB 18613 compliance notices, and SEC 10-K disclosures from listed motor manufacturers. Bottom-up unit shipment estimates triangulated against top-down industrial automation investment flows.
Segmentation dimensions modeled span product architecture, connectivity protocol, end-use sector, and application duty cycle across the projection horizon. CAGRs derive from regression analysis against industrial production indices, energy price trajectories, and regulatory compliance deadline clustering. Forecast inputs incorporate rare earth magnet price volatility bands and semiconductor foundry capacity utilization assumptions specific to variable frequency drive controller supply.
Material uncertainties — rare earth supply disruption, Taiwan foundry capacity constraints, and IEC 62443 harmonization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and industrial capital expenditure recovery patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Torque Motor Market
Electric Motor
Car Charger Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Voice Coil Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
Smart E-Drive Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Global Motor Soft Starter Market