
 Global Vehicle Starter Motor Market | 2026-2036
Global Vehicle Starter Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vehicle Starter Motor Market Outlook
ISO 16750-2 environmental testing for electrical loads is unwinding competitive access for starter motor suppliers lacking certified validation labs. Robert Bosch GmbH leverages captive testing infrastructure across Germany and China to sustain OEM qualification timelines. Denso Corporation anchors its position through brushless motor R&D intensity in Japan. Valeo Group competes on integrated starter-generator architectures that merge cranking and generation functions.
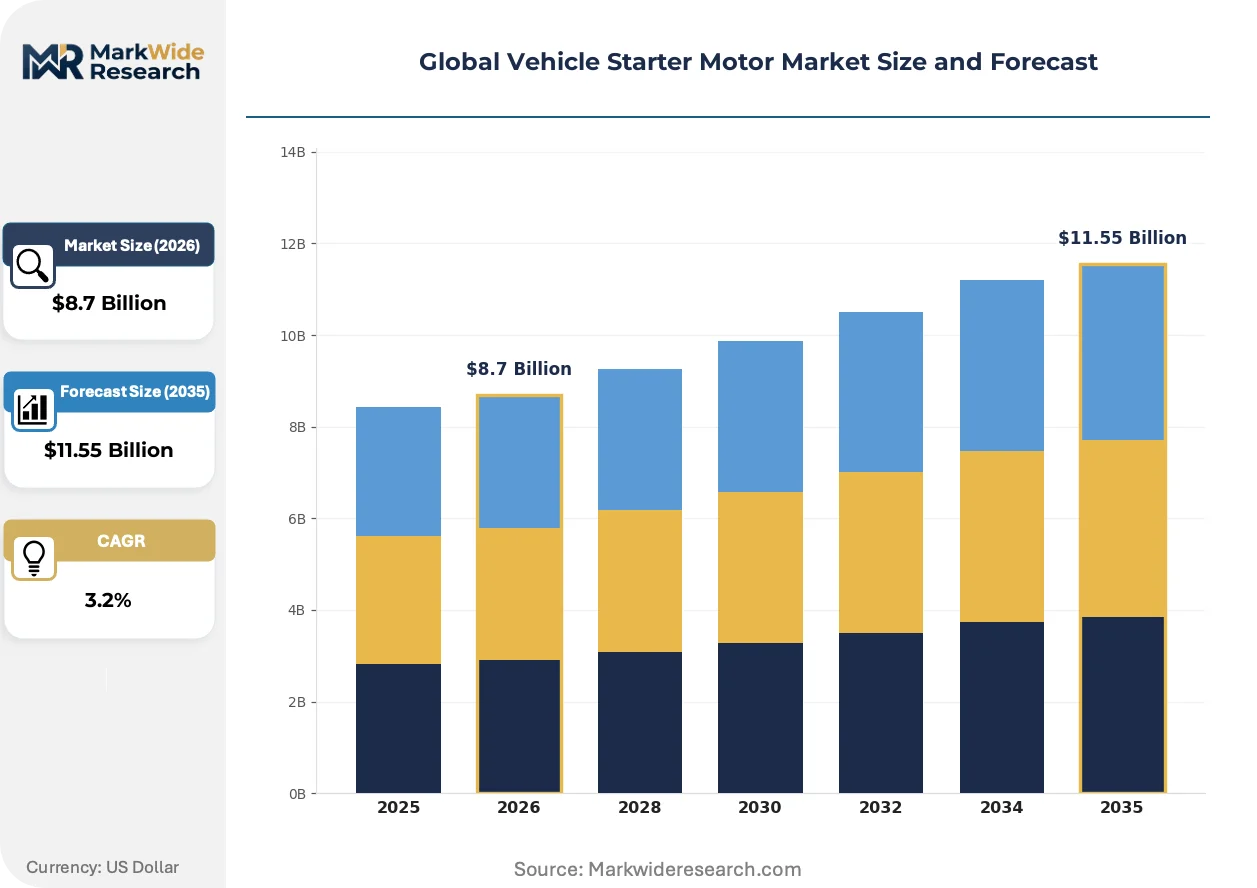
A vehicle starter motor is an electromechanical device converting battery DC power into rotational mechanical energy via pinion engagement with the engine flywheel, typically delivering 0.8 to 2.5 kW output depending on engine displacement and cold-cranking amp requirements. Its primary purpose is initiating internal combustion engine operation before sustained ignition cycles commence. Electric product types now command the dominant value share as 12V and 48V architectures replace legacy recoil systems in passenger and commercial applications. Permanent magnet technology leads volume production for OEM channels while brushless designs capture margin pools in premium modular installations. Aftermarket providers represent a mature demand channel with predictable replacement cycles, whereas integrated installation formats are expanding fastest in new vehicle platforms.
FCC electromagnetic compatibility standards in the United States, REACH substance restrictions across Europe, and China's GB/T compliance framework collectively shape material selection, shielding design, and market access protocols for starter motor manufacturers. EPA fuel economy benchmarks indirectly drive demand for lighter, more efficient cranking systems that reduce parasitic engine loads. Stakeholders must monitor 48V mild-hybrid architecture proliferation and corresponding starter-generator fusion trends that could redefine product boundaries and supplier qualification requirements.
Market Dynamics
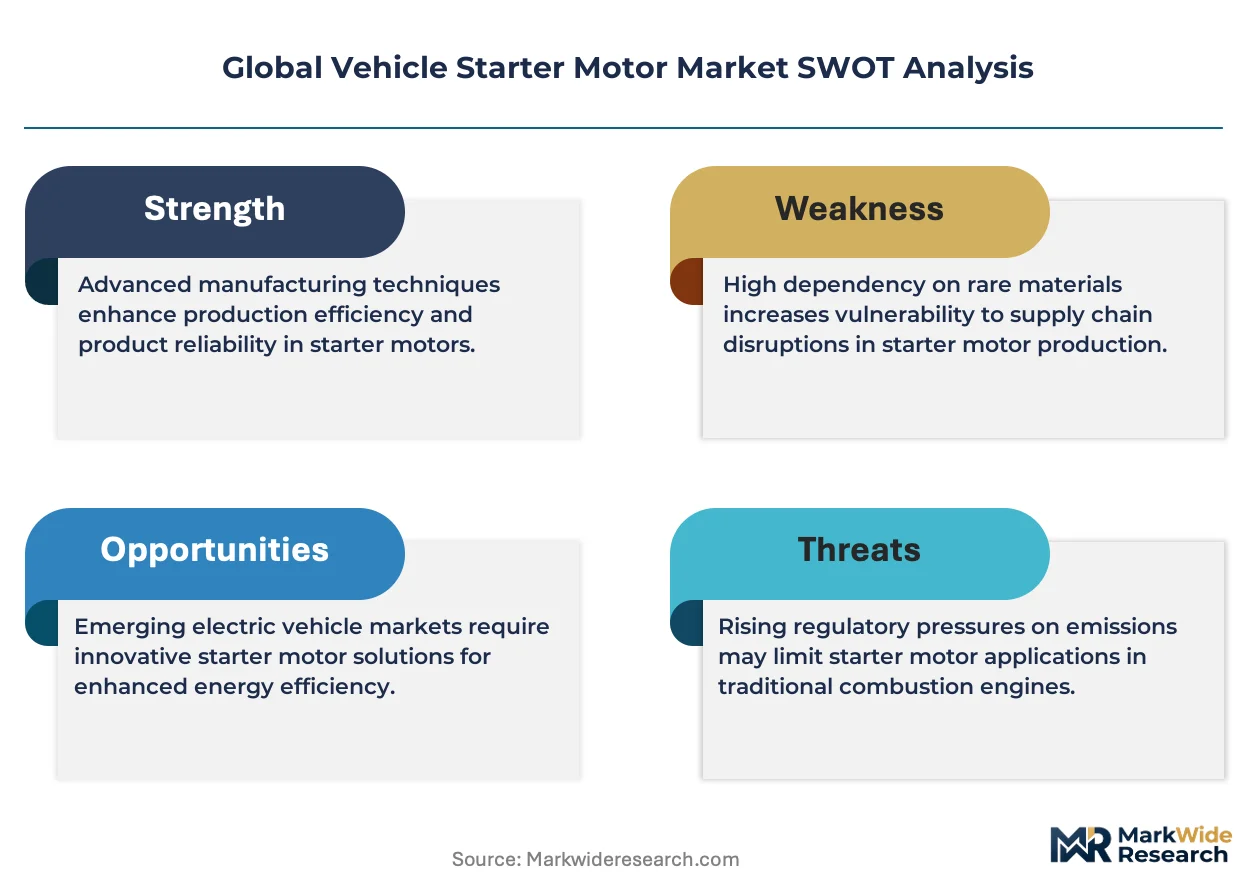
48V mild-hybrid architectures are compressing the boundary between standalone starter motors and integrated starter-generator systems, forcing suppliers to recalibrate R&D roadmaps and qualification protocols across passenger and commercial vehicle platforms.
Growth Catalysts
- China's NEV dual-carbon mandate:The Ministry of Ecology and Environment's emissions framework accelerates factory adoption of high-torque electric starter units in domestic light commercial assembly lines.
- Brushless permanent magnet technology:Magnetic material efficiency gains enable 15-20% torque density improvements over wound-field designs, penetrating premium modular installations in German and Japanese OEM channels.
- Brazilian fleet replacement cycles:Commercial vehicle operators in São Paulo and Minas Gerais states are shortening preventive maintenance intervals for starter motor swaps amid expanding logistics contract volumes.
Market Restraints
- Copper and rare-earth price volatility:Neodymium and copper coil material costs swing 20-35% quarterly, compressing margin buffers for mid-tier suppliers without long-term offtake agreements.
- ISO 16750-2 validation concentration:Certified environmental testing infrastructure clusters in Germany, China, and Japan, locking out emerging-market competitors from OEM qualification pipelines.
- Integrated starter-generator substitution:Belt-driven and crankshaft-mounted ISG systems eliminate discrete starter motor SKUs in 48V architectures above 2.0L displacement segments.
Strategic Opportunities
- India's light commercial vehicle assembly scaling:Domestic OEM capacity expansion in Pune and Chennai creates demand for localized starter motor sourcing with BIS certification pathways.
- REACH substance restriction compliance services:European aftermarket distributors require documentation support for lead-free brush compositions and recycled copper traceability, opening service-layer revenue.
- Wireless diagnostic integration:Bluetooth-enabled starter motor condition monitoring converges with telematics platforms, enabling predictive replacement scheduling for US and European fleet managers.
Industry Challenges
- ISO 16750-2 certification timeline compression:OEM qualification windows have narrowed from 18 months to 10 months, straining validation lab capacity and engineering headcount at tier-2 suppliers.
- Legacy 12V electrical architecture integration:Dual-voltage platform engineering requires backward-compatible starter motor designs that function across 12V and 48V battery systems without component duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vehicle Starter Motor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
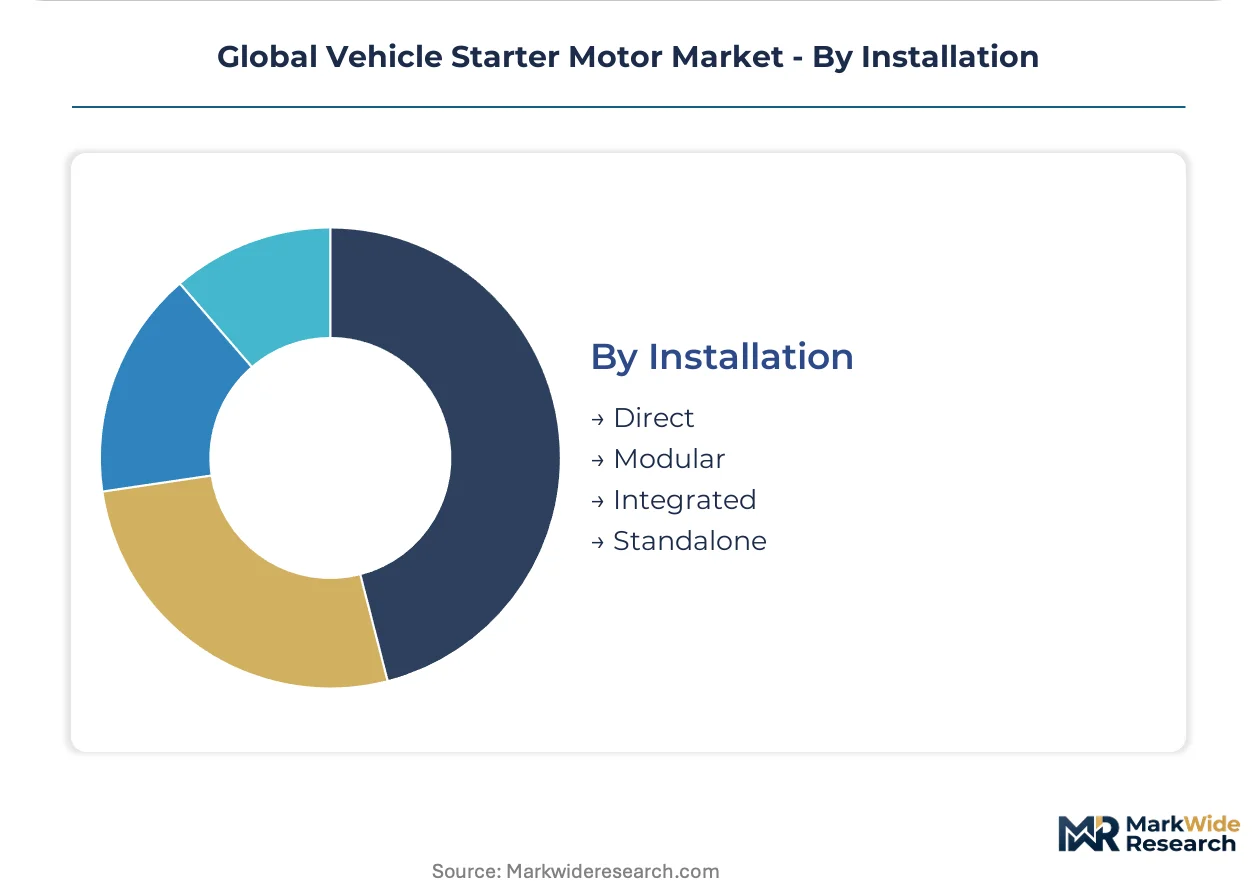
| Segmentation | Product Type: Recoil, Automatic, Manual, Electric End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Technology: Brushless, Induction, Permanent Magnet, Solenoid Installation: Direct, Modular, Integrated, Standalone |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Valeo Group, Mitsubishi Electric Corporation, Hitachi Astemo Ltd., Mitsuba Corp, SEG Automotive, Prestolite Electric, MAHLE Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vehicle Starter Motor Market Strategic Shifts
Electrification mandates and thermal efficiency targets are rewriting component specifications faster than supplier qualification cycles can absorb, creating a technology adoption gap between premium modular platforms and cost-optimized legacy installations.
Permanent magnet brushless motor designs are bifurcating the product landscape. These units eliminate carbon brush wear and electromagnetic interference through electronic commutation, penetrating German and Japanese premium OEM channels while wound-field architectures retain volume share in price-sensitive commercial segments. The technology split is compressing R&D budgets at multi-line suppliers forced to maintain parallel development tracks.
REACH substance restrictions across Europe are reshaping material procurement protocols. ECHA's candidate list expansions for lead and cadmium compounds now cover brush compositions and housing alloys, forcing reformulation of long-validated component specifications. Aftermarket suppliers serving EU-27 markets face the steepest compliance cost escalation as traceability documentation requirements extend through tier-3 raw material sources.
Fleet telematics penetration is compressing replacement cycle predictability. Commercial vehicle operators in North America and Western Europe now demand starter motor condition data through CAN bus integration, unbundling traditional preventive maintenance schedules from component supplier relationships. This behavioral shift favors suppliers with embedded sensor capabilities and API-accessible diagnostic platforms over catalog-based aftermarket distributors.
Global Vehicle Starter Motor Market Segmentation
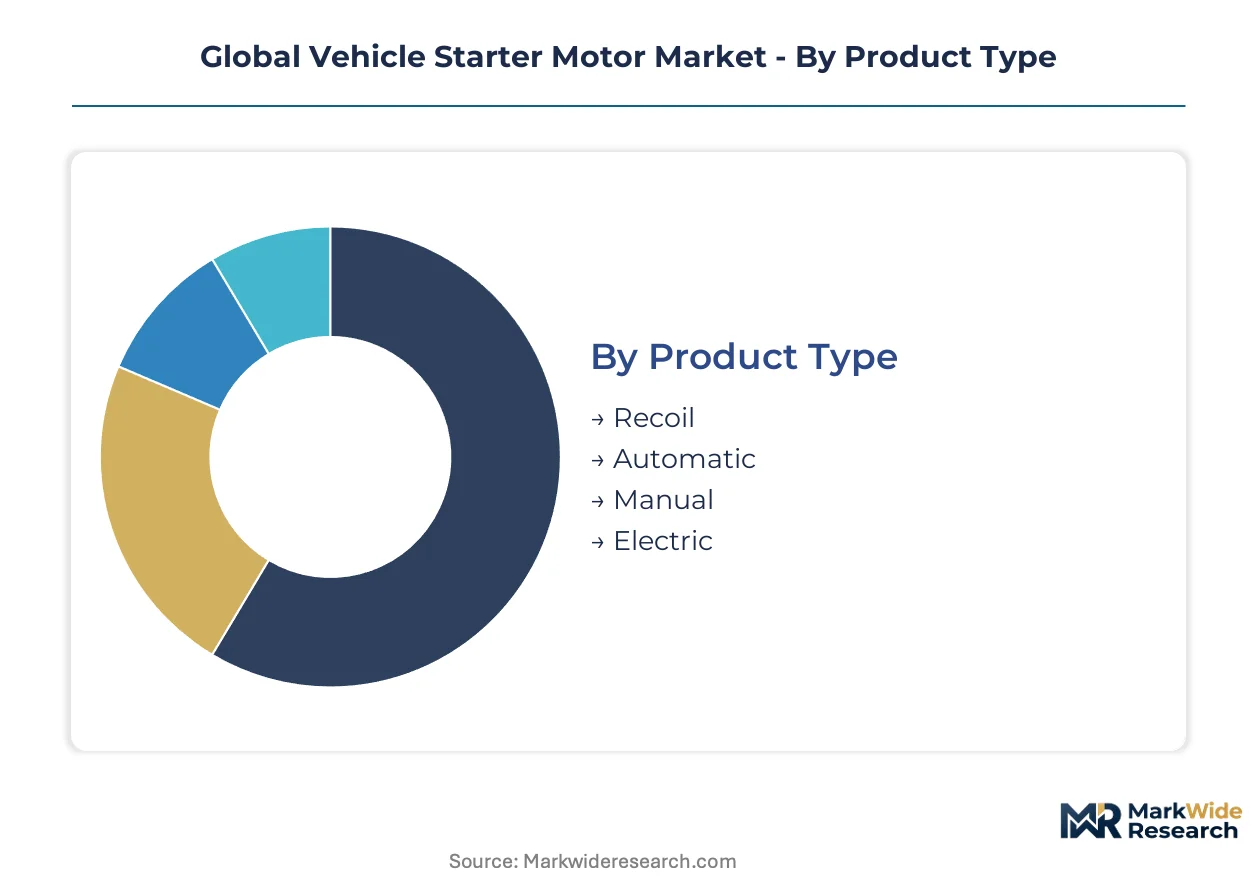
Starter motor procurement patterns diverge sharply across product architectures and customer channels, with electrification mandates and qualification protocols reshaping how suppliers allocate R&D and manufacturing capacity. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures intensify.
Product Type:
EPA fuel economy benchmarks and China's dual-carbon mandate create divergent compliance burdens across starter motor architectures, with electric formats facing electromagnetic compatibility testing while legacy mechanical systems confront material restriction protocols.
- Electric:DC motor designs converting battery power through pinion-flywheel engagement dominate new vehicle platforms, with China's NEV mandate accelerating factory adoption in domestic light commercial assembly lines. Demand concentrates in 12V and 48V architectures as OEMs phase out mechanical alternatives.
- Automatic:Pre-engaged drive mechanisms with integrated solenoid control capture premium modular installations in German and Japanese OEM channels, where brushless commutation and reduced electromagnetic interference justify unit cost premiums over conventional designs.
- Recoil:Pull-cord mechanical systems retain niche presence in small-engine agricultural equipment and emerging-market two-wheeler segments.
- Manual:Hand-crank legacy formats persist in vintage vehicle restoration and extreme-cost-optimized commercial applications.
Established volume favors Electric; emerging adoption favors Automatic.
End User:
Customer channel economics split between qualification-intensive OEM relationships and predictable aftermarket replacement cycles, with fleet telematics penetration now unbundling traditional preventive maintenance schedules.
- OEMs:Original equipment manufacturers impose ISO 16750-2 environmental validation requirements that compress qualification timelines from 18 to 10 months, favoring suppliers with captive testing infrastructure in Germany and China.
- Aftermarket Providers:Distributors serving replacement demand face REACH documentation burdens for lead-free brush compositions and recycled copper traceability, with European aftermarket channels requiring tier-3 material source verification.
- Vehicle Assemblers:Domestic capacity expansion in India's Pune and Chennai corridors creates localized sourcing requirements with BIS certification pathways.
- Repair Shops:Independent service channels in Brazil's São Paulo and Minas Gerais states are shortening preventive maintenance intervals amid expanding logistics contract volumes.
OEMs command margin concentration; aftermarket providers deliver cash flow stability.
Technology:
Magnetic material efficiency and electronic commutation architectures are bifurcating R&D investment, forcing multi-line suppliers to maintain parallel development tracks across premium and cost-optimized segments.
- Brushless:Electronic commutation eliminates carbon brush wear and electromagnetic interference, penetrating German and Japanese premium OEM channels where 15-20% torque density improvements over wound-field designs justify engineering premiums.
- Permanent Magnet:Neodymium-based rotor configurations lead volume production for OEM channels, though rare-earth price volatility compresses margin buffers for suppliers without long-term offtake agreements.
- Induction:Wound-field architectures retain commercial vehicle share where purchase price sensitivity outweighs efficiency gains.
- Solenoid:Electromechanical switching mechanisms integrate with pre-engaged drive systems in automatic starter formats.
Permanent Magnet anchors volume share; Brushless climbs the fastest in value terms.
Installation:
Physical integration depth determines supplier qualification complexity, with 48V mild-hybrid architectures compressing the boundary between discrete components and fused starter-generator systems.
- Integrated:Belt-driven and crankshaft-mounted configurations merging cranking and generation functions eliminate discrete starter motor SKUs in 48V architectures above 2.0L displacement segments, forcing suppliers to recalibrate R&D roadmaps.
- Modular:Self-contained units with standardized mounting interfaces serve premium vehicle platforms where serviceability and component upgrade paths preserve supplier relationships.
- Direct:Engine-block-mounted conventional formats persist in legacy 12V architectures and cost-optimized commercial applications.
- Standalone:Discrete component configurations face substitution pressure as OEMs consolidate electrical machine functions.
Direct installation retains fleet penetration; Integrated gains share fastest in new platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NEV dual-carbon mandate and India's domestic assembly scaling are redirecting procurement flows across Asia-Pacific, while EPA benchmarks and REACH restrictions reshape supplier qualification requirements in Western markets.
China
Domestic light commercial vehicle assembly lines in Shanghai and Chongqing are accelerating factory adoption of high-torque electric starter units. The Ministry of Ecology and Environment's emissions framework enforces GB/T compliance for electromagnetic compatibility certification. Tier-1 suppliers cluster in the Yangtze River Delta to serve localized OEM sourcing requirements.
Germany
Premium modular installations in Stuttgart and Munich drive brushless motor R&D intensity for torque density improvements. KBA type-approval protocols and ISO 16750-2 environmental validation requirements compress qualification timelines. Captive testing infrastructure in Baden-Württemberg sustains OEM partnership pipelines for tier-1 suppliers.
United States
Fleet telematics penetration among commercial vehicle operators shortens preventive maintenance intervals for starter motor replacements. FCC electromagnetic compatibility standards govern shielding design and market access protocols. Automotive suppliers concentrate in Michigan and Ohio to serve Detroit Three procurement channels.
Brazil
Expanding logistics contract volumes in São Paulo and Minas Gerais states are compressing fleet replacement cycles. ANVISA substance regulations intersect with Mercosur automotive standards for material traceability. Aftermarket distributors in the Southeast region face documentation burdens for lead-free brush compositions.
India
Domestic OEM capacity expansion in Pune and Chennai corridors creates demand for localized starter motor sourcing. BIS certification pathways govern electrical safety and performance validation for component suppliers. Tier-2 manufacturers in Tamil Nadu are upgrading testing capabilities to meet compressed qualification windows.
Global Vehicle Starter Motor Market Competitive Environment
Listed leaders compete with private specialists across capital access and R&D scale, creating a tiered structure where consolidated tier-1 players anchor OEM relationships while mid-cap fabricators serve aftermarket channels. The vendor base stratifies around three archetypes: integrated automotive suppliers with captive electrical machine divisions, standalone starter motor specialists with regional manufacturing footprints, and diversified industrial motor manufacturers extending into vehicle applications. Dominant competitive moves include backward integration into rare-earth magnet supply chains and strategic partnerships for 48V mild-hybrid system co-development.
Within the integrated automotive tier, Robert Bosch GmbH and Denso Corporation exemplify scale-driven positioning through German and Japanese headquarters structures. Valeo Group occupies a distinct archetype as a French-listed supplier with S.A. corporate form. These three entities represent the premium-tier vector where captive testing infrastructure and OEM qualification timelines converge.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo Group |
| Mitsubishi Electric Corporation |
| Hitachi Astemo Ltd. |
| Mitsuba Corp |
| SEG Automotive |
| Prestolite Electric |
| MAHLE Group |
| Others |
Value Chain & Pricing Dynamics
Brushless permanent magnet motor adoption displacing wound-field architectures simultaneously redraws procurement geography toward rare-earth magnet suppliers and compresses margin buffers for tier-2 manufacturers lacking long-term neodymium offtake agreements. This substitution dynamic concentrates pricing power with vertically integrated tier-1 suppliers while fragmenting cost structures across mid-tier fabricators.
Pricing Analysis
Certification level creates the primary spread across starter motor tiers, with ISO 16750-2 validation anchoring premium pricing for OEM-qualified suppliers while aftermarket providers compete on REACH documentation bundled with unit sales. Three-tier pricing structure separates captive-tested premium units from standard BIS-certified products and economy-grade unbranded alternatives. Cost compression in the mid-tier intensifies because copper and rare-earth price volatility erodes fixed-margin contracts. Fleet operators demonstrate highest price sensitivity through telematics-enabled predictive maintenance, whereas premium German and Japanese OEMs absorb certification premiums for torque density gains.
Supply Chain Analysis
China and Japan anchor rare-earth magnet processing and brushless motor manufacturing, with Germany retaining captive testing infrastructure for OEM validation. Neodymium, copper coil stock, and electronic commutation controllers constitute critical input dependencies. Single-source vulnerability concentrates in Yangtze River Delta magnet processors subject to export quota fluctuations. Distribution runs through tier-1 supplier direct OEM contracts and aftermarket distributor networks serving independent repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless diagnostic integration and REACH compliance documentation services are expanding faster than hardware unit growth, creating recurring-revenue layers that decouple supplier economics from replacement cycle volatility.
For Market Incumbents: Consolidate captive testing infrastructure in Germany and China to compress ISO 16750-2 qualification timelines from 18 months toward 10-month windows, defending against emerging-market competitors building BIS-certified capacity in India. Deepen backward integration into rare-earth magnet supply chains to buffer neodymium price volatility compressing mid-tier margins. For New Entrants and Emerging Players: Predictive maintenance platform gaps where incumbents under-serve fleet telematics integration create white-space targets for Bluetooth-enabled condition monitoring bundled with starter motor hardware. India's Pune and Chennai assembly corridors offer the most penetrable geography for localized BIS-certified sourcing partnerships with domestic OEM capacity expansion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed tier-2 automotive component specialists lacking 48V mild-hybrid R&D roadmaps. Long-term viability over a 5-10 year horizon favors targets with integrated starter-generator co-development partnerships. The signal to watch is belt-driven ISG adoption rates above 2.0L displacement segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Neodymium offtake agreements insulate tier-1 suppliers from quarterly price swings. |
| ISO 16750-2 Captive Testing Infrastructure Expansion | Baden-Württemberg and Yangtze River Delta labs sustain compressed OEM qualification pipelines. |
| 48V Mild-Hybrid System Co-Development Partnership | Belt-driven ISG architectures merge cranking and generation functions for European OEM platforms. |
| Wireless Diagnostic Platform Integration | Bluetooth-enabled condition monitoring converges with fleet telematics for predictive replacement scheduling. |
| REACH Compliance Documentation Service Layer | European aftermarket distributors require tier-3 material traceability for lead-free brush compositions. |
Study Parameters
A standing panel of OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributor operations managers, and fleet maintenance supervisors provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs trade records for copper and rare-earth flows, and SEC filings from listed automotive suppliers. Bottom-up unit economics triangulated against top-down OEM procurement spend estimates across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including regional vehicle assembly forecasts and electrification penetration trajectories. Segmentation modeling spanned product architecture, end-user channel, magnetic technology type, and physical installation format. CAGRs were derived from fitted growth curves applied to annual unit demand and average selling price trajectories, with 48V mild-hybrid adoption rates and fleet telematics penetration serving as key sensitivity inputs.
Underlying assumptions cover stable rare-earth supply quotas, continued ISO 16750-2 validation concentration, and linear electrification mandates, with deviation risk concentrated in neodymium export restrictions and accelerated ISG substitution timelines. Recalibration cycles align with material shifts in dual-carbon policy enforcement and 48V architecture proliferation across passenger vehicle platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
High Speed Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Implant Motors Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Traction Motors Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Motorcycle Battery Market
Electric Motor
US Solar E-Bike Market