
 Torque Motor Market | 2026-2036
Torque Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Motor Market Outlook
Semiconductor equipment OEMs is rotating demand away from traditional servo-motor configurations toward frameless torque motors for direct-drive rotary tables. Kollmorgen Corporation leverages its frameless motor architecture to anchor the wafer-handling segment with high pole-count designs. Siemens AG competes through integrated motion control platforms that bundle torque motors with digital twin software. Moog Inc specializes in high-torque-density solutions for defense and aerospace test rigs, sustaining long-term program relationships.
A torque motor is a specialized permanent-magnet synchronous motor designed to deliver high torque at low speeds without mechanical transmission elements such as gearboxes or belts, typically achieving torque constants exceeding 100 Nm/A and direct-drive positioning accuracy below 1 arc-second. Its primary purpose is to eliminate mechanical backlash and compliance in precision motion systems for semiconductor lithography, robotic joints, and telescope azimuth drives. Brushless torque motors lead the product type landscape due to their maintenance-free operation and thermal efficiency in continuous-duty cycles, while direct drive technology captures the fastest growth trajectory as OEMs eliminate mechanical transmission layers to improve mean time between failures. AC torque motors retain mature positions in textile machinery and heavy industrial indexing where cost sensitivity outweighs precision requirements.
The US Department of Energy motor efficiency standards and EPA industrial emissions guidelines shape product roadmaps by mandating minimum efficiency classes and driving electrification of formerly hydraulic systems. Japan's METI enforces JIS C 4034 efficiency benchmarks that filter import eligibility and push manufacturers toward premium magnet grades. China's GB 18613 motor efficiency standards and MIIT industrial upgrading directives accelerate domestic torque motor adoption while raising technical barriers for non-compliant suppliers. Stakeholders must monitor rare earth magnet supply security and regional efficiency tier convergence to align R&D portfolios with diverging compliance timelines.
Market Dynamics
Semiconductor lithography OEMs are eliminating mechanical transmission layers entirely, replacing servo-motor-plus-gearbox architectures with direct-drive frameless torque motors to achieve sub-arc-second positioning stability for EUV wafer stages.
Growth Catalysts
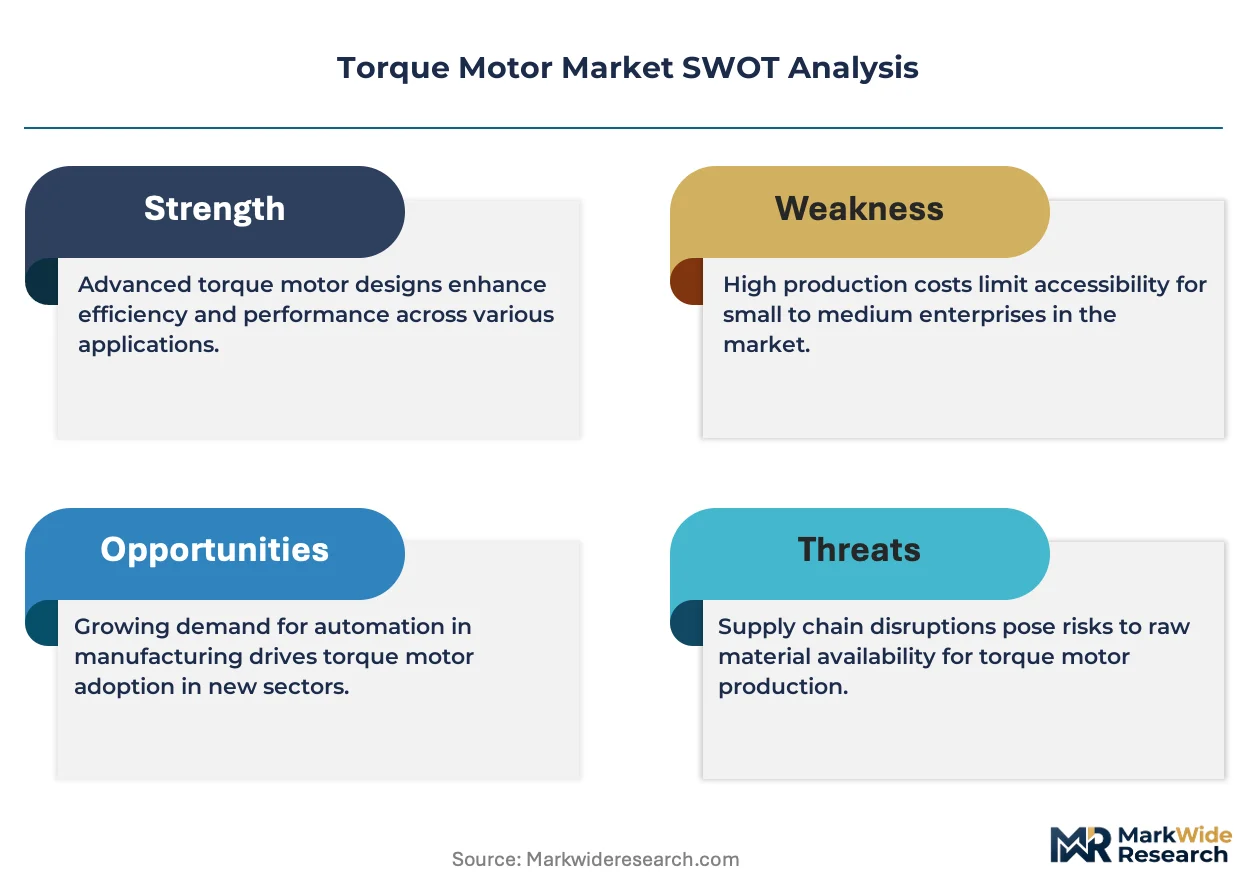
- China's MIIT efficiency mandates:GB 18613 motor efficiency standards are accelerating domestic torque motor adoption while raising technical barriers for non-compliant suppliers, forcing upgrades across industrial automation.
- Wafer-handling robotics:Semiconductor fabrication equipment manufacturers are rotating demand toward frameless torque motors for direct-drive rotary tables, eliminating backlash in vacuum-compatible positioning stages.
- Japan's METI industrial electrification roadmap:JIS C 4034 efficiency benchmarks filter import eligibility and push manufacturers toward premium rare-earth magnet grades, tightening performance standards.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in China's Inner Mongolia and Jiangxi provinces, creating geopolitical exposure for magnet-grade torque motor producers.
- High-precision winding equipment capex:Distributed winding machines for high pole-count designs require capital outlays exceeding conventional motor production lines by factors of three to five.
- AC torque motor substitution in cost-sensitive indexing:Textile machinery and heavy industrial applications retain mature AC torque motor positions where precision requirements yield to total cost of ownership.
Strategic Opportunities
- Defense and aerospace test rig electrification:High-torque-density solutions for turret simulators and antenna positioning systems are displacing hydraulic actuation in long-term program relationships.
- Telescope azimuth drive modernization:Direct-drive torque motors eliminate gear train maintenance in astronomical observatories, opening replacement cycles across Chile's Atacama and Hawaii's Mauna Kea facilities.
- Digital twin integration:Motion control platforms bundling torque motors with real-time simulation software are creating service-based revenue streams distinct from hardware margins.
Industry Challenges
- Electromagnetic compatibility certification timelines:IEC 61000-6-2 and IEC 61000-6-4 testing for industrial immunity and emissions extends product qualification cycles by six to nine months.
- Thermal management integration complexity:Frameless motor embedding requires simultaneous optimization of stator heat rejection paths and machine structure dynamics, demanding cross-functional engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Motor Market |
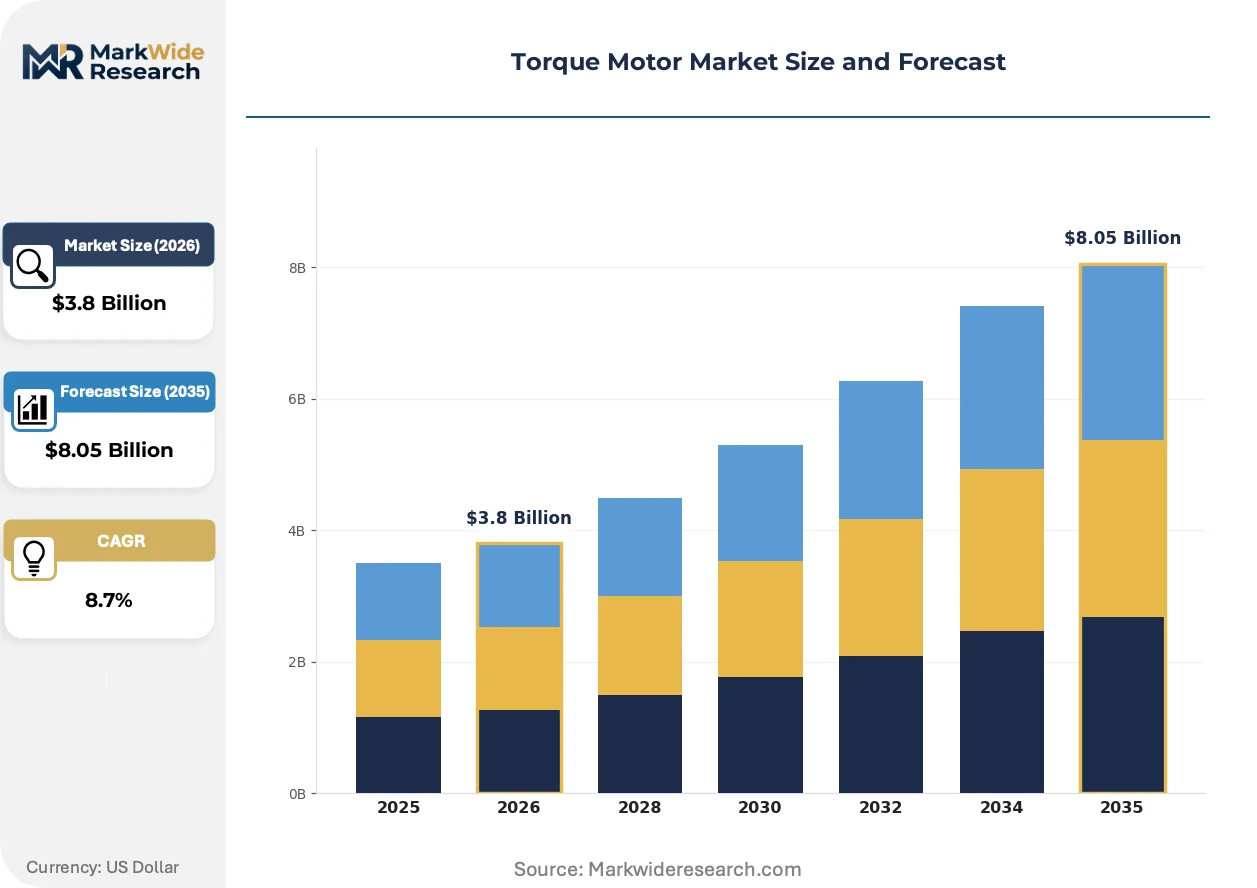
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Torque Motors, DC Torque Motors, Brushless Torque Motors, Stepper Torque Motors Application: Robotics, Industrial Automation, Aerospace, Automotive, Textile Machinery End User: Manufacturers, OEMs, Research Institutions, Maintenance Providers Technology: Direct Drive, Closed Loop Control, Open Loop Control, Digital Control |
| Companies Covered | Siemens AG, Kollmorgen Corporation, Moog Inc, ETEL motion technology, ABB Ltd, HIWIN GmbH, Tecnotion B.V., Yaskawa Electric Corporation, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Motor Market Strategic Shifts
Direct-drive architectures are compressing mechanical supply chains while regulatory efficiency tiers and buyer consolidation are reshaping competitive requirements across precision motion segments.
Halbach-array magnet configurations are displacing conventional radial magnet topologies in high-performance torque motors. Semiconductor lithography OEMs at ASML's supply base have adopted these arrangements for their superior airgap flux density and reduced magnet volume. This topology is displacing legacy ferrite-assisted designs in wafer stage applications where kilohertz bandwidth demands previously required larger magnet masses.
EPA industrial emissions guidelines and the US Department of Energy motor efficiency standards are mandating minimum NEMA Premium efficiency classes for motors above one horsepower. These rules are driving electrification of formerly hydraulic positioning systems in metal forming and injection molding. California's CARB industrial emissions framework is accelerating this transition in North American precision automation clusters.
Buyer consolidation among semiconductor capital equipment vendors is compressing supplier qualification cycles and unbundling after-sales service contracts. Equipment OEMs now demand torque motor suppliers maintain regional repair depots within four-hour flight time of major fabs. This pattern is most visible in Germany's precision automation cluster around Munich and Stuttgart, where Siemens and KUKA procurement teams have consolidated vendor panels.
Torque Motor Market Segmentation
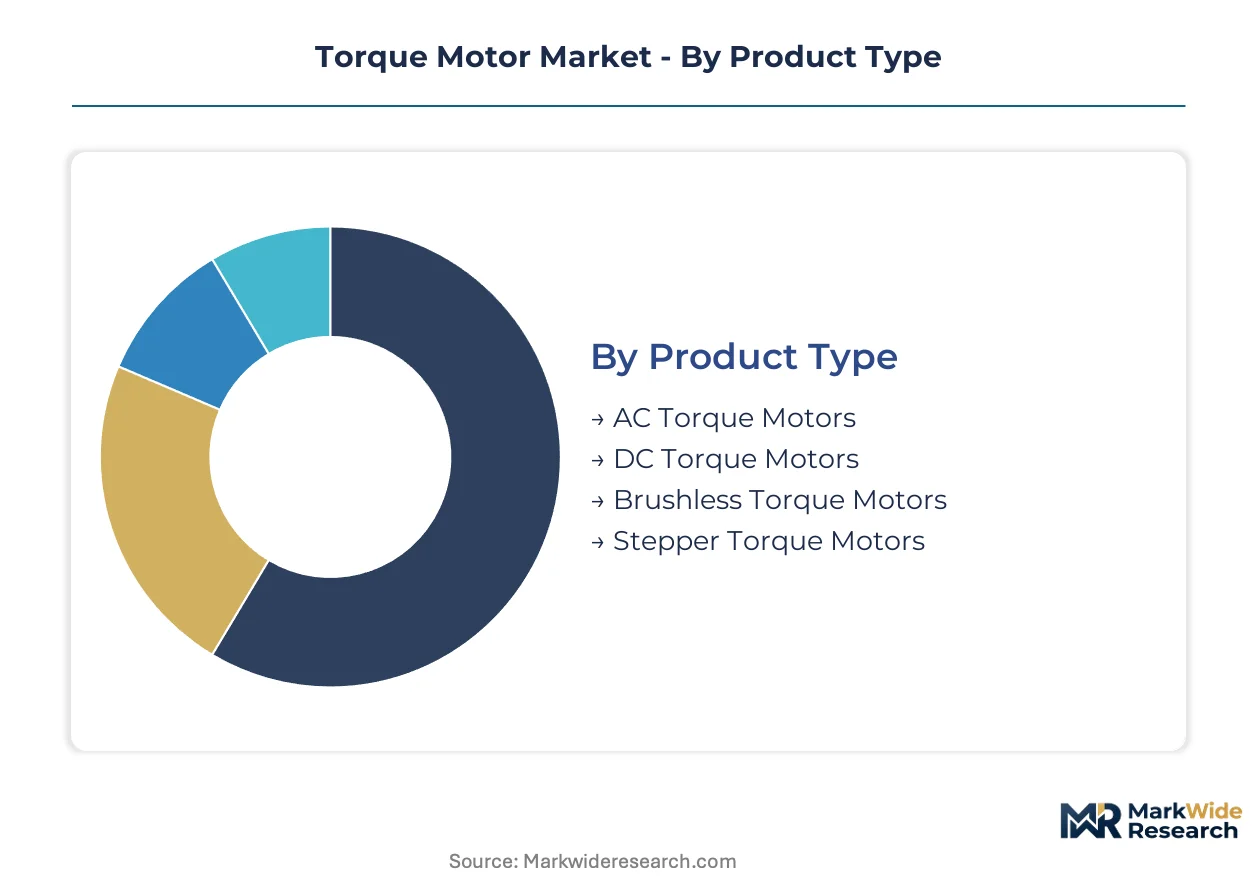
Torque motor procurement patterns diverge sharply across product architectures and control philosophies. Semiconductor capital equipment vendors, defense contractors, and precision automation OEMs each impose distinct technical specifications that fragment supplier portfolios.
Product Type:
Brushless torque motors command the widest margin pools due to maintenance-free operation in continuous-duty vacuum environments and thermal efficiency premiums.
- Brushless Torque Motors:Permanent-magnet synchronous designs eliminate brush wear and particulate generation. Wafer-handling stages at Taiwan Semiconductor Manufacturing and Samsung Electronics fabs specify these for Class 1 cleanroom compatibility.
- AC Torque Motors:Induction-based architectures dominate textile looms and heavy industrial indexing where purchase price outweighs positioning precision. India's Surat and Tiruppur textile clusters sustain volume demand despite efficiency disadvantages.
- DC Torque Motors:Brushed commutator designs persist in legacy machine tool retrofits and cost-constrained motion systems.
- Stepper Torque Motors:Hybrid stepper variants serve open-loop positioning in packaging machinery and laboratory automation.
The dominant share belongs to brushless torque motors, while AC torque motors is closing the gap fastest in emerging industrial electrification programs.
Application:
Volume concentrates in robotics and industrial automation, yet aerospace test rigs generate the highest unit margins through program longevity and qualification barriers.
- Robotics:Collaborative robot joints and SCARA arms demand frameless direct-drive torque motors for zero-backlash motion. Germany's KUKA and Japan's FANUC specify these for cobot wrist axes.
- Aerospace:Flight simulator motion bases and antenna positioning systems require high-torque-density solutions. Moog Inc and Parker Hannifin hold long-term supply relationships with US defense primes.
- Industrial Automation:Semiconductor lithography stages and machine tool rotary tables drive precision requirements. ASML's EUV wafer positioning systems anchor demand here.
- Automotive:Electric power steering test benches and battery assembly lines adopt torque motors for repeatable torque profiling.
- Textile Machinery:Warping and sizing equipment in Turkey's Bursa and China's Keqiao retain mature AC torque motor installations.
Robotics captures the steepest expansion trajectory as collaborative automation penetrates small-batch manufacturing.
End User:
OEM procurement teams extract the steepest price concessions through volume commitments and panel consolidation, while research institutions pay premiums for customization flexibility.
- OEMs:Semiconductor capital equipment vendors consolidate supplier panels and mandate regional repair depot proximity. Siemens and ASML procurement teams enforce four-hour response time clauses.
- Manufacturers:Tier-1 automotive and industrial automation producers specify torque motors for in-house motion system integration.
- Research Institutions:CERN, NASA JPL, and Max Planck Institute observatories commission bespoke direct-drive solutions for telescope azimuth modernization.
- Maintenance Providers:Aftermarket service contracts for legacy machine tools and defense platforms sustain winding refurbishment demand.
OEMs dominate procurement volume, though research institutions is expanding fastest as astronomical observatory replacement cycles accelerate.
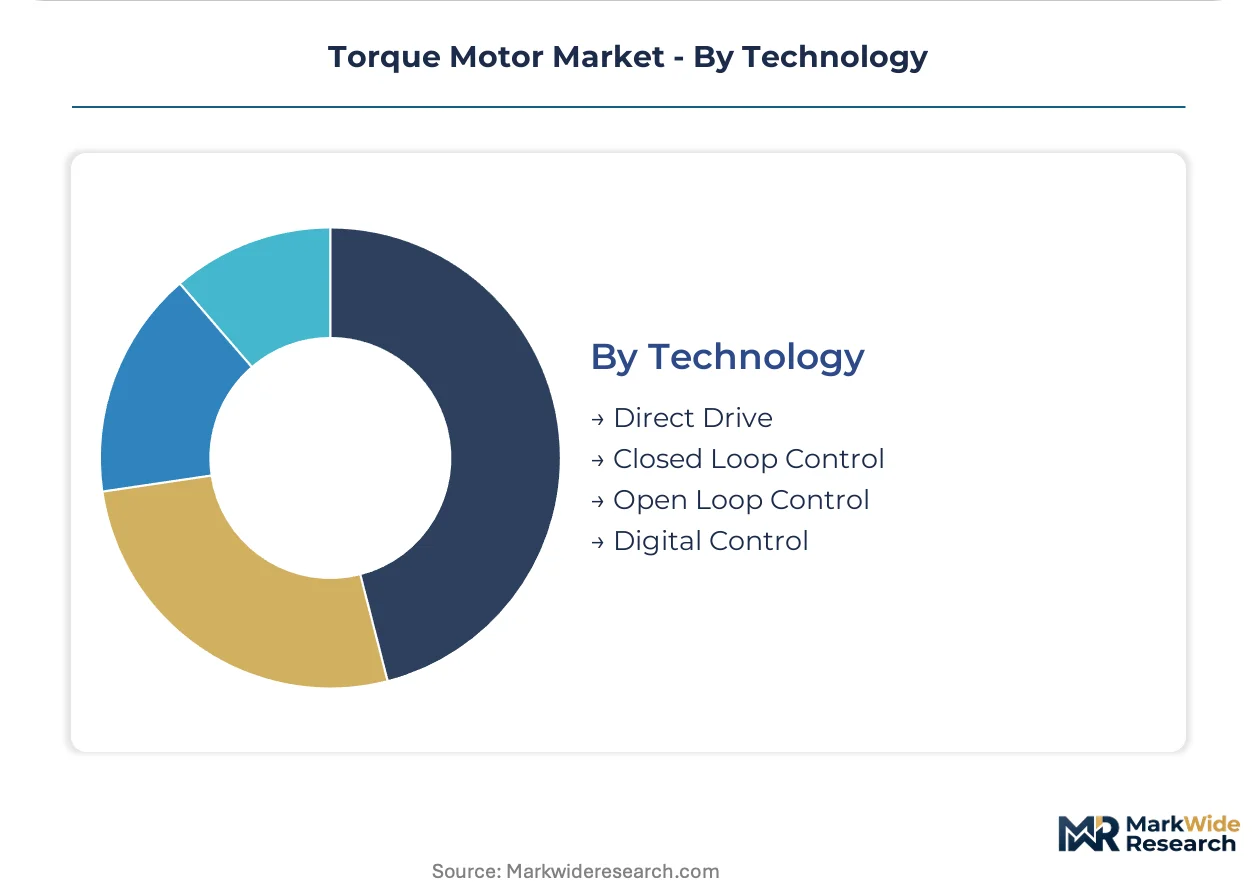
Technology:
Control architecture selection determines system integration complexity and aftermarket service attach rates.
- Direct Drive:Frameless motor embedding eliminates mechanical transmission entirely. Semiconductor lithography OEMs specify these for sub-arc-second positioning stability.
- Closed Loop Control:Resolver and encoder feedback architectures dominate precision automation where drift tolerance approaches zero.
- Digital Control:EtherCAT and PROFINET interface integration enables real-time synchronization with PLC environments.
- Open Loop Control:Stepper-based positioning persists in cost-sensitive applications where absolute accuracy is secondary.
Direct drive technology holds the dominant position, while closed loop control is gaining share fastest as safety-critical applications mandate feedback redundancy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German torque motor exports flow primarily to semiconductor fabrication facilities in Taiwan and South Korea, while Chinese manufacturers supply cost-optimized variants to India's textile automation sector.
United States
Defense aerospace test rigs and telescope observatory modernization drive demand for high-torque-density solutions. The Department of Energy motor efficiency standards mandate NEMA Premium classifications for industrial applications above one horsepower. Precision automation clusters in Greater Boston and California's Bay Area concentrate procurement for semiconductor capital equipment.
Germany
Industrial robotics OEMs and machine tool builders specify frameless direct-drive architectures for zero-backlash motion systems. The KBA and federal efficiency frameworks enforce minimum performance tiers for factory automation components. Munich and Stuttgart anchor Europe's densest precision automation supplier ecosystem, with Siemens and KUKA procurement teams consolidating vendor panels.
China
Domestic semiconductor fabrication expansion and industrial electrification programs accelerate torque motor adoption across wafer-handling stages. MIIT's GB 18613 motor efficiency standards and industrial upgrading directives raise technical barriers for import eligibility. The Yangtze River Delta and Pearl River Delta concentrate both manufacturing capacity and end-user demand from SMIC and Hua Hong Semiconductor fabs.
Japan
Collaborative robot joint manufacturers and precision automation OEMs drive specifications for maintenance-free brushless designs. METI's JIS C 4034 efficiency benchmarks filter import eligibility and push manufacturers toward premium rare-earth magnet grades. The Kanto and Chubu regions host FANUC and Yaskawa production facilities with integrated torque motor supply chains.
South Korea
Memory and logic semiconductor capital equipment vendors specify vacuum-compatible direct-drive solutions for EUV wafer positioning. The national industrial technology framework supports domestic motor component localization initiatives. Samsung Electronics and SK Hynix fabrication complexes in Gyeonggi Province anchor regional demand concentration.
Torque Motor Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and geographic reach. The vendor base organizes into three tiers: diversified industrial conglomerates with integrated motion platforms, dedicated motor specialists with application-specific architectures, and regional fabricators serving cost-sensitive indexing equipment. Strategic moves center on backward integration into rare-earth magnet supply chains and regional repair depot expansion to meet four-hour response mandates from semiconductor OEMs.
Within the diversified industrial tier, Siemens AG and ABB Ltd represent integrated platform providers bundling torque motors with digital infrastructure. Among dedicated motor specialists, Kollmorgen Corporation and Moog Inc exemplify archetypes differentiated by precision automation versus defense-aerospace positioning. ETEL motion technology and Tecnotion B.V. occupy positions as European frameless motor specialists. Yaskawa Electric Corporation and Nidec Corporation anchor Asian-origin supply capacity.
| Leading Market Players |
|---|
| Siemens AG |
| Kollmorgen Corporation |
| Moog Inc |
| ETEL motion technology |
| ABB Ltd |
| HIWIN GmbH |
| Tecnotion B.V. |
| Yaskawa Electric Corporation |
| Nidec Corporation |
| Others |
Value Chain & Pricing Dynamics
High-pole-count winding equipment utilization rates above 85 percent in Germany's precision automation cluster create scale economies that compress unit costs for frameless torque motors while simultaneously erecting capital barriers for prospective entrants. This concentration of specialized production capacity anchors price floors for premium direct-drive architectures and funnels margin pressure toward cost-optimized AC torque motor tiers serving textile and heavy industrial indexing applications.
Pricing Analysis
Technology-generation pricing gaps separate Halbach-array magnet configurations from conventional radial topologies by 15-25 percent at equivalent torque density, while legacy ferrite-assisted designs trade at steeper discounts in wafer-handling retrofits. Three-tier pricing structure across premium, standard, and economy levels reflects magnet grade differentiation, with N52-grade neodymium commanding premiums over N42 variants, and vacuum-compatible encapsulation adding further cost layers. Pricing pressure stems from buyer consolidation among semiconductor capital equipment vendors extracting volume concessions through panel reduction. OEM procurement teams exhibit lowest price sensitivity for EUV lithography stages, while India's Surat textile cluster sustains highest elasticity for AC torque motor replacements.
Supply Chain Analysis
Rare-earth magnet processing chokepoints in China's Inner Mongolia and Jiangxi provinces tether global torque motor production to concentrated upstream capacity, with neodymium and dysprosium separation facilities representing single-source vulnerabilities for premium magnet grades. Magnet wire supply draws from Japan's Furukawa Electric and South Korea's LS Cable, while precision lamination steel sources from Nippon Steel and ThyssenKrupp. Tariff exposure on Chinese-processed rare earths creates supply chain risk as alternative magnet processing capacity in Malaysia and Australia remains insufficient for demand substitution. Distribution runs through regional repair depots mandated by semiconductor OEM four-hour response clauses, with Siemens and KUKA procurement teams enforcing proximity requirements across Germany's Munich-Stuttgart corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torque motor penetration sits at early-cycle expansion as direct-drive architectures displace servo-motor-plus-gearbox configurations across semiconductor lithography and collaborative robotics, with EUV wafer stage adoption providing sustained demand tailwinds through the analysis window.
For Market Incumbents: Compound defensive positioning through backward integration into rare-earth magnet supply chains and captive winding equipment capacity additions in Germany's precision automation cluster. Kollmorgen Corporation's frameless motor architecture faces emerging pressure from integrated motion control platforms bundling hardware with digital twin software, demanding certification investment in IEC 61000 electromagnetic compatibility to sustain ASML supply base eligibility. Regional repair depot expansion represents the critical lever for meeting four-hour response mandates from consolidating semiconductor OEM procurement teams.
For New Entrants and Emerging Players: Aftermarket service contract gaps in legacy machine tool retrofit and defense platform refurbishment create white-space opportunities where incumbents under-serve winding refurbishment demand. India's Tiruppur textile cluster presents the most penetrable geography for cost-optimized AC torque motor supply, with maintenance provider relationships offering lower qualification barriers than OEM direct supply. Digital control integration partnerships with EtherCAT and PROFINET ecosystem vendors provide the essential go-to-market angle for bypassing entrenched channel relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dedicated motor specialists with application-specific architectures over diversified industrial conglomerates, as Halbach-array magnet topology transitions concentrate margin capture in precision automation segments. Long-term viability over a five-to-ten year window hinges on rare-earth magnet supply security and regional efficiency tier convergence. Acquisition targets should display ETEL motion technology's frameless specialization or Moog Inc's defense-aerospace program relationships. The signal to watch is MIIT GB 18613 efficiency standard enforcement tightening, which would accelerate domestic Chinese capacity buildout and compress import eligibility windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium processing mitigates Inner Mongolia concentration risk for premium torque motor producers. |
| Regional Repair Depot Expansion | Four-hour response mandates from ASML and Siemens procurement teams require proximity infrastructure. |
| Halbach-Array Magnet Topology Adoption | Superior airgap flux density reduces magnet volume for kilohertz-bandwidth EUV wafer stages. |
| Digital Twin Software Integration | Motion control platforms bundling torque motors with real-time simulation create service-based revenue streams. |
| Vacuum-Compatible Encapsulation Certification | Class 1 cleanroom compatibility enables Taiwan Semiconductor Manufacturing and Samsung Electronics fab supply. |
Study Parameters
Cross-validation between semiconductor capital equipment procurement disclosures and rare-earth magnet trade flow data anchors the qualitative findings on supply chain concentration. Primary interviews with frameless motor design engineers, cleanroom equipment procurement managers, precision automation R&D directors, and aftermarket service heads at defense platform operators combined with secondary validation from MIIT GB standard filings, METI JIS C 4034 efficiency benchmarks, US Department of Energy motor efficiency rulemakings, and SEC 10-K disclosures from listed motion control vendors. Bottom-up torque motor shipment aggregation and top-down precision automation equipment demand triangulation establish volume estimates.
Sensitivity analysis on rare-earth magnet price scenarios and semiconductor capital expenditure cycles tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product architecture (brushless versus AC versus DC), control philosophy (direct drive versus closed loop versus open loop), application vertical (semiconductor lithography, collaborative robotics, aerospace test rigs, telescope drives), and geographic regulatory cluster (MIIT efficiency tier markets, METI JIS markets, NEMA Premium jurisdictions). CAGRs derive from equipment replacement cycle analysis and technology substitution elasticity estimates, with EUV lithography stage adoption curves and collaborative robot joint penetration rates serving as industry-specific forecast inputs.
Underlying assumptions cover sustained semiconductor fabrication capacity expansion, stable rare-earth magnet processing concentration, and efficiency standard enforcement continuity, with deviation risk concentrated in geopolitical disruption of Chinese magnet supply and faster-than-expected AC torque motor substitution in cost-sensitive indexing. Practitioners should keep alternative scenarios live as MIIT enforcement intensity and Halbach-array manufacturing yield improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Traction Motor Core Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Electric Trolling Motors Market