
 Automotive Blower Motor Market | 2026-2036
Automotive Blower Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Blower Motor Market Analytics
Brushless DC specification upgrades are redrawing supplier economics across climate-module procurement. Brose leverages in-house motor and electronics integration to sustain pricing power in European premium vehicle programs. Denso anchors its position through captive supply relationships with Toyota and Lexus hybrid architectures. Valeo competes by extending its thermal systems portfolio into heat-pump-integrated blower modules for battery electric platforms.
An automotive blower motor is an electromechanical air-moving device, typically rated between 12V and 48V, that generates forced airflow across heater cores and evaporator coils to regulate cabin temperature and defrost surfaces. Centrifugal blower configurations dominate OEM fitment due to superior static pressure performance against dense HVAC filter loading. The electric vehicle end-user segment represents the fastest-expanding demand pool, as dual-zone and tri-zone climate systems multiply motor counts per vehicle. Aftermarket installation channels occupy mature, price-sensitive volume, while integrated factory-fit modules capture the majority of margin concentration.
NHTSA safety standards for defrosting performance and EPA fuel-economy testing protocols both mandate minimum airflow rates that directly shape motor torque and efficiency specifications in US-bound vehicles. The EU F-Gas Regulation and CE marking requirements for electromagnetic compatibility constrain thermal system design choices across European passenger and commercial vehicle programs. Stakeholders must monitor how 800V high-voltage architectures in next-generation EVs will force isolation and semiconductor redesigns in blower motor control electronics.
Market Dynamics
The transition to 48V mild-hybrid and full battery electric architectures is forcing fundamental redesigns of blower motor electromagnetic compatibility, thermal management, and semiconductor isolation across all vehicle programs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of high-GWP refrigerants accelerates heat pump adoption in climate modules, doubling motor counts per vehicle thermal system.
- NEV production concentration in China:Domestic procurement intensity for blower motors now exceeds conventional ICE vehicle attachment rates by factor of two-to-three per platform.
- Dual-zone climate standardization:Premium and mass-market segments alike mandate independent temperature control for driver and passenger zones.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings compress margins for permanent magnet brushless DC motor suppliers.
- Semiconductor supply concentration:IGBT and MOSFET sourcing bottlenecks from Taiwan and South Korea constrain controller module production scaling.
- Copper winding substitution limits:Aluminum magnet wire remains electrically inferior for high-torque density applications in compact HVAC housings.
Strategic Opportunities
- 800V high-voltage EV platforms:Isolation-rated motor controllers and ceramic capacitors create premium component tier with limited qualified supplier base.
- India PLI scheme for auto components:Localized manufacturing incentives attract module assembly investments serving ASEAN export markets.
- Smart HVAC convergence:Integration of particulate sensors, humidity monitors, and blower motors into unified climate control units enables software-defined thermal management.
Industry Challenges
- Embedded software competency gaps:Motor control algorithm development for field-oriented control requires power electronics expertise scarce in traditional mechanical component suppliers.
- ISO 26262 functional safety certification:ASIL-rated blower systems for autonomous vehicle cabins extend validation timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Blower Motor Market |
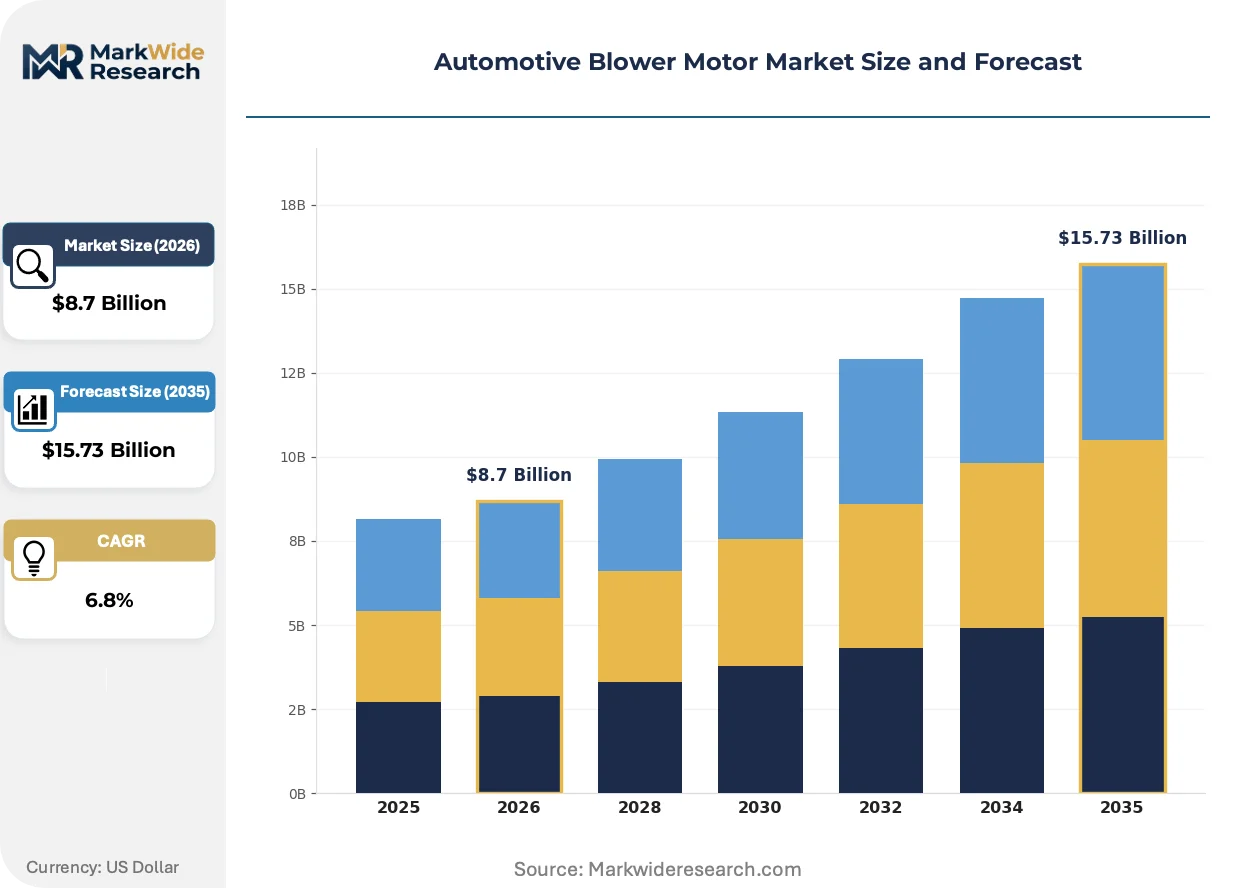
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fan, Centrifugal Blower, Dual Inlet, Single Inlet End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Electric Vehicles Installation Type: OEM, Aftermarket, Retrofit, Integrated Power Rating: 12V, 24V, 48V, Others |
| Companies Covered | Brose, Valeo, Denso, Continental, Nidec, Marelli Corporation, Hyoseong Electric, MAHLE, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Blower Motor Market Evolving Landscape
Electrification is compressing product lifecycles and collapsing the boundary between thermal hardware and vehicle electronics. Three converging developments are restructuring supplier capabilities and procurement criteria.
Brushless DC motor architectures with integrated field-oriented control are fragmenting the supplier landscape between integrated module specialists and component vendors. Tier 1 climate system manufacturers now specify motors with embedded CAN communication and diagnostic capability, disqualifying legacy brushed motor suppliers from new platform bids. The technology shift compresses addressable market for standalone motor producers while expanding margin capture for electronics-integrated suppliers.
EPA fuel-economy testing protocols now incorporate cabin conditioning energy consumption as a measured input, tightening airflow efficiency specifications for US-bound vehicles. NHTSA defrost performance mandates maintain minimum torque requirements that conflict with downsizing objectives. OEM engineering teams respond by specifying ultra-efficient fan blade geometries and low-friction bearing systems that satisfy both regulatory constraints.
Fleet procurement of aftermarket blower assemblies is consolidating through authorized service channel networks, displacing traditional jobber distribution. Large commercial vehicle operators negotiate direct supply agreements with motor remanufacturers for standardized HVAC component pools. North American heavy-duty truck segments exhibit the most pronounced channel compression, with national leasing companies centralizing climate system maintenance spend.
Automotive Blower Motor Market Segmentation
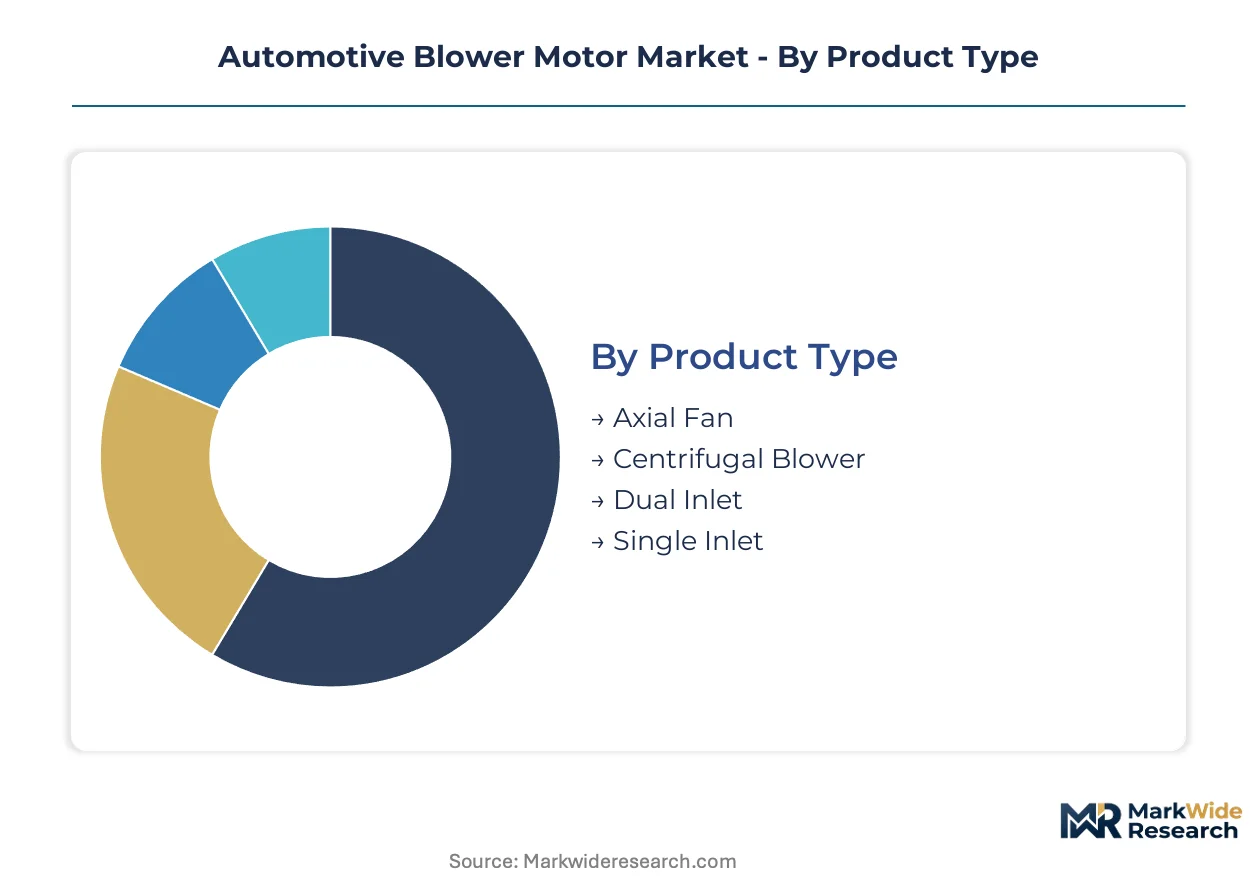
Segmentation in the automotive blower motor market reveals how electrification architectures and regulatory testing protocols reshape procurement specifications across vehicle programs. Product type and power rating classifications now determine supplier qualification criteria more than traditional price-volume metrics.
Product Type:
EU F-Gas Regulation phase-down of high-GWP refrigerants and EPA fuel-economy testing protocols both mandate specific airflow geometries that favor certain blower configurations over others in regional vehicle programs.
- Centrifugal Blower:Generates superior static pressure performance against dense HVAC filter loading through curved blade impeller designs. Demand concentrates in European passenger car programs where CE marking requirements for electromagnetic compatibility constrain axial alternatives in compact engine bays.
- Axial Fan:Moves air parallel to the motor shaft with lower pressure generation but higher volumetric flow rates at equivalent power draw. Adoption favors commercial vehicle HVAC systems in China where NEV production volume now dominates procurement intensity for simplified thermal architectures.
- Dual Inlet:Draws air from opposing housing apertures to balance noise signatures in premium cabin environments.
- Single Inlet:Standard fitment for economy vehicle segments with unidirectional airflow paths and reduced component count.
Established volume favors Centrifugal Blower; emerging adoption favors Axial Fan.
End User:
Cost tier stratification separates premium climate-module integration from aftermarket replacement economics across vehicle lifecycle stages.
- Electric Vehicles:Require dual-zone and tri-zone climate systems that multiply motor counts per platform compared to conventional architectures. Demand clusters in China where domestic procurement intensity for blower motors exceeds conventional ICE attachment rates by substantial margins.
- Passenger Vehicles:Represent the baseline volume segment with standardized 12V and 24V motor specifications across mass-market OEM programs.
- Commercial Vehicles:Prioritize durability ratings and extended service intervals in fleet-operated transport applications.
- Heavy-Duty Trucks:Exhibit pronounced channel compression through national leasing companies centralizing climate system maintenance spend in North American authorized service networks.
Passenger Vehicles anchor current procurement volume; Electric Vehicles command the steepest expansion trajectory.
Installation Type:
Supply concentration in integrated factory-fit modules captures margin concentration that aftermarket channels cannot replicate.
- OEM:Factory-fit modules specify motors with embedded CAN communication and diagnostic capability, disqualifying legacy brushed motor suppliers from new platform bids. Procurement concentrates with Tier 1 climate system manufacturers who bundle thermal hardware with vehicle electronics.
- Aftermarket:Occupies mature, price-sensitive volume through jobber distribution networks facing displacement by authorized service channel consolidation.
- Retrofit:Serves vehicle modification segments upgrading older HVAC systems to meet revised defrost performance standards.
- Integrated:Combines particulate sensors, humidity monitors, and blower motors into unified climate control units enabling software-defined thermal management.
OEM commands margin concentration; Integrated represents the fastest-climbing adoption curve.
Power Rating:
Application voltage determines semiconductor isolation requirements and electromagnetic compatibility certification pathways.
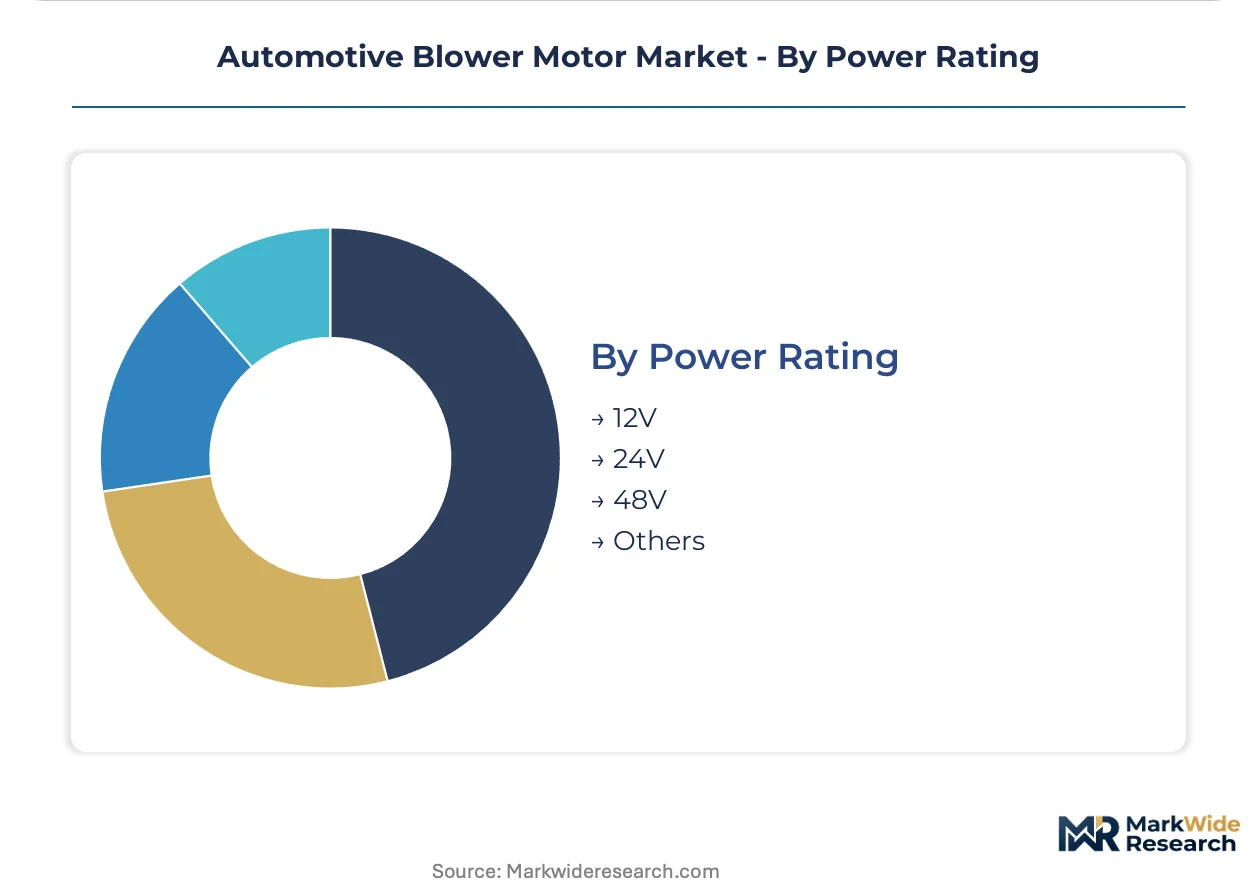
- 48V:Mild-hybrid electrical architectures under EU emissions rules force motor redesigns with isolation-rated controllers and ceramic capacitors. Limited qualified supplier base creates premium component tier for European passenger car programs.
- 12V:Dominates legacy ICE vehicle architectures with established supply chains and standardized controller modules.
- 24V:Serves commercial vehicle electrical systems with higher torque requirements for larger cabin volumes.
- Others:Encompasses emerging 800V high-voltage EV platforms forcing fundamental redesigns of motor thermal management and semiconductor isolation.
12V retains established volume dominance; 48V gains share fastest through regulatory-driven platform transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier networks for automotive blower motors concentrate in manufacturing corridors tied to major vehicle assembly clusters, with procurement patterns diverging sharply between mature 12V architectures and emerging high-voltage platforms.
China
NEV production volume in Shanghai, Shenzhen, and Xi'an now drives blower motor procurement intensity exceeding conventional ICE attachment rates by substantial margins. MIIT dual carbon goals accelerate heat pump adoption across domestic EV platforms. Yangtze River Delta suppliers scale brushless DC module output to serve BYD and Tesla Gigafactory demand.
Germany
48V mild-hybrid electrical architectures under KBA emissions compliance force motor redesigns across Stuttgart and Munich engineering centers. EU F-Gas Regulation phase-down mandates heat-pump-integrated blower modules for premium passenger programs. Baden-Württemberg component suppliers capture isolation-rated controller contracts for next-generation EV thermal systems.
United States
EPA fuel-economy testing protocols incorporating cabin conditioning energy consumption tighten airflow efficiency specifications for Detroit Three vehicle programs. NHTSA defrost performance mandates maintain minimum torque requirements conflicting with motor downsizing objectives. Southeast assembly corridors in Tennessee and South Carolina anchor climate module procurement for transplanted OEM operations.
Japan
Captive supply relationships between Tier 1 thermal specialists and Toyota hybrid architectures sustain concentrated procurement channels in Aichi Prefecture. METI technology roadmaps prioritize semiconductor integration in motor control electronics. Kansai region suppliers develop field-oriented control algorithms for ASIL-rated autonomous vehicle cabin systems.
India
PLI scheme incentives for auto components attract module assembly investments serving ASEAN export markets from Tamil Nadu and Gujarat manufacturing zones. Domestic OEM programs prioritize cost-optimized 12V and 24V motor specifications for mass-market passenger and commercial vehicles. BIS electromagnetic compatibility certification requirements constrain supplier qualification pathways for European-bound exports.
Automotive Blower Motor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the supplier base. Integrated module specialists with in-house motor and electronics capabilities capture premium pricing in European and Japanese OEM programs, while component-focused vendors compete on scale in aftermarket and emerging economy vehicle segments. Two strategic archetypes dominate: captive Tier 1 thermal system suppliers with OEM equity ties, and independent motor specialists pursuing electronics integration through acquisition. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion into China NEV supply chains.
Within the integrated Tier 1 tier, Brose, Denso, and Valeo exemplify contrasting approaches to climate-module procurement consolidation. Brose represents European premium-program positioning through captive motor and electronics integration. Denso anchors Japanese hybrid and EV architectures through long-standing OEM supply relationships. Valeo occupies the thermal systems convergence space, extending portfolio scope into heat-pump-integrated modules for battery electric platforms. These three entities illustrate how supplier economics fragment between electronics-integrated specialists and legacy mechanical component vendors disqualified from new platform bids requiring embedded CAN communication and diagnostic capability.
| Leading Market Players |
|---|
| Brose |
| Valeo |
| Denso |
| Continental |
| Nidec |
| Marelli Corporation |
| Hyoseong Electric |
| MAHLE |
| Bosch |
| Others |
Value Network & Pricing Analysis
Ninety-day semiconductor inventory cycles in motor controller modules concentrate procurement leverage with integrated Tier 1 suppliers and compress standalone component vendors into spot-market pricing. This lead-time band shapes how EU F-Gas Regulation compliance costs flow through climate-module contracts and where rare earth magnet volatility erodes margin buffers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European passenger car programs, separating heat-pump-integrated modules with isolation-rated controllers from legacy 12V brushed motor alternatives. Pricing stratifies across premium, standard, and economy tiers based on ASIL certification grade and volume scale. Cost compression in aftermarket channels is intensifying because fleet procurement consolidation displaces jobber distribution networks. Heavy-duty truck fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership contracts, while independent repair shops face maximum margin pressure.
Supply Chain Analysis
Ninety-day semiconductor inventory cycles expose the sector to Taiwan and South Korea sourcing concentration for IGBT and MOSFET controller components. The supply chain draws from China for rare earth magnet processing, Germany for precision bearing systems, and Mexico for final module assembly serving North American OEMs. Single-source vulnerability in ceramic capacitor grades for 48V isolation creates qualification bottlenecks. Distribution runs through Tier 1 climate system manufacturers who bundle motors with embedded CAN diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined thermal management represents a service-attach opportunity expanding faster than hardware replacement cycles, as predictive HVAC maintenance contracts monetize sensor-integrated blower modules through recurring revenue streams.
For Market Incumbents: Consolidate backward integration into semiconductor sourcing to defend against controller module supply bottlenecks from Taiwan concentration. Capture captive supply relationships with NEV platform engineering teams in China through co-development agreements on 800V isolation architectures. Lock in rare earth magnet offtake contracts before dysprosium price volatility compresses brushless DC margins. For New Entrants and Emerging Players: Differentiate on field-oriented control algorithm competency to penetrate the embedded software gap constraining legacy mechanical suppliers. Target India's PLI scheme manufacturing zones for module assembly serving ASEAN export markets with cost-optimized 12V specifications. Pursue direct fleet supply agreements with national leasing companies centralizing heavy-duty truck climate maintenance spend. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 800V high-voltage EV platform components due to isolation-rated semiconductor and ceramic capacitor requirements. Five-to-ten year viability favors integrated module specialists with captive electronics capabilities over standalone motor producers disqualified from new platform bids. Watch for heat pump adoption inflection in China NEV production as signal for motor count multiplication per vehicle.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Backward Integration | Captive IGBT sourcing from Taiwan fabs secures controller module allocation for EU 48V programs. |
| Heat Pump Module Development | Dual-motor climate architectures for EU F-Gas compliance capture premium pricing in Stuttgart engineering centers. |
| India PLI Manufacturing Footprint | Tamil Nadu assembly zones serve ASEAN export markets with BIS-certified electromagnetic compatibility. |
| Software-Defined Thermal Integration | Embedded CAN diagnostics enable predictive maintenance contracts displacing aftermarket jobber channels. |
| 800V Isolation Certification | Ceramic capacitor qualification creates limited supplier tier for next-generation EV thermal systems. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 thermal system procurement managers, aftermarket distribution heads, and semiconductor supply specialists provided ongoing calibration across the research process. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EU F-Gas regulatory filings, and MIIT NEV production disclosures. Bottom-up motor count modeling triangulated against top-down climate-module revenue estimates.
Consistency checks validated volume and value outputs against external production benchmarks across the analysis window. The analytical framework segmented by propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to NEV attachment rate trajectories and ICE replacement cycle assumptions. Forecast inputs incorporated semiconductor lead-time dynamics and rare earth magnet price elasticity effects.
Material uncertainties — semiconductor allocation shocks, rare earth export restrictions, and 800V platform timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory phase-down schedules and OEM platform transition commitments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Motorcycle Market
Electric Motor
Starter Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Vibrator Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
High Speed Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Torque Motor Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Frameless Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Global Automotive Onboard Charger Market