
 Electric Vehicle Traction Motor Core Market | 2026-2036
Electric Vehicle Traction Motor Core Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Traction Motor Core Market Insights
IATF 16949 automotive quality certification is unwinding the supplier base for electric vehicle traction motor cores, filtering out stampers lacking process traceability and statistical process control. Mitsui High-tec leverages decades of laminated core expertise to anchor Japanese OEM supply chains. POSCO sustains captive electrical steel production, controlling upstream material consistency for its core stamping operations. Suzhou Fine-stamping competes on high-speed progressive die capacity serving domestic Chinese EV platforms.
An electric vehicle traction motor core comprises stacked, insulated laminations of silicon electrical steel that channel magnetic flux and minimize eddy-current losses during high-frequency operation. These cores typically achieve magnetic saturation above 2.0 T and operate at switching frequencies of 5–15 kHz in modern inverter-driven architectures, converting electrical energy into mechanical torque with efficiency targets exceeding 97% in peak zones. Permanent magnet synchronous configurations dominate passenger vehicle applications where power density and efficiency at partial load matter most, while induction motor cores retain structural share in commercial vehicle platforms prioritizing cost resilience and rare-earth independence. Copper winding material commands margin concentration due to conductivity advantages and supply tightness, though aluminum substitution gains traction in cost-optimized two-wheeler and bus segments.
The EPA tailpipe standards, EU Green Deal vehicle CO2 targets, and China's MIIT NEV credit system collectively mandate higher motor efficiency thresholds that cascade into lamination thickness, insulation grade, and core loss specifications. NHTSA fuel economy rules and REACH material compliance further constrain material selection and manufacturing chemistry for suppliers accessing North American and European OEM channels. Stakeholders must monitor how regional content requirements and carbon border adjustments reshape sourcing geography for electrical steel and rare-earth magnet materials.
Market Dynamics
The laminated electrical steel supply chain is consolidating around captive melt-to-stack operations as OEMs demand sub-50-micron lamination tolerances and full-batch traceability for high-efficiency motor platforms.
Growth Catalysts
- China MIIT NEV credit system:Mandates escalate motor efficiency thresholds, forcing laminated core procurement upgrades across domestic EV platforms.
- Hairpin winding adoption:Stator designs with rectangular copper conductors increase slot fill factors, demanding precision-stacked cores with tighter lamination tolerances.
- East Asian manufacturing corridors:Concentrated motor production in Japan, China, and South Korea generates procurement scale effects for tier-one lamination suppliers.
Market Restraints
- Electrical steel supply concentration:Non-oriented silicon steel production clusters in China and Japan, exposing buyers to regional logistics disruptions and alloy pricing volatility.
- Rare-earth magnet dependency:Permanent magnet synchronous motor cores require neodymium-iron-boron magnets concentrated in Chinese processing facilities.
- IATF 16949 certification barriers:Stamping operations lacking statistical process control and full traceability systems face exclusion from OEM supply chains.
Strategic Opportunities
- India PLI scheme for automotive:Domestic EV manufacturing incentives create localized demand for laminated core stamping capacity with import-substitution potential.
- Induction motor resurgence:Rare-earth-independent motor architectures gain traction in commercial vehicle segments seeking supply chain resilience.
- Silicon carbide inverter pairing:Higher switching frequencies from wide-bandgap semiconductors enable thinner lamination designs with reduced core losses.
Industry Challenges
- Progressive die tooling capex:High-speed lamination lines require multi-million-dollar precision tooling investments with extended qualification timelines.
- Copper winding supply tightness:Conductivity material shortages strain stator assembly operations and compress margin structures at contract manufacturers.
- REACH material compliance:European chemical regulations constrain insulation coating chemistries and require reformulation of lamination bonding systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Traction Motor Core Market |
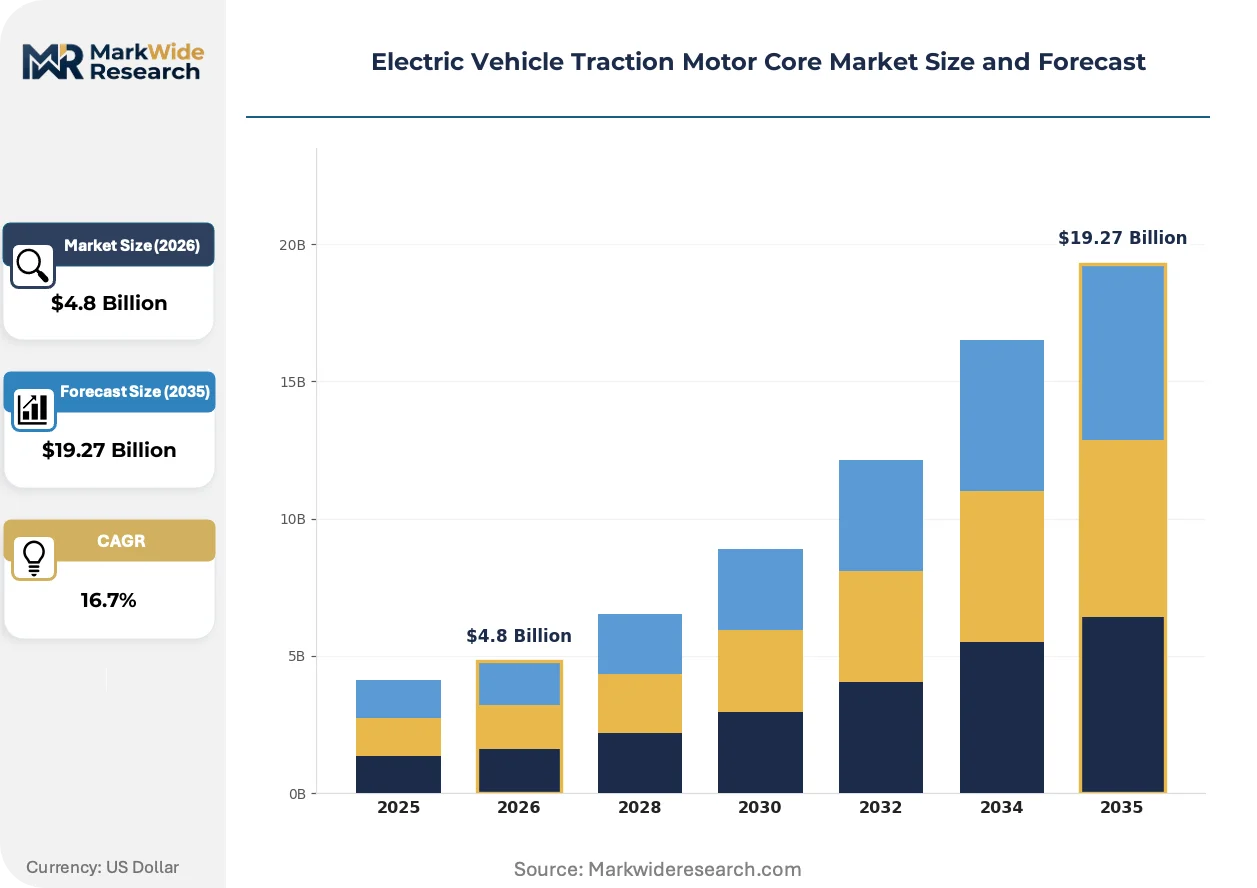
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Permanent Magnet, Induction, Switched Reluctance, Synchronous Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Material: Copper, Aluminum, Steel, Rare Earth End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | Mitsui High-tec, POSCO, EUROTRANCIATURA, Suzhou Fine-stamping, Tempel Steel, Wuxi Longsheng Technology, Yutaka Giken, Hidria, R.Bourgeois, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Traction Motor Core Market Trends and Innovations
Magnetic core engineering is pivoting toward thinner-gauge electrical steels and advanced insulation systems as inverter switching frequencies climb and efficiency regulations tighten across major automotive markets.
Self-bonding lamination technology is miniaturizing traditional core assembly processes by eliminating mechanical interlocking features. Japanese and Korean motor suppliers are adopting these adhesive-coated steels for high-speed rotor applications. The process compression is miniaturizing core stack tolerances while reducing inter-lamination eddy current paths.
EU Green Deal vehicle CO2 targets are mandating fleet-average emissions reductions that cascade into motor efficiency specifications. OEMs now require lamination suppliers to document carbon intensity across steel melting, rolling, and stamping operations. German and French automotive channels are prioritizing cores from electric arc furnace routes with renewable energy inputs.
Platform consolidation among battery-electric vehicle architectures is concentrating procurement volumes with fewer stamping suppliers. Tier-one motor manufacturers are awarding multi-year laminated core contracts with attached tooling investment commitments. This buyer concentration is most visible in Chinese EV platform supply chains where annual motor volumes exceed single-factory capacity thresholds.
Electric Vehicle Traction Motor Core Market Segmentation
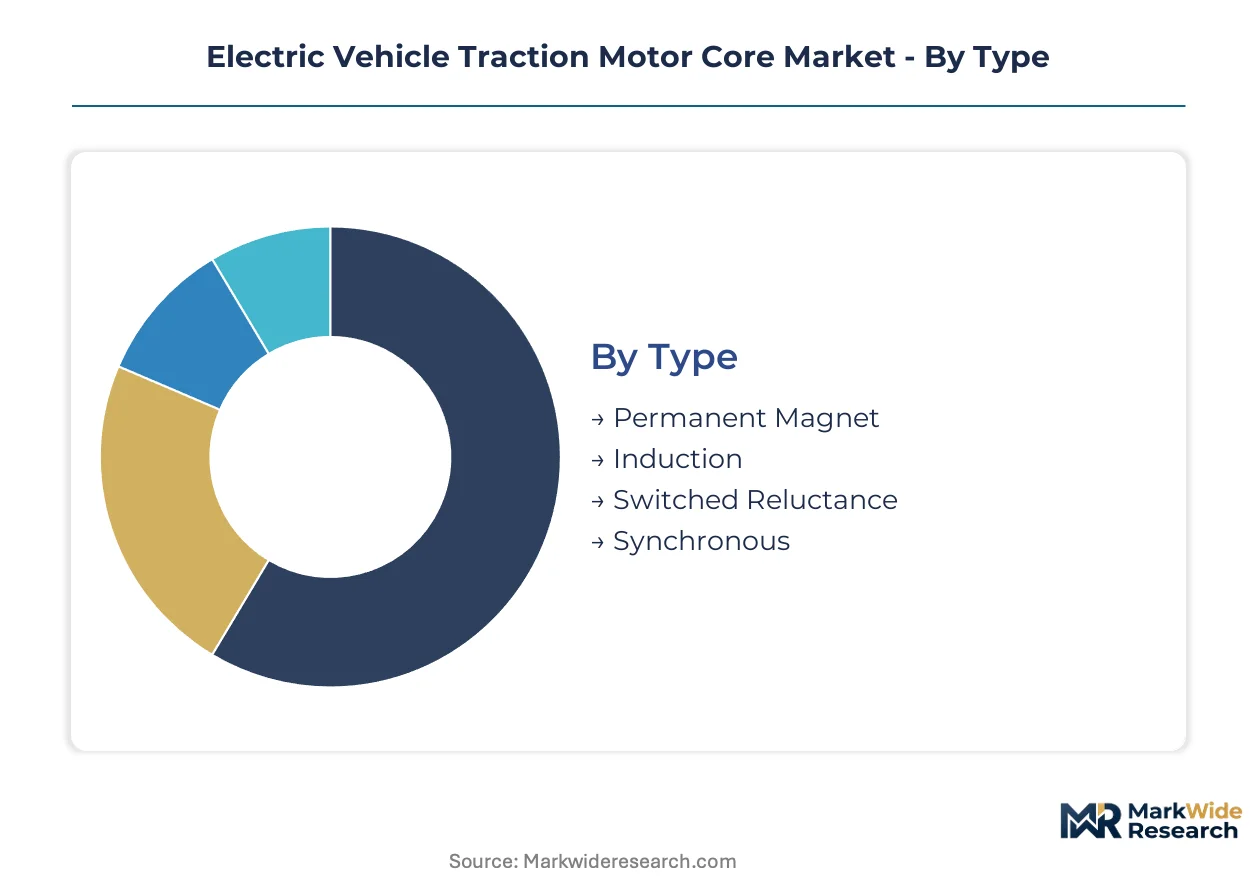
Electric vehicle traction motor cores fragment across motor topology, vehicle platform, conductor material, and supply chain position. Each dimension carries distinct technical specifications, procurement volumes, and margin structures that shape supplier capabilities and competitive positioning.
Type:
Permanent magnet configurations dominate Japanese and Chinese OEM supply chains, while induction architectures retain stronger share in European commercial vehicle platforms seeking rare-earth independence.
- Permanent Magnet:Neodymium-iron-boron rotor assemblies deliver peak power density above 4 kW/kg and efficiency exceeding 97% in partial-load zones. Procurement concentrates with Chinese OEMs under MIIT NEV credit mandates; rare-earth processing dependency constrains European sourcing flexibility.
- Induction:Copper or aluminum cage rotors eliminate magnet supply risk while accepting modest efficiency trade-offs at low speeds. German commercial vehicle manufacturers specify these cores for long-haul trucks prioritizing supply chain resilience over peak power density.
- Switched Reluctance:Salient-pole rotors without windings or magnets suit cost-optimized two-wheeler platforms in India.
- Synchronous:Wound-field or reluctance variants serve heavy-duty bus applications requiring extended high-torque operation.
Permanent magnet holds the largest share; momentum sits with induction as rare-earth price volatility accelerates alternative motor architecture qualification.
Application:
Passenger vehicle platforms generate procurement scale that justifies dedicated lamination lines, while commercial and bus segments prioritize thermal durability over manufacturing velocity.
- Passenger Vehicles:Battery-electric sedans and crossovers specify hairpin-wound stators with 0.25–0.30 mm silicon steel laminations. Chinese platforms from BYD, NIO, and XPeng drive annual core volumes exceeding single-supplier capacity thresholds.
- Commercial Vehicles:Medium-duty trucks and vans accept thicker 0.35 mm laminations with reduced switching frequency tolerance. European fleet operators under EU Green Deal CO2 targets specify these cores for urban delivery routes with frequent stop-start cycles.
- Two-Wheelers:Scooter and motorcycle motors in India and Southeast Asia substitute aluminum for copper to hit sub-$200 powertrain cost targets.
- Buses:Electric transit fleets in South Korea and Japan demand extended insulation life for high-mileage duty cycles.
Passenger vehicles command procurement volume leadership; commercial vehicles are climbing the fastest as last-mile electrification mandates expand across German and French urban zones.
Material:
Conductor selection splits across conductivity requirements and cost positioning, with copper commanding premium segments and aluminum penetrating price-sensitive categories.
- Copper:100% IACS conductivity windings enable compact slot designs and reduced resistive losses. Japanese tier-one suppliers specify oxygen-free copper for 800V architectures in luxury EV platforms.
- Aluminum:61% IACS conductivity demands 60% larger conductor cross-sections but eliminates supply tightness risk. Indian two-wheeler manufacturers specify aluminum stators under PLI scheme cost constraints.
- Steel:Non-oriented silicon electrical steel with 2–3% silicon content forms the magnetic circuit backbone.
- Rare Earth:Neodymium and dysprosium additions to permanent magnet grades enable 150°C continuous operation.
Copper retains the dominant share; aluminum is expanding most quickly in emerging market two-wheeler and entry-level passenger vehicle segments.
End User:
OEM captive motor production and tier-1 contract manufacturing split procurement patterns, with aftermarket channels remaining nascent in this component category.
- OEMs:Vertical integration into lamination stamping accelerates at BYD, Tesla, and Hyundai as platform volumes justify dedicated capacity. These facilities achieve lot-to-lot traceability required for IATF 16949 certification.
- Tier-1 Suppliers:Bosch, Denso, and Nidec source laminated cores from specialized stampers with progressive die expertise. Their procurement contracts attach multi-year tooling investment commitments.
- Aftermarket Providers:Remanufactured stator cores serve legacy hybrid vehicle fleets in Japan with extended service intervals.
- Dealerships:Minimal direct procurement; service operations rely on tier-1 distribution networks for replacement components.
OEMs hold the largest procurement share; tier-1 suppliers are gaining the steepest expansion trajectory as platform consolidation concentrates outsourced motor manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port anchors East Asian electrical steel flows, handling over one billion tons of cargo annually and channeling silicon steel coils toward motor stamping facilities across the Pacific Rim.
China
BYD and NIO battery-electric platforms drive laminated core procurement at volumes exceeding single-supplier capacity. MIIT NEV credit mandates tighten motor efficiency thresholds, forcing 0.25 mm lamination adoption. The Yangtze River Delta corridor concentrates stamping operations serving domestic OEMs with sub-50-micron tolerance requirements.
Japan
Toyota and Nissan electrification programs sustain precision lamination demand for hybrid and full-electric powertrains. METI carbon neutrality roadmaps accelerate thin-gauge electrical steel development. The Nagoya-Toyota industrial zone hosts integrated melt-to-stack operations controlling upstream material consistency.
Germany
Mercedes-Benz and BMW 800V architectures specify hairpin-wound stators with full-batch traceability documentation. EU Green Deal fleet CO2 targets mandate 97%-plus motor efficiency, cascading into insulation grade specifications. The Bavarian automotive cluster sources cores from suppliers documenting electric arc furnace carbon intensity.
South Korea
Hyundai and Kia dedicated EV platforms justify captive lamination stamping capacity with IATF 16949 certification. KBA type-approval processes enforce electromagnetic compatibility testing for high-frequency inverter operation. The Busan-Ulsan manufacturing belt concentrates motor production with attached multi-year tooling investment commitments.
United States
Tesla and Rivian vertical integration into core stamping accelerates as platform volumes justify dedicated capacity. EPA tailpipe standards and NHTSA fuel economy rules constrain motor loss budgets. The Texas manufacturing corridor attracts electrical steel distribution networks serving Southwestern EV assembly plants.
Electric Vehicle Traction Motor Core Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with consolidated tier-one supply chains filtering out stampers lacking IATF 16949 process traceability. Japanese and Korean electrical steel conglomerates anchor regional procurement networks through captive melt-to-stack operations. Three archetypes dominate: vertically integrated steel-to-core manufacturers, high-speed progressive die specialists, and rare-earth-independent induction motor fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs award multi-year contracts with attached tooling commitments.
Within the vertically integrated tier, Mitsui High-tec and POSCO exemplify steel-to-core control strategies, with the former anchoring Japanese OEM supply chains and the latter sustaining captive electrical steel production. Suzhou Fine-stamping occupies a position among high-speed progressive die specialists serving domestic Chinese EV platforms with precision-stacked core capacity.
| Leading Market Players |
|---|
| Mitsui High-tec |
| POSCO |
| EUROTRANCIATURA |
| Suzhou Fine-stamping |
| Tempel Steel |
| Wuxi Longsheng Technology |
| Yutaka Giken |
| Hidria |
| R.Bourgeois |
| Others |
Pricing and Supply Chain Analysis
Multi-year laminated core contracts with attached tooling investment commitments lock in supply access and price visibility for OEMs scaling battery-electric platforms. China's MIIT NEV credit system and EU CO2 fleet standards tighten motor efficiency thresholds, forcing buyers to absorb premium lamination grades or risk procurement exclusion.
Pricing Analysis
IATF 16949 certification level creates the primary spread between qualified suppliers and excluded stampers. Contract-based long-term offtake dominates, with volume scale and hairpin-winding precision requirements driving price differentiation. Cost compression in domestic Chinese EV platforms is intensifying because BYD and NIO annual motor volumes exceed single-supplier capacity thresholds. Tier-1 contract manufacturers show least price sensitivity due to attached multi-year tooling commitments, while aftermarket providers face acute margin pressure.
Supply Chain Analysis
China and Japan anchor non-oriented silicon electrical steel production, with South Korea feeding specialized high-frequency grades. The laminated core supply chain draws from electrical steel coils, rare-earth magnet materials, and copper winding conductors. Single-source vulnerability concentrates in Chinese neodymium-iron-boron processing facilities. Distribution runs through East Asian manufacturing corridors spanning the Yangtze River Delta, Nagoya-Toyota industrial zone, and Busan-Ulsan belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of sub-50-micron lamination tolerance capability with full-batch traceability is concentrating procurement power among certified stampers. This gap separates qualified suppliers from excluded competitors across Japanese, Korean, and German OEM channels.
For Market Incumbents: Fortify melt-to-stack control over electrical steel sourcing to defend against rare-earth price volatility and alloy supply disruptions. Mitsui High-tec and POSCO demonstrate this through captive upstream material consistency. Expand progressive die capacity in the Yangtze River Delta corridor to capture Chinese platform consolidation volumes. For New Entrants and Emerging Players: IATF 16949 certification fast-track through statistical process control investment opens tier-1 supply chain access currently filtered to incumbent stampers. Target India's PLI scheme automotive incentives for localized stamping capacity with import-substitution potential. Position around induction motor core fabrication for commercial vehicle segments seeking rare-earth independence. For Investors and Strategic Acquirers: High-speed progressive die specialists with hairpin-winding precision capability represent acquisition targets as platform consolidation concentrates procurement. Long-term viability hinges on silicon carbide inverter pairing enabling thinner lamination designs. Watch silicon carbide adoption curves as inflection indicator for next-generation core specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Electrical Steel Production | POSCO controls upstream material consistency for its core stamping operations against alloy pricing volatility. |
| Hairpin Winding Precision Investment | High-speed progressive die capacity captures slot fill factor demands from 800V architectures at Mercedes-Benz. |
| Induction Motor Core Fabrication | Rare-earth-independent architectures penetrate German commercial vehicle platforms under EU Green Deal targets. |
| Self-Bonding Lamination Adoption | Adhesive-coated steels eliminate mechanical interlocking for Japanese and Korean high-speed rotor applications. |
| India PLI Scheme Localization | Domestic stamping capacity addresses import-substitution potential for two-wheeler and bus electrification mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; and secondary validation through vehicle production databases, customs records for electrical steel trade flows, and IATF 16949 certification registries. Bottom-up triangulation across motor topology segmentation and top-down cross-check against platform consolidation trends anchored volume estimates.
Across the analysis window, the forecasting framework modeled permanent magnet versus induction motor architectures, passenger versus commercial vehicle platforms, and copper versus aluminum conductor materials. CAGRs derived from platform volume trajectories, efficiency regulation cascades, and silicon carbide inverter adoption curves. Hairpin winding penetration rates and lamination thickness specifications served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT NEV credit enforcement and EU Green Deal fleet CO2 target maintenance; material deviation in rare-earth supply geography or electrical steel trade policy would warrant model refresh. Recalibration cycles align with material shifts in inverter semiconductor technology and carbon border adjustment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Motors for Robot Body and Robot Wheels Market