
 Automotive Electric Commutators Market | 2026-2036
Automotive Electric Commutators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Commutators Market Insights
Modular motor-commutator bundling is pivoting procurement patterns across automotive electrification programs. Kolektor leverages its European manufacturing footprint to supply integrated rotary commutator assemblies for hybrid starter-generators. Shenzhen Kaizhong Precision Technology Co., Ltd. anchors high-volume production of copper segment bars for Chinese EV motor platforms. Friedrich Nettelhoff GmbH & Co. KG differentiates through precision-milled silver-copper composite commutators serving German OEM direct-current motor requirements.
Automotive electric commutators are electromechanical switching devices composed of copper segments insulated by mica or polymer composites, engineered to reverse current direction in DC and universal motors operating between 12V and 800V architectures. Their primary purpose is maintaining continuous torque output in starter motors, HVAC blowers, power steering pumps, and traction motors across conventional and electrified vehicles. Rotary commutators dominate current revenue pools due to entrenched starter motor and auxiliary motor applications, while composite material configurations represent the fastest-growing segment as OEMs seek weight reduction and extended brush life in e-motor designs. Copper material grades sustain the largest volume share, though silver-plated variants command premium positioning in high-RPM traction motor segments where arcing resistance proves critical.
The EPA, NHTSA, and EU Green Deal collectively mandate CO2 reductions and zero-emission vehicle thresholds that force commutator suppliers to certify copper sourcing, mica insulation thermal ratings, and recyclability under REACH and RoHS frameworks. These regulations elevate technical barriers for aftermarket providers while rewarding Tier-1 suppliers with validated lifecycle documentation. Stakeholders must monitor how solid-state motor controller advances and silicon carbide inverter diffusion reshape commutator relevance across next-generation automotive motor architectures.
Market Dynamics
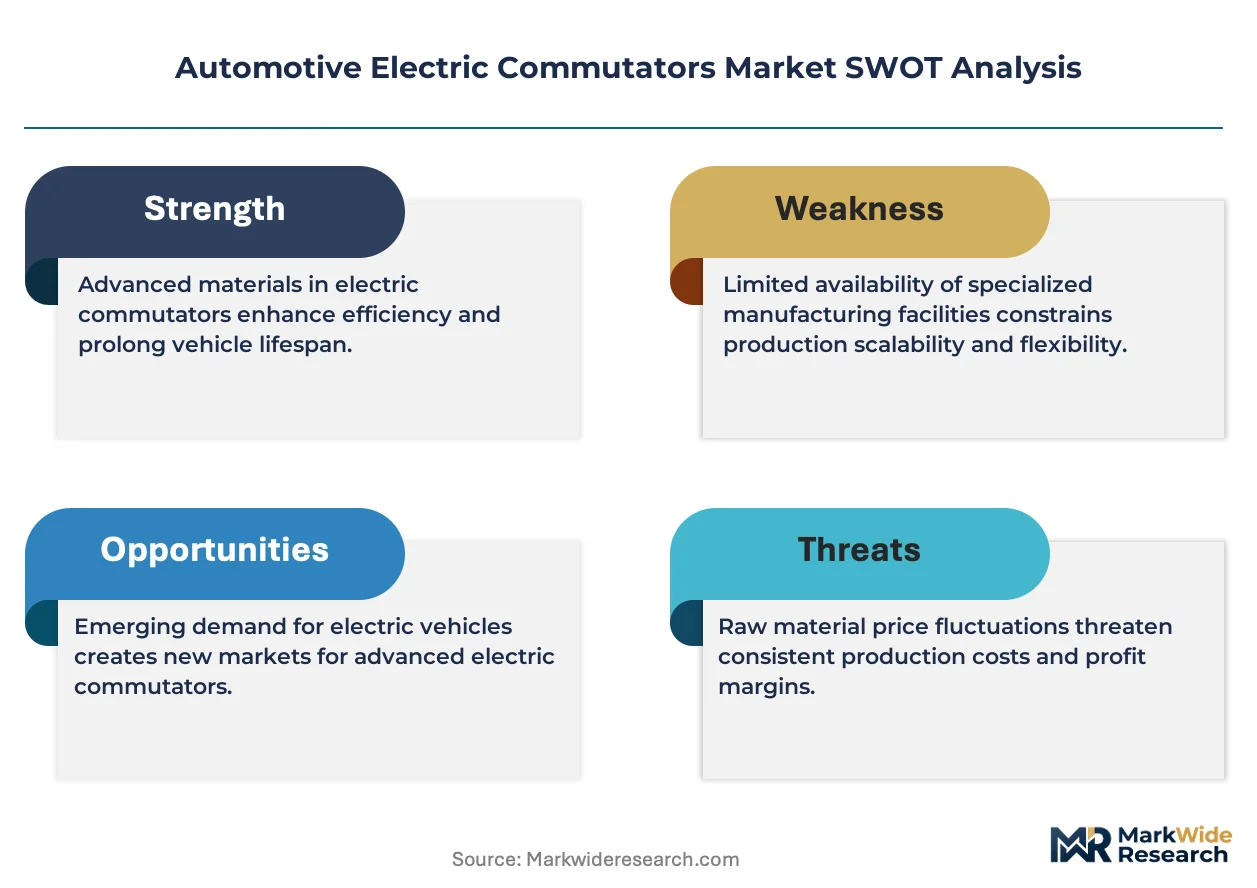
Powertrain electrification is compressing commutator specifications across voltage architectures, forcing suppliers to certify copper segment designs simultaneously for 12V auxiliary motors and 800V traction systems. This dual-certification burden concentrates procurement authority with Tier-1 motor integrators who can amortize validation costs across multiple OEM programs.
Growth Catalysts
- NHTSA fuel economy mandates:US corporate average fuel economy standards compel automakers to electrify starter-generators and HVAC systems, expanding high-efficiency commutator volumes in Detroit Three supply chains.
- Copper-silver composite plating:Advanced metallurgy extends brush life in high-RPM e-motor applications, enabling commutator retention in traction motor designs where solid-state alternatives remain cost-prohibitive.
- German e-axle production:Bosch and ZF Friedrichshafen anchor European motor manufacturing in Baden-Württemberg, creating localized demand for precision-milled commutator assemblies with validated REACH documentation.
Market Restraints
- Copper price volatility:London Metal Exchange copper futures expose commutator margins to commodity swings that OEM contracts rarely index beyond quarterly adjustments.
- Mica supply concentration:High-grade phlogopite mica for segment insulation concentrates in Indian and Madagascan mining operations, creating geopolitical exposure for thermal-rated commutator production.
- Solid-state motor controller diffusion:Silicon carbide inverter adoption enables brushless motor architectures that eliminate mechanical commutation entirely in premium EV segments.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive electronics attract commutator suppliers to establish copper bar fabrication capacity serving domestic EV motor demand.
- Remanufacturing channel expansion:Circular economy mandates under EU Green Deal create certified refurbishment revenue streams for starter motor commutators in European aftermarket channels.
- Polymer composite insulation:Mica-free segment construction reduces weight and enables automated assembly, converging with Chinese EV platform cost targets for high-volume motor production.
Industry Challenges
- Cross-voltage platform engineering:Simultaneous 12V and 800V motor design requirements fragment R&D resources and extend product validation timelines beyond typical OEM development cycles.
- REACH substance documentation:Full material disclosure for copper alloys and insulation binders demands specialized regulatory affairs capacity that smaller suppliers struggle to maintain.
- Brush-commutator interface modeling:Predictive wear algorithms for mixed-material contacts remain immature, forcing reliance on physical testing that compresses design iteration windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Commutators Market |
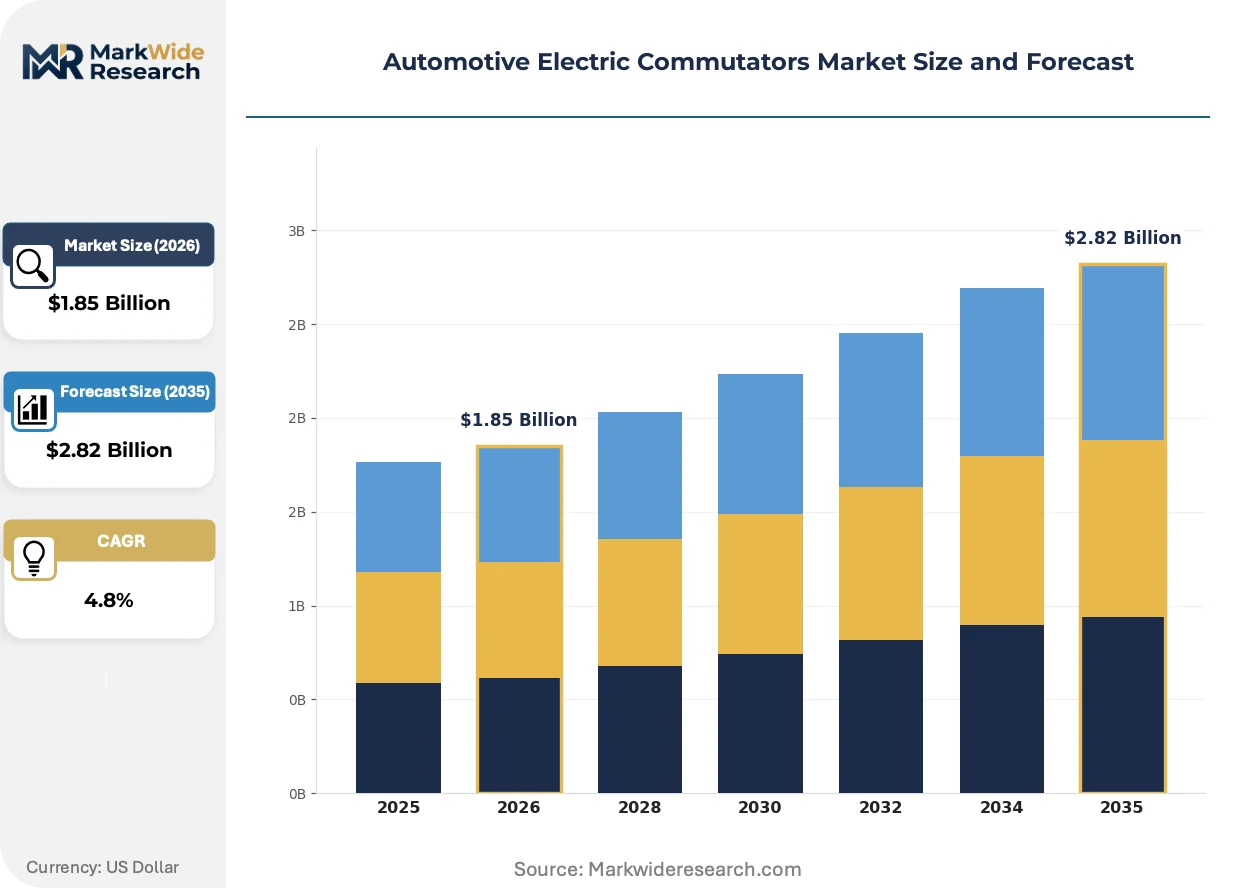
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Linear, Integral, Composite Material: Copper, Graphite, Aluminum, Silver Application: Electric Vehicles, Hybrid Vehicles, Motorcycles, Commercial Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Kolektor, Shenzhen Kaizhong Precision Technology Co., Ltd., Angu, SUGIYAMA SEISAKUSHO, Ningbo Sunico International Ltd., Zhejiang Greatwall Commutator Co., Ltd., Friedrich Nettelhoff GmbH & Co. KG, SUZHOU KEGU ELECTRIC APPLIANCE CO., LTD., TOLEDO COMMUTATOR COMPANY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Commutators Market Trends and Innovations
Material science advances and regulatory disclosure requirements are restructuring how commutator suppliers compete, with thermal performance and recyclability certification becoming primary differentiators alongside traditional cost and precision metrics.
Additive manufacturing is converging with copper metallurgy to enable complex internal cooling channel geometries in high-current commutator segments. Tier-1 motor suppliers in Stuttgart and Shanghai are piloting laser powder bed fusion for prototype traction motor components. This convergence is compressing lead times for custom segment geometries from months to weeks.
REACH Annex XVII restrictions on mica dust exposure are forcing insulation material transitions across European supply chains. ECHA enforcement actions against unregistered mica processors have accelerated polymer composite adoption. German OEMs now require third-party lifecycle assessments for all commutator insulation materials in new platform qualifications.
Direct sourcing from copper smelters is displacing traditional distributor relationships among high-volume motor manufacturers. BYD and Tesla have established captive supply agreements with Chilean and Zambian mining operations. This channel shift is most visible in Chinese EV production, where motor integrators seek price stability through long-term offtake contracts rather than spot market exposure.
Automotive Electric Commutators Market Segmentation
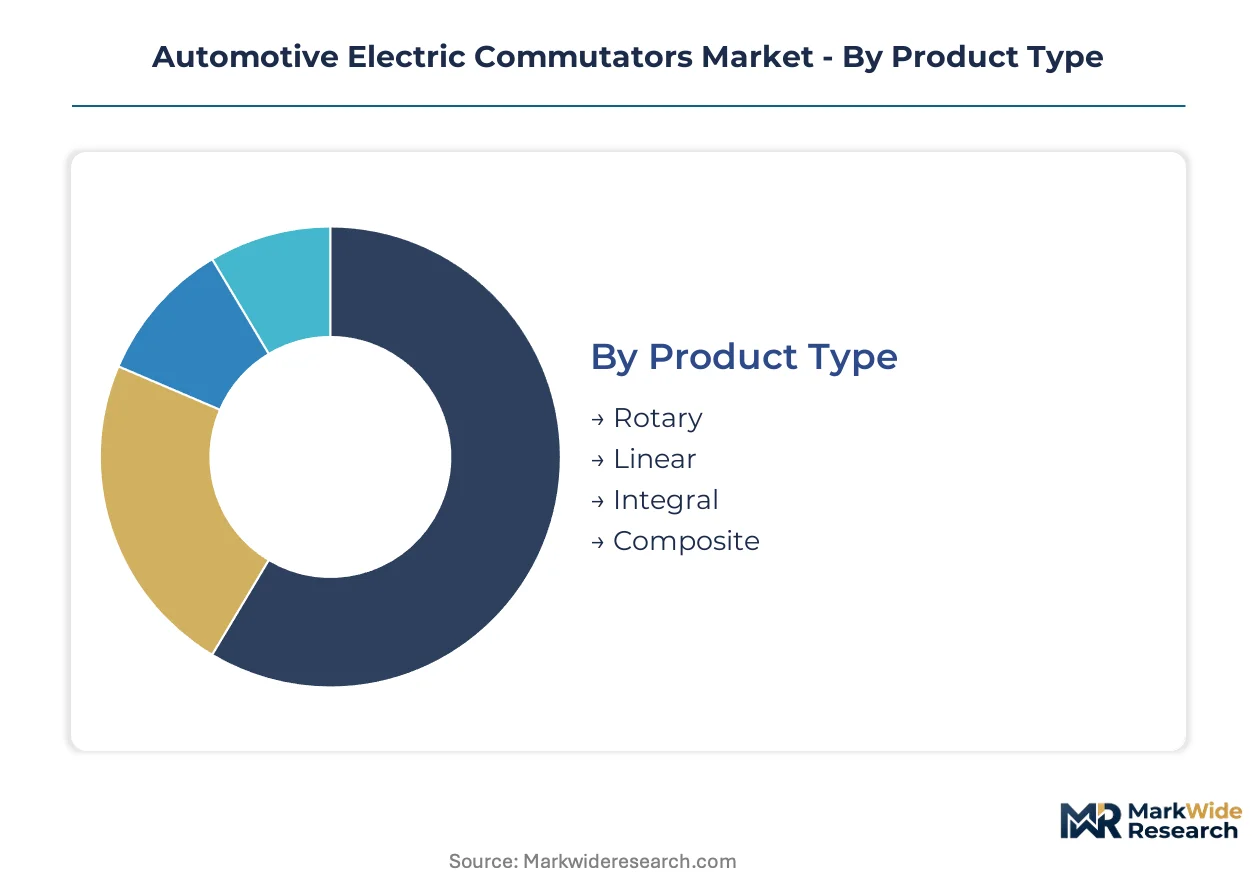
Commutator suppliers engineer distinct product architectures to match voltage requirements across starter motors, auxiliary systems, and traction applications. Material selection and end-user certification protocols fragment procurement patterns, forcing manufacturers to maintain parallel production lines for legacy and electrified platforms.
Product Type:
Supply concentration among German and Chinese motor integrators favors rotary and composite configurations with validated REACH documentation.
- Rotary:Cylindrical copper segment assemblies rotate against carbon brushes to reverse current in DC and universal motors. Starter motor demand in Detroit Three supply chains and German e-axle programs sustains volume dominance despite traction motor electrification pressures.
- Composite:Polymer-matrix segment construction replaces mica insulation with engineered thermoplastics, cutting weight and enabling automated winding. BYD and Tesla procurement teams in Shanghai and Shenzhen specify composite commutators for cost-optimized EV auxiliary motors.
- Linear:Flat-track copper bar arrangements serve limited linear actuator applications in power seat and sunroof mechanisms.
- Integral:Monolithic rotor-commutator castings reduce assembly steps for high-volume starter motor production in Indian and Brazilian vehicle plants.
Rotary configurations absorb the bulk of installed capacity; composite designs are expanding most quickly.
Material:
Cost tiering separates commodity copper grades from precious-metal plating required for high-RPM traction service.
- Copper:Electrolytic tough pitch and oxygen-free grades form the conductive backbone for 12V starter and HVAC blower motors. LME price volatility exposes margins, yet copper remains the default for 80% of automotive commutator tonnage due to conductivity and formability.
- Silver:Electroplated silver-copper composites deliver arc resistance and extended brush life in 800V traction motors spinning above 15,000 RPM. ZF Friedrichshafen and Bosch specify silver-plated segments for European premium EV platforms where replacement intervals must exceed 300,000 kilometers.
- Graphite:Molded carbon segments serve specialty low-current applications in motorcycle alternators and small-engine starters.
- Aluminum:Lightweight alloy segments trial in aerospace-derived auxiliary motors where every gram reduction counts against CAFE compliance calculations.
Copper commands the volume base; silver plating climbs the fastest as 800V architectures proliferate.
Application:
Customer type determines voltage specification, with OEM electrification roadmaps dictating commutator thermal and insulation ratings.
- Electric Vehicles:Traction motor commutators must withstand 800V potential and regenerative braking current reversals. Chinese NEV platforms in Ningbo and Hefei drive demand for liquid-cooled segment assemblies with integrated temperature sensing.
- Hybrid Vehicles:Belt-integrated starter-generator systems require compact commutators bridging 48V mild-hybrid and 400V full-hybrid architectures. German OEMs in Stuttgart and Wolfsburg qualify dual-voltage designs for modular powertrain strategies.
- Motorcycles:Small-displacement starter motors prioritize cost over longevity in Southeast Asian and Indian two-wheeler markets.
- Commercial Vehicles:Heavy-duty starter and HVAC systems in long-haul trucks demand enhanced brush life under severe duty cycles.
Hybrid applications anchor near-term volume; pure electric platforms show the steepest expansion trajectory.
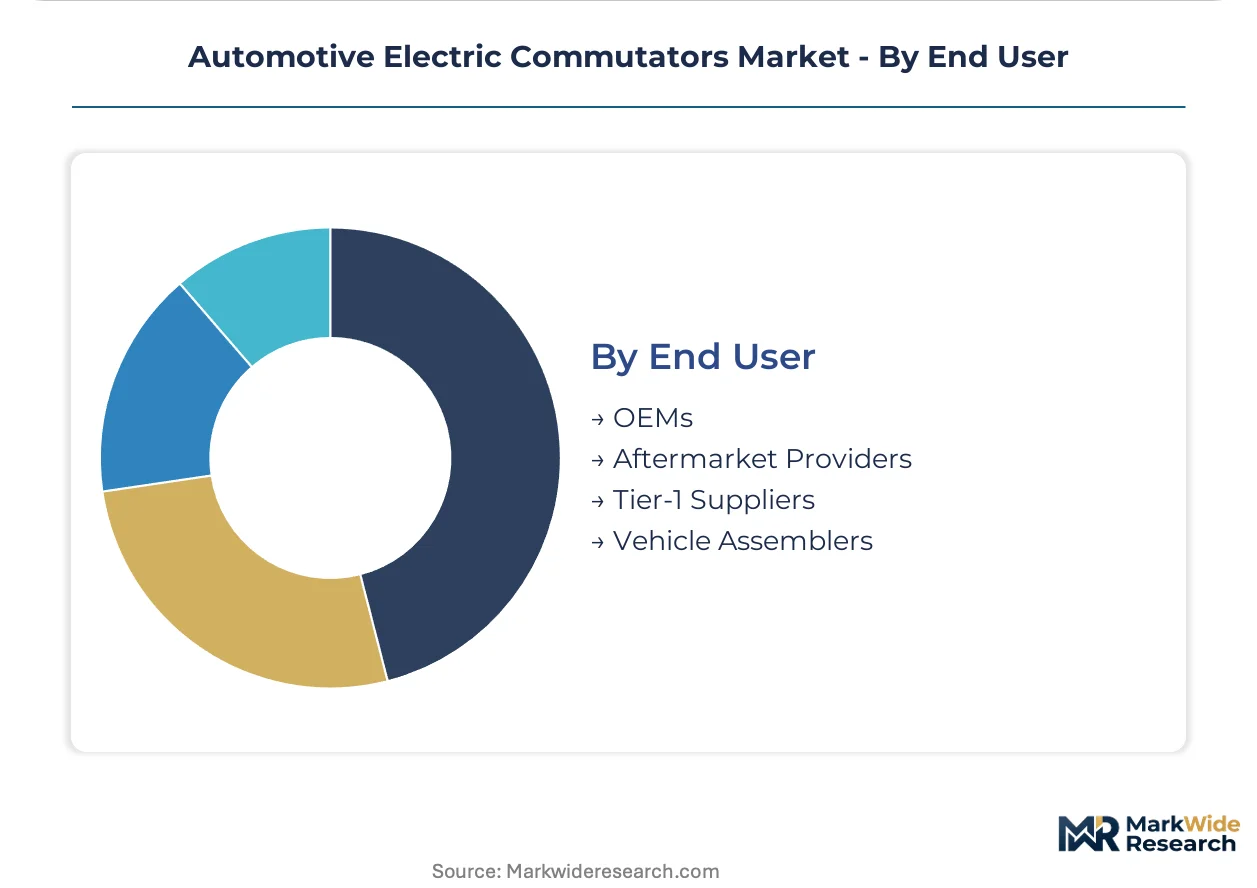
End User:
Procurement authority concentrates with Tier-1 motor integrators who amortize validation costs across multiple OEM programs.
- Tier-1 Suppliers:Bosch, Continental, and ZF Friedrichshafen source validated commutator assemblies for integrated e-axle and starter motor production. These firms dictate material specifications, insulation thermal ratings, and copper provenance documentation under REACH and RoHS frameworks.
- OEMs:Tesla and BYD exercise direct sourcing from Chilean and Zambian copper smelters, bypassing traditional distributor channels to lock in price stability for captive motor production.
- Aftermarket Providers:Remanufacturing specialists in European circular economy channels refurbish starter motor commutators under EU Green Deal certified refurbishment protocols.
- Vehicle Assemblers:Contract manufacturers in Mexico and Eastern Europe receive pre-assembled motor-commutator modules for final vehicle integration.
Tier-1 suppliers capture the dominant procurement share; OEM direct sourcing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and China while consumption spreads across electrified vehicle markets in North America and Europe. German e-axle manufacturing absorbs precision-milled commutator output. Chinese NEV platforms drive volume demand for copper segment assemblies.
Germany
Bosch and ZF Friedrichshafen anchor European e-axle production in Baden-Württemberg, generating concentrated demand for REACH-validated commutator assemblies. EU Green Deal circular economy mandates require full material disclosure for copper sourcing and mica insulation. Stuttgart motor integrators specify silver-copper composite segments for premium EV platforms exceeding 300,000 kilometer service intervals.
China
BYD and Tesla Gigafactory Shanghai procure liquid-cooled commutator assemblies for 800V traction motor platforms in Ningbo and Hefei. MIIT new energy vehicle mandates accelerate copper bar fabrication capacity expansion. Shenzhen and Suzhou host high-volume production of polymer-composite insulated segments serving cost-optimized domestic EV auxiliary motors.
United States
Detroit Three electrification programs expand high-efficiency commutator volumes for belt-integrated starter-generators and HVAC systems. NHTSA corporate average fuel economy standards compel auxiliary motor electrification across light-duty platforms. Michigan and Ohio manufacturing corridors concentrate Tier-1 motor integrator procurement authority for validated 12V and 48V commutator designs.
India
Domestic EV motor demand attracts copper bar fabrication investment under the PLI scheme for advanced automotive components. BIS certification requirements and DGFT import substitution policies elevate local content thresholds. Tamil Nadu and Gujarat automotive clusters incubate commutator supply capacity serving two-wheeler starter motor and emerging four-wheeler traction applications.
Japan
Hybrid vehicle production sustains compact commutator demand bridging 48V mild-hybrid and 400V full-hybrid architectures. METI carbon neutrality roadmaps mandate motor efficiency improvements across Toyota and Honda supply chains. Aichi Prefecture and Kansai region motor manufacturers qualify dual-voltage commutator designs for modular powertrain export programs.
Automotive Electric Commutators Market Competitive Landscape
The competitive structure tilts toward integrated motor-commutator bundlers with validated regulatory documentation. Tier-1 motor integrators concentrate procurement authority, forcing suppliers to amortize dual-voltage certification costs across multiple OEM programs. Three archetypes dominate: European precision specialists with REACH-compliant silver-copper composites, Chinese high-volume fabricators serving cost-driven NEV platforms, and Japanese hybrid-system component suppliers. Capacity expansion and backward integration into copper smelter relationships represent the dominant competitive moves.
Among European precision specialists, Friedrich Nettelhoff GmbH & Co. KG exemplifies the validated-documentation archetype for German OEM direct-current motor requirements. Chinese fabricators including Shenzhen Kaizhong Precision Technology Co., Ltd. and Zhejiang Greatwall Commutator Co., Ltd. occupy positions within high-volume copper segment production for domestic EV platforms. Kolektor represents the integrated bundling model with European manufacturing footprint serving hybrid starter-generator programs.
| Leading Market Players |
|---|
| Kolektor |
| Shenzhen Kaizhong Precision Technology Co., Ltd. |
| Angu |
| SUGIYAMA SEISAKUSHO |
| Ningbo Sunico International Ltd. |
| Zhejiang Greatwall Commutator Co., Ltd. |
| Friedrich Nettelhoff GmbH & Co. KG |
| SUZHOU KEGU ELECTRIC APPLIANCE CO., LTD. |
| TOLEDO COMMUTATOR COMPANY |
| Others |
Pricing and Supply Chain Analysis
Silver-copper composite certification tiers bifurcate procurement economics between German OEM traction motor programs and cost-optimized Chinese auxiliary motor platforms. This performance gap manifests in contract structures: Bosch and ZF Friedrichshafen lock in multi-year offtake agreements with REACH-validated European suppliers, while Shenzhen fabricators compete on spot-market copper bar pricing for domestic NEV volume.
Pricing Analysis
Margin tightening in commodity copper segments reflects LME price volatility that OEM contracts rarely index beyond quarterly adjustments. Three-tier pricing structure across premium, standard, and economy levels separates silver-plated 800V traction designs from electrolytic copper starter motor grades and polymer-composite auxiliary units. Cost-down pressure on standard-tier suppliers accelerates because Chinese motor integrators consolidate procurement authority around high-volume, single-source contracts. Tier-1 motor manufacturers show lowest price sensitivity given validation cost amortization requirements; aftermarket remanufacturers face highest sensitivity due to circular economy margin constraints.
Supply Chain Analysis
Skilled tool-and-die workforce availability in Stuttgart, Suzhou, and Detroit corridors anchors precision-milled commutator production capacity. Supply concentrates in Germany for REACH-certified silver-copper composites, China for high-volume copper bar fabrication, and India for emerging PLI-subsidized capacity. Raw material dependencies draw from Chilean and Zambian copper smelters, Indian and Madagascan high-grade phlogopite mica, and German-engineered polymer composite feedstock. Single-source vulnerability concentrates in mica insulation supply given ECHA enforcement actions against unregistered processors. Distribution runs through Tier-1 motor integrator direct procurement channels rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance documentation creates a cost-of-compliance moat that rewards validated suppliers with multi-year OEM platform lock-in while screening out smaller competitors lacking specialized regulatory affairs capacity.
For Market Incumbents: Cement platform engineering partnerships with Bosch and ZF Friedrichshafen by co-developing dual-voltage 12V/800V commutator architectures that fragment competitor R&D resources. Deepen backward integration into Chilean copper smelter relationships to neutralize LME price volatility exposure threatening margin stability in commodity segments. For New Entrants and Emerging Players: Tier-2 motor integrators in India's Tamil Nadu automotive cluster represent the most penetrable entry point given PLI scheme subsidies and BIS certification thresholds still below REACH complexity. Target remanufacturing channel partnerships with European circular economy certified refurbishment protocols as a regulatory-compliant go-to-market angle bypassing Tier-1 procurement concentration. For Investors and Strategic Acquirers: Re-rating potential sits with precision-milled silver-copper composite specialists given NHTSA fuel economy mandates and EPA tailpipe standards accelerating 800V traction motor adoption. Long-term viability favors suppliers with validated lifecycle documentation capacity under EU Green Deal frameworks. Watch silicon carbide inverter diffusion rates as the critical signal for mechanical commutation displacement risk in premium EV segments.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Voltage Platform Certification | REACH-validated 12V/800V designs lock in Bosch and ZF Friedrichshafen procurement authority across hybrid and electric architectures. |
| Copper Smelter Captive Supply | Direct offtake agreements with Chilean and Zambian mining operations neutralize LME price volatility compressing commodity segment margins. |
| Polymer Composite Insulation Transition | Mica-free segment construction aligns with ECHA enforcement trends and enables automated assembly for Chinese NEV cost targets. |
| Remanufacturing Channel Expansion | EU Green Deal certified refurbishment protocols create circular economy revenue streams in European aftermarket starter motor applications. |
| India PLI Manufacturing Footprint | Tamil Nadu and Gujarat copper bar fabrication capacity captures domestic EV motor demand under BIS and DGFT localization mandates. |
Research Methodology
Trade databases, SEC 10-K filings, and vehicle production registries formed the secondary backbone for volume and value estimation. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and copper smelter commercial managers combined with secondary validation through customs records and IHS Markit registration data. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated final market estimates.
Historical trendline analysis across installed base expansion, content-per-vehicle trajectories, and technology substitution patterns informed the projection framework. Segmentation dimensions modeled include product type, material grade, voltage architecture, propulsion system category, and regional production cluster. CAGRs derived from regression analysis of correlated automotive production forecasts and electrification penetration assumptions. Key inputs encompassed NHTSA compliance timelines, MIIT new energy vehicle mandates, and copper price scenario modeling.
Caveats apply where solid-state motor controller diffusion, mica supply disruptions, or REACH regulatory scope expansions could materially shift the outlook. Forecasts reflect assumptions regarding OEM electrification roadmap stability and Tier-1 supplier consolidation patterns. A small set of triggers—silicon carbide inverter adoption rates, ECHA enforcement intensity, and India PLI scheme disbursement velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Voice Coil Motor Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Frameless Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Positive Displacement Motor Market