
 Electric Propulsion Systems Market | 2026-2036
Electric Propulsion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Propulsion Systems Market Foresight
Modular thruster packaging is realigning buyer choice across the Electric Propulsion Systems landscape. ArianeGroup leverages European launch infrastructure to anchor integrated propulsion modules for institutional payloads. Boeing competes through sustained R&D intensity in high-power ion systems for deep-space missions. Northrop Grumman dominates satellite bus integration, controlling channel access for bundled electric propulsion configurations.
Electric propulsion systems generate thrust by accelerating ionized propellant through electrostatic or electromagnetic fields, achieving specific impulse values exceeding chemical rockets by factors of three to ten. These systems serve primary commercial and military purposes including orbit raising, station-keeping, and interplanetary trajectory correction. Hall Effect Thrusters occupy the largest installed base among type segments due to mature flight heritage and predictable degradation curves. Space Exploration applications represent the fastest-expanding demand pool as lunar and cislunar missions multiply. Government Agencies channel the dominant procurement volume, though Commercial Companies are capturing margin pools through service-based orbital transfer offerings.
FAA licensing requirements for commercial launch and reentry shape propulsion qualification timelines in the United States. ESA's Clean Space initiative and REACH chemical restrictions constrain propellant selection for European-manufactured systems. Japan's METI coordinates national space technology roadmaps that direct domestic thruster development priorities. Stakeholders must monitor evolving debris mitigation standards that will redefine minimum thrust capability thresholds for end-of-life disposal maneuvers.
Market Dynamics
Hall Effect Thruster flight heritage is consolidating procurement preferences across geostationary satellite operators, compressing qualification timelines for alternative electrostatic technologies and reshaping supplier tier structures.
Growth Catalysts
- ESA Clean Space Initiative:REACH chemical restrictions on hydrazine-based propellants are accelerating Hall Effect Thruster adoption for European institutional payloads.
- Cislunar Infrastructure Buildout:NASA Artemis program requirements for lunar orbit transfer vehicles are expanding addressable demand for high-power ion systems.
- End-of-Life Disposal Mandates:Debris mitigation standards from FCC licensing conditions are mandating minimum delta-v capabilities for commercial satellite deorbiting.
Market Restraints
- Xenon Supply Concentration:Noble gas extraction capacity concentrates in Russian and Qatari industrial gas facilities, creating propellant cost volatility.
- Power Processing Unit Complexity:High-voltage electronics reliability limitations extend qualification timelines for deep-space mission profiles.
- Krypton Substitution Economics:Lower-specific-impulse krypton thrusters trade performance for propellant availability, constraining high-energy mission applications.
Strategic Opportunities
- Japan METI Roadmap Alignment:National space technology directives are channeling domestic R&D funding toward compact thruster packaging for smallsat constellations.
- Orbit-Transfer-as-a-Service:Commercial companies are capturing margin pools by bundling electric propulsion with launch brokering for geostationary orbit insertion.
- Gridded Ion-Hall Hybrid Architectures:Converging electrostatic and electromagnetic acceleration mechanisms are opening performance envelopes for interplanetary cargo missions.
Industry Challenges
- Plasma Physics Talent Scarcity:Specialized expertise in discharge chamber modeling and erosion prediction limits thruster development team scaling.
- FAA Qualification Timelines:Commercial launch licensing requirements for novel propulsion configurations extend time-to-revenue for system integrators.
- Spacecraft Bus Integration Complexity:Thermal management and power distribution interface standards vary across satellite manufacturers, fragmenting module design economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Propulsion Systems Market |
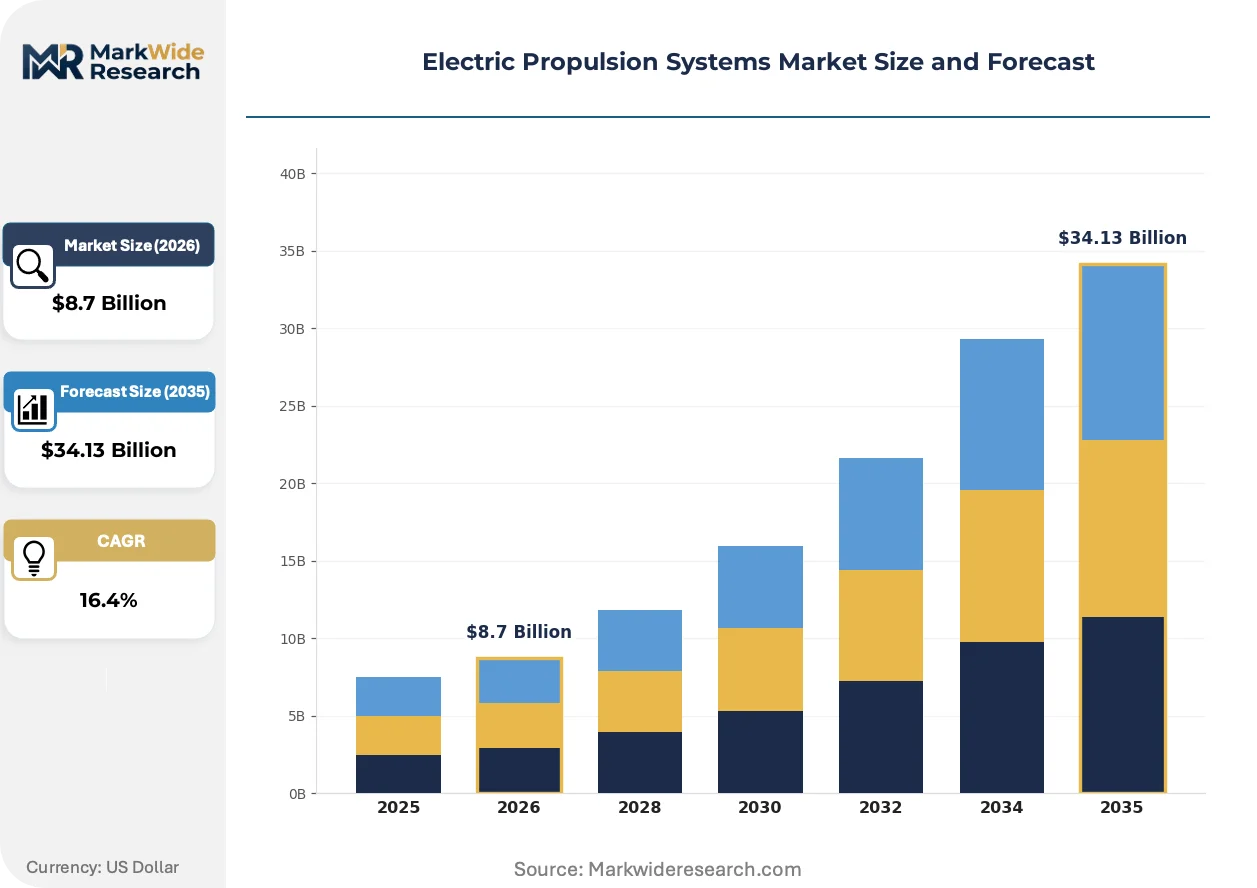
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Ion Thrusters, Hall Effect Thrusters, Pulsed Plasma Thrusters, Electrothermal Thrusters Application: Aerospace, Maritime, Suburban Transportation, Space Exploration Technology: Electric Motors, Supercapacitors, Fuel Cells, Energy Storage Systems End User: Government Agencies, Commercial Companies, Research Institutions, Private Enterprises |
| Companies Covered | ArianeGroup, Boeing, Lockheed Martin, Northrop Grumman, Airbus, Busek, Aerojet Rocketdyne, L3Harris Technologies, Bellatrix Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Propulsion Systems Market Shifts & Advancements
Propulsion architecture choices are narrowing as flight-proven configurations capture procurement budgets, while regulatory chemistry restrictions and service-based business models restructure value capture mechanisms.
Magnetic shielding techniques for Hall Effect Thrusters are consolidating erosion mitigation strategies across commercial satellite programs. Boeing and institutional buyers in France are prioritizing magnetically shielded designs for extended station-keeping missions. This technology is consolidating supplier differentiation around lifetime predictability rather than specific impulse performance alone.
REACH chemical restrictions from ECHA are prohibiting hydrazine monopropellant systems for European-manufactured spacecraft. ESA procurement mandates now require green propulsion alternatives for all new institutional payloads. Satellite bus integrators in Germany and Italy are responding by qualifying Hall Effect Thruster modules for orbit raising and station-keeping functions.
Service-based orbital transfer offerings are unbundling propulsion procurement from satellite manufacturing. Commercial operators in the United States are contracting dedicated orbital transfer vehicles rather than integrating thrusters directly onto payload spacecraft. This pattern concentrates most visibly among geostationary communications satellite operators seeking to defer capital expenditure to operational expenditure structures.
Electric Propulsion Systems Market Segmentation
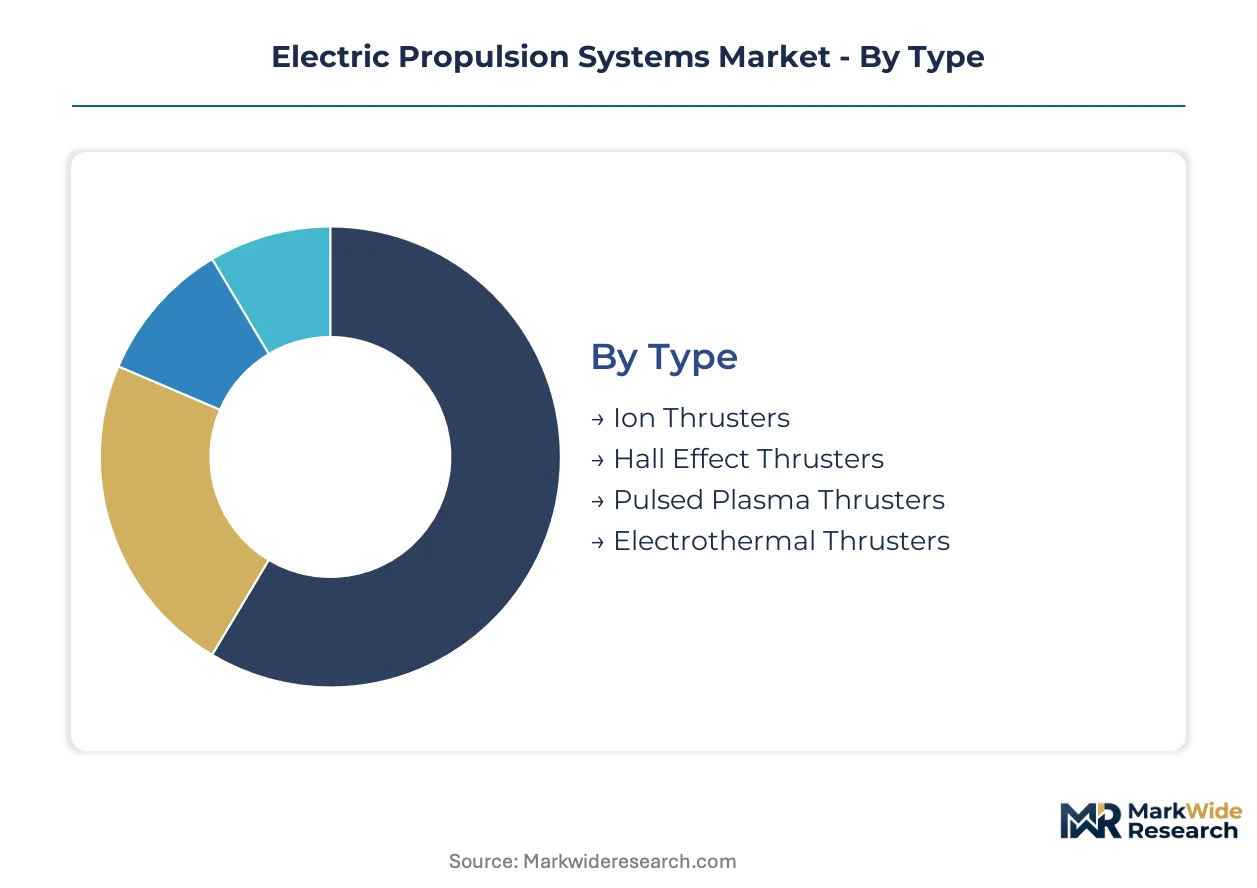
Segmentation in electric propulsion systems reveals how technology maturity and procurement authority reshape competitive access. Suppliers must calibrate offerings across standalone thruster sales, integrated satellite bus packages, and full orbital transfer services.
Type:
Integration depth varies sharply by thruster architecture, with some configurations optimized for embedded satellite bus mounting and others designed for standalone orbital transfer vehicle deployment.
- Hall Effect Thrusters:These electromagnetic devices accelerate ions using a radial magnetic field and axial electric field, achieving specific impulse values between 1500 and 2000 seconds. Procurement concentrates among geostationary satellite operators in the United States and France, driven by ESA Clean Space mandates eliminating hydrazine alternatives. Flight heritage spanning multiple decades compresses qualification timelines and locks in supplier relationships.
- Ion Thrusters:Gridded electrostatic accelerators extract ions through screen electrodes, delivering higher specific impulse than Hall designs but requiring more complex power processing. NASA Artemis program requirements for lunar orbit transfer vehicles are channeling development funding toward high-power variants, with Boeing sustaining R&D intensity for deep-space cargo missions.
- Pulsed Plasma Thrusters:Ablative solid propellant systems generate thrust through rapid electrical discharge, suited for precise attitude control on small satellites. Japan's METI roadmap directs domestic manufacturers toward compact packaging for constellation applications.
- Electrothermal Thrusters:Resistojet and arcjet designs heat propellant electrically before expansion, occupying a performance tier between chemical and electrostatic systems. Limited adoption reflects specific impulse constraints against competing technologies.
Volume placements concentrate in Hall Effect Thrusters; the faster expansion belongs to Ion Thrusters.
Application:
Cost tier stratification separates capital-intensive deep-space programs from operational expenditure models in commercial satellite services.
- Space Exploration:Interplanetary trajectory correction, lunar orbit insertion, and cislunar infrastructure buildout demand high-power systems with decade-plus operational lifetimes. NASA procurement anchors this segment, with ESA contributing institutional funding for Mars sample return architectures.
- Aerospace:Satellite station-keeping and orbit raising constitute the installed revenue base, with geostationary operators in the United States contracting dedicated orbital transfer vehicles to defer capital expenditure.
- Maritime:Electric propulsion for surface vessels operates on entirely different physics—superconducting motors driving fixed-pitch propellers—sharing only the "electric" descriptor with space applications.
- Suburban Transportation:Urban air mobility concepts and regional electric aircraft development remain pre-commercial, with FAA certification timelines extending qualification requirements.
Revenue gravity centers in Aerospace; the steepest expansion trajectory sits with Space Exploration.
Technology:
Maturity gradients separate flight-proven power processing from emerging energy storage architectures still seeking space qualification.
- Electric Motors:High-voltage Hall thruster discharge chambers and ion extraction grids depend on precision-wound magnetic circuits and thermal management systems. Supplier differentiation concentrates in lifetime predictability and erosion mitigation.
- Energy Storage Systems:Lithium-ion and emerging solid-state battery configurations buffer solar array output for pulsed thruster firing. Power processing unit complexity limits adoption for deep-space profiles.
- Supercapacitors:Rapid charge-discharge cycles suit pulsed plasma thruster applications, though energy density constraints restrict operational duration.
- Fuel Cells:Regenerative systems for crewed spacecraft life support overlap partially with propulsion power demands, creating dual-use procurement economies.
Procurement volume clusters in Electric Motors; Energy Storage Systems are climbing the fastest.
End User:
Customer type determines contract structure, with government agencies demanding cost-plus development terms and commercial operators seeking fixed-price service agreements.
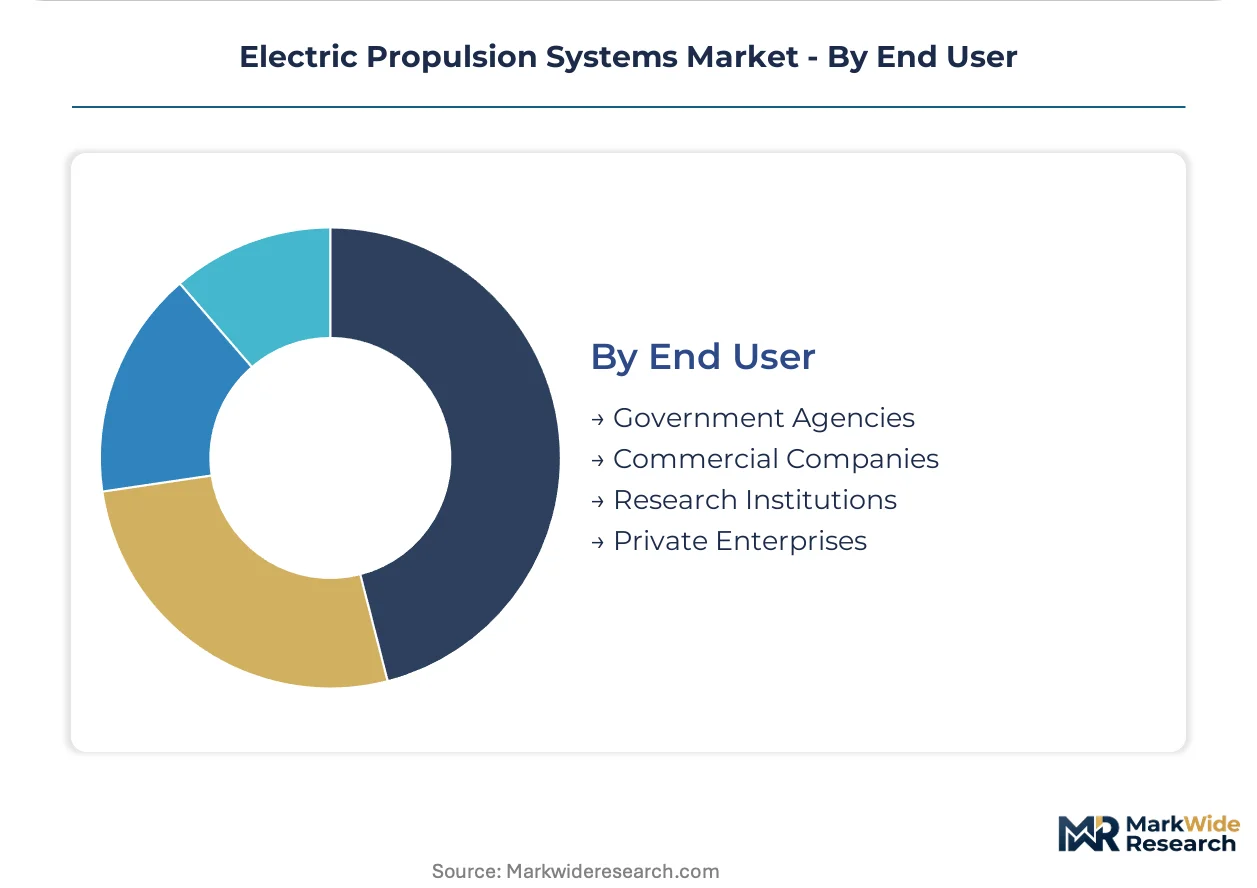
- Government Agencies:NASA, ESA, and JAXA channel dominant procurement volume through multiyear supply contracts, anchoring supplier revenue visibility. FCC licensing conditions for debris mitigation now mandate minimum delta-v capabilities, tightening technical specifications.
- Commercial Companies:Geostationary satellite operators and emerging orbital transfer service providers capture margin pools through bundled offerings. Northrop Grumman's satellite bus integration controls channel access for bundled configurations.
- Research Institutions:University and laboratory thruster development programs qualify novel electrostatic and electromagnetic concepts, feeding technology pipelines for operational systems.
- Private Enterprises:Venture-backed constellation operators and cislunar logistics startups represent emerging demand with limited flight heritage requirements.
Contract value concentrates in Government Agencies; Commercial Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thruster manufacturing concentrates in established aerospace clusters while consumption spreads across satellite operator hubs and institutional procurement centers. Production capacity anchors in defense-integrated supply chains near Washington DC, Toulouse, and Tokyo. Demand fragmentation across geostationary operators, constellation ventures, and government missions shapes regional specialization patterns.
United States
NASA Artemis procurement and FCC debris mitigation mandates anchor institutional demand for high-power ion systems. FAA commercial launch licensing shapes qualification timelines for novel propulsion configurations. Los Angeles aerospace corridor hosts integrated satellite bus manufacturers bundling Hall thruster modules for geostationary operators.
France
ESA Clean Space initiative and REACH chemical restrictions eliminate hydrazine alternatives for European institutional payloads. ArianeGroup leverages Guiana Space Centre access to anchor integrated propulsion modules for institutional missions. Toulouse aerospace cluster concentrates flight-qualified Hall Effect Thruster production for export markets.
Japan
METI national space technology roadmaps direct domestic R&D toward compact thruster packaging for smallsat constellations. JAXA cislunar logistics requirements expand addressable demand for high-efficiency systems. Nagoya industrial corridor hosts precision magnetic circuit suppliers feeding discharge chamber manufacturers.
Germany
Debris mitigation standards from national space legislation mandate minimum delta-v capabilities for commercial satellite licensing. ESA procurement through German institutional channels sustains gridded ion thruster development programs. Munich-Stuttgart aerospace belt concentrates power processing unit engineering talent for deep-space mission profiles.
United Kingdom
UK Space Agency funding for in-orbit servicing demonstrations creates demand for precision maneuvering thrusters. National Space Strategy prioritizes sovereign launch capability development with integrated propulsion requirements. Harwell Space Cluster hosts emerging orbital transfer service providers bundling electric propulsion with launch brokering.
Electric Propulsion Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology maturity tiers. Market structure consolidates around defense-integrated primes controlling satellite bus integration channels, while specialist thruster houses capture niche performance segments. Three archetypes dominate: institutional primes bundling propulsion with spacecraft platforms, component specialists supplying discharge chambers and power electronics, and emerging service operators unbundling orbital transfer from satellite manufacturing. Competitive moves concentrate on strategic partnerships for flight heritage accumulation and geographic expansion through ESA and JAXA supply chain qualification.
Within the institutional prime tier, ArianeGroup and Boeing occupy positions reflecting European launch infrastructure integration and sustained R&D intensity in high-power systems respectively. Northrop Grumman anchors satellite bus integration dominance, controlling channel access for bundled electric propulsion configurations. Among specialist suppliers, Busek and Bellatrix Aerospace represent focused pure-play archetypes concentrating on thruster development rather than platform integration. L3Harris Technologies sits within the diversified defense conglomerate segment, leveraging cross-divisional electronics capabilities for power processing unit supply.
| Leading Market Players |
|---|
| ArianeGroup |
| Boeing |
| Lockheed Martin |
| Northrop Grumman |
| Airbus |
| Busek |
| Aerojet Rocketdyne |
| L3Harris Technologies |
| Bellatrix Aerospace |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in Russia and Qatar anchor xenon extraction capacity, concentrating propellant pricing power while Hall Effect Thruster manufacturers face procurement volatility that reshapes contract structures toward long-term offtake agreements.
Pricing Analysis
Cost-down pressure on flight-qualified systems accelerates because krypton substitution economics trade performance for propellant availability. Three-tier pricing structure across heritage-proven, newly-qualified, and experimental configurations separates NASA Artemis-tier missions from geostationary station-keeping and emerging constellation applications. Price differentiation hinges on flight heritage certification and power processing unit complexity. Commercial satellite operators exhibit highest price sensitivity; deep-space institutional buyers prioritize lifetime predictability over unit cost.
Supply Chain Analysis
Refurbishment flows for Power Processing Units remain underdeveloped, constraining circular economy participation as erosion-worn discharge chambers require replacement rather than remanufacturing. Supply concentrates in the United States, France, and Japan where defense-integrated aerospace clusters feed precision magnetic circuit fabrication. Raw material dependencies center on high-purity xenon, ceramic discharge chamber substrates, and radiation-hardened electronics. Single-source vulnerability in noble gas extraction creates tariff-exposed chokepoints. Distribution runs through satellite bus integrators bundling thruster modules with platform procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics intensify as thruster houses pursue captive xenon processing and Power Processing Unit in-house production to defend margin pools against propellant cost volatility.
For Market Incumbents: Extend flight heritage accumulation through ESA and JAXA supply chain qualification to lock out emerging electrostatic alternatives. Deepen backward integration into noble gas processing infrastructure in Qatar and domestic extraction partnerships. Control channel access by bundling Hall thruster modules with satellite bus platforms against orbital-transfer-as-a-service unbundling. For New Entrants and Emerging Players: The premium-to-economy pricing gap in smallsat constellation applications creates entry space for compact Pulsed Plasma Thruster packaging. Target Japan's METI-funded domestic R&D programs for technology validation pathways. Pursue gridded ion-Hall hybrid architectures as a performance-differentiated wedge against established Hall Effect heritage. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play thruster specialists with ESA Clean Space qualification completion in France and Germany. Five-to-ten year viability hinges on cislunar infrastructure contract capture beyond geostationary replacement demand. Monitor NASA Artemis lunar orbit transfer vehicle procurement awards as inflection signal for high-power ion system addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Shielding Technology Deployment | Boeing and ArianeGroup prioritize magnetically shielded Hall designs for extended station-keeping lifetime predictability. |
| Xenon Supply Agreement Structuring | Long-term offtake contracts with Russian and Qatari industrial gas facilities mitigate propellant cost volatility exposure. |
| Orbit-Transfer-as-a-Service Launch | Northrop Grumman leverages satellite bus integration dominance to bundle electric propulsion with launch brokering for geostationary operators. |
| Gridded Ion-Hall Hybrid Development | Converging electrostatic and electromagnetic acceleration mechanisms opens performance envelopes for NASA Artemis cargo missions. |
| REACH Compliance Certification | ESA procurement mandates for green propulsion alternatives eliminate hydrazine competitors and accelerate Hall Effect Thruster adoption. |
Research Methodology
Multi-period observation of NASA procurement awards, ESA Clean Space implementation timelines, and FCC debris mitigation licensing conditions anchored the trend analysis, supplemented by interviews with satellite bus integration engineers, Hall thruster discharge chamber specialists, power processing unit designers, and geostationary operator procurement directors. Secondary validation drew from ESA public procurement databases, FAA commercial launch licensing records, JAXA technology roadmap publications, and METI space industry policy filings. Bottom-up thruster unit shipment estimates and top-down addressable market sizing were triangulated against institutional budget authorization documents.
The input-output matrix mapped Power Processing Unit complexity, specific impulse performance tiers, and flight heritage certification status against procurement authority segmentation across government agencies and commercial operators. Modeled dimensions spanned thruster architecture type, application mission profile, end-user contract structure, and regional regulatory cluster. CAGRs were derived from multivariate regression against historical institutional procurement cycles and emerging constellation deployment schedules. Forecast inputs incorporated REACH chemical restriction phase-out timelines and Artemis program milestone dependencies.
Inputs from ESA and JAXA procurement disclosure protocols were available through the study window; gaps in classified military satellite propulsion specifications introduce uncertainty bands around defense-integrated demand estimates. Forecasts reflect documented assumptions regarding xenon supply continuity and debris mitigation standard adoption velocity. Material deviation in Russian noble gas export licensing or FCC licensing condition enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Frameless Motor Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Torque Motor Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Automotive Hub Motors Market
Electric Motor
Air Motor Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Hub Drive Motor Market
Electric Motor
High Speed Motor Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Large Synchronous Motor Market