
 Optical Microcontrollers Market | 2026-2036
Optical Microcontrollers Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Microcontrollers Market Analytics
The capability gap between photonic foundry investments and legacy electronic-only fabrication is unwinding competitive hierarchies. Texas Instruments leverages its analog-to-optical signal conditioning portfolio to sustain design wins in industrial sensing. STMicroelectronics anchors European supply through its integrated photonics pilot line in Crolles. Infineon Technologies differentiates via silicon carbide and gallium nitride co-packaging with optical interfaces for automotive lidar.
Optical microcontrollers merge CMOS electronic logic with photonic waveguide structures, typically operating at 850 nm to 1550 nm wavelengths for low-loss fiber coupling and achieving modulation rates exceeding 50 Gbps per channel. These devices serve telecommunications, industrial automation, and aerospace systems requiring immunity to electromagnetic interference and massive parallel data throughput. Hybrid controllers lead current revenue as telecom operators retrofit existing electronic racks with pluggable optical engines. Photonic circuits represent the fastest-expanding technology segment, driven by co-packaged optics demand in AI training clusters. Sensing applications command premium margins due to aerospace qualification requirements and automotive functional safety certifications.
The FCC governs laser safety classifications and electromagnetic emissions for optical controllers deployed in US telecommunications infrastructure, while the EU AI Act imposes transparency requirements on autonomous systems using optical sensing arrays. China's MIIT enforces GB standards for optical interconnect reliability in data center equipment, creating divergent certification burdens for multinational suppliers. Stakeholders must monitor whether regional standards for photonic integration converge or fragment as sovereign technology strategies harden.
Market Dynamics
The transition from pluggable optical modules to co-packaged optics in AI training clusters is compressing design cycles and forcing foundry partnerships that previously operated on decade-long horizons.
Growth Catalysts
- MIIT GB Standards:China's mandatory reliability testing for data center optical interconnects is accelerating domestic procurement of qualified controllers.
- Silicon Photonics Foundry Capacity:South Korea's photonics corridor expansion is lowering wafer costs for multi-channel transceiver designs.
- Automotive Lidar Integration:Functional safety certifications under ISO 26262 are creating specification pull from tier-one sensor suppliers.
Market Restraints
- Indium Phosphide Supply Concentration:Laser source substrate production clusters in East Asian foundries create single-source vulnerability for 1550 nm designs.
- EU F-Gas Regulation:Restrictions on fluorinated cooling gases for high-power laser assemblies are forcing thermal management redesigns.
- Electronic-Photonic Packaging Yield:Hybrid die bonding complexity keeps mature-node controllers cost-competitive below 400 Gbps.
Strategic Opportunities
- Co-Packaged Optics in AI Clusters:The shift from pluggable to on-board optical engines opens socket opportunities at switch ASIC proximity.
- India's PLI Scheme:Domestic manufacturing incentives for telecom equipment are attracting optical component assembly investments.
- Aerospace EMI Immunity:Optical isolation requirements in satellite and avionics systems command qualification premiums over copper alternatives.
Industry Challenges
- Photonic Design Talent Scarcity:The intersection of CMOS layout and waveguide simulation expertise remains concentrated in academic and national lab pipelines.
- Multi-Jurisdiction Certification Burden:Concurrent FCC laser safety, ECHA substance declarations, and MIIT reliability testing extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Microcontrollers Market |
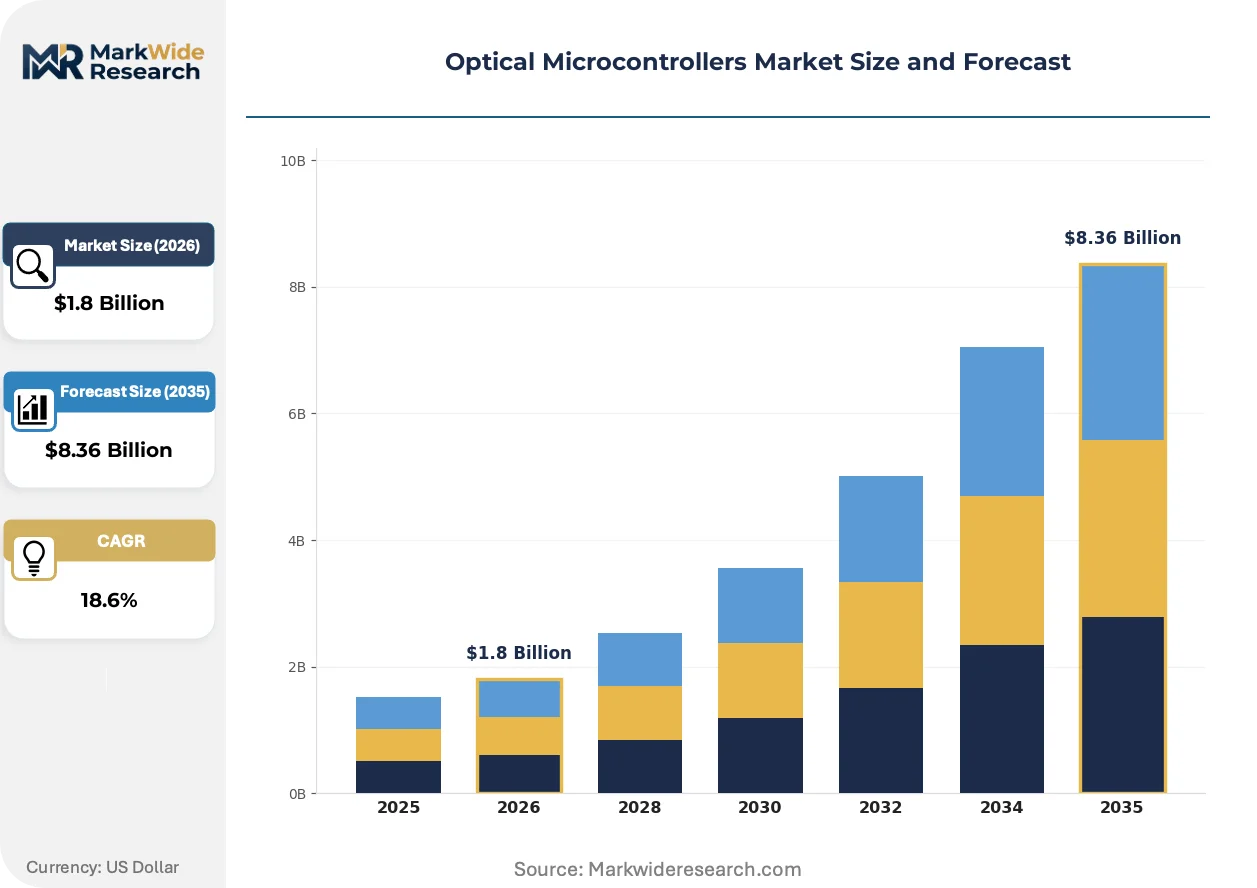
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Controllers, Analog Controllers, Hybrid Controllers, Integrated Controllers Technology: Optical Interconnects, Photonic Circuits, Laser Diodes, Sensors End User: Telecommunications, Consumer Electronics, Industrial Automation, Aerospace Application: Data Transmission, Signal Processing, Sensing, Imaging |
| Companies Covered | Microchip Technology, Texas Instruments, STMicroelectronics, Infineon Technologies, Renesas Electronics Corporation, NXP Semiconductors, Maxim Integrated, Analog Devices, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Microcontrollers Market Evolving Landscape
Photonic integration is crossing a threshold where electronic control logic and optical signal paths merge at the die level, eliminating the module-board boundary that defined prior generations.
Silicon photonics process platforms are bifurcating between foundry-standard silicon-on-insulator flows for high-volume transceivers and specialized indium phosphide-silicon nitride hybrids for sensing applications requiring wider wavelength tuning. Telecom operators are standardizing on the silicon platform for 800 Gbps datacenter interconnects. Automotive lidar suppliers are absorbing the compound semiconductor premium for 1550 nm eye-safe operation.
The EU AI Act transparency requirements for autonomous sensing systems are forcing optical array manufacturers to document training data provenance and decision logic. Industrial automation vendors serving European markets must now maintain algorithm audit trails alongside hardware reliability records. Machine vision integrators in Germany and France are selecting controllers with pre-certified documentation packages to accelerate deployment timelines.
Buyers in hyperscale datacenter procurement are consolidating optical controller suppliers to capture volume pricing while demanding open-source photonic design kits for second-source qualification. This concentration is displacing the fragmented module vendor landscape that characterized 100 Gbps and 400 Gbps generations. The shift is most visible in US and Chinese cloud operator RFPs specifying multi-source compatible optical engine form factors.
Optical Microcontrollers Market Segmentation
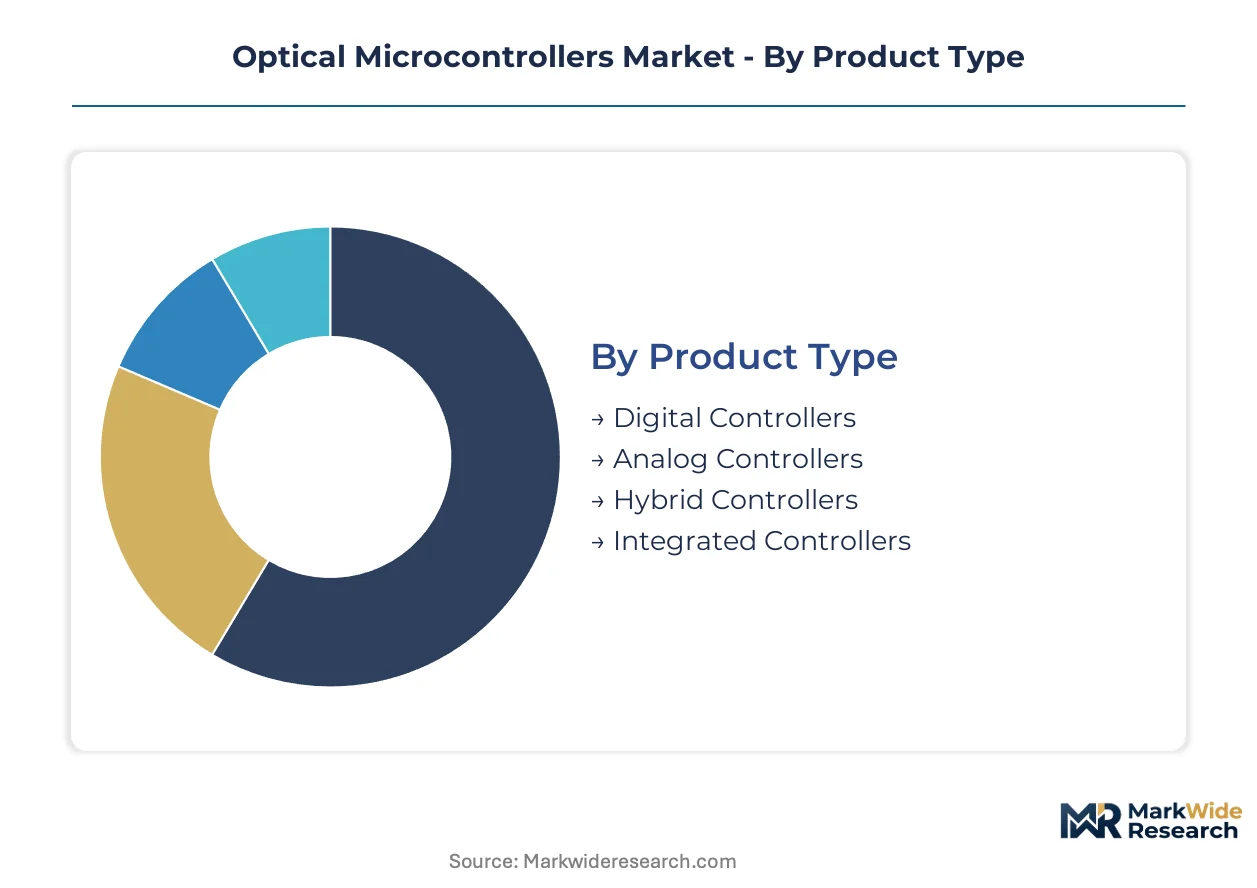
Segmentation in optical microcontrollers reveals how electronic-photonic integration depth determines channel strategy. Product architecture dictates whether devices flow through telecom equipment OEMs, automotive tier-ones, or direct-to-fabless design houses.
Product Type:
Channel mix splits sharply between retrofit-friendly pluggable formats and co-packaged solutions destined for switch ASIC proximity.
- Hybrid Controllers:These devices combine CMOS logic with photonic waveguide structures at the substrate level, enabling 50+ Gbps modulation per channel while maintaining backward compatibility with existing electronic racks. Demand concentrates in North American hyperscale datacenter operators retrofitting 400 Gbps infrastructure. Telecom procurement teams specify hybrid controllers to bridge legacy copper backplanes with emerging optical fabrics.
- Integrated Controllers:Full die-level merger of electronic and photonic processing eliminates module-board boundaries entirely. South Korean photonics foundries are absorbing the majority of wafer starts for this architecture. Co-packaged optics demand in AI training clusters is compressing design cycles and forcing foundry partnerships.
- Digital Controllers:Pure electronic signal processing with optical I/O interfaces serves cost-sensitive industrial automation segments.
- Analog Controllers:Continuous-wave laser modulation for sensing applications commands premium margins in aerospace qualification pipelines.
By volume, Hybrid Controllers lead. By growth pace, Integrated Controllers are expanding most quickly.
Technology:
Cost tier stratification separates high-volume silicon photonics from compound semiconductor premiums for specialized wavelengths.
- Photonic Circuits:Silicon-on-insulator process platforms achieve wafer-scale integration of waveguides, modulators, and detectors at 1310-1550 nm wavelengths. China's MIIT GB standards for optical interconnect reliability are accelerating domestic procurement of qualified photonic circuits. AI cluster operators specify these devices for 800 Gbps datacenter interconnects.
- Sensors:Indium phosphide-silicon nitride hybrids enable wider wavelength tuning for FMCW lidar and spectroscopic applications. Automotive functional safety certifications under ISO 26262 are creating specification pull from German and Japanese tier-one suppliers. Eye-safe 1550 nm operation absorbs the compound semiconductor cost premium.
- Optical Interconnects:Pluggable transceiver modules retain share below 400 Gbps where electronic-photonic packaging yield challenges persist.
- Laser Diodes:Discrete pump sources and seed lasers supply industrial cutting and medical equipment markets.
Photonic Circuits dominate unit shipments. Sensors command the steepest expansion trajectory.
End User:
Application maturity determines margin structure, with aerospace qualification pipelines sustaining premium pricing against telecom volume plays.
- Telecommunications:Datacenter interconnect and metro fiber upgrades drive the largest addressable volume. FCC laser safety classifications and electromagnetic emissions rules govern US infrastructure deployment. Open-source photonic design kit demands from hyperscale buyers are consolidating supplier relationships.
- Aerospace:Satellite optical inter-satellite links and avionics data buses require immunity to electromagnetic interference. EU AI Act transparency requirements for autonomous sensing systems force documentation of training data provenance alongside hardware reliability records.
- Industrial Automation:Machine vision and precision positioning systems absorb controllers with pre-certified documentation packages to accelerate European deployment timelines.
- Consumer Electronics:AR/VR proximity sensing and biometric applications remain nascent with stringent cost constraints.
Telecommunications generates the highest absolute revenue. Aerospace delivers the strongest margin expansion.
Application:
Customer type bifurcation separates high-volume datacenter operators from specialized integrators serving sensing and imaging niches.
- Data Transmission:Parallel optical links for switch-to-switch and rack-to-rack connectivity represent the primary volume application. India's PLI scheme for telecom equipment manufacturing is attracting optical component assembly investments. Co-packaged optics migration is displacing legacy pluggable module sockets.
- Sensing:Lidar, spectroscopy, and structural health monitoring command qualification premiums. EU F-Gas Regulation restrictions on fluorinated cooling gases are forcing thermal management redesigns for high-power laser assemblies.
- Signal Processing:Analog-to-optical conversion for RF-over-fiber and phased array antennas serves defense and telecommunications infrastructure.
- Imaging:Optical coherence tomography and machine vision systems require precise wavelength stability and low noise floors.
Data Transmission anchors volume. Sensing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in optical microcontrollers tilt heavily toward East Asian manufacturing clusters, with design activity concentrated in North American and European R&D centers. Trade balances reflect photonics foundry capacity investments outpacing domestic controller design capabilities across multiple jurisdictions.
United States
Hyperscale datacenter operators in Northern Virginia and Oregon drive procurement of 800 Gbps optical interconnects. FCC laser safety classifications and electromagnetic emissions rules govern infrastructure deployment timelines. Silicon photonics startups cluster around Boston and San Jose, partnering with South Korean foundries for wafer fabrication.
China
Domestic cloud operators and telecom infrastructure buildouts absorb the largest regional volume of hybrid controllers. MIIT enforces GB standards for optical interconnect reliability, accelerating procurement of qualified domestic and foreign suppliers. The Yangtze River Delta hosts photonics packaging facilities serving both local demand and re-export markets.
South Korea
Memory semiconductor manufacturers extend into photonics foundry services, lowering wafer costs for multi-channel transceiver designs. Government-backed research institutes anchor the photonics corridor between Seoul and Daejeon. Samsung and SK Hynix adjacent suppliers are absorbing majority wafer starts for integrated controller architectures.
Germany
Automotive lidar tier-ones in Bavaria and Baden-Württemberg specify controllers under ISO 26262 functional safety frameworks. The EU AI Act transparency requirements force documentation of training data provenance for autonomous sensing systems. Stuttgart and Munich host machine vision integrators selecting pre-certified controller packages.
Japan
Industrial automation and precision equipment manufacturers in the Chubu and Kansai regions sustain demand for analog controllers with optical I/O. METI standards govern optical component reliability in telecommunications infrastructure. Osaka-based trading houses coordinate procurement of indium phosphide substrates from East Asian suppliers.
Optical Microcontrollers Market Competitive Landscape
Concentration sits with diversified semiconductor conglomerates possessing analog-to-digital signal conditioning heritage. The vendor base stratifies across three tiers: integrated device manufacturers with captive photonics pilot lines, fabless design houses licensing silicon photonics process platforms, and discrete optical component specialists supplying laser sources and modulators. Dominant competitive moves include foundry partnership formations for co-packaged optics capacity and backward integration into silicon photonics process development.
Among diversified semiconductor manufacturers, Texas Instruments, STMicroelectronics, and Infineon Technologies exemplify the integrated device manufacturer archetype. Texas Instruments represents the analog-centric approach to optical signal conditioning. STMicroelectronics occupies a position anchoring European supply security through its Crolles pilot line. Infineon Technologies sits within the automotive-qualified segment, with its company structure reflecting German engineering heritage.
| Leading Market Players |
|---|
| Microchip Technology |
| Texas Instruments |
| STMicroelectronics |
| Infineon Technologies |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| Maxim Integrated |
| Analog Devices |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Wafer-scale silicon photonics capacity utilization above 85% in South Korean foundries compresses cost curves for multi-channel transceiver designs while simultaneously elevating price floors for specialized indium phosphide substrates. This scale asymmetry between silicon and compound semiconductor platforms concentrates margin capture among integrated device manufacturers with captive pilot lines.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale and ISO 26262 certification tier as the primary price differentiation drivers. Cost compression in standard silicon photonics controllers is intensifying because hyperscale datacenter procurement teams consolidate supplier relationships around open-source photonic design kits. Automotive tier-one suppliers exhibit the least price sensitivity due to functional safety qualification premiums, while industrial automation integrators in Europe demonstrate highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Strategic stockpiling of indium phosphide substrates and specialty gases dominates inventory strategy among automotive lidar suppliers facing EU F-Gas Regulation restrictions. Manufacturing concentrates in South Korea, China, and Taiwan, with supply chains drawing from germanium substrates, III-V compound semiconductors, and fluorinated cooling gases. Single-source vulnerability for 1550 nm laser source substrates creates structural risk. Distribution runs through telecom equipment OEMs and direct fabless design house channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical microcontroller hardware margins are compressing while firmware licensing and predictive maintenance subscriptions expand at multiples of equipment sales, transforming vendor economics toward recurring revenue models.
For Market Incumbents: Compound defensive positioning through backward integration into silicon photonics process development and exclusive foundry partnerships for co-packaged optics capacity. Threats from fabless design houses licensing open-source photonic platforms demand certification investment in MIIT GB standards and FCC laser safety classifications to maintain socket access at hyperscale operators. For New Entrants and Emerging Players: Pre-certified documentation packages for EU AI Act transparency requirements offer a fast-track into German and French machine vision integrator procurement pipelines. The most penetrable white-space sits in India's PLI scheme-attracted telecom equipment assembly ecosystem, where domestic manufacturing incentives lower capital barriers. A direct-to-fabless design house go-to-market angle bypasses entrenched telecom OEM relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified semiconductor conglomerates with analog-to-digital signal conditioning heritage over pure-play photonics startups. Long-term viability hinges on co-packaged optics socket capture in AI training clusters. The acquisition target archetype combines silicon photonics process IP with automotive ISO 26262 qualification records. Foundry partnership announcements with South Korean memory manufacturers signal inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures wafer capacity at South Korean memory-adjacent facilities for co-packaged optics. |
| MIIT GB Standards Certification | Unlocks procurement from China's domestic cloud operators and telecom infrastructure buildouts. |
| ISO 26262 Functional Safety Qualification | Enables premium pricing from German and Japanese automotive lidar tier-one suppliers. |
| Open-Source Photonic Design Kit Release | Addresses hyperscale buyer demands for multi-source compatible optical engine form factors. |
| Indium Phosphide Substrate Stockpiling | Mitigates single-source vulnerability for 1550 nm eye-safe automotive lidar designs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and customs trade data. Interviews with photonics foundry operations directors, telecom equipment procurement managers, automotive Tier 1 supplier engineers, and industrial automation integrators informed demand-side validation. Bottom-up unit shipment estimates triangulated against top-down semiconductor equipment spending analysis.
Segmentation dimensions modeled span product architecture, technology platform, end-use industry, and application type across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves for co-packaged optics in AI clusters and ISO 26262-qualified automotive lidar penetration. Forecast inputs include foundry capacity expansion timelines and regulatory certification burden trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale datacenter investment and stable indium phosphide substrate supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as MIIT standards enforcement intensity and EU F-Gas Regulation implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
5G Chipset Market