
 High-Performance Dual-Core Processor Market | 2026-2036
High-Performance Dual-Core Processor Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Dual-Core Processor Market Insights
Automotive Tier-1 suppliers are collapsing legacy procurement patterns for single-core legacy chips while migrating toward dual-core architectures for real-time control systems. Intel Corporation leverages its foundry partnerships to sustain wafer supply commitments across European automotive clusters. Advanced Micro Devices anchors its position through R&D intensity in x86 power-efficiency roadmaps tailored for embedded thermal constraints. Qualcomm Technologies differentiates by dominating ARM-based designs for telematics and advanced driver-assistance controllers.
A high-performance dual-core processor integrates two independent execution cores on a single die, typically fabricated at process nodes between 7nm and 22nm, with shared L2 cache hierarchies and clock speeds exceeding 2.5 GHz for deterministic response in real-time workloads. The architecture serves industrial and commercial purposes where parallel task separation matters: one core handles operating system overhead while the second manages safety-critical or latency-sensitive application threads. X86 architectures lead in scientific computing and data center edge nodes where legacy software compatibility preserves margin pools, while ARM cores capture the fastest expansion in IoT gateways and smart appliances due to watt-per-performance advantages. RISC-V is displacing MIPS in aerospace control and defense contractor supply chains as open-ISA licensing eliminates royalty stacking.
CE marking under the EU's Radio Equipment Directive shapes electromagnetic compatibility thresholds for telecommunications equipment deployments across European member states. The EU AI Act imposes conformity assessment obligations on edge computing devices with autonomous decision-making capabilities, directly affecting processor validation cycles for network routers and smart appliances. In the United States, FCC Part 15 emissions standards constrain clock-speed ceilings for unshielded consumer electronics enclosures. Stakeholders must monitor how divergent certification timelines between Brussels and Washington alter go-to-market sequencing for dual-core platforms targeting cross-Atlantic defense and telecom contracts.
Market Dynamics
The EU AI Act and CE marking under the Radio Equipment Directive are compressing validation cycles for edge computing processors, forcing semiconductor vendors to front-load certification costs while automotive Tier-1 suppliers accelerate dual-core migration for deterministic control systems.
Growth Catalysts
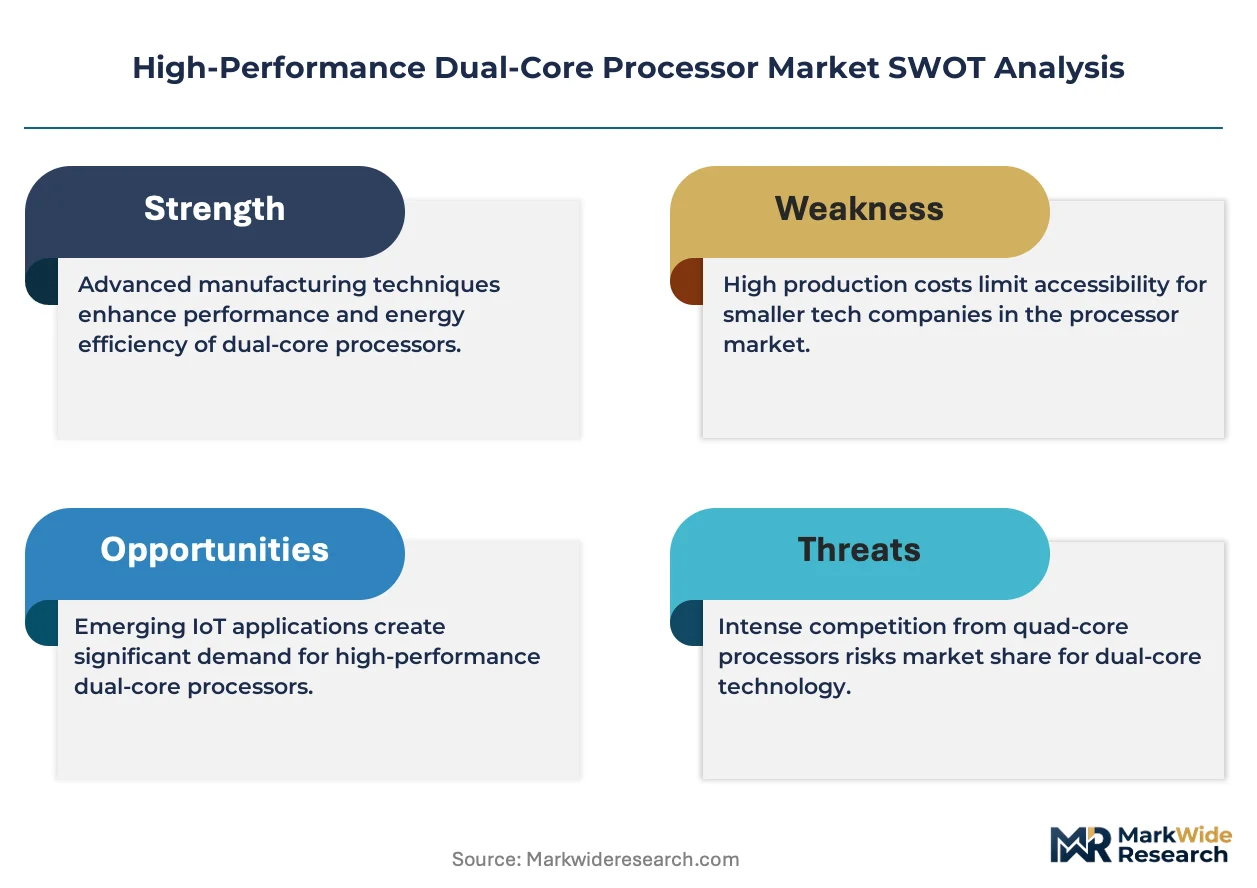
- Automotive real-time control mandates:Tier-1 suppliers are collapsing legacy single-core procurement for dual-core architectures that separate operating system overhead from safety-critical threads in advanced driver-assistance controllers.
- EU AI Act conformity pathways:The regulation imposes assessment obligations on autonomous edge devices, creating captive demand for validated dual-core platforms in network routers and smart appliances across member states.
- Industrial automation corridor concentration:Germany's manufacturing belt is absorbing volume for deterministic response processors in robotics and motion control systems.
Market Restraints
- Advanced node wafer allocation:Foundry capacity at 7nm to 22nm nodes concentrates among three major suppliers, exposing automotive clusters to allocation rationing during demand spikes.
- Electromagnetic compatibility thresholds:CE marking and FCC Part 15 emissions standards constrain clock-speed ceilings for unshielded consumer electronics enclosures.
- RISC-V open-ISA substitution:The royalty-free architecture is displacing MIPS in aerospace control and defense contractor supply chains, pressuring proprietary dual-core margins.
Strategic Opportunities
- India PLI scheme localization:The production-linked incentive framework for electronics manufacturing is attracting dual-core packaging and testing investments for domestic IoT gateway supply.
- Telematics-ADAS convergence:ARM-based dual-core designs are capturing socket opportunities where infotainment and driver assistance functions merge on unified compute platforms.
- EU Green Deal circularity mandates:Extended producer responsibility requirements for semiconductor waste are favoring modular dual-core designs with upgradeable L2 cache hierarchies.
Industry Challenges
- Cross-Atlantic certification divergence:Staggered timelines between Brussels conformity assessment and Washington FCC approvals are delaying go-to-market sequencing for dual-core platforms targeting defense and telecom contracts.
- Legacy software stack porting:x86 compatibility requirements in scientific computing edge nodes are extending validation cycles for thermal-constrained embedded deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Dual-Core Processor Market |
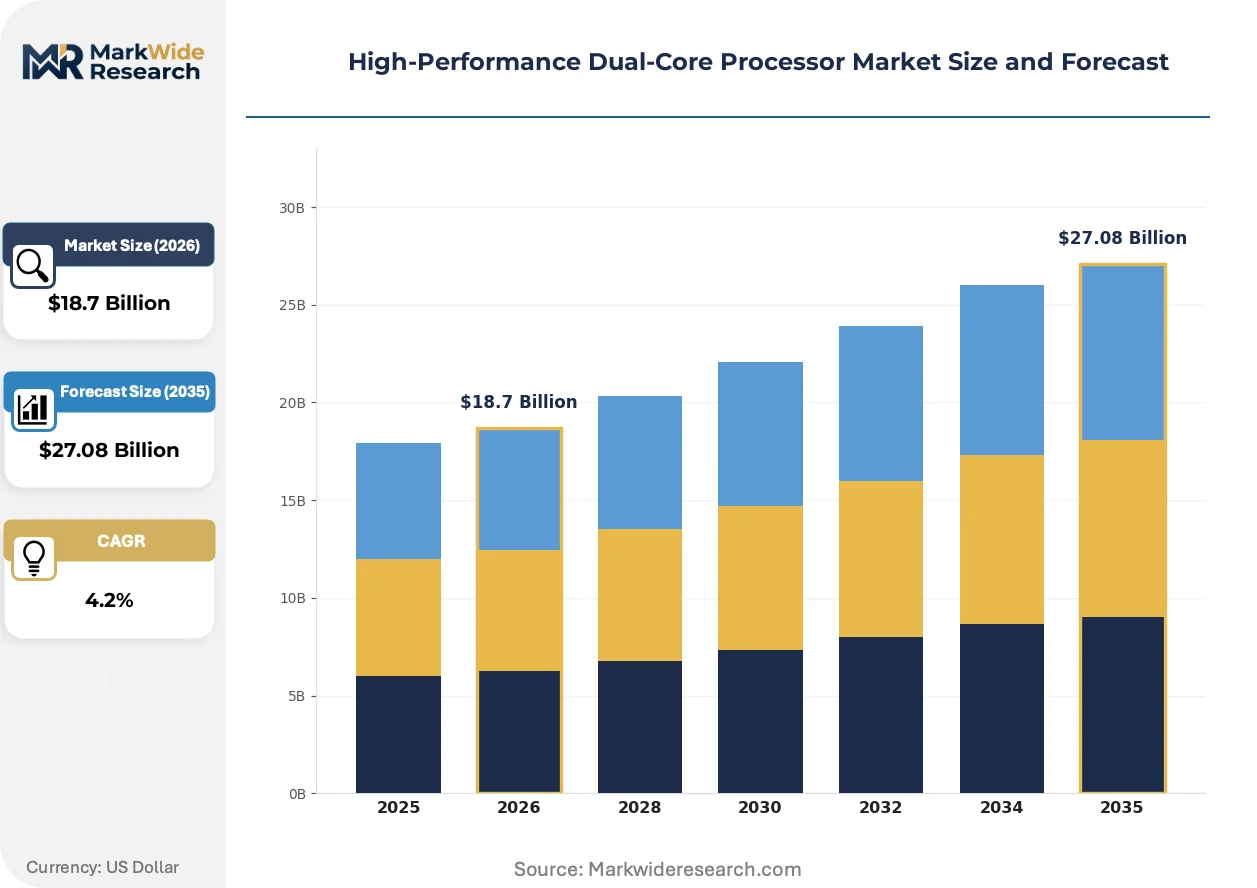
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Architecture: X86, ARM, MIPS, RISC-V, Power Architecture Application: Gaming Consoles, Embedded Systems, Aerospace Control, Telecommunications Equipment, Scientific Computing Deployment: Edge Computing Devices, IoT Gateways, Data Center Servers, Network Routers, Smart Appliances End User Industry: Telecom Operators, Defense Contractors, Research Institutions, Consumer Electronics Manufacturers, Automotive Tier-1 Suppliers |
| Companies Covered | Intel Corporation, Advanced Micro Devices, Qualcomm Technologies, Apple, MediaTek, Samsung Electronics, NXP Semiconductors, Renesas Electronics, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Dual-Core Processor Market Trends and Innovations
Process node compression and heterogeneous integration are redefining power-performance boundaries for embedded dual-core architectures, while regulatory fragmentation and procurement centralization reshape competitive positioning.
Chiplet-based dual-core packaging is miniaturizing die-to-die interconnects for shared L2 cache hierarchies. Automotive Tier-1 suppliers are adopting these configurations for zonal controllers in electric vehicle architectures. The approach is miniaturizing thermal management overhead while preserving deterministic response guarantees.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility thresholds for telecommunications equipment deployments. Processor vendors must pre-validate clock harmonics and shielding effectiveness before member state market entry. Network router manufacturers in Germany and France are absorbing six-month certification extensions into product roadmaps.
Automotive procurement consolidation is collapsing legacy distributor relationships. Tier-1 suppliers are mandating direct foundry contracts with wafer supply commitments for dual-core volumes. This concentration is most visible in Stuttgart and Munich, where Bosch and Continental are captive-sourcing ARM-based designs for telematics controllers.
High-Performance Dual-Core Processor Market Segmentation
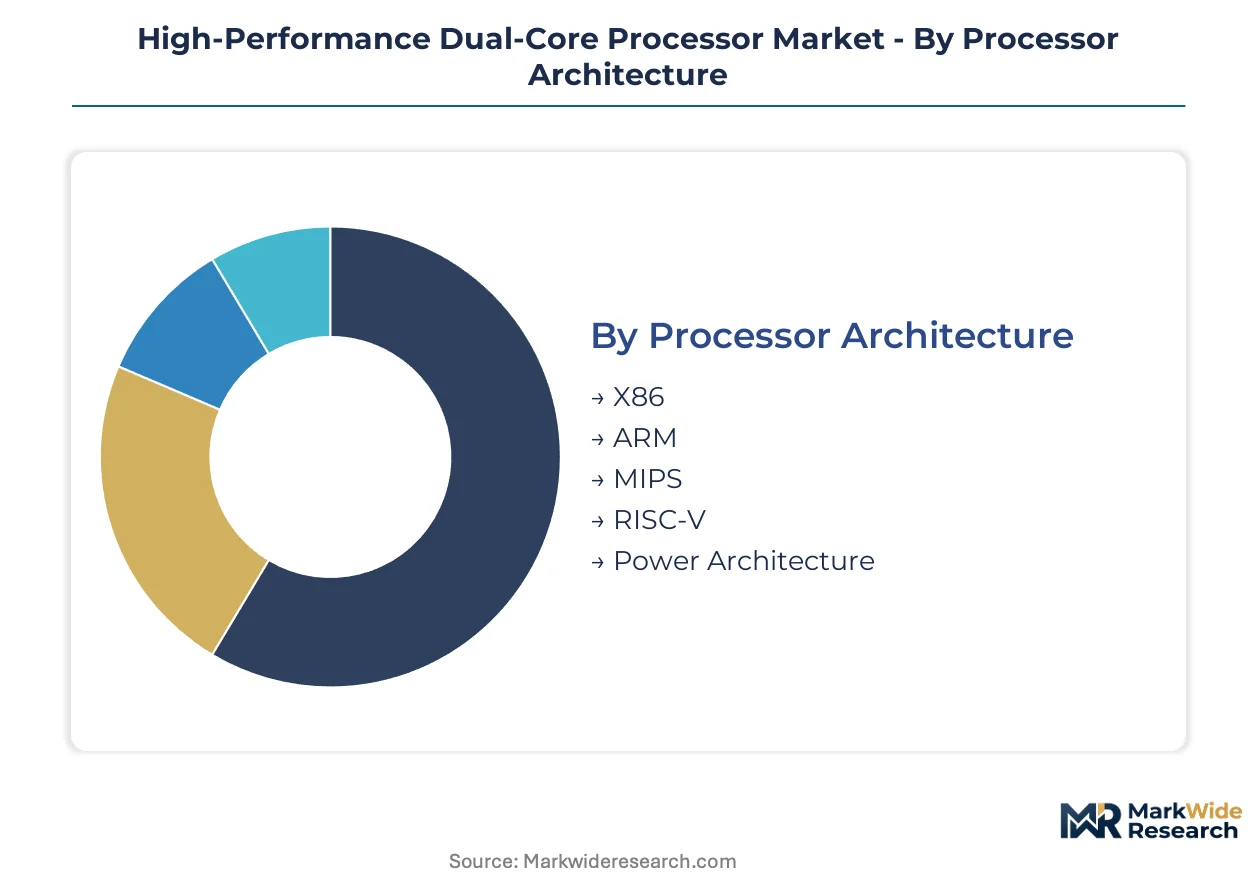
Dual-core processor segmentation reveals divergent vulnerability profiles across instruction-set architectures and deployment contexts. Substitution pressures from open-ISA alternatives and heterogeneous integration are fragmenting traditional revenue pools while concentrating margin capture in certified, safety-critical tiers.
Processor Architecture:
RISC-V's royalty-free licensing is compressing margin structures for proprietary instruction-set architectures, forcing incumbent vendors to defend position through software ecosystem lock-in and pre-validated safety packages.
- X86:Dominates scientific computing and data center edge nodes with legacy binary compatibility and mature compiler toolchains. Demand concentrates in Stuttgart's industrial automation corridor where deterministic response requirements preserve incumbent socket positions.
- ARM:Captures the steepest expansion curve in IoT gateways and telematics controllers through watt-per-performance advantages and consolidated foundry supply. Automotive Tier-1 suppliers in Munich are mandating ARM-based designs for unified infotainment-ADAS platforms.
- MIPS:Retains entrenched positions in legacy aerospace control systems where recertification costs delay migration. Defense contractors in France maintain MIPS procurement for backward-compatible avionics stacks.
- RISC-V:Displacing proprietary cores in defense and aerospace supply chains through open-ISA licensing that eliminates royalty stacking. Indian PLI scheme beneficiaries are adopting RISC-V for domestic IoT gateway production.
- Power Architecture:Persists in high-reliability telecommunications infrastructure where decades-long field deployment cycles favor continuity over performance migration. Network router manufacturers in Germany absorb extended validation timelines for Power-based control planes.
X86 retains volume leadership in legacy-anchored compute segments; RISC-V holds the steepest expansion curve as open-ISA adoption accelerates in defense and emerging economy manufacturing.
Application:
Cost-tier stratification separates premium-certified safety applications from commodity consumer electronics, with margin compression most severe in gaming and entertainment endpoints.
- Gaming Consoles:Volume-driven segment with compressed margins and rapid generational turnover. Consumer electronics manufacturers in Japan prioritize thermal-constrained designs for compact living-room form factors.
- Embedded Systems:Real-time operating system separation on dual-core dies enables deterministic response for safety-critical threads. Automotive Tier-1 suppliers in Germany are collapsing single-core procurement for these architectures in advanced driver-assistance controllers.
- Aerospace Control:DO-178C certification requirements and extended field-life mandates preserve incumbent architectures. Defense contractors in France and Germany absorb multi-year validation cycles for dual-core flight-control processors.
- Telecommunications Equipment:CE marking under the EU Radio Equipment Directive imposes electromagnetic compatibility thresholds that constrain clock-speed ceilings. Network router manufacturers in France are integrating six-month certification extensions into product roadmaps.
- Scientific Computing:x86 compatibility requirements in edge-node deployments extend validation cycles for thermal-constrained embedded configurations. Research institutions in Germany's industrial automation corridor absorb premium pricing for validated scientific compute modules.
Embedded Systems command the dominant revenue share; Aerospace Control maintains the most defensible margin structure through certification barriers.
Deployment:
Supply concentration at 7nm to 22nm foundry nodes exposes deployment categories to allocation rationing, with IoT gateways and smart appliances facing the sharpest capacity constraints.
- Edge Computing Devices:EU AI Act conformity assessment obligations create captive demand for pre-validated dual-core platforms. CE marking requirements in Brussels compress go-to-market timelines for autonomous decision-making endpoints.
- IoT Gateways:ARM-based designs dominate through integrated wireless baseband and application processor consolidation. India's PLI scheme is attracting packaging and testing investments for domestic IoT gateway supply.
- Data Center Servers:x86 architectures preserve margin pools through legacy software compatibility in scientific computing edge nodes. Thermal constraints in hyperscale deployments favor power-efficiency roadmaps from Advanced Micro Devices and Intel.
- Network Routers:Electromagnetic compatibility thresholds under CE marking constrain unshielded enclosure designs. Telecom operators in France and Germany prioritize pre-validated clock harmonics for member state market entry.
- Smart Appliances:EU Green Deal circularity mandates favor modular designs with upgradeable L2 cache hierarchies. Extended producer responsibility requirements in Brussels are reshaping socket strategies for white-goods manufacturers.
Edge Computing Devices anchor volume absorption; IoT Gateways are climbing the fastest as wireless convergence accelerates socket consolidation.
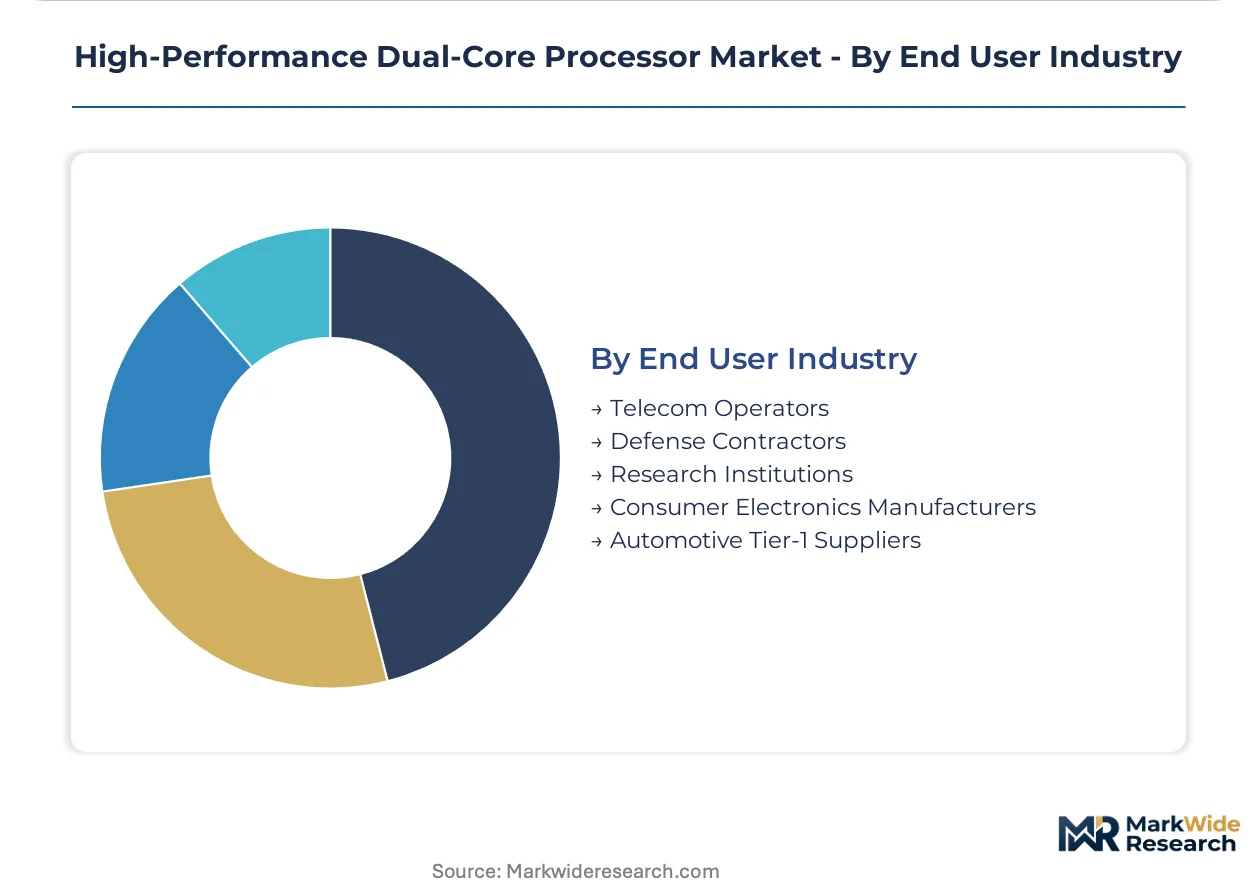
End User Industry:
Customer-type stratification separates price-sensitive consumer electronics procurement from captive-sourcing arrangements in automotive and defense, with telecom operators occupying a contested middle tier.
- Telecom Operators:CE marking and FCC Part 15 emissions standards constrain clock-speed ceilings for unshielded consumer premises equipment. Cross-Atlantic certification divergence delays go-to-market sequencing for dual-core platforms targeting unified European and North American deployments.
- Defense Contractors:RISC-V displacement of MIPS accelerates in aerospace control as open-ISA licensing eliminates royalty stacking. French and German defense procurement is consolidating around domestic foundry partnerships with wafer supply commitments.
- Research Institutions:x86 compatibility requirements in scientific computing edge nodes extend validation cycles. Germany's industrial automation corridor absorbs premium pricing for thermal-constrained embedded configurations.
- Consumer Electronics Manufacturers:Margin compression from RISC-V substitution and commoditized ARM designs pressures pricing structures. Japanese manufacturers prioritize compact thermal management for living-room gaming form factors.
- Automotive Tier-1 Suppliers:Direct foundry contracting with wafer supply commitments collapses legacy distributor relationships. Bosch and Continental in Stuttgart and Munich are captive-sourcing ARM-based designs for telematics-ADAS convergence platforms.
Automotive Tier-1 Suppliers command the steepest volume expansion; Defense Contractors retain the most defensible margin structure through certification moats and national procurement preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer supply commitments concentrate among three major foundry operators, exposing automotive clusters in Stuttgart, Munich, and Dresden to allocation rationing during demand spikes. Certification divergence between Brussels and Washington reshapes go-to-market sequencing for dual-core platforms targeting cross-Atlantic defense contracts.
United States
FCC Part 15 emissions standards constrain clock-speed ceilings for unshielded consumer electronics enclosures. The IRA domestic content provisions are reshaping procurement preferences for federal edge computing deployments. Defense contractors in Austin and Boston absorb multi-month validation cycles for dual-core flight-control processors.
Germany
CE marking under the EU Radio Equipment Directive tightens electromagnetic compatibility thresholds for telecommunications equipment. The EU AI Act imposes conformity assessment obligations on autonomous edge devices. Bosch and Continental in Stuttgart and Munich are captive-sourcing ARM-based designs for telematics-ADAS convergence platforms.
China
MIIT domestic semiconductor substitution programs accelerate RISC-V adoption for industrial automation controllers. GB standards for electromagnetic compatibility constrain unshielded enclosure designs. Foundry capacity in Shanghai and Beijing prioritizes dual-core volumes for domestic IoT gateway supply chains.
India
PLI scheme production-linked incentives attract dual-core packaging and testing investments for domestic electronics manufacturing. BIS certification requirements compress validation timelines for smart appliance deployments. Karnataka and Telangana are absorbing volume for ARM-based designs in wireless gateway production.
Japan
METI technology roadmaps prioritize power-efficiency benchmarks for thermal-constrained embedded configurations. JIS standards for industrial equipment shape deterministic response requirements. Consumer electronics manufacturers in Tokyo and Osaka prioritize compact thermal management for living-room gaming form factors.
High-Performance Dual-Core Processor Market Competitive Landscape
Concentration sits with x86 incumbents and ARM-based specialists competing across divergent certification moats. Three to five foundry-dependent players control premium-tier supply for automotive and aerospace verticals. Strategic archetypes include legacy-anchored ecosystem defenders, watt-per-performance ARM specialists, and open-ISA challengers. Capacity expansion and direct Tier-1 foundry contracting dominate competitive moves, with M&A activity targeting pre-validated safety packages.
Within the x86 ecosystem tier, Intel Corporation and Advanced Micro Devices exemplify legacy-anchored positioning through mature compiler toolchains and thermal-constrained embedded roadmaps. Qualcomm Technologies occupies a position among ARM-based specialists, representing watt-per-performance advantages in telematics and advanced driver-assistance controllers where automotive procurement consolidation favors direct foundry relationships.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices |
| Qualcomm Technologies |
| Apple |
| MediaTek |
| Samsung Electronics |
| NXP Semiconductors |
| Renesas Electronics |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Radio Equipment Directive gates both supplier qualification and price differentiation simultaneously, forcing dual-core processor vendors to absorb six-month certification extensions before accessing member state markets while buyers sort into premium-validated and standard-tier procurement pools based on electromagnetic compatibility compliance levels.
Pricing Analysis
EU AI Act conformity assessment obligations dictate the pricing tier structure across edge computing deployments, separating premium-certified platforms for autonomous decision-making endpoints from standard-tier processors lacking pre-validated safety packages. Pricing stratifies across automotive-grade, industrial-grade, and consumer-grade tiers, with certification level and volume scale serving as primary differentiation drivers. Cost compression in consumer electronics sockets is intensifying because RISC-V open-ISA alternatives eliminate royalty stacking. Consumer electronics manufacturers exhibit highest price sensitivity, while defense contractors absorbing multi-year validation cycles demonstrate lowest sensitivity.
Supply Chain Analysis
Inventory buffers at automotive Tier-1 suppliers have compressed to twelve-week horizons, exposing procurement teams to allocation rationing whenever foundry capacity tightens at 7nm to 22nm nodes. Wafer supply concentrates in Taiwan, South Korea, and the United States, with advanced node production drawing from silicon substrates, photolithography equipment, and specialty chemical etchants. Single-source vulnerability around extreme ultraviolet lithography systems threatens supply continuity. Distribution runs through direct foundry contracts rather than legacy distributor relationships, with Bosch and Continental in Stuttgart and Munich captive-sourcing ARM-based designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act imposes conformity assessment obligations that reshape competitive boundaries, creating a regulatory inflection where pre-validated dual-core platforms capture disproportionate margin expansion against uncertified alternatives.
For Market Incumbents: Fortify ecosystem lock-in through pre-validated safety packages for DO-178C aerospace applications and CE marking pre-certification for telecommunications equipment. RISC-V open-ISA substitution in defense contractor supply chains threatens proprietary architecture margins. Backward integration into foundry partnerships with wafer supply commitments anchors automotive socket positions against allocation rationing.
For New Entrants and Emerging Players: CE marking fast-track services for network router manufacturers in France and Germany represent the most penetrable white-space target, compressing six-month certification extensions through pre-validated electromagnetic compatibility testing. India's PLI scheme for electronics manufacturing offers secondary expansion terrain for domestic IoT gateway packaging and testing. A foundry partnership with wafer supply commitments unlocks Tier-1 supplier procurement channels.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward pre-validated edge computing platform specialists with existing conformity assessment pathways. Long-term viability over a multi-year horizon favors targets with automotive-grade certification moats and direct Bosch or Continental supply relationships. The signal to watch is CE marking approval velocity for network router manufacturers in Brussels, indicating which platforms can compress go-to-market timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification Investment | Compresses six-month validation extensions for network router manufacturers in France and Germany. |
| Direct Foundry Contracting | Secures wafer supply commitments for automotive Tier-1 suppliers in Stuttgart and Munich. |
| RISC-V Architecture Migration | Eliminates royalty stacking for defense contractors in French and German aerospace control systems. |
| Chiplet-Based Packaging Adoption | Miniaturizes thermal management overhead for zonal controllers in electric vehicle architectures. |
| India PLI Scheme Localization | Attracts dual-core packaging and testing investments for domestic IoT gateway supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across automotive Tier-1 procurement teams, foundry capacity planners, network router engineering leads, defense contractor avionics specialists, and industrial automation systems integrators. Primary interview insights combined with secondary validation from SEC semiconductor filings, EU Radio Equipment Directive implementation guidance, customs wafer trade data, and automotive production databases. Bottom-up volume builds across processor architecture segments triangulated against top-down market sizing from foundry capacity disclosures.
Across the analysis window, the forecasting framework models processor architecture, application deployment context, end-user industry, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from annualized shipment trajectories adjusted for foundry allocation constraints and certification timeline compression. Key inputs include wafer supply commitments from three major foundry operators, EU AI Act conformity assessment obligation implementation schedules, and automotive Tier-1 supplier procurement consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained foundry capacity expansion, stable regulatory implementation timelines, or continued automotive electrification would require recalibration. Forecasts reflect documented assumptions around certification velocity, allocation rationing severity, and open-ISA substitution pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Integrated Graphics Chipset Market