
 Germany Automotive Smart Keys Market | 2026-2036
Germany Automotive Smart Keys Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Smart Keys Market Foresight
Aftermarket distribution for replacement smart keys is tilting toward authorized dealership networks and certified Tier-1 supplier channels. Continental AG leverages its integrated semiconductor and mechatronics portfolio to control in-house production of secure key transponders. Robert Bosch GmbH anchors its position through R&D intensity in radio frequency identification protocols for passive entry systems. Huf Hülsbeck & Fürst GmbH & Co. KG specializes in mechanical-electronic hybrid platforms that sustain brand strength across German OEM programs.
Germany automotive smart keys are electronic access devices combining encrypted transponder chips, low-frequency antennas, and near field communication or Bluetooth Low Energy modules to authenticate vehicle entry and enable push-button ignition. Manufacturing employs laser-etched key blades, injection-molded fob housings with IP67 sealing, and cleanroom assembly of cryptographic controllers to meet automotive-grade reliability standards. Keyless entry systems dominate unit volumes as OEMs standardize passive access across mid-range passenger vehicle lineups, while Bluetooth Low Energy segments capture expanding margin pools through smartphone-as-a-key integrations. Ultrasonic technology leads in luxury car access applications where centimeter-precision localization prevents relay attacks.
Germany's KBA enforces UN ECE Regulation 116 for electronic immobilizer certification, while the EU Cyber Resilience Act imposes baseline security requirements on connected vehicle components including smart key ecosystems. REACH compliance shapes material selection for fob housings and circuit substrates, restricting certain flame retardants and phthalates in consumer-facing automotive electronics. Stakeholders must monitor how firmware-over-the-air update mandates and evolving insurance industry cyber risk assessments reshape product liability and aftermarket service obligations.
Market Dynamics
Bluetooth Low Energy and Ultrasonic-based digital key solutions are compressing replacement cycles across Bavarian and Baden-Württemberg OEM lineups, forcing Tier-1 suppliers to reconfigure cryptographic controller production lines.
Growth Catalysts
- UN ECE Regulation 116:Germany's KBA type-approval requirements for electronic immobilizers mandate hardware upgrades across vehicle platforms, pulling demand for secure transponder architectures.
- Electric vehicle lineups:Premium passenger vehicle manufacturers in Stuttgart and Munich integrate smartphone-as-a-key functionality as standard equipment, expanding addressable hardware volumes.
- Passive entry standardization:Mid-range passenger vehicle programs now specify encrypted LF antenna modules, eliminating mechanical key dependency in volume segments.
Market Restraints
- Semiconductor supply concentration:Secure element foundry capacity concentrates in East Asian packaging houses, exposing German module assemblers to allocation volatility.
- Phthalate substitution costs:REACH compliance for fob housings forces reformulation of injection-molded polymers, elevating material qualification timelines.
- Relay attack countermeasures:Ultrasonic localization hardware adds bill-of-materials complexity that compresses margin pools in economy vehicle programs.
Strategic Opportunities
- Aftermarket channel consolidation:Authorized dealership networks capture replacement smart key volumes previously fragmented through independent locksmiths.
- Firmware-over-the-air mandates:EU Cyber Resilience Act requirements create recurring service revenue streams for cryptographic key updates.
- Mechanical-electronic hybrid platforms:Huf Hülsbeck & Fürst GmbH & Co. KG demonstrates sustained OEM program retention through dual-interface architectures.
Industry Challenges
- Cleanroom assembly scale-up:Cryptographic controller production requires ISO Class 7 environments that constrain capacity expansion in existing German electronics facilities.
- Insurance cyber risk assessments:Evolving liability frameworks for key-cloning incidents complicate product warranty structuring and aftermarket service obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Smart Keys Market |
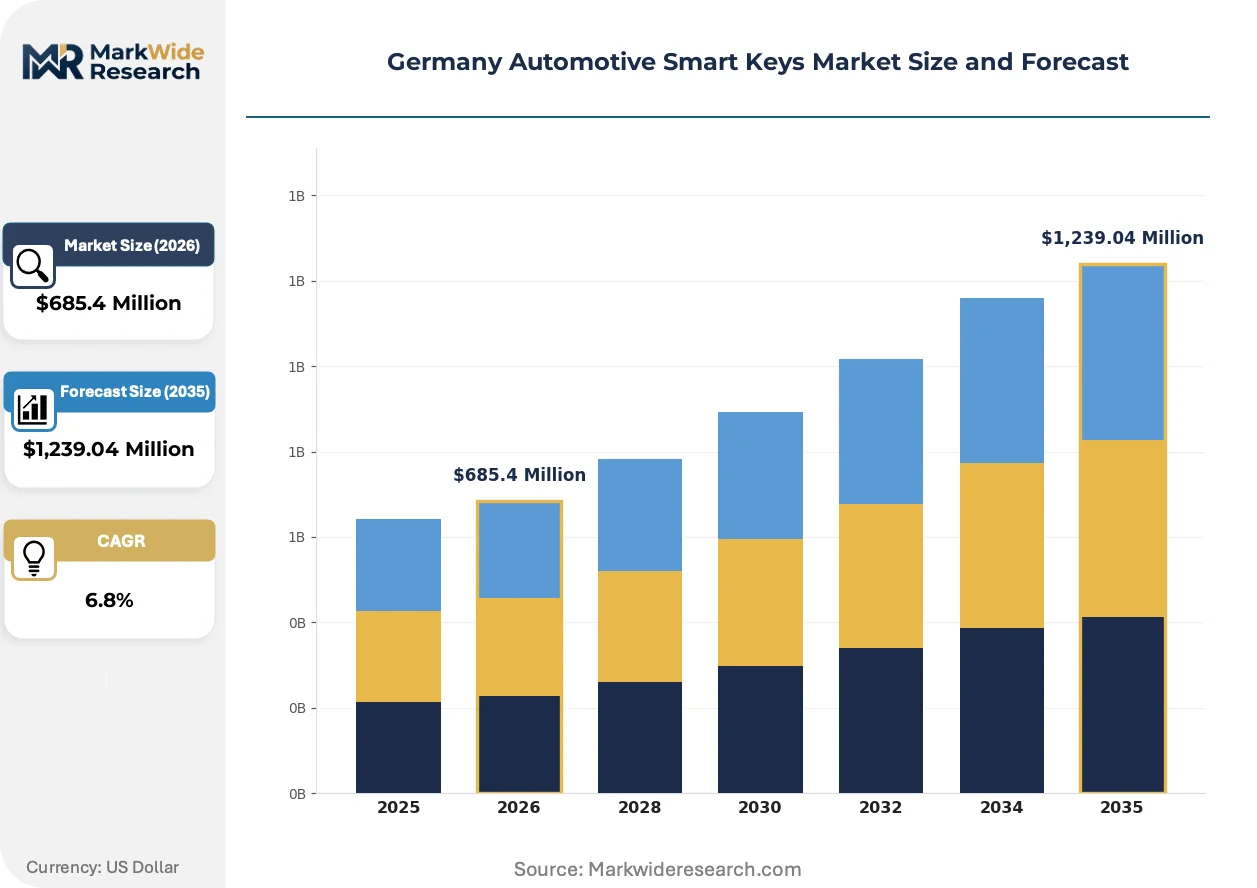
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Key, Keyless Entry System, Transponder Key, Smart Key Fob Technology: Radio Frequency Identification, Bluetooth Low Energy, Near Field Communication, Infrared, Ultrasonic Application: Passenger Vehicle Security, Fleet Management, Vehicle Sharing Services, Luxury Car Access End User: OEMs, Vehicle Assemblers, Aftermarket Providers, Dealerships, Tier-1 Suppliers |
| Companies Covered | Continental AG, ZF Friedrichshafen AG, Robert Bosch GmbH, Denso Corporation, Valeo SA, Huf Hülsbeck & Fürst GmbH & Co. KG, HELLA GmbH & Co. KGaA, Infineon Technologies AG, NXP Semiconductors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Smart Keys Market Shifts & Advancements
Smartphone-as-a-key architectures are collapsing the distinction between physical fobs and mobile credentials, rewiring how OEMs specify entry system hardware and how owners experience vehicle access.
Ultrasonic sensing arrays for centimeter-precision localization are digitizing theft-prevention protocols in luxury vehicle access systems. BMW Group and Mercedes-Benz AG deploy these modules across S-Class and 7-Series lineups to neutralize relay attack vectors. The technology is digitizing how German OEMs validate owner proximity, compressing the hardware boundary between passive entry and biometric authentication.
Germany's KBA enforcement of UN ECE Regulation 116 immobilizer standards tightens cryptographic key length requirements annually. Component suppliers must resubmit transponder architectures for type-approval with each vehicle platform refresh. Bavarian engineering centers absorb the compliance burden through captive testing laboratories, insulating program timelines from regulatory friction.
Fleet operators and corporate buyers now specify keyless entry as a procurement threshold rather than an option package. Leasing companies in Frankfurt and Hamburg mandate smartphone-integrated access for executive vehicle pools, displacing traditional fob distribution through rental counter channels. This preference shift concentrates specification power among commercial fleet managers rather than individual retail purchasers.
Germany Automotive Smart Keys Market Segmentation
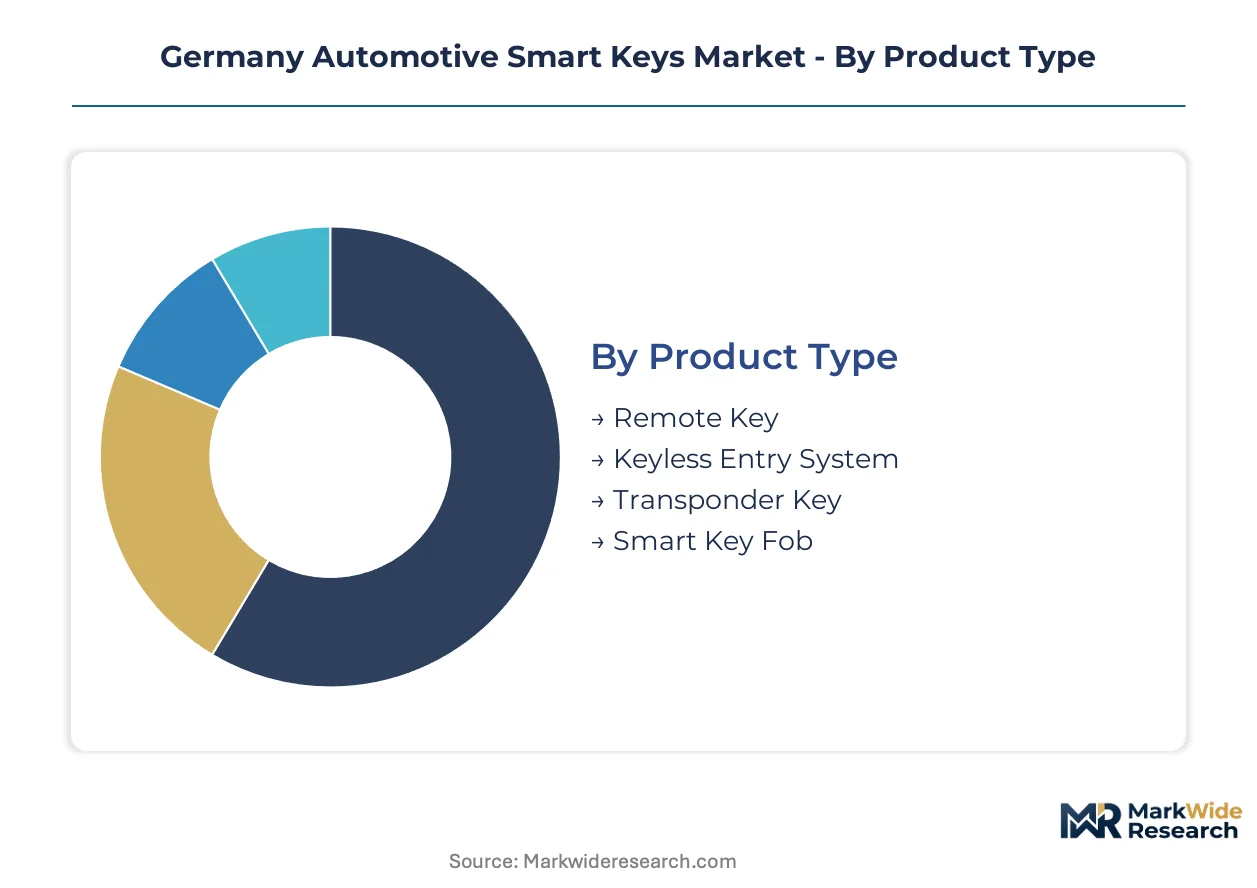
German OEM procurement patterns diverge sharply across product architectures, with Bavarian and Baden-Württemberg manufacturers driving specification fragmentation. Technology selection now hinges on cybersecurity certification timelines under KBA enforcement, while application segmentation reflects fleet electrification priorities.
Product Type:
Mature mechanical-electronic hybrids dominate current program volumes, though emerging fully digital architectures are compressing replacement cycles.
- Remote Key:Combines encrypted transponder chips with low-frequency antenna modules for line-of-sight vehicle access. Stuttgart-based OEMs specify these for entry-level electric vehicle lineups where cost discipline outweighs passive entry convenience.
- Keyless Entry System:Passive LF antenna arrays authenticate proximity without button activation, now standard across mid-range passenger vehicles assembled in Munich and Wolfsburg. KBA type-approval requirements for UN ECE Regulation 116 immobilizer integration pull hardware upgrades.
- Transponder Key:Legacy mechanical blade with embedded cryptographic controller, sustaining aftermarket demand through Bavarian dealership networks.
- Smart Key Fob:Multi-protocol device integrating BLE, NFC, and UWB radios for smartphone-as-a-key readiness.
Keyless Entry System handles the majority of throughput; Smart Key Fob is the fastest mover on share.
Technology:
Cost tier stratification separates premium ultrasonic localization from economy RFID implementations, with margin compression accelerating at the standard tier.
- Radio Frequency Identification:Legacy LF/HF transponder protocols for basic immobilizer functions. Volume manufacturers in Lower Saxony retain these for cost-sensitive vehicle programs.
- Bluetooth Low Energy:Smartphone-as-a-key backbone enabling credential provisioning without physical fob distribution. Mercedes-Benz AG and BMW Group mandate BLE modules across S-Class and 7-Series lineups, expanding addressable hardware volumes.
- Near Field Communication:Tap-to-unlock authentication for backup access when smartphone batteries deplete.
- Infrared:Obsolete directional protocol surviving only in legacy fleet retrofit applications.
- Ultrasonic:Centimeter-precision sensing arrays neutralize relay attack vectors through time-of-flight measurement. Baden-Württemberg engineering centers deploy these in luxury access systems where theft prevention justifies bill-of-materials premiums.
Radio Frequency Identification retains the deepest installed base; Ultrasonic is climbing the fastest as security specifications tighten.
Application:
Customer type differentiation now separates fleet procurement thresholds from individual retail option packages, rewiring distribution economics.
- Passenger Vehicle Security:Standardized passive entry and push-button ignition across private-owner vehicle programs. KBA annual tightening of cryptographic key length requirements forces transponder architecture resubmission with each platform refresh.
- Fleet Management:Corporate leasing companies in Frankfurt and Hamburg mandate smartphone-integrated access for executive vehicle pools, displacing traditional fob distribution through rental counter channels.
- Vehicle Sharing Services:Cloud-credential provisioning for short-term access without physical key handoff.
- Luxury Car Access:Biometric-ready architectures with ultrasonic proximity validation and personalized cabin pre-configuration.
Passenger Vehicle Security generates the highest absolute unit volumes; Fleet Management is gaining share fastest as commercial procurement concentrates specification power.
End User:
Supply concentration among captive Tier-1 operations contrasts with fragmented aftermarket channel consolidation toward authorized networks.
- OEMs:Volkswagen AG, BMW Group, and Mercedes-Benz AG specify entry system architectures directly, leveraging captive semiconductor partnerships for secure element sourcing.
- Vehicle Assemblers:Contract manufacturing operations in Saxony and Thuringia integrate keyless modules under OEM-directed bill-of-materials.
- Aftermarket Providers:Independent locksmiths face shrinking replacement key volumes as encrypted credential provisioning restricts unauthorized duplication.
- Dealerships:Bavarian and Baden-Württemberg authorized networks capture smart key replacement demand through certified Tier-1 supplier channels.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH anchor production through in-house secure transponder and RFID protocol R&D.
OEMs command the dominant procurement position; Dealerships are expanding most quickly as aftermarket access consolidates under authorized certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube canal network and Autobahn freight corridors enable just-in-time delivery of cryptographic controllers from Bavarian assembly plants to Wolfsburg and Stuttgart manufacturing clusters. This logistics backbone underwrites Germany's concentration of automotive smart key production.
Bavaria
BMW Group's Munich headquarters mandates smartphone-as-a-key functionality across electric vehicle lineups, pulling demand for Bluetooth Low Energy modules. KBA type-approval laboratories in Munich process UN ECE Regulation 116 immobilizer certifications for transponder architectures. Continental AG operates secure element assembly in Ingolstadt under ISO Class 7 cleanroom standards.
Baden-Württemberg
Mercedes-Benz AG in Stuttgart specifies ultrasonic localization arrays for S-Class theft prevention, neutralizing relay attack vectors through time-of-flight measurement. The state's REACH enforcement office monitors phthalate substitution in injection-molded fob housings. Robert Bosch GmbH anchors RFID protocol development in Gerlingen, supplying passive entry systems to regional OEM programs.
Lower Saxony
Volkswagen AG's Wolfsburg operations standardize encrypted LF antenna modules across mid-range passenger vehicles, eliminating mechanical key dependency. The region's concentration of contract vehicle assemblers integrates keyless modules under OEM-directed bills-of-materials. Huf Hülsbeck & Fürst GmbH & Co. KG maintains mechanical-electronic hybrid production in Velbert for legacy platform support.
North Rhine-Westphalia
Fleet leasing companies in Düsseldorf and Cologne mandate smartphone-integrated access for executive vehicle pools, displacing traditional fob distribution. The state's automotive supplier density supports Tier-1 module integration for export-bound production. HELLA GmbH & Co. KGaA operates development centers in Lippstadt for antenna array optimization.
Hesse
Frankfurt's corporate procurement headquarters concentrate specification power for commercial fleet smart key deployments. The region's insurance industry cyber risk assessors evaluate product liability frameworks for key-cloning incidents. Infineon Technologies AG maintains semiconductor design operations in Neubiberg adjacent to Frankfurt's financial district.
Germany Automotive Smart Keys Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying secure transponders and antenna modules. The vendor structure concentrates among captive Tier-1 operations with in-house semiconductor partnerships, while independent module assemblers face capacity constraints from cleanroom assembly requirements. Two strategic archetypes dominate: integrated mechatronics conglomerates controlling cryptographic controller production, and semiconductor foundries supplying secure elements to multiple system integrators. Competitive positioning hinges on M&A activity consolidating aftermarket distribution channels, and strategic partnerships between OEMs and BLE protocol developers for smartphone-as-a-key standardization.
Among Germany-based integrated suppliers, Continental AG, Robert Bosch GmbH, and Huf Hülsbeck & Fürst GmbH & Co. KG occupy positions spanning the system-to-component spectrum. Continental AG exemplifies the captive semiconductor archetype through in-house secure transponder production. Robert Bosch GmbH represents sustained R&D intensity in radio frequency identification protocols. Huf Hülsbeck & Fürst GmbH & Co. KG anchors the mechanical-electronic hybrid tier, demonstrating program retention across OEM lineups through dual-interface architectures. These three entities collectively illustrate how German automotive supply chains embed cryptographic security at multiple value chain levels.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo SA |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| HELLA GmbH & Co. KGaA |
| Infineon Technologies AG |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
East Asian secure element foundry concentration in Taiwan and South Korea anchors upstream cryptographic controller supply, concentrating margin capture with module integrators who control cleanroom assembly capacity in Bavaria and Baden-Württemberg. OEM procurement consolidation toward captive Tier-1 partnerships compresses pricing power for independent assemblers lacking in-house semiconductor sourcing.
Pricing Analysis
Volume-discount tiering structures separate premium ultrasonic localization arrays from economy RFID implementations across German OEM programs. Pricing stratifies across premium, standard, and economy tiers based on certification grade under KBA type-approval timelines and volume scale commitments. Cost compression in economy vehicle programs intensifies because BLE module standardization eliminates differentiation leverage. Fleet procurement managers exhibit lowest price sensitivity due to cybersecurity compliance mandates, while independent aftermarket providers face acute margin pressure from encrypted credential restrictions.
Supply Chain Analysis
Contract-manufacturing concentration rests with TSMC and Samsung Foundry for secure element wafer fabrication, with OSAT partners in Malaysia and Vietnam handling cryptographic controller packaging. German module assemblers draw from silicon carbide substrates, injection-molded IP67 housings, and LF antenna ferrite cores. Single-source vulnerability in East Asian packaging houses exposes production schedules to allocation volatility. Distribution runs through authorized dealership networks capturing replacement key volumes previously fragmented through independent locksmiths.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation among Frankfurt and Hamburg leasing companies concentrates specification power with commercial buyers, displacing individual retail purchasers as the dominant demand archetype in this market.
For Market Incumbents: Entrench program retention through captive cleanroom assembly expansion in Ingolstadt and Gerlingen, insulating against semiconductor allocation volatility from East Asian foundries. Deepen backward integration into secure transponder design to neutralize margin compression from BLE module commoditization. Prioritize KBA certification pipeline acceleration to maintain type-approval advantages over emerging entrants lacking captive testing laboratories. For New Entrants and Emerging Players: Mid-range electric vehicle programs in Lower Saxony represent the most penetrable entry point where cost discipline currently outweighs passive entry convenience. Aftermarket firmware-over-the-air update services for legacy fleet deployments offer recurring revenue without cleanroom capital requirements. Pursue partnership routes with vehicle sharing operators requiring cloud-credential provisioning infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding ISO Class 7 capacity but lacking OEM program scale. Long-term viability hinges on smartphone-as-a-key protocol standardization capturing replacement cycle compression across the analysis window. Monitor KBA enforcement intensity for UN ECE Regulation 116 cryptographic key length escalations as inflection indicator for hardware refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Backward Integration | Continental AG's captive semiconductor production insulates margin pools from foundry allocation volatility. |
| Ultrasonic Localization Deployment | Mercedes-Benz AG's S-Class arrays establish centimeter-precision theft prevention as luxury segment baseline. |
| Firmware-over-the-Air Infrastructure | EU Cyber Resilience Act mandates create recurring service revenue streams for cryptographic key updates. |
| Aftermarket Channel Certification | Bavarian dealership networks capture replacement volumes through Tier-1 supplier authorization requirements. |
| BLE Protocol Standardization | BMW Group's smartphone-as-a-key functionality expands addressable hardware volumes across electric lineups. |
Research Methodology
Desk research of KBA type-approval filings, UN ECE Regulation 116 certification databases, and OEM supplier disclosure documents preceded structured interviews with Tier-1 procurement directors, OEM platform engineers, aftermarket dealership operations managers, and semiconductor supply specialists. Primary fieldwork across Bavarian and Baden-Württemberg engineering centers combined with secondary validation through vehicle production databases and IHS Markit registration data. Bottom-up module shipment estimates triangulated against top-down OEM program specifications.
Assumptions held fixed include KBA enforcement continuity for immobilizer standards and REACH compliance trajectory for fob housing materials, while electric vehicle adoption pace and smartphone-as-a-key penetration rates varied across sensitivity scenarios. The analytical framework modeled segmentation across propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from logistic adoption curve fitting applied to BLE and ultrasonic technology diffusion patterns, with semiconductor supply elasticity and fleet procurement concentration serving as key forecast inputs.
Practitioners should monitor East Asian foundry allocation announcements and KBA cryptographic key length revision schedules for early signals of supply constraint or regulatory acceleration. Forecasts reflect documented assumptions regarding cleanroom capacity expansion timelines and fleet electrification procurement thresholds. Quarterly review of Tier-1 supplier backlog reports and KBA type-approval submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market