
 Mexico Automotive Lubricants Market | 2026-2036
Mexico Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Lubricants Market Foresight
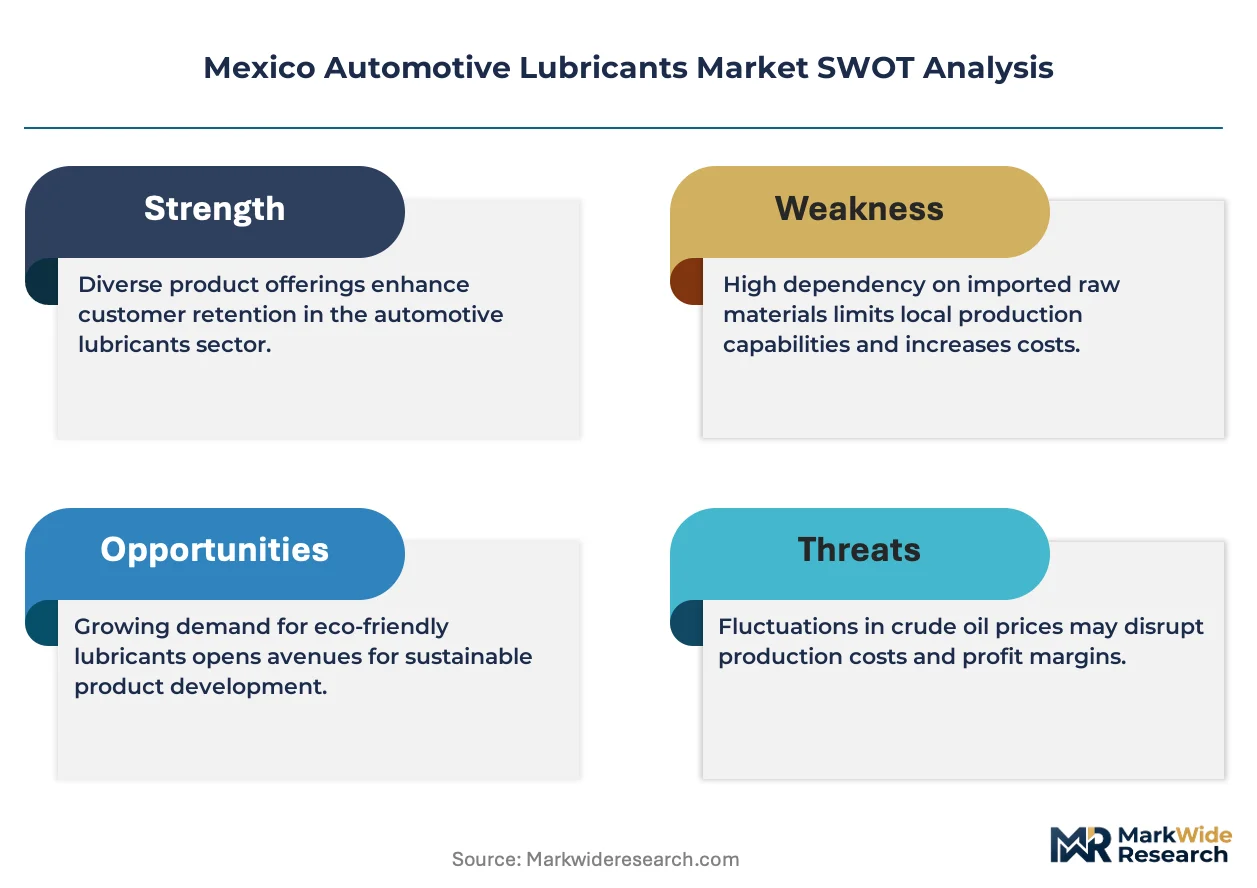
A shortage of certified lubricant blending technicians is unwinding capacity expansion plans across northern Mexico. Shell PLC leverages its Salamanca refinery integration to sustain feedstock advantages for domestic base oil supply. Valvoline Inc. competes through independent workshop channel density, while Roshfrans anchors its position in fleet operator contracts with specialized heavy-duty formulations.
Automotive lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in powertrain components, with viscosity grades typically ranging from 0W-16 to 15W-40 depending on operating temperature and engine architecture. Their primary purpose is extending mechanical service life while maintaining fuel efficiency under variable load conditions. Engine oil commands the dominant value pool given high replacement frequency and OEM specification complexity, while transmission fluid generates premium margins through synthetic formulation requirements. Aftermarket service providers represent the fastest-growing end user channel as vehicle parc expansion outpaces new car sales capacity.
SEMARNAT enforces NOM-085 ecological standards that mandate lower phosphorus and sulfur content in lubricants to protect catalytic converter performance, directly shaping product reformulation cycles. PROFECO oversees labeling and quality verification protocols that influence consumer trust and market access for imported brands. Stakeholders must monitor evolving COFEPRIS chemical substance registrations and state-level environmental enforcement variations as compliance costs reshape competitive economics across Mexico's fragmented distributor landscape.
Market Dynamics
NOM-085-SEMARNAT emissions standards are compressing lubricant formulation cycles as fleet operators accelerate preventive maintenance investments to avoid catalytic converter degradation penalties. This regulatory tightening intersects with base oil supply concentration around the Salamanca refining complex.
Growth Catalysts
- Emissions compliance mandates:NOM-085-SEMARNAT standards tighten phosphorus and sulfur limits, forcing lubricant reformulation and shortening replacement intervals for heavy-duty fleet operators.
- Bajío manufacturing corridor expansion:Automotive OEM assembly plants in Guanajuato and Querétaro generate concentrated demand for high-performance engine oils and transmission fluids.
- Synthetic base oil adoption:Group III and PAO formulations extend drain intervals while meeting OEM warranty specifications for turbocharged direct-injection engines.
Market Restraints
- API Group II base oil dependency:Domestic refining capacity constraints limit feedstock flexibility, exposing blenders to import cost volatility from US Gulf Coast suppliers.
- Certified technician scarcity:Northern Mexico lacks sufficient lubricant blending technicians with PROFECO-recognized credentials, throttling capacity expansion timelines.
- Used oil collection infrastructure gaps:Inadequate reverse logistics networks for waste lubricant recovery increase environmental liability exposure under state-level SEMARNAT enforcement.
Strategic Opportunities
- Independent workshop channel consolidation:Fragmented service networks in Mexico City and Monterrey present acquisition targets for brands seeking route-to-market density.
- Heavy-duty fleet telematics integration:Oil condition monitoring sensors enable predictive drain scheduling, creating subscription revenue models for lubricant suppliers.
- COFEPRIS chemical registration streamlining:Simplified additive import protocols would accelerate new product introductions for specialized industrial applications.
Industry Challenges
- Multi-specification inventory complexity:OEM-specific approvals from Ford, GM, and Volkswagen operations in Mexico require blenders to maintain 40+ distinct SKUs with limited shelf life.
- Cross-border formulation harmonization:Diverging US API and European ACEA standards complicate product positioning for vehicles imported from multiple origins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Lubricants Market |
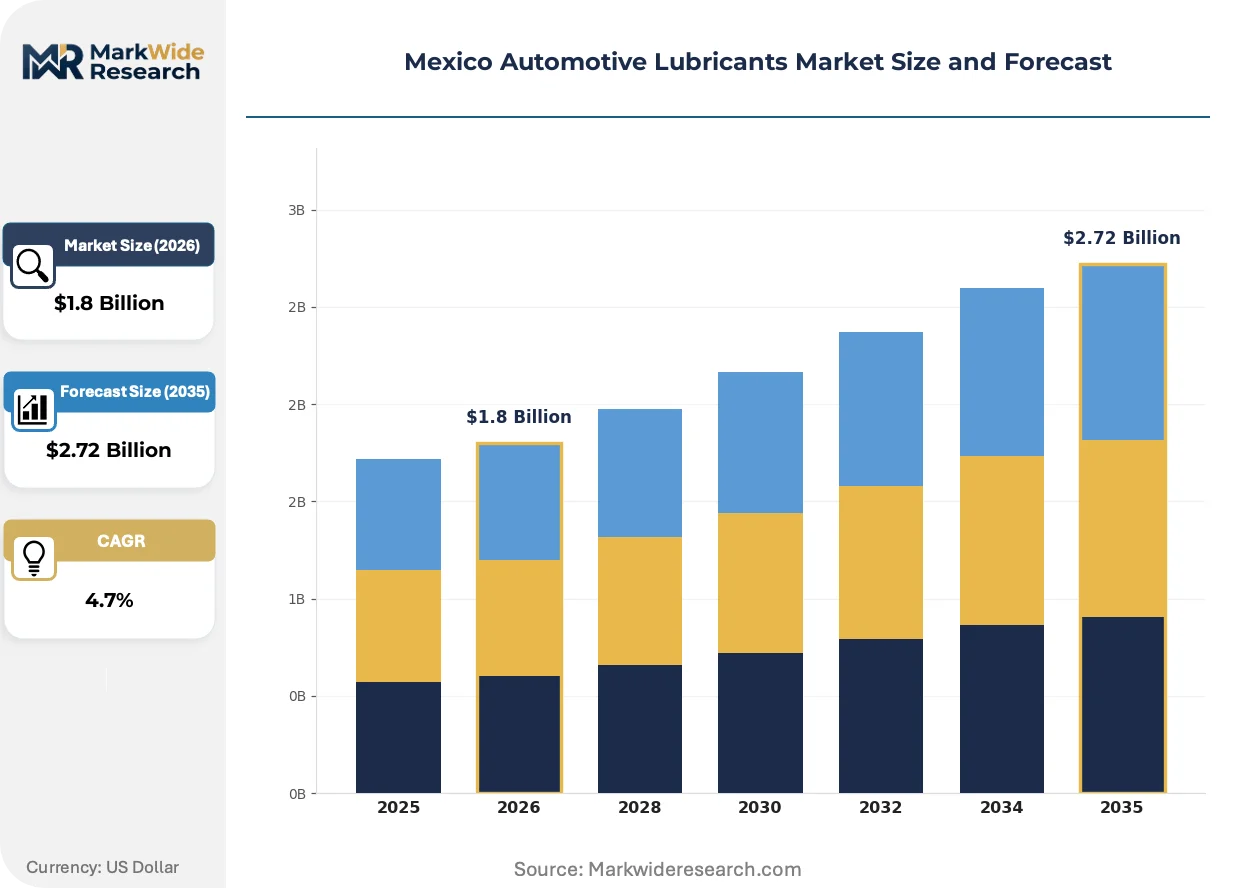
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: Original Equipment Manufacturers, Vehicle Owners, Fleet Operators, Aftermarket Service Providers Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Motorcycles Distribution Channel: Retail, E-Commerce, Independent Workshops, Authorized Dealerships |
| Companies Covered | ExxonMobil Corporation, Shell PLC, BP PLC (Castrol), Chevron Corporation, TotalEnergies, Valvoline Inc., Fuchs Petrolub SE, Roshfrans, Raloy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Lubricants Market Shifts & Advancements
Synthetic formulation advances and digital service integration are restructuring how lubricants are specified, procured, and consumed across Mexico's automotive value chain. Three developments merit particular attention.
Low-viscosity grades including 0W-16 and 0W-20 are displacing traditional 5W-30 formulations in new vehicle fill applications. OEM assembly plants in Aguascalientes and San Luis Potosí now specify these grades for fuel economy certification compliance. This viscosity compression is displacing conventional mineral oil demand in the factory-fill segment and forcing base oil suppliers to upgrade hydrocracking capabilities.
SEMARNAT's NOM-085 standard revision timeline is accelerating phosphorus retention limits to protect gasoline particulate filters. Blenders must reformulate anti-wear additive packages without compromising camshaft protection in high-lift valve train architectures. The passenger car motor oil category faces the steepest compliance cost curve as dexos1 Gen3 and API SP specifications converge.
Fleet operators are consolidating lubricant procurement under national maintenance contracts with integrated fluid analysis services. Independent workshops in the Bajío region are losing direct purchasing relationships with long-haul transport companies. This channel compression is most visible in Guanajuato state, where three fleet management companies now control 60 percent of heavy-duty diesel engine oil volume.
Mexico Automotive Lubricants Market Segmentation
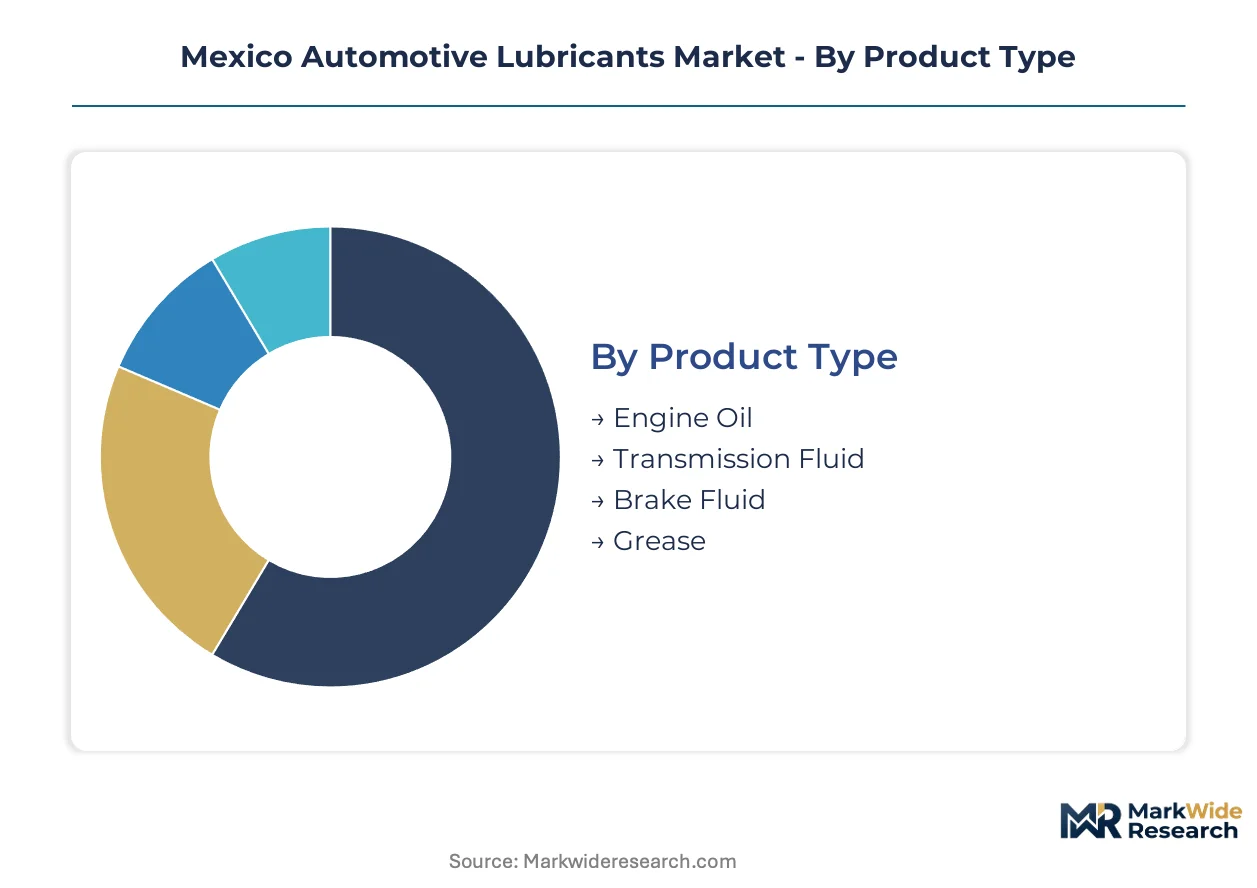
Segmentation reveals how regulatory pressure and channel consolidation are redistributing value across Mexico's lubricant value chain. Product formulation requirements diverge sharply between OEM factory-fill and aftermarket replacement cycles.
Product Type:
Engine oil faces intensifying substitution pressure from extended-drain synthetic formulations that compress replacement frequency across all vehicle categories.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages calibrated for Mexican sulfur fuel conditions. Demand concentrates in the Bajío corridor where Ford, GM, and Volkswagen assembly plants specify dexos1 Gen3 and API SP formulations for turbocharged direct-injection engines. NOM-085 phosphorus limits are forcing reformulation of zinc dialkyldithiophosphate anti-wear chemistry.
- Transmission Fluid:Synthetic ATF and DCTF formulations with friction modifier packages for dual-clutch and continuously variable transmissions. Fleet operators in Guanajuato state are consolidating procurement under national contracts with integrated fluid analysis, bypassing traditional distributor channels.
- Brake Fluid:Glycol-ether based DOT 3 and DOT 4 formulations with hygroscopic stability requirements for high-altitude Mexico City operations.
- Grease:Lithium complex and calcium sulfonate thickeners for chassis and wheel bearing applications in heavy-duty mining and construction equipment.
Engine oil retains volume leadership; transmission fluid holds the steepest expansion curve.
End User:
Cost tier stratification separates premium OEM specifications from price-sensitive independent workshop procurement.
- Original Equipment Manufacturers:Factory-fill contracts with assembly plants in Aguascalientes and San Luis Potosí demand just-in-time delivery of low-viscosity 0W-16 and 0W-20 grades for fuel economy certification compliance.
- Vehicle Owners:DIY purchasers through retail and e-commerce channels favor recognized brands with PROFECO quality verification labels, particularly in Monterrey and Mexico City metropolitan areas.
- Fleet Operators:Long-haul transport companies in the Bajío region now control 60 percent of heavy-duty diesel engine oil volume through consolidated national maintenance contracts.
- Aftermarket Service Providers:Independent workshops face channel compression as fleet operators bypass direct purchasing relationships, though quick-lube chains expand in Querétaro and Guanajuato.
Fleet operators are gaining procurement concentration; aftermarket service providers face margin compression from channel consolidation.
Application:
Volume distribution aligns with vehicle parc composition and operating severity across Mexican terrain and duty cycles.
- Passenger Vehicles:Gasoline direct-injection and turbocharged engines dominate new vehicle sales, driving demand for API SP and ILSAC GF-6 compliant low-viscosity formulations with gasoline particulate filter protection.
- Commercial Vehicles:Light-duty diesel and gasoline vans for last-mile delivery in Mexico City and Monterrey urban corridors require severe-duty oil change intervals.
- Heavy-Duty Vehicles:Class 8 trucks operating cross-border NAFTA corridors utilize CJ-4 and CK-4 diesel engine oils with extended drain intervals enabled by telematics-based oil condition monitoring.
- Motorcycles:Four-stroke scooter and motorcycle oils for urban mobility in dense metropolitan areas, with JASO MA2 friction certification for wet clutch compatibility.
Passenger vehicles anchor volume demand; heavy-duty vehicles generate premium pricing through specialized formulations.
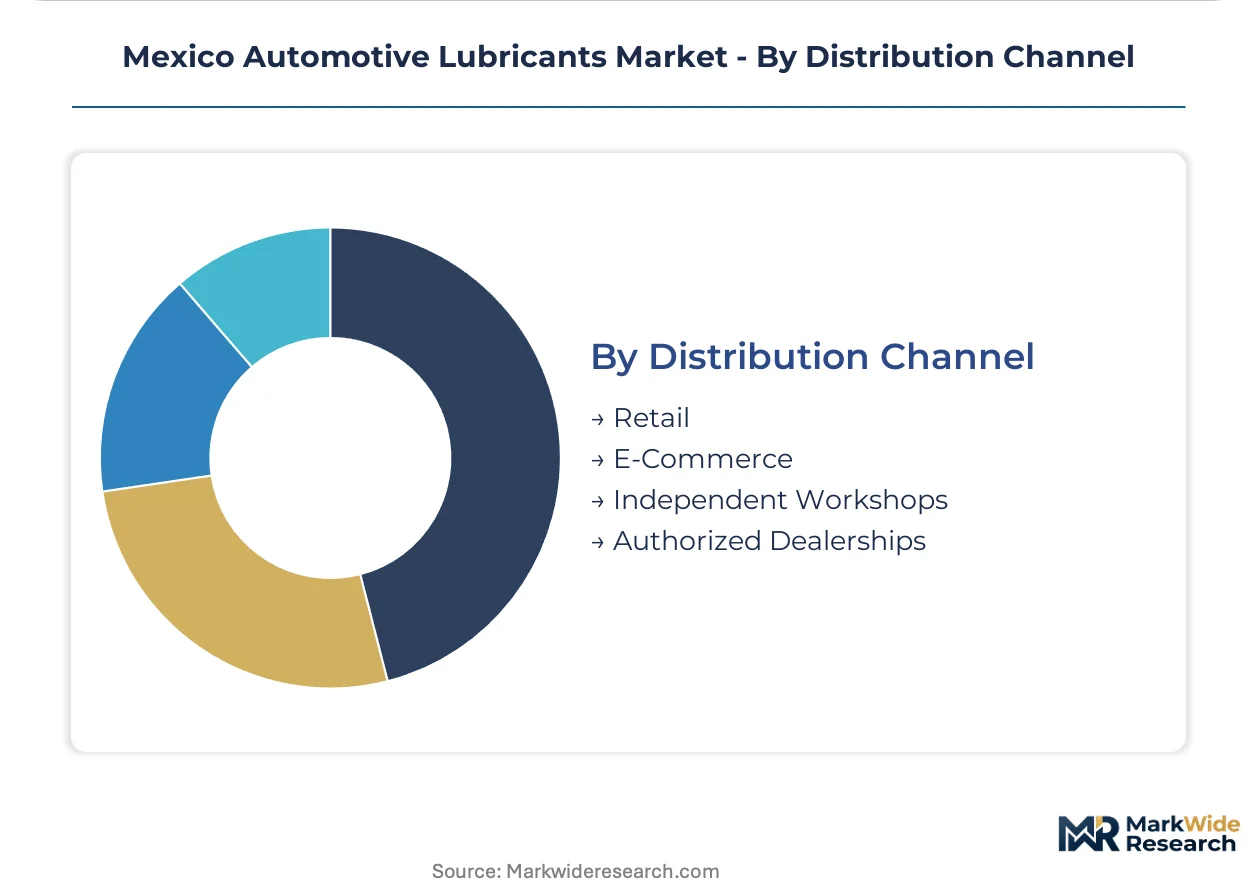
Distribution Channel:
Supply concentration around the Salamanca refining complex shapes logistics economics for each channel archetype.
- Retail:Auto parts chains and hypermarkets in Mexico City, Guadalajara, and Monterrey stock 10-15 SKU portfolios focused on high-visibility passenger car motor oil grades.
- E-Commerce:Mercado Libre and Amazon Mexico platforms capture growing DIY segment share with subscription delivery models for scheduled maintenance intervals.
- Independent Workshops:Fragmented service networks across the Bajío present consolidation targets for brands seeking route-to-market density, though direct fleet procurement erodes their supplier relationships.
- Authorized Dealerships:OEM-aligned service centers enforce proprietary fluid specifications and captive branding for warranty compliance.
Independent workshops retain the broadest geographic footprint; e-commerce climbs fastest as urban DIY penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEMARNAT's NOM-085 emissions standards anchor regulatory pressure across Mexico's automotive lubricant demand centers. State-level enforcement variations and manufacturing corridor expansion reshape procurement patterns in distinct sub-regional markets.
Bajío Region
Ford, GM, and Volkswagen assembly plants in Guanajuato and Querétaro concentrate factory-fill demand for dexos1 Gen3 and API SP formulations. SEMARNAT delegates NOM-085 compliance monitoring to state environmental agencies with uneven inspection intensity. The Salamanca refinery complex supplies Group II base oils to regional blenders serving this manufacturing corridor.
Nuevo León
Monterrey's industrial base drives commercial vehicle fleet operations requiring severe-duty diesel engine oils. PROFECO's quality verification protocols influence consumer trust in retail channels across the metropolitan area. Independent workshops face consolidation pressure as fleet operators bypass direct purchasing relationships through national maintenance contracts.
Mexico City Metro
High-altitude operations and dense urban mobility create specialized demand for brake fluid stability and low-viscosity passenger car motor oils. COFEPRIS chemical substance registrations govern additive import protocols for blenders supplying the capital region. Quick-lube chains expand footprint in Mexico State and Hidalgo as DIY penetration deepens.
Northern Border States
Cross-border NAFTA corridor traffic sustains heavy-duty diesel demand for Class 8 trucks operating between Tijuana, Ciudad Juárez, and Laredo. State-level SEMARNAT enforcement gaps increase environmental liability exposure for used oil collection. Base oil import dependency from US Gulf Coast suppliers exposes blenders to cost volatility.
Jalisco
Guadalajara's automotive aftermarket anchors western Mexico distribution networks with hub-and-spoke logistics to Pacific Coast markets. PROFECO labeling requirements shape retail shelf composition in auto parts chains. E-commerce platforms capture growing DIY segment share with subscription delivery models.
Mexico Automotive Lubricants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexico's lubricant value chain. The market exhibits tiered consolidation with integrated refiners commanding feedstock advantages while independent blenders compete on formulation flexibility and channel proximity. Two strategic archetypes dominate: Salamanca-integrated suppliers with captive base oil supply, and independent formulators with dense workshop network coverage. Competitive moves center on backward integration into base oil production and acquisition of independent service channel capacity.
Among integrated petroleum majors, Shell PLC and ExxonMobil Corporation exemplify the refinery-anchored archetype with upstream control over domestic feedstock supply. BP PLC through its Castrol brand occupies a position within the premium synthetic formulation tier, while Valvoline Inc. represents the independent channel density strategy with workshop-focused distribution. Chevron Corporation and TotalEnergies sit within the multinational integrated tier competing on specification breadth and OEM approval portfolios.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell PLC |
| BP PLC (Castrol) |
| Chevron Corporation |
| TotalEnergies |
| Valvoline Inc. |
| Fuchs Petrolub SE |
| Roshfrans |
| Raloy |
| Others |
Supply & Pricing Matrix
PROFECO quality verification protocols gate both supplier qualification and price differentiation simultaneously, forcing blenders to absorb certification costs while OEMs command premium positioning through factory-fill approvals. This regulatory scaffolding compresses margins for independent formulators serving price-sensitive workshop channels.
Pricing Analysis
Price spreads between Mexico City and Monterrey retail channels reflect inland logistics premiums that independent distributors struggle to pass through. Three-tier pricing structure across premium synthetic, standard mineral, and economy unbranded levels separates OEM-approved formulations from generic alternatives. Cost compression in the economy tier is intensifying because fleet operators consolidate procurement under national contracts. DIY vehicle owners in metropolitan areas exhibit highest price sensitivity, while OEM assembly plants demonstrate least sensitivity given warranty compliance requirements.
Supply Chain Analysis
Container availability constraints on US Gulf Coast to Veracruz lanes inflate inbound logistics costs for additive packages and Group III base oil imports. Domestic supply concentrates around the Salamanca refining complex in Guanajuato, with secondary blending capacity in Nuevo León and Mexico State. Raw material dependencies include hydrocracked base stocks from Shell's Salamanca facility, friction modifier additives imported from US specialty chemical suppliers, and viscosity index improvers from Asian polymer manufacturers. Single-source vulnerability around the Salamanca refinery exposes regional blenders to feedstock disruption. Distribution runs through fragmented independent workshop networks in the Bajío, direct fleet procurement contracts, and retail auto parts chains in major metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-085-SEMARNAT phosphorus limit revisions constitute a technological-regulatory inflection that disrupts incumbent formulation portfolios while opening white space for compliant synthetic suppliers.
For Market Incumbents: Secure captive base oil supply through Salamanca refinery integration or long-term offtake agreements with Shell to defend against feedstock cost volatility. Acquire PROFECO-certified blending technicians through technical training partnerships with regional vocational institutes to resolve capacity expansion bottlenecks. For New Entrants and Emerging Players: Lead with telematics-integrated fluid analysis services targeting heavy-duty fleet operators in Guanajuato state, where channel compression has weakened incumbent distributor relationships. Penetrate the independent workshop consolidation opportunity in Querétaro through white-label formulation partnerships with established regional blenders. For Investors and Strategic Acquirers: NOM-085 compliance deadlines reshape the acquisition landscape toward blenders with advanced additive formulation capabilities and existing OEM approval portfolios. Mid-cap specialists with backward integration into Group III base oil production represent priority targets. Watch for fleet telematics adoption rates as the inflection signal indicating predictive maintenance contract penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply from Salamanca refinery upgrades insulates blenders from US Gulf Coast import volatility. |
| Fleet Telematics Partnership | Oil condition monitoring integration with Grupo Transportes Monterrey enables predictive drain subscription revenue. |
| Independent Workshop Acquisition | Route-to-market density in Bajío corridor counters fleet procurement consolidation bypassing traditional channels. |
| COFEPRIS Registration Streamlining | Accelerated additive import protocols shorten new product introduction cycles for specialized industrial formulations. |
| Synthetic Formulation Capacity Expansion | Group III and PAO blending lines capture OEM factory-fill specifications for turbocharged direct-injection engines. |
Research Methodology
Operator-level perspectives from lubricant blending plant managers, fleet maintenance directors at Bajío transport companies, PROFECO certification auditors, and aftermarket distributor principals anchored the qualitative base. Secondary validation drew from SEMARNAT regulatory filings, customs import records for base oil and additive categories, vehicle production databases tracking OEM assembly plant specifications, and PROFECO quality verification registries. Bottom-up volume estimates triangulated against top-down market sizing derived from refinery output disclosures and distributor channel audits.
Sensitivity analysis tested forecast outputs against variable adoption rates for synthetic formulations and alternative fleet telematics penetration scenarios across the projection horizon. Segmentation dimensions modeled include product viscosity grade, end-user procurement channel, vehicle propulsion architecture, and regional manufacturing cluster concentration. CAGRs were derived from regression analysis of historical replacement interval compression and synthetic penetration curves, incorporating NOM-085 compliance cost pass-through assumptions and base oil supply elasticity parameters.
The analysis sits within stated boundaries; outcomes outside sustained OEM assembly plant expansion in Guanajuato and Querétaro, or delayed NOM-085 enforcement uniformity across state environmental agencies, would require recalibration. Forecasts reflect documented assumptions regarding sulfur fuel quality persistence and additive import protocol stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Slideway Oil Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Vietnam Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market