
 Russia Commercial Vehicles Lubricants Market | 2026-2036
Russia Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Commercial Vehicles Lubricants Market Analytics
A widening capability gap in base oil refining is rotating competitive advantage toward integrated producers. Gazpromneft-Lubricants leverages captive feedstock from parent Gazprom to secure cost stability across Siberian and Far Eastern distribution zones. LUKOIL sustains formulation leadership through its St. Petersburg research complex, while ROSNEFT competes on volume scale via its Omsk and Angarsk blending assets. ExxonMobil Corporation navigates sanctions-adjusted supply chains by repositioning through third-country blending partnerships.
Russia commercial vehicles lubricants encompass mineral, synthetic, and semi-synthetic formulations engineered to withstand extreme thermal cycling from minus fifty degrees Celsius in Arctic regions to sustained high-load operation on Trans-Siberian routes, with primary purpose being friction reduction, wear protection, and extended drain intervals for diesel engines operating under severe duty cycles. Engine oil occupies the dominant value position given per-unit consumption volumes and premium synthetic penetration in long-haul trucking, while hydraulic oil captures expanding share from construction-linked commercial fleets where cold-start pumpability specifications drive formulation complexity. Fleet operators represent the most concentrated end-user segment, with procurement consolidating through direct distributor agreements rather than fragmented retail purchases.
Russia's Technical Regulation of the Customs Union (TR CU 030/2012) governs lubricant quality and labeling requirements, while Rosstandart administers GOST R certification for domestic market access; both frameworks push formulators toward higher base oil group specifications and additive package transparency. The Ministry of Transport's vehicle inspection regime reinforces drain-interval compliance, creating structured replacement demand independent of discretionary fleet spending. Stakeholders must monitor how sanctions-driven supply chain reconfiguration affects additive chemical sourcing and whether domestic Russian additive production scales sufficiently to maintain formulation parity with imported alternatives.
Market Dynamics
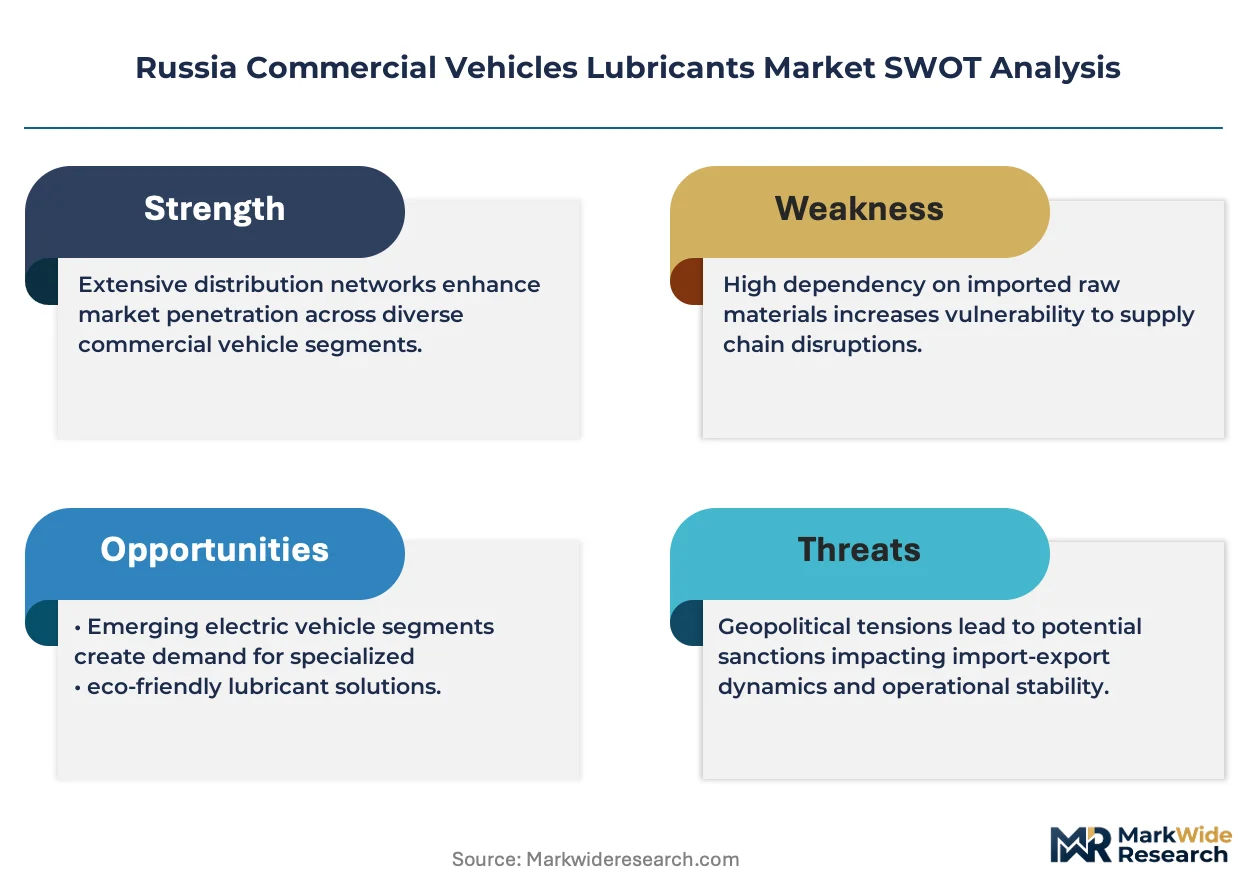
Import substitution mandates from Russia's Ministry of Industry and Trade are restructuring supply chains, forcing formulators to replace imported Group II/III base oils and additive packages with domestic alternatives while maintaining GOST R certification parity. This policy-driven feedstock pivot is compressing margins for non-integrated blenders and rewarding captive refinery operators.
Growth Catalysts
- Eastward logistics corridor expansion:Long-haul trucking volumes along Trans-Siberian routes are rising as trade flows redirect toward China and Central Asia, extending engine duty cycles and synthetic lubricant consumption.
- TR CU 030/2012 enforcement tightening:Rosstandart's enhanced labeling and quality verification protocols are phasing out informal suppliers, consolidating procurement toward certified domestic formulators.
- Arctic fleet cold-start specifications:Minus-fifty-degree operational requirements in Yamal and Vorkuta are mandating advanced pour-point depressant formulations, creating premium product tiers.
Market Restraints
- Base oil Group III import dependency:Sanctions-blocked catalyst and hydrocracker technology from Western licensors constrain domestic production of high-viscosity-index feedstock.
- Additive package concentration:PPD, detergent, and antioxidant chemistries remain concentrated among a narrow set of third-country suppliers, creating single-source vulnerability.
- Extended drain interval ceiling:Current Russian refining capabilities limit synthetic formulation stability beyond 80,000-kilometer claims without imported PAO/ester base stocks.
Strategic Opportunities
- Far Eastern distribution infrastructure:Underdeveloped blending and storage capacity in Khabarovsk and Vladivostok creates first-mover advantage for localized production serving China-border logistics.
- Construction fleet hydraulic oil premiumization:Cold-start pumpability specifications for excavators and cranes in Siberian permafrost zones remain underserved by standard mineral formulations.
- Rosstandart fast-track certification:Streamlined GOST R pathways for formulations using domestically produced base oils incentivize backward integration into refinery operations.
Industry Challenges
- Additive chemist talent scarcity:Soviet-era lubricant formulation expertise has aged out without sufficient university pipeline replacement in tribology and petrochemistry.
- Sanctions-adjusted supply chain reconfiguration:Redirecting additive chemical flows through Central Asian transshipment points extends lead times and complicates batch consistency.
- Legacy fleet compatibility testing:Older Kamaz and Ural engine designs require reformulation validation that delays new synthetic product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Commercial Vehicles Lubricants Market |
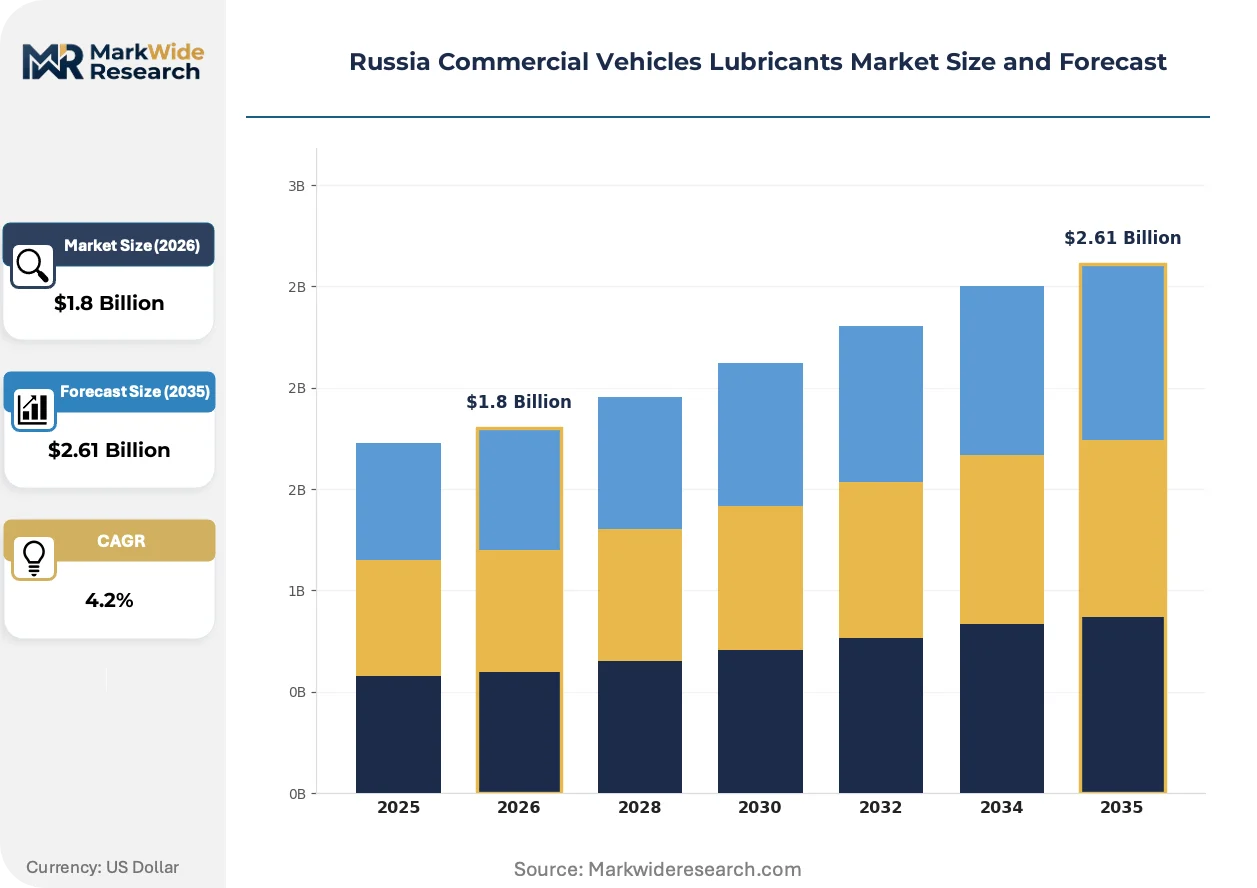
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil Application: Trucks, Buses, Vans, Trailers End User: Fleet Operators, Logistics Companies, Government Agencies, Independent Operators Distribution Channel: Retail Stores, Online Platforms, Distributors, Service Stations |
| Companies Covered | ExxonMobil Corporation, Gazprom, LUKOIL, ROSNEFT, Royal Dutch Shell Plc, DelfinGroup, FUCHS, Gazpromneft-Lubricants, Liqui Moly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Commercial Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and procurement architecture are diverging simultaneously as sanctions pressure and regulatory mandates force parallel adaptation across the value chain. Technology sourcing, compliance frameworks, and buyer behavior are each undergoing distinct recalibration.
Group III+ hydrocracked base oil production is fragmenting competitive advantage away from blenders dependent on imported feedstock. Integrated refinery operators with captive hydrocracker units are capturing margin expansion, while independent formulators face formulation downgrade or supply interruption. This feedstock control asymmetry is fragmenting the mid-tier blender segment into acquisition targets or contract manufacturers.
Rosstandart's 2024 amendments to GOST R 53776-2010 are tightening NOACK volatility and sulfated ash limits for heavy-duty diesel engine oils. The industrial consequence is accelerated obsolescence of Group I mineral formulations in long-haul applications. Fleet operators in the Central Federal District are responding by consolidating procurement around suppliers with certified in-house testing laboratories.
Fleet procurement departments are centralizing lubricant buying decisions away from regional maintenance supervisors. Direct distributor agreements with national blenders are displacing fragmented retail purchases through regional jobbers. This concentration is most visible among Moscow-based logistics consolidators operating 500-plus vehicle fleets on international corridor routes.
Russia Commercial Vehicles Lubricants Market Segmentation
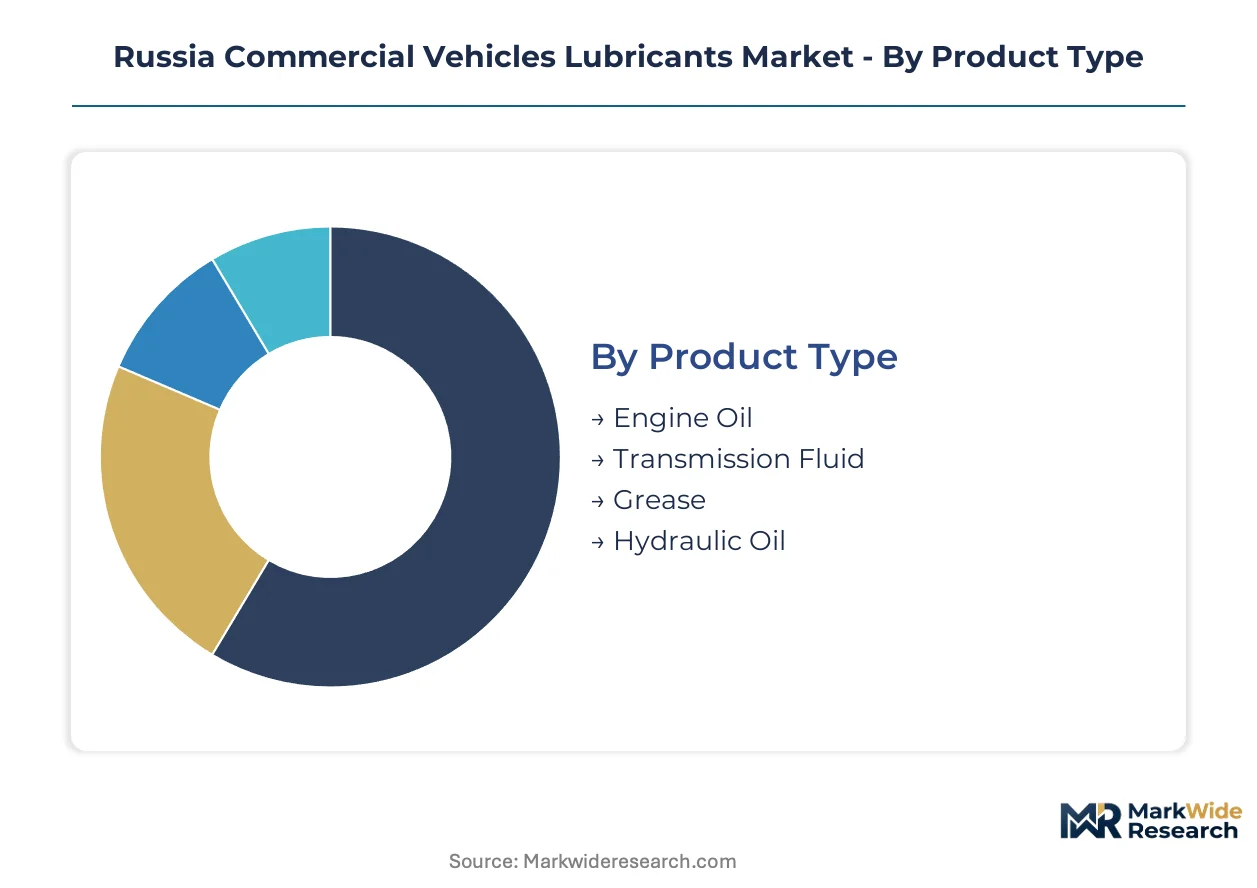
Segmentation in the Russia commercial vehicles lubricants market reveals how procurement authority and technical specifications diverge across buyer types and vehicle duty cycles. Channel configuration and formulation requirements vary sharply between long-haul fleet consolidation and fragmented independent operator purchasing.
Product Type:
Channel-mix patterns show engine oil and hydraulic oil flowing predominantly through direct distributor agreements with fleet operators, while transmission fluid and grease retain higher retail penetration through service stations serving fragmented maintenance shops.
- Engine Oil:Mineral, synthetic, and semi-synthetic formulations engineered for friction reduction and wear protection across extreme thermal cycling from Arctic cold-start to sustained high-load Trans-Siberian operation. Demand concentrates in the Central Federal District around Moscow, where fleet density and premium synthetic penetration in long-haul trucking drive procurement consolidation through direct distributor agreements.
- Hydraulic Oil:Cold-start pumpability specifications tailored for construction-linked commercial fleets operating excavators and cranes in Siberian permafrost zones. Yamal and Vorkuta permafrost operations mandate advanced pour-point depressant formulations, creating premium tiers underserved by standard mineral alternatives.
- Transmission Fluid:Formulations for manual and automated manual transmissions in heavy-duty commercial vehicles.
- Grease:Lubricating greases for chassis, wheel bearings, and universal joints in commercial vehicle maintenance.
Engine oil dominates installed base. Hydraulic oil is where expansion concentrates.
Application:
Volume distribution tracks the eastward logistics corridor expansion, with trucks and trailers capturing disproportionate synthetic lubricant consumption against buses and vans concentrated in urban duty cycles with shorter drain intervals.
- Trucks:Heavy-duty diesel engines operating severe duty cycles across Trans-Siberian routes with extended drain interval requirements. Long-haul trucking volumes redirecting toward China and Central Asia are extending engine duty cycles and synthetic lubricant consumption.
- Trailers:Fifth-wheel, landing gear, and braking system lubrication for intermodal freight equipment. Far Eastern distribution infrastructure in Khabarovsk and Vladivostok creates first-mover advantage for localized production serving China-border logistics corridors.
- Buses:Urban and intercity passenger transport vehicles with stop-start duty cycles.
- Vans:Light commercial vehicles for last-mile delivery and urban logistics.
Trucks anchor volume procurement. Trailers are climbing the fastest on corridor expansion.
End User:
Customer-type concentration shows fleet operators and logistics companies consolidating procurement through national distributor agreements, while government agencies and independent operators sustain fragmented retail channel dependence.
- Fleet Operators:Centralized procurement departments controlling lubricant buying decisions for 500-plus vehicle fleets on international corridor routes. Moscow-based logistics consolidators are displacing fragmented retail purchases through regional jobbers with direct national blender agreements.
- Logistics Companies:Third-party freight operators managing diversified vehicle assets across multiple duty cycles.
- Government Agencies:Municipal and federal fleet procurement subject to public tender regulations.
- Independent Operators:Owner-operators and small fleet maintenance through regional service stations.
Fleet operators dominate procurement consolidation. Logistics companies are gaining share fastest on corridor expansion.
Distribution Channel:
Margin structure varies sharply by channel, with distributors capturing value from fleet consolidation while online platforms and service stations compete on convenience for fragmented demand.
- Distributors:National and regional lubricant distributors with certified in-house testing laboratories meeting Rosstandart's tightened GOST R 53776-2010 amendments. Procurement consolidation around suppliers with verification capabilities is accelerating distributor tier concentration.
- Service Stations:Maintenance facilities providing lubricant change services for independent operators and small fleets.
- Retail Stores:Automotive parts retailers serving walk-in maintenance shops and owner-operators.
- Online Platforms:E-commerce channels for standardized product procurement in remote regions.
Distributors dominate fleet-facing volume. Online platforms are expanding most quickly in Far Eastern coverage gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Central Federal District while Far Eastern markets absorb supply-chain premiums. Regional divergence reflects refinery proximity, fleet density, and sanctions-adjusted logistics costs. Sub-regional dynamics vary sharply across Russia's federal districts.
Central Federal District
Moscow anchors procurement consolidation for 500-plus vehicle fleets operating international corridor routes. The Ministry of Industry and Trade's import substitution mandates accelerate GOST R certification requirements for domestic blenders. Fleet operators in the Moscow region displace fragmented retail purchases through direct national distributor agreements with certified testing laboratories.
Volga Federal District
Omsk and Angarsk blending assets capture volume scale from eastward logistics corridor expansion. Rosstandart's tightened NOACK volatility limits under GOST R 53776-2010 amendments phase out Group I mineral formulations. The Samara-Tolyatti industrial cluster sustains formulation validation for legacy Kamaz engine compatibility testing.
Siberian Federal District
Minus-fifty-degree Arctic specifications in Krasnoyarsk and Irkutsk mandate advanced pour-point depressant formulations. The Ministry of Transport's vehicle inspection regime reinforces drain-interval compliance for Trans-Siberian long-haul operations. Novosibirsk serves as the primary distribution node for synthetic lubricant penetration in severe-duty diesel applications.
Far Eastern Federal District
Underdeveloped blending capacity in Khabarovsk and Vladivostok creates first-mover advantage for localized production serving China-border logistics. Sanctions-adjusted supply chain reconfiguration extends additive chemical lead times through Central Asian transshipment points. The Primorsky Krai port infrastructure redirects trade flows toward Asia-Pacific markets.
Northwestern Federal District
St. Petersburg research complexes sustain formulation leadership for premium synthetic development. The Baltic Sea logistics corridor faces sanctions-blocked catalyst technology constraints for Group III hydrocracked base oil production. Fleet density in the Leningrad Oblast concentrates demand for extended 80,000-kilometer drain interval claims.
Russia Commercial Vehicles Lubricants Market Competitive Landscape
Concentration sits with integrated refinery operators possessing captive hydrocracker units and backward integration into base oil feedstock. The vendor base separates into three tiers: state-controlled energy majors with captive refining, international majors navigating sanctions-adjusted supply chains, and independent blenders facing margin compression. Two dominant competitive moves define positioning: acquisition of mid-tier blenders by integrated operators, and third-country partnership structures for additive chemical sourcing.
Among Russia-based integrated producers, Gazpromneft-Lubricants, LUKOIL, and ROSNEFT occupy distinct positions within the state-controlled tier. Gazpromneft-Lubricants exemplifies captive feedstock advantage through parent-company hydrocarbon access. LUKOIL represents formulation leadership anchored in research infrastructure. ROSNEFT embodies volume-scale positioning through distributed blending assets. These three entities collectively illustrate how refinery integration determines competitive viability under import substitution policy pressure.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Gazprom |
| LUKOIL |
| ROSNEFT |
| Royal Dutch Shell Plc |
| DelfinGroup |
| FUCHS |
| Gazpromneft-Lubricants |
| Liqui Moly |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between fleet operators and integrated blenders lock in both Group III base oil supply access and price visibility across the analysis window, insulating procurement departments from spot market volatility while compressing margins for non-integrated formulators.
Pricing Analysis
The customization-premium spread separates synthetic formulations with Arctic pour-point specifications from standard mineral grades serving urban duty cycles. Three-tier pricing structure across premium, standard, and economy levels tracks GOST R certification tiers and drain interval claims. Cost compression in the mid-tier segment is intensifying because independent blenders lack captive hydrocracker feedstock. Fleet operators with 500-plus vehicle counts exhibit lowest price sensitivity, while owner-operators through retail channels drive hardest bargain.
Supply Chain Analysis
Russia and Kazakhstan anchor regional base oil production through Omsk, Angarsk, and Pavlodar refining complexes. Domestic supply draws from captive refinery output, yet additive chemistries rest on third-country sourcing through Central Asian transshipment. Single-source vulnerability concentrates in pour-point depressant and detergent packages. Distribution runs through national lubricant distributors with certified testing laboratories serving fleet direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement centralization around direct distributor agreements signals platform-economics inflection, with interoperability between telematics drain monitoring and automated reorder systems reshaping buyer-supplier relationships.
For Market Incumbents: Compound formulation leadership through backward integration into domestic additive production, countering sanctions-driven supply interruption. Expand certified testing laboratory networks in the Far Eastern Federal District to capture China-border logistics corridor demand. Rosstandart's tightened GOST R enforcement phases out informal competitors.
For New Entrants and Emerging Players: Differentiate on cold-start pumpability specifications for construction fleet hydraulic applications in Siberian permafrost zones. Target underdeveloped blending capacity in Khabarovsk and Vladivostok as geographic white space. Pursue fast-track GOST R certification for formulations using wholly domestic base oil feedstock.
For Investors and Strategic Acquirers: Mid-tier independent blenders with established fleet distributor relationships but lacking refinery integration represent prime acquisition targets. Long-term viability hinges on additive package self-sufficiency within the strategic planning horizon. Watch domestic PAO/ester base stock production scale as inflection indicator for synthetic formulation parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Production | Captive supply of detergent and PPD chemistries reduces sanctions exposure for integrated blenders. |
| Far Eastern Distribution Infrastructure Buildout | Localized blending in Khabarovsk and Vladivostok captures China-border logistics corridor expansion. |
| GOST R Certification Fast-Track Investment | Rosstandart streamlined pathways reward domestic base oil formulations with accelerated market access. |
| Telematics-Integrated Fleet Procurement Platforms | Automated drain monitoring and reorder interoperability consolidates buyer power around national distributors. |
| Arctic Specification Formulation Development | Minus-fifty-degree pour-point capabilities command premium positioning in Yamal and Vorkuta operations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, lubricant formulators, refinery operations managers, and Rosstandart certification officials; and secondary validation through customs trade records, Ministry of Industry and Trade import substitution policy documents, GOST R regulatory filings, and base oil production statistics. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Across the projection horizon, the analytical framework modeled engine oil, hydraulic oil, transmission fluid, and grease segments by trucks, trailers, buses, and van applications. CAGRs derived from fleet expansion rates, drain interval extension trends, and synthetic penetration curves in severe-duty diesel operations. Forecast inputs incorporated eastward logistics corridor volume shifts and Arctic fleet cold-start specification mandates.
The analysis sits within stated boundaries; outcomes outside sustained import substitution policy enforcement or additive chemistry supply continuity would require recalibration. Forecasts reflect assumptions on domestic base oil Group III production scale and sanctions-adjusted supply chain reconfiguration stability. Recalibration cycles align with material shifts in Rosstandart regulatory amendments and Ministry of Transport inspection regime changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Marine Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Synthetic Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Drilling Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Global Compressor Oil Market