
 Colombia Automotive Lubricants Market | 2026-2036
Colombia Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Automotive Lubricants Market Outlook
Multi-source procurement among national distributors is broadening access to synthetic and semi-synthetic formulations across Colombia's Andean region. Terpel anchors its position through captive refining infrastructure and nationwide fuel-station retail networks. Shell plc competes via technology leadership in low-viscosity grades suited to local temperature extremes. Petrobras leverages its Brazilian supply base to sustain cost-competitive positioning in bulk fleet contracts.
Automotive lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission systems; typical motor oils achieve viscosity grades between SAE 0W-16 and 20W-50 through Group II or Group III base stock blending with detergent-dispersant and anti-wear chemistries. Motor oil dominates product-type revenue due to high replacement frequency across Colombia's aging passenger vehicle parc, while transmission fluid represents the fastest-growing category as automatic gearbox penetration rises in urban commercial fleets. Among applications, heavy-duty trucks command premium pricing through extended-drain specifications, whereas motorcycle lubricants occupy a high-volume, margin-compressed tier serving informal mechanics.
Colombia's Ministry of Mines and Energy enforces biofuel blending standards that directly affect lubricant additive compatibility, while the National Institute of Metrology (INM) certifies product quality under NTC technical regulations aligned with ASTM and SAE benchmarks. The Superintendency of Industry and Commerce monitors anticompetitive distribution practices that constrain workshop-level channel access. Stakeholders must track impending sulfur-content revisions and base oil import tariff adjustments to calibrate formulation and sourcing strategies.
Market Dynamics
Biofuel blending mandates from Colombia's Ministry of Mines and Energy are forcing reformulation of base oil chemistries, creating ripple effects across additive compatibility, drain intervals, and warranty positioning for lubricant suppliers serving the Andean market.
Growth Catalysts
- Extended-drain specifications:Heavy-duty fleet operators in Bogotá's logistics corridor are adopting synthetic formulations that stretch service intervals, reducing total cost of ownership and locking in premium product demand.
- Automatic transmission penetration:Urban commercial fleets across Medellín's industrial zone are replacing manual gearboxes, generating fresh demand for specialized transmission fluids with friction-modifier packages.
- NTC quality enforcement:Colombia's technical regulations aligned with ASTM benchmarks are squeezing informal blenders out of formal channels, consolidating volume with certified suppliers.
Market Restraints
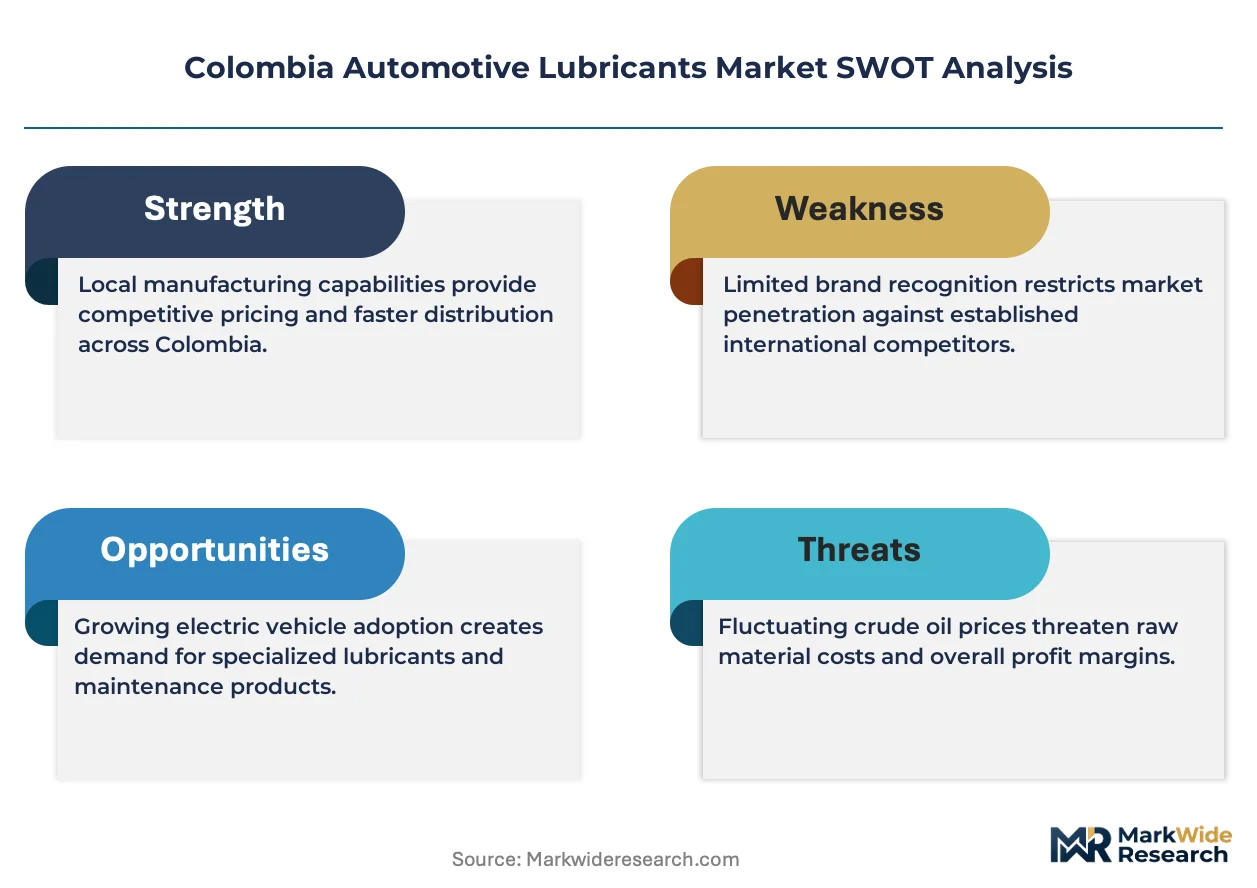
- Group II/III base oil import dependence:Domestic refining capacity constraints force Colombian blenders to source base stocks from Brazilian and US Gulf Coast suppliers, exposing margins to freight volatility and currency fluctuation.
- Bioethanol additive incompatibility:E10 and E20 blending mandates degrade conventional seal materials and detergent packages, requiring costly reformulation that smaller distributors cannot absorb.
- Used oil collection infrastructure gaps:Informal reclaimers in peripheral municipalities capture an estimated majority of drain volume, blocking circular economy participation by organized distributors.
Strategic Opportunities
- Cali-Pacific corridor penetration:Buenaventura port logistics and Valle del Cauca agro-industrial machinery remain underserved by synthetic product distribution, offering first-mover positioning.
- Two-wheeler service bundling:Motorcycle parc density in secondary cities creates openings for integrated oil-change-plus-maintenance packages targeting informal mechanic networks.
- Carbon accounting alignment:Colombia's gradual adoption of EU-style sustainability reporting standards positions bio-based and re-refined lubricant lines for preferential procurement by state-linked fleet operators.
Industry Challenges
- Formulation chemist scarcity:Local technical universities produce insufficient lubricant-specific chemical engineers, forcing blenders to import talent or accept extended product development cycles.
- Workshop certification complexity:INM laboratory accreditation requirements for quality claims demand capital investment in spectroscopic testing equipment that mid-tier distributors struggle to justify.
- Multi-grade inventory management:Temperature variation across Colombia's altitudinal zones forces distributors to stock 0W-20 through 20W-50 simultaneously, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Automotive Lubricants Market |
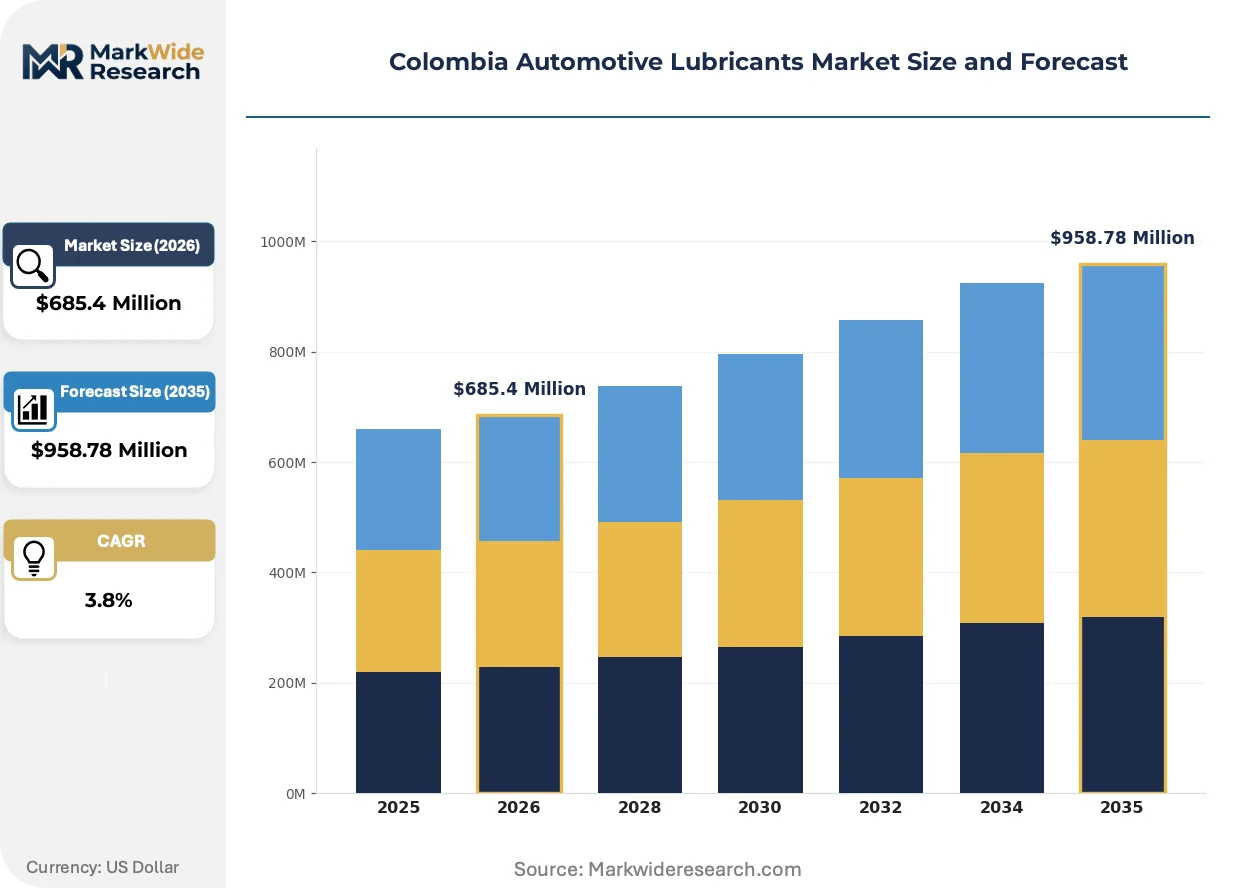
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $958.78 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Oil, Gear Oil, Transmission Fluid, Brake Fluid Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Retail Outlets, Authorized Dealers, Online, Service Stations End User: Fleet Owners, Individual Consumers, Workshops, Auto Manufacturers |
| Companies Covered | BP p.l.c., TotalEnergies, Terpel, Motul, Petrobras, Shell plc, BioMax, Primax, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Automotive Lubricants Market Strategic Shifts
Formulation chemistry and distribution logistics are undergoing parallel transformation as electrification, regulatory tightening, and fleet professionalization reshape how lubricants are specified, sold, and consumed across Colombian territory.
Low-viscosity motor oils formulated with Group III base stocks and advanced polymer thickeners are electrifying the passenger vehicle segment, with Bogotá-based dealer networks now defaulting to 0W-20 and 5W-30 grades for post-2020 engine platforms. These formulations reduce cold-start friction losses that dominate urban fuel consumption patterns. The shift is compressing demand for conventional 15W-40 and 20W-50 products toward the motorcycle and aged-vehicle aftermarket.
Colombia's Ministry of Mines and Energy is tightening sulfur-content ceilings in transport fuels, which indirectly elevates combustion chamber deposits and places new detergent-dispersant demands on crankcase lubricants. Blenders must now balance ash content against exhaust aftertreatment compatibility for Euro-VI-equivalent trucks entering through Andean corridor import channels. This regulatory vector favors additive suppliers with heavy-duty diesel credentials over generalist formulators.
Fleet procurement desks in Medellín and Cali are consolidating supplier relationships through annual framework agreements that bundle lubricant supply with used-oil collection and condition-monitoring services. This procurement evolution displaces spot purchasing through traditional distributor networks, concentrating volume with suppliers capable of delivering field-based oil analysis and drain-interval optimization. The pattern is most visible in refrigerated transport and construction equipment verticals where uptime economics dominate total cost calculations.
Colombia Automotive Lubricants Market Segmentation
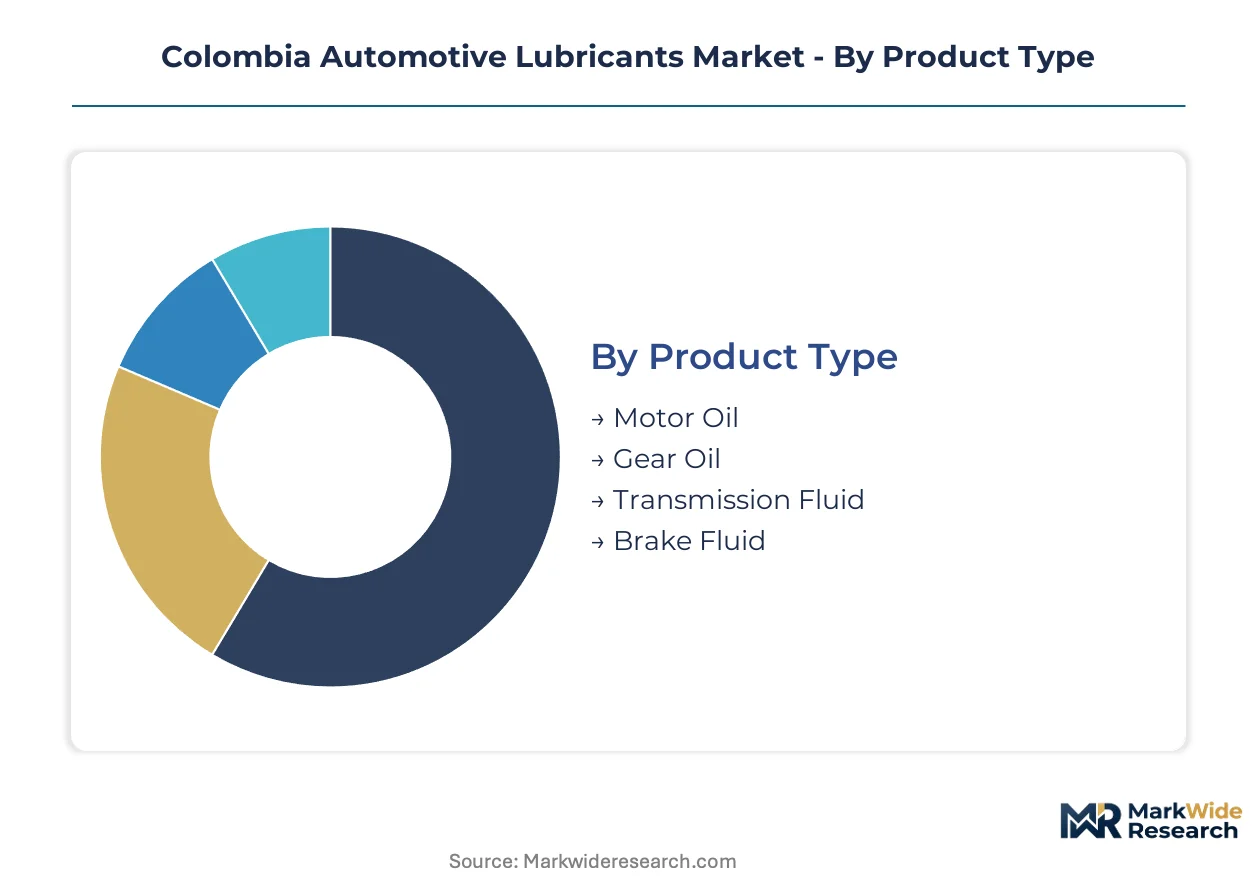
Segmentation reveals how lubricant demand fragments across vehicle technologies, procurement behaviors, and service channel structures in Colombia's Andean geography. Understanding these divisions exposes where formulation investments concentrate and where distribution economics favor synthetic over mineral products.
Product Type:
Replacement cycles and drain-interval economics differentiate lubricant chemistry investments across engine, transmission, and braking systems.
- Motor Oil:Formulated from Group II or Group III base stocks with detergent-dispersant and anti-wear additive packages, achieving viscosity grades from SAE 0W-16 through 20W-50. Demand clusters in Bogotá's metropolitan service cluster where aging passenger vehicle parc drives high-frequency change intervals and synthetic upgrade penetration.
- Transmission Fluid:Specialized formulations containing friction-modifier packages engineered for automatic gearbox thermal stability and shift quality. Urban commercial fleets across Medellín's industrial corridor are converting from manual transmissions, accelerating specification of premium synthetic ATF grades with extended service life.
- Gear Oil:Extreme-pressure lubricants for differential and axle assemblies, formulated with sulfur-phosphorus additive chemistry for heavy-load protection.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3, DOT 4, or DOT 5.1 specifications for high-temperature braking system operation.
Volume placements concentrate in motor oil; the faster expansion belongs to transmission fluid.
Application:
Vehicle duty cycles and operating severity determine lubricant performance tier selection and procurement channel preferences.
- Heavy-Duty Trucks:Extended-drain synthetic formulations engineered for Euro-VI-equivalent engines operating in high-altitude Andean corridors. Fleet operators in Bogotá's logistics zone specify premium CK-4 and FA-4 grades to maximize uptime and compress total maintenance cost.
- Passenger Vehicles:Low-viscosity motor oils (0W-20, 5W-30) dominating post-2020 engine platforms for fuel economy compliance. Dealer networks in major metropolitan centers now default to synthetic products, displacing conventional mineral oils to independent workshop channels.
- Commercial Vehicles:Light and medium-duty trucks requiring balanced cost-performance lubrication for mixed urban-highway operation.
- Motorcycles:High-volume, margin-compressed mineral and semi-synthetic grades serving informal mechanic networks in secondary cities.
Revenue intensity peaks with heavy-duty trucks; motorcycle applications deliver volume scale at compressed margin.
Distribution Channel:
Channel structure determines product authentication, technical support access, and inventory carrying cost allocation.
- Authorized Dealers:OEM-captive distribution with certified technician training and warranty-compliant service protocols. New vehicle sales channels in Bogotá and Medellín anchor synthetic product penetration through bundled maintenance packages.
- Service Stations:Fuel-retail-integrated lubricant sales leveraging captive refining infrastructure and nationwide geographic coverage. Terpel's network exemplifies this channel's reach into intermediate municipalities beyond metropolitan cores.
- Retail Outlets:General automotive parts stores and hypermarket lubricant sections serving DIY consumers and small independent workshops.
- Online:Emerging direct-to-consumer and B2B procurement platforms with logistics constraints outside major urban centers.
Transaction density favors authorized dealers; service stations extend geographic coverage most effectively.
End User:
Procurement sophistication and total cost economics separate volume buyers from price-sensitive spot purchasers.
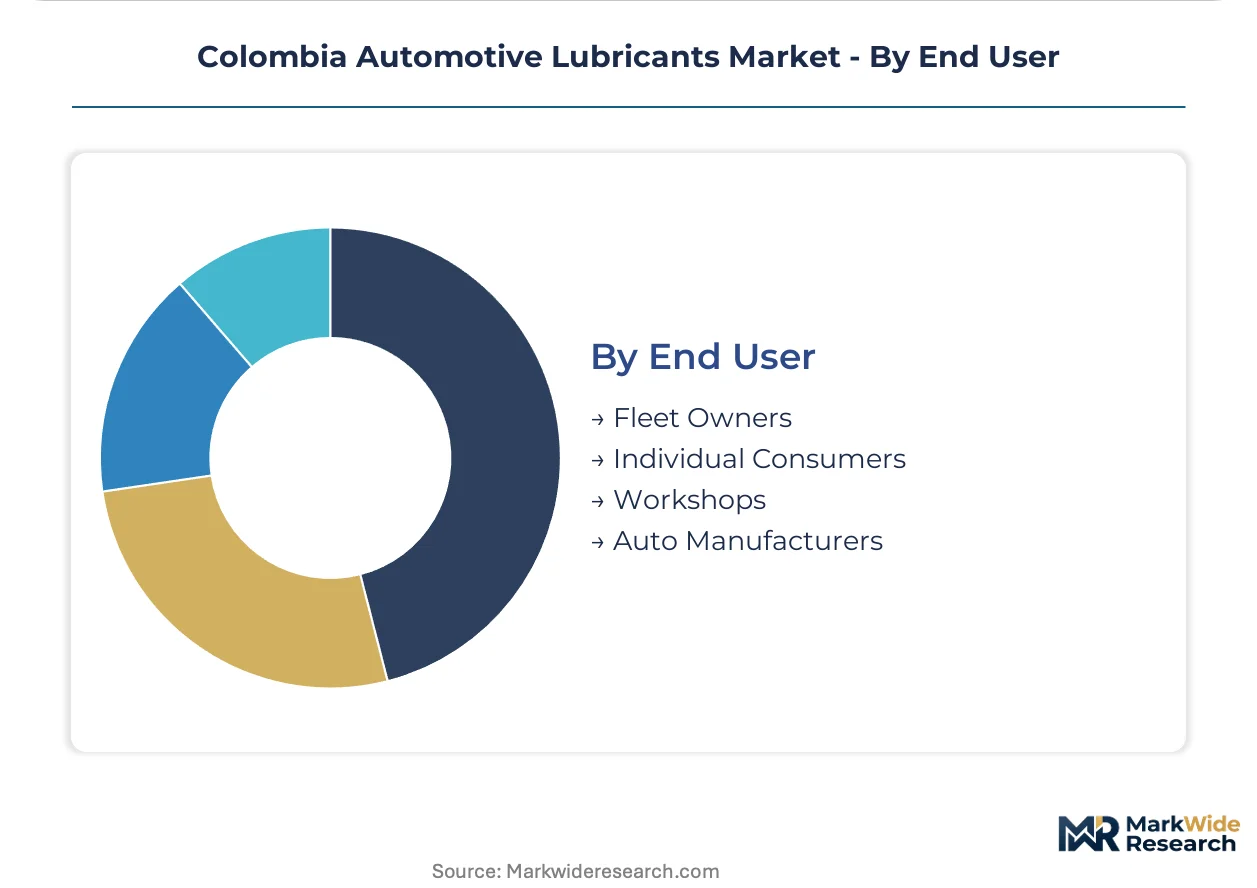
- Fleet Owners:Professional procurement desks negotiating annual framework agreements bundling lubricant supply with condition monitoring and used-oil collection. Refrigerated transport and construction verticals in Medellín and Cali exemplify this segment's uptime-driven specification behavior.
- Workshops:Independent and chain-affiliated service providers balancing inventory cost against customer price sensitivity. INM certification requirements for quality claims favor larger workshop groups with capital for spectroscopic testing equipment.
- Individual Consumers:Price-conscious purchasers selecting lubricants based on brand recognition and immediate availability rather than technical specification.
- Auto Manufacturers:Factory-fill procurement decisions influencing aftermarket specification through warranty tie-ins and dealer network training.
Margin capture concentrates with fleet owners; workshop networks mediate the largest volume flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andean base oil logistics and Caribbean port access anchor Colombia's lubricant distribution architecture, with domestic blending capacity concentrated near Barrancabermeja's refining complex and imported additive packages flowing through Cartagena's maritime terminals.
Bogotá Metropolitan Cluster
Extended-drain synthetic formulations dominate procurement among refrigerated transport fleets and construction equipment operators seeking uptime optimization. Colombia's Ministry of Mines and Energy enforces biofuel blending standards that force reformulation of crankcase lubricants for E10 and E20 compatibility. The Sabana industrial corridor hosts the densest concentration of authorized dealer networks and fleet procurement desks negotiating annual framework agreements.
Medellín Industrial Corridor
Automatic transmission fluid demand accelerates as urban commercial fleets replace manual gearboxes in light and medium-duty distribution vehicles. Antioquia's environmental authority monitors used oil collection compliance, though informal reclaimers still capture majority drain volume in peripheral municipalities. The Aburrá Valley's manufacturing zones concentrate condition-monitoring service providers bundling lubricant supply with oil analysis.
Cali-Pacific Corridor
Buenaventura port logistics and Valle del Cauca agro-industrial machinery remain underserved by synthetic product distribution, creating first-mover positioning for suppliers extending coverage from established Andean hubs. The regional government promotes logistics infrastructure investment linking Pacific maritime access to interior consumption centers. Palm oil processing and sugarcane harvesting equipment generate seasonal demand spikes for heavy-duty hydraulic fluids and gear lubricants.
Barrancabermeja Refining Zone
Domestic Group II base stock production from Ecopetrol's refinery reduces import dependence for regional blenders serving Santander and neighboring departments. The National Institute of Metrology certifies product quality at local laboratories, though formulation chemist scarcity forces extended product development cycles. Captive refining infrastructure supports cost-competitive positioning in bulk fleet contracts across northeastern Colombia.
Caribbean Coastal Cities
Cartagena and Barranquilla function as import gateways for additive packages and finished lubricants from US Gulf Coast and Brazilian suppliers. Port logistics and free trade zone status attract distributors establishing regional warehousing for northern Colombia and Venezuelan border trade. Coastal temperature extremes and marine corrosion environments drive specification of high-detergent formulations for commercial fishing and port handling equipment.
Colombia Automotive Lubricants Market Competitive Environment
Capacity expansion dominates the current landscape as national distributors broaden synthetic and semi-synthetic formulation access across Colombia's Andean region. The market structure concentrates around three archetypes: integrated refiners with captive retail networks, international majors leveraging technology licensing, and regional distributors dependent on imported base stocks. M&A activity and strategic partnerships between additive suppliers and local blenders represent the primary competitive vectors reshaping channel control.
Among integrated energy conglomerates, Terpel anchors market presence through nationwide fuel-station retail networks and captive refining infrastructure. Shell plc and BP p.l.c. occupy positions defined by technology leadership in low-viscosity grades and global formulation expertise. Petrobras leverages its Brazilian supply base to sustain cost-competitive positioning in bulk fleet contracts, while TotalEnergies and Chevron Corporation represent the international major tier competing through premium product portfolios and OEM relationships.
| Leading Market Players |
|---|
| BP p.l.c. |
| TotalEnergies |
| Terpel |
| Motul |
| Petrobras |
| Shell plc |
| BioMax |
| Primax |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
Group II and Group III base oil indices from US Gulf Coast and Brazilian suppliers cascade through Colombian blending operations into three distinct pricing tiers: premium synthetic formulations with extended-drain warranties, mid-grade semi-synthetics for fleet frameworks, and economy mineral oils serving informal channels. Currency fluctuation against the dollar amplifies tier separation, compressing margins on unbundled spot transactions while reinforcing annual contract premiums.
Pricing Analysis
Warranty bundling separates premium from standard tiers—synthetic grades include OEM-backed drain-interval guarantees and condition-monitoring services, while economy products carry no performance assurances and flow through cash-only mechanic networks. Price differentiation hinges on certification grade under INM-NTC standards and volume scale in fleet procurement. Cost compression in the mineral tier is intensifying because informal reclaimers undercut organized collection economics. Individual consumers in secondary cities exhibit highest price sensitivity; refrigerated transport fleets in Bogotá show least sensitivity due to uptime economics.
Supply Chain Analysis
Dual-sourcing requirements from major fleet operators force blenders to qualify both Brazilian and US Gulf Coast base oil suppliers simultaneously, preventing single-origin dependency. Geographic supply concentration centers on Brazil, the United States, and domestic Ecopetrol production from Barrancabermeja. Raw material dependencies span Group II/III base stocks, detergent-dispersant additive packages, and viscosity modifier polymers. Single-source vulnerability persists in specialized friction-modifier chemistries for automatic transmission fluids. Distribution runs through authorized dealer networks in metropolitan cores, Terpel's fuel-station retail footprint in intermediate municipalities, and informal channels in peripheral zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's automotive lubricants sector is becoming a vertical-integration race as players pursue captive refining infrastructure to offset import exposure and currency volatility.
For Market Incumbents: Anticipate biofuel mandate escalation by pre-positioning E20-compatible seal and detergent formulations before regulatory deadlines compress reformulation timelines. Secure backward integration into additive blending or captive base oil sourcing to defend margin position against Brazilian import cost swings. Consolidate workshop certification networks to lock out informal competitors lacking INM laboratory accreditation capital. For New Entrants and Emerging Players: Colombia's Ministry of Mines and Energy biofuel blending standards open a window for specialty additive suppliers offering ethanol-compatible chemistry packages to mid-tier blenders lacking in-house formulation capability. Target the Cali-Pacific corridor's synthetic distribution gap through Buenaventura port logistics relationships. Pursue two-wheeler service bundling in secondary cities where motorcycle parc density exceeds organized maintenance penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier distributors with established fleet relationships in Medellín and Cali but strained working capital from multi-grade inventory requirements. Long-term viability hinges on synthetic product mix expansion and carbon-accounting alignment for state-linked procurement. Watch for sulfur-content ceiling revisions and base oil import tariff adjustments as inflection indicators for formulation strategy shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive sourcing from Ecopetrol or Brazilian partners reduces currency exposure for blenders serving Andean fleet contracts. |
| Workshop Certification Network Expansion | INM-accredited service partnerships lock in synthetic product penetration against informal mechanic channels in secondary cities. |
| E20-Compatible Formulation Development | Ethanol-resistant seal and detergent packages align with Ministry of Mines and Energy mandates for biofuel blending compliance. |
| Condition-Monitoring Service Bundling | Oil analysis and drain-interval optimization deepen fleet relationships in Bogotá's refrigerated transport vertical. |
| Pacific Corridor Distribution Buildout | Buenaventura port access and Valle del Cauca agro-industrial coverage capture underserved synthetic demand in western Colombia. |
Study Parameters
Document review covered customs and trade data, Ecopetrol refining disclosures, and NTC technical regulations, complemented by interviews with lubricant formulation chemists, fleet procurement managers at refrigerated transport operators, aftermarket distributors in Bogotá and Medellín, and workshop network operators. Secondary validation drew from Ministry of Mines and Energy policy filings, INM certification records, and base oil import statistics. Bottom-up volume builds across product types and applications were triangulated against top-down macroeconomic drivers.
Segment-level projections across motor oil, transmission fluid, gear oil, and brake fluid categories were generated using vehicle parc aging curves, automatic transmission penetration rates, and biofuel mandate implementation timelines across the analysis window. CAGRs were derived from elasticity modeling of synthetic upgrade adoption against total cost of ownership calculations. Key inputs included heavy-duty truck fleet expansion in Andean logistics corridors and motorcycle parc density in secondary urban centers.
The model assumes a particular technology adoption path; alternative pathways for electric vehicle powertrain penetration would alter the outlook for crankcase lubricant demand intensity. Deviation in biofuel blending mandate enforcement timelines or base oil import tariff schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Engine Oil Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Automotive Differential Housing Market