
 Industrial Bearings Market | 2026-2036
Industrial Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Bearings Market Foresight
Robotics adoption across manufacturing floors is realigning procurement patterns toward precision bearing solutions. SKF Group leverages its sensor-integrated bearing platforms to capture value in predictive maintenance contracts. Timken Company sustains dominance in tapered roller configurations for heavy-industry deployments. Schaeffler Group differentiates through ceramic hybrid bearings targeting electric drivetrain thermal envelopes.
Industrial bearings are precision-engineered mechanical components that constrain relative motion to desired movements while reducing friction between rotating and stationary machine parts, typically manufactured from through-hardened alloy steel with raceway geometries ground to micron-level tolerances. Their primary industrial purpose centers on load transmission, shaft support, and operational longevity across rotating equipment in continuous-process environments. Roller bearings occupy the largest value share due to their superior radial load capacity in mining and construction machinery, while ceramic material variants represent the fastest-expanding margin pool as electrification drives thermal performance requirements. Ball bearings retain maturity in standardized conveyor and pumping applications where cost optimization outweighs specification intensity.
The US EPA enforces material restrictions on lubricant formulations used in bearings deployed near sensitive waterways, compelling suppliers to reformulate grease chemistries. EMA's machinery safety directives in Europe mandate documented fatigue-life testing for bearings integrated into medical and aerospace equipment. China's GB standards and MIIT industrial upgrading policies enforce localization ratios that reshape supply chain configurations for foreign-owned bearing plants. Stakeholders must monitor how dual carbon compliance timelines in China and the EU Green Deal's embodied-carbon tracking requirements alter raw-material sourcing economics for steel and ceramic feedstocks.
Market Dynamics
Robotics integration on manufacturing floors is compressing procurement cycles toward precision bearing specifications, forcing suppliers to realign production capacity from standardized to micron-tolerance product lines.
Growth Catalysts
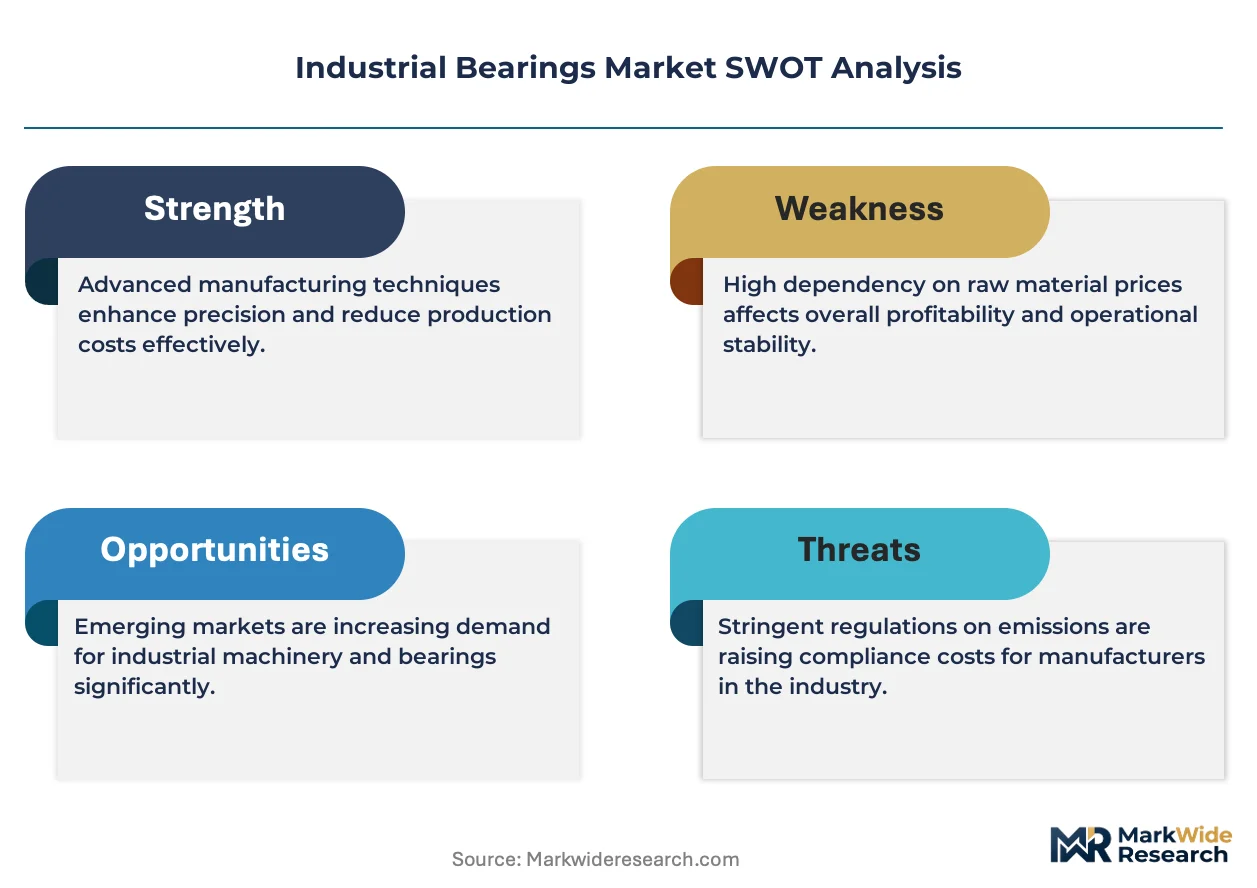
- REACH compliance in Europe:Stricter material specifications for high-load applications are filtering out low-grade suppliers and concentrating demand among certified precision manufacturers.
- Electric drivetrain thermal envelopes:Ceramic hybrid bearings are capturing specification share as electrification pushes operating temperatures beyond conventional steel limits.
- Germany's industrial heartland:Automotive and machinery OEMs anchor premium bearing consumption, creating a concentrated demand pool that rewards localized technical service capabilities.
Market Restraints
- Alloy steel feedstock volatility:Through-hardened steel prices fluctuate with scrap metal markets and energy costs, compressing margin predictability for standardized product lines.
- China's localization mandates:MIIT industrial upgrading policies enforce domestic content ratios that fragment supply chain configurations for foreign-owned bearing plants.
- Sliding bearing substitutes:Magnetic levitation and air-bearing technologies are displacing mechanical bearings in ultra-high-speed spindles above 50,000 RPM.
Strategic Opportunities
- Sensor-integrated predictive maintenance:IoT-enabled bearing platforms create recurring revenue streams through condition-monitoring service contracts.
- India's PLI scheme for manufacturing:Production-linked incentives for machinery and auto components are drawing bearing capacity toward subcontinent assembly hubs.
- EU Green Deal embodied-carbon tracking:Steel and ceramic feedstock provenance documentation opens premium pricing for low-carbon bearing variants.
Industry Challenges
- Grinding technician scarcity:Raceway geometry finishing requires 5-7 year apprenticeship pipelines that regional labor markets struggle to populate.
- ISO 281 fatigue-life certification timelines:Medical and aerospace equipment mandates extend validation cycles to 18-24 months, delaying revenue recognition.
- Legacy ERP integration:Smart bearing data streams require retrofitting MES systems on 15-20 year-old plant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Bearings Market |
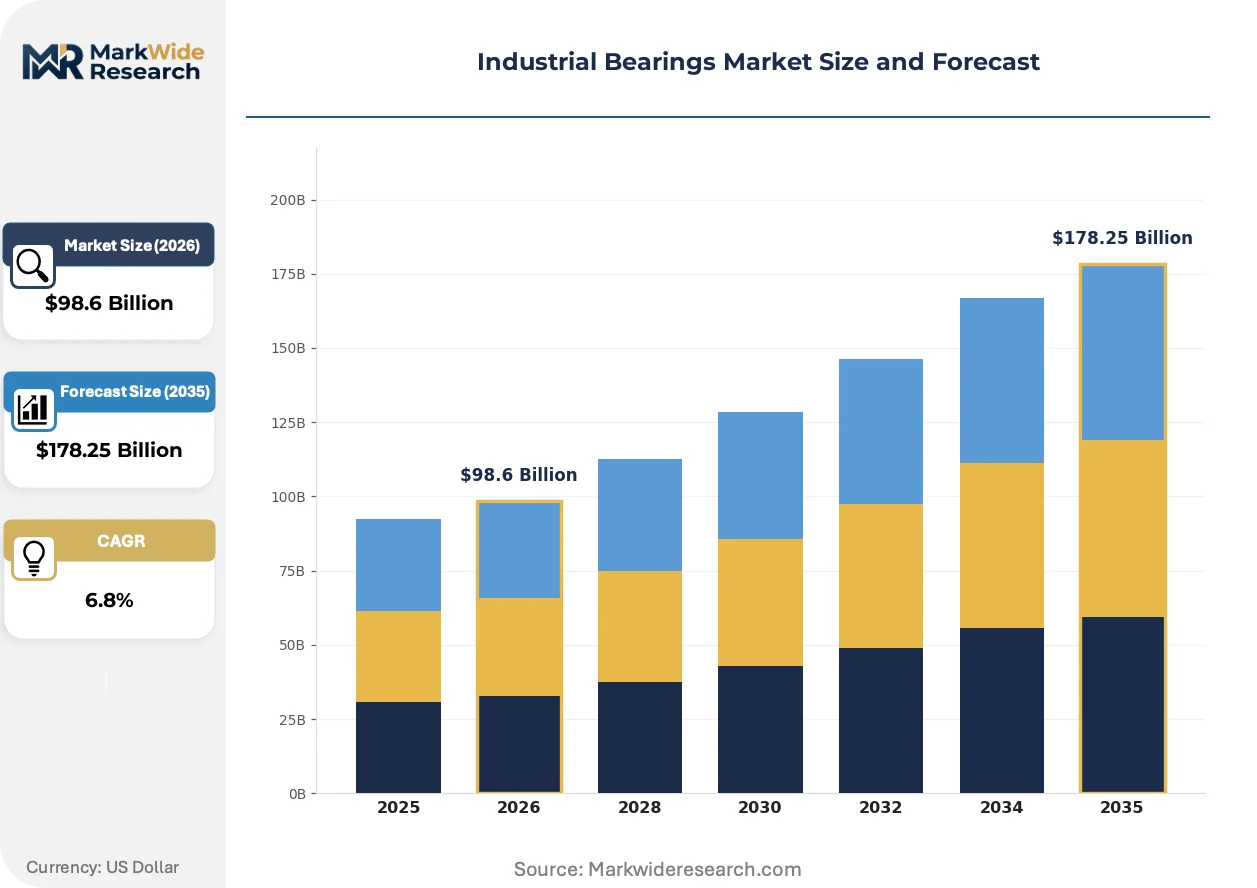
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Thrust Bearings, Sleeve Bearings End User: Aerospace, Automotive Manufacturing, Construction, Mining Material: Steel, Ceramic, Plastic, Composite Application: Robotics, Conveyors, Pumping Systems, Textile Machinery |
| Companies Covered | Timken Company, JTEKT Corporation, SKF Group, RBC Bearings Incorporated, NACHI-Fujikoshi Corp., NSK Ltd., Schaeffler Group, Kaydon Bearings, NTN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Bearings Market Shifts & Advancements
Digitalization is threading through bearing value chains, converting mechanical components into data-generating nodes that reshape how industrial buyers evaluate total cost of ownership.
Ceramic hybrid bearing architectures are overtaking conventional steel configurations in electric vehicle drivetrains and wind turbine gearboxes. Automotive OEMs specify silicon nitride rolling elements for thermal stability above 150°C operating envelopes. This material transition is compressing supplier qualification timelines and favoring manufacturers with in-house ceramic sintering capabilities.
EPA emissions rules on lubricant formulations near sensitive waterways are compelling grease chemistry reformulation across US-deployed bearing portfolios. Industrial users in pulp and paper, food processing, and marine applications face compliance-driven specification changes. Bearing suppliers with biobased lubricant partnerships capture specification share in watershed-proximate installations.
Aftermarket service unbundling is fragmenting traditional distributor relationships in North American industrial maintenance. End-users source bearings directly from manufacturers while contracting lubrication and installation to specialized field service providers. This channel bifurcation is most visible in Texas and Louisiana petrochemical corridors where integrated service contracts once dominated procurement.
Industrial Bearings Market Segmentation
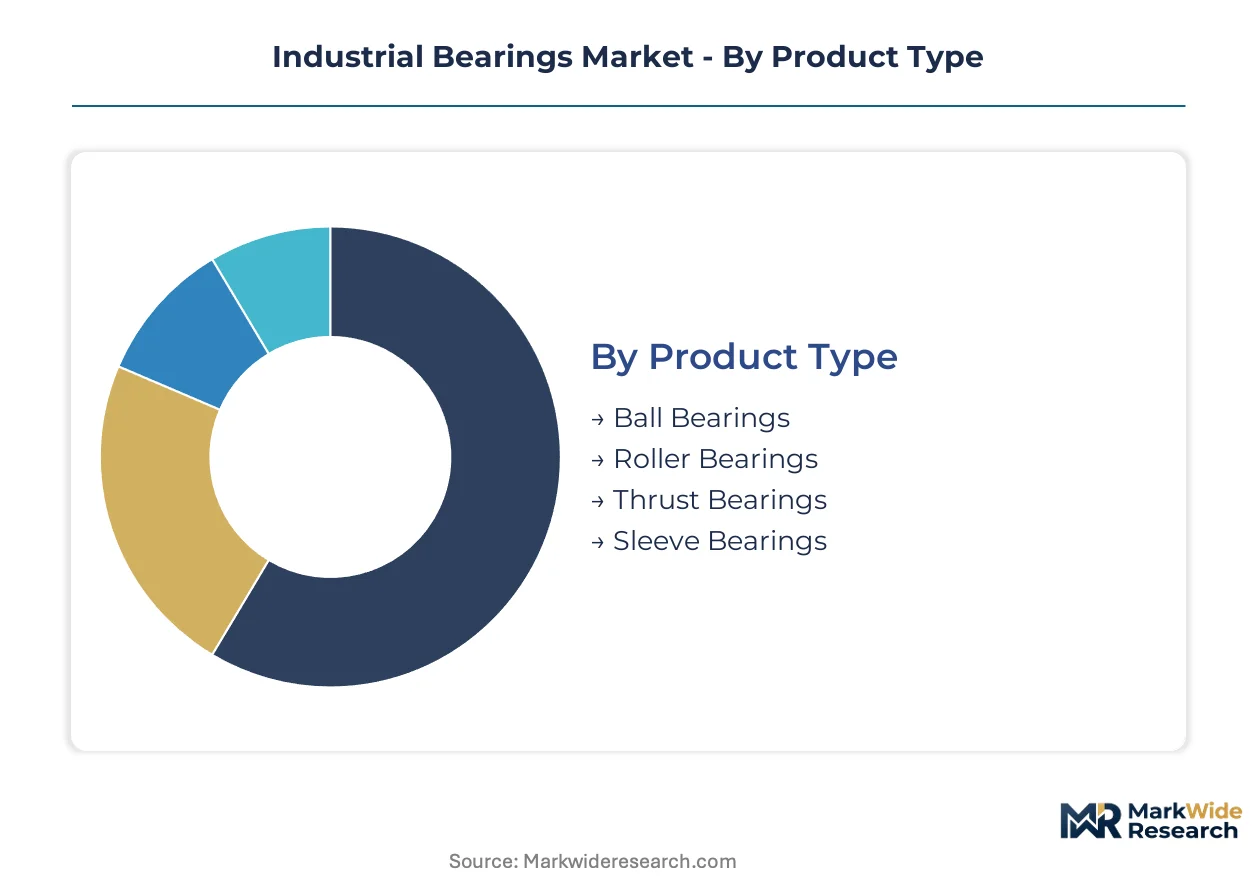
Industrial bearings segment across multiple technical and commercial dimensions that determine specification intensity, procurement channels, and margin structures. Each axis reveals distinct competitive dynamics between standardized commodity supply and precision-engineered solutions.
Product Type:
Integration depth varies sharply — roller bearings dominate heavy-load standalone applications while ball bearings embed extensively in precision subassemblies.
- Roller Bearings:Cylindrical and tapered configurations transmit radial and axial loads through line contact geometries. Mining equipment in Australia's Pilbara region and German automotive presses specify these for shock-load endurance. Thermal expansion tolerance separates premium from commodity grades.
- Ball Bearings:Point-contact raceways enable high-speed rotation with minimal friction coefficients. Japanese robotics OEMs and Dutch semiconductor equipment manufacturers embed these in servo motor assemblies where micron-level runout control determines system accuracy.
- Thrust Bearings:Axial-load specialization serves vertical pump shafts and gearbox pinions. Water treatment facilities in the US Great Lakes corridor represent concentrated demand pockets.
- Sleeve Bearings:Journal-style plain bearings operate in low-speed, high-load conveyors and marine propulsion shafts. Cost-sensitive procurement dominates this segment.
Roller bearings lead volumes today; ceramic-hybrid ball bearings are gaining share fastest.
End User:
Cost tier stratification separates specification-intensive OEM supply from aftermarket replacement cycles across industrial verticals.
- Automotive Manufacturing:Electric drivetrain thermal envelopes above 150°C now specify ceramic rolling elements. German OEMs and South Korean battery assembly lines anchor premium demand concentration.
- Aerospace:FAA-certified fatigue-life documentation extends qualification timelines to 24 months. Landing gear and engine accessory drives represent highest-margin applications.
- Mining:Pit crushers and grinding mills in Chile's Atacama and Western Australia's iron ore belts consume large-bore spherical roller bearings. Abrasive contamination drives sealed-unit preference.
- Construction:Hydraulic excavators and crane slewing rings prioritize availability over specification intensity. Rental fleet maintenance generates recurring aftermarket demand.
Automotive manufacturing leads volumes today; aerospace applications command the steepest margin expansion trajectory.
Material:
Application temperature and load intensity determine material selection, with electrification forcing a supply-side transition in ceramic capabilities.
- Steel:Through-hardened alloy compositions remain default for standardized industrial applications. Scrap metal price volatility compresses margin predictability for commodity grades.
- Ceramic:Silicon nitride rolling elements withstand thermal excursions beyond steel limits. Wind turbine gearboxes and EV motor bearings in China's Yangtze Delta manufacturing corridor drive specification conversion.
- Plastic:Polymer races suit corrosive chemical environments and food-grade washdown requirements. Pharmaceutical packaging equipment in Switzerland and Denmark specifies these for contamination control.
- Composite:Hybrid metal-polymer constructions reduce weight in aerospace actuators and medical imaging equipment. Limited supplier base constrains volume scaling.
Steel leads volumes today; ceramic is climbing the fastest as electrification rewrites thermal specifications.
Application:
Customer type fragmentation separates integrated OEM specification from distributor-led MRO procurement across machinery categories.
- Robotics:Six-axis articulated arms and SCARA configurations demand ABEC-7 precision grades with integrated encoder feedback. Japanese and German automation OEMs consolidate supply among certified precision manufacturers.
- Conveyors:Bulk material handling systems in US grain elevators and Brazilian iron ore ports prioritize sealed-unit longevity over specification intensity. Price-per-meter dominates procurement.
- Pumping Systems:API-standard process pumps in Texas and Louisiana petrochemical corridors specify thrust bearings for vertical shaft configurations. EPA lubricant restrictions near waterways drive grease reformulation.
- Textile Machinery:High-speed spindles above 20,000 RPM favor ceramic hybrids or air-bearing substitutes. India's Surat and Tirupur clusters represent concentrated regional demand.
Conveyors lead volumes today; robotics is expanding most quickly as manufacturing automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns track diverging compliance costs for alloy steel sourcing and ceramic feedstock documentation. Manufacturers relocate capacity toward jurisdictions offering carbon-accounting clarity and apprenticeship pipeline stability.
United States
EPA lubricant restrictions near waterways compel grease chemistry reformulation for pulp-and-paper and marine applications. The agency's emissions rules tighten material specifications for bearings deployed in sensitive watersheds. Texas and Louisiana petrochemical corridors concentrate demand for API-standard thrust bearings in vertical pump configurations.
Germany
EMA machinery safety directives mandate documented fatigue-life testing for medical and aerospace equipment integrations. REACH compliance filters out low-grade suppliers from high-load application supply chains. Baden-Württemberg's automotive OEMs and Bavarian machinery manufacturers anchor premium bearing consumption pools.
China
MIIT industrial upgrading policies enforce localization ratios that reshape foreign-owned plant supply chain configurations. Dual carbon compliance timelines alter raw-material sourcing economics for steel and ceramic feedstocks. Yangtze Delta manufacturing clusters drive specification conversion toward silicon nitride rolling elements for EV motor bearings.
India
PLI scheme incentives for machinery and auto components draw bearing capacity toward subcontinent assembly hubs. BIS standards enforcement raises entry barriers for uncertified imports. Gujarat and Maharashtra industrial corridors generate concentrated demand from textile machinery spindles and conveyor systems.
Japan
METI industrial standards push precision-grade specifications for robotics and semiconductor equipment integrations. JIS certification requirements extend supplier qualification timelines for micron-tolerance product lines. Kanto and Kansai manufacturing belts concentrate demand from six-axis articulated arm OEMs and servo motor assembly operations.
Industrial Bearings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision-grade applications consolidating around certified producers while standardized lines fragment across price-competitive supply bases. Three strategic archetypes dominate: sensor-integrated platform providers, ceramic hybrid specialists, and tapered roller incumbents serving heavy-industry deployments. Capacity expansion and backward integration into ceramic sintering capabilities represent the dominant competitive moves reshaping supplier positioning.
Among European-based precision manufacturers, SKF Group and Schaeffler Group exemplify the platform-specialist archetype through sensor-integrated and ceramic hybrid offerings. Timken Company anchors the heavy-industry tier with tapered roller configurations. Japanese fabricators including NSK Ltd. and JTEKT Corporation occupy positions in robotics and automotive precision supply chains.
| Leading Market Players |
|---|
| Timken Company |
| JTEKT Corporation |
| SKF Group |
| RBC Bearings Incorporated |
| NACHI-Fujikoshi Corp. |
| NSK Ltd. |
| Schaeffler Group |
| Kaydon Bearings |
| NTN Corporation |
| Others |
Supply & Pricing Matrix
Alloy steel scrap volatility cascades through three pricing tiers as commodity-grade bearings absorb feedstock swings while precision manufacturers pass thermal-performance premiums to automotive OEMs in Germany and EV assemblers in China's Yangtze Delta.
Pricing Analysis
Distributor margins compress most acutely in standardized ball-bearing segments where direct-to-OEM procurement bypasses traditional channel layers. Pricing stratifies across precision-certified, standard industrial, and economy grades, with ISO 281 fatigue-life documentation commanding 15-20 point premiums. Cost compression in commodity tiers intensifies because Indian and Chinese contract manufacturers compete on volume scale. Aftermarket buyers in construction and mining exhibit highest price sensitivity; aerospace and medical OEMs prioritize certification tier over unit cost.
Supply Chain Analysis
China's MIIT localization mandates and India's PLI domestic-content thresholds reshape sourcing patterns for foreign-owned plants in both jurisdictions. Bearing manufacturing draws from through-hardened alloy steel feedstocks in Germany and Japan, ceramic powder suppliers in China, and precision grinding equipment from Switzerland. Single-source vulnerability concentrates in silicon nitride ceramic sintering capabilities. Distribution runs through authorized distributor networks for MRO replacement cycles and direct OEM supply agreements for new equipment builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-accounting compliance costs diverge sharply between EU Green Deal jurisdictions and subcontinent manufacturing hubs, creating locational arbitrage for bearing capacity expansion.
For Market Incumbents: Extend sensor-integrated platform capabilities to capture predictive maintenance service contracts before magnetic levitation substitutes displace mechanical bearings above 50,000 RPM. Deepen backward integration into ceramic sintering to secure silicon nitride supply for EV thermal envelopes. Lock in apprenticeship pipeline partnerships in Germany and Japan to defend grinding technician scarcity. For New Entrants and Emerging Players: India's PLI scheme for machinery and auto components opens a window for greenfield capacity targeting textile machinery spindles in Gujarat and conveyor systems in Maharashtra. BIS certification requirements filter out uncertified imports, creating protected domestic share. Pursue OEM direct-supply relationships rather than distributor channel contests where incumbents hold entrenched positions. For Investors and Strategic Acquirers: Consolidation pressure builds where grinding technician apprenticeship pipelines fail to populate regional labor markets. Long-term viability centers on manufacturers with in-house ceramic capabilities and sensor-platform revenue streams. Target acquisition archetype: mid-cap precision specialists with JIS or EMA certifications but underdeveloped IoT service layers. Watch apprenticeship graduation rates in Baden-Württemberg and Kanto as inflection indicators for supply-constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Sintering Capacity Expansion | Captures silicon nitride supply security for EV drivetrain thermal specifications exceeding 150°C. |
| Sensor-Platform Service Contracts | Converts mechanical components into recurring revenue through predictive maintenance subscriptions. |
| Apprenticeship Pipeline Investment | Secures 5-7 year raceway geometry finishing expertise that regional labor markets cannot supply. |
| Green Certification Documentation | Unlocks premium pricing for low-carbon steel and ceramic variants under EU Green Deal tracking. |
| Direct OEM Supply Agreements | Bypasses distributor margin compression in Texas and Louisiana petrochemical corridor pump applications. |
Research Methodology
Bottom-up end-use equipment modeling reconciled against top-down bearing supplier shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at mining operations in Western Australia, plant engineers at German automotive presses, OEM procurement teams in Japan's robotics sector, and aftermarket service heads in Texas petrochemical facilities combined with secondary validation from SEC filings, customs trade records, and EMA machinery safety directive documentation. Top-down triangulation against alloy steel scrap price indices and ceramic powder trade flows validates volume assumptions.
Input-output matrices map bearing consumption to installed base rotations across robotics, conveyors, pumping systems, and textile machinery segments over the projection horizon. Modeled dimensions include product type, material grade, precision certification tier, and regional production cluster. CAGRs derive from equipment replacement cycle analysis and specification conversion rates toward ceramic hybrids. Forecast inputs incorporate REACH compliance cost pass-through assumptions and MIIT localization ratio enforcement timelines.
Revisions become necessary when dual carbon compliance timelines accelerate in China, EPA lubricant restrictions expand beyond watershed-proximate applications, or magnetic levitation substitute costs fall below mechanical bearing thresholds in ultra-high-speed spindles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Washer System Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Step Plate Market