
 Global Automotive Connector Market | 2026-2036
Global Automotive Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Connector Market Analysis
Engineering talent with high-voltage interconnection expertise is rotating toward EV-dedicated programs, tightening supply for legacy internal-combustion connector lines. TE Connectivity leverages its captive manufacturing of sealed connectors for powertrain electrification. Yazaki Corporation anchors its competitive position through deep integration with Japanese OEM wire-harness architectures. Amphenol Corporation differentiates by specializing in fiber-optic and RF connector portfolios for advanced driver-assistance sensor arrays.
Automotive connectors are electromechanical joining devices engineered to transmit electrical signals and power across vehicle subsystems, typically rated for temperatures spanning negative forty to one hundred twenty-five degrees Celsius and sealed against ingress per IP6K9K standards. Their primary purpose is ensuring reliable circuit continuity amid vibration, thermal cycling, and electromagnetic interference in mobile environments. Sealed connectors command the largest revenue pool due to underhood and battery-pack exposure requirements, while fiber-optic connectors represent the fastest-expanding technology segment as lidar and camera bandwidth demands escalate. PCB connectors retain mature, high-volume status in body electronics modules where pin-density and cost efficiency dominate procurement criteria.
FDA standards for automotive-grade materials do not apply here; instead, NHTSA crash-safety protocols and EPA emissions compliance indirectly shape connector durability and weight requirements in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in plating and housing compounds. China's MIIT enforces GB standards for new-energy vehicle electrical architecture that mandate specific connector formats for charging and battery interfaces. Stakeholders must monitor how divergent regional electrification timelines reshape connector specification harmonization and tooling investment recovery cycles.
Market Dynamics
Platform voltage escalation from 400V to 800V architectures is compressing connector development cycles and forcing simultaneous redesigns across powertrain, charging, and thermal management subsystems.
Growth Catalysts
- EU Green Deal material mandates:Copper-aluminum hybrid connector designs gain regulatory preference as OEMs reduce rare earth dependency in high-current pathways.
- Battery management system density:Cell monitoring circuits now require 3-5X more signal connectors per kilowatt-hour than internal combustion powertrains.
- Stuttgart-Tokyo-Detroit production clusters:Geographic concentration of EV platform engineering accelerates specification harmonization and supplier qualification throughput.
Market Restraints
- Lithium and copper price volatility:Raw material cost swings compress gross margins on high-amperage connector families before long-term supply agreements mature.
- Japanese wire-harness supplier concentration:Three integrated players control 60% of tier-one assembly capacity, creating single-source risk for specialized connector formats.
- IP6K9K sealing thermal limits:Current polymer housing compounds degrade above 150°C, constraining placement adjacent to silicon carbide inverters.
Strategic Opportunities
- India PLI scheme for auto components:Domestic manufacturing incentives attract connector producers to localize for Maruti Suzuki and Tata Motors EV programs.
- Lidar sensor fiber-optic convergence:Multi-gigabit optical backbones displace copper coaxial in perception stacks, opening new connector form factors.
- China MIIT GB/T charging standard harmonization:Unified connector specifications across state-owned OEMs reduce tooling fragmentation and enable scale economies.
Industry Challenges
- High-voltage safety certification timelines:UL and TÜV validation cycles for 800V-rated connectors now extend 14-18 months, delaying platform launches.
- Legacy 12V architecture integration:Dual-voltage vehicle designs force connector suppliers to maintain parallel tooling for mature and emerging power domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Connector Market |
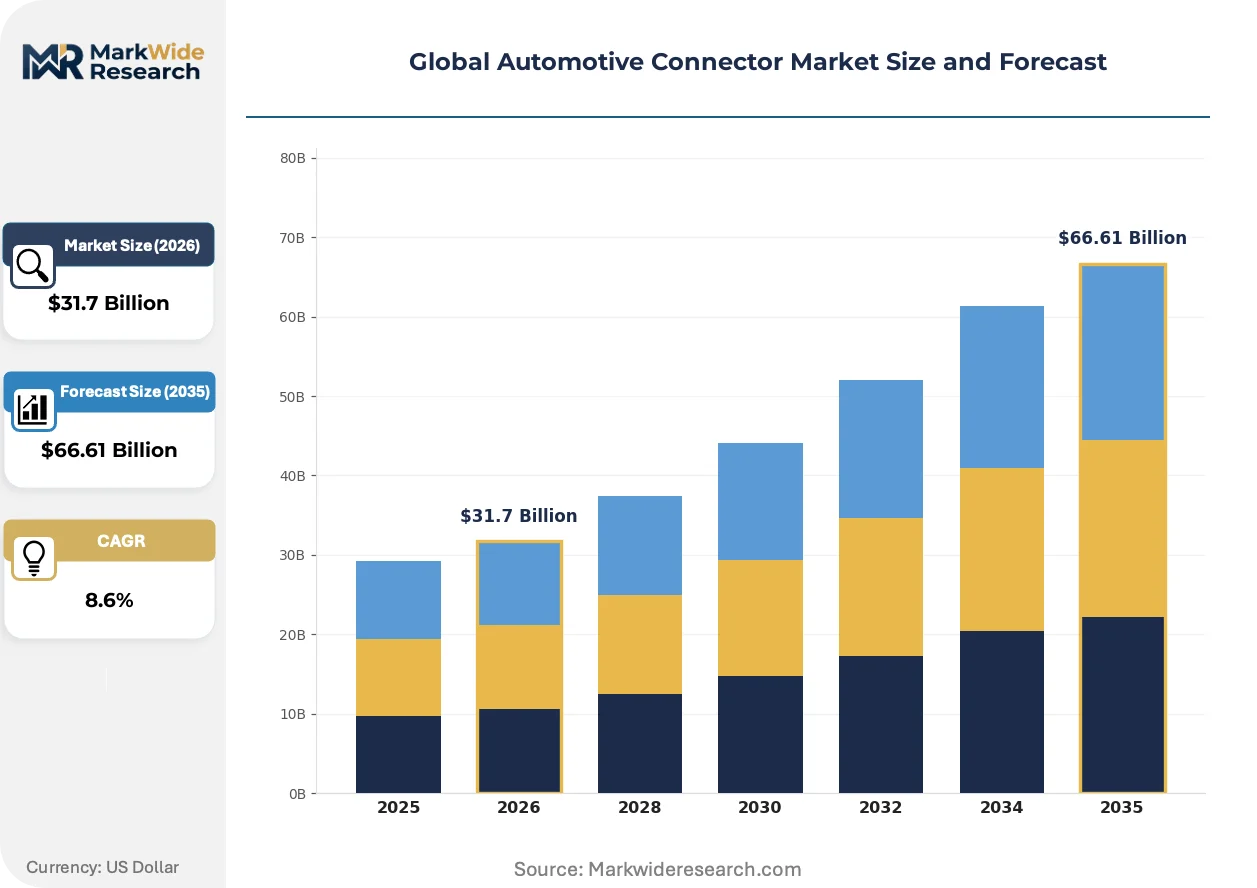
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $66.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Connectors, Unsealed Connectors, PCB Connectors, Fiber Optic Connectors Technology: Hybrid, Electrical, Optical, RF End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Powertrain, Body Electronics, Safety & Security, Infotainment |
| Companies Covered | TE Connectivity, Aptiv PLC, Amphenol Corporation, Yazaki Corporation, Molex, Sumitomo Electric Industries, Hirose Electric, Rosenberger Group, Japan Aviation Electronics Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Connector Market Emerging Trajectories
Voltage tier proliferation and sensor bandwidth demands are fragmenting connector portfolios while compressing development timelines. Suppliers now engineer simultaneously for three distinct electrification stages.
Copper-aluminum hybrid terminal designs are miniaturizing high-current junctions without sacrificing conductivity. Tier-one harness manufacturers in Germany and China have adopted these bimetal configurations for 2026 platform releases. The technology is miniaturizing battery pack junction boxes by 30% versus pure copper equivalents, freeing critical packaging volume for cell stacking density.
REACH substance restrictions on nickel and cadmium plating compounds entered enforcement phase across EU member states in early 2025. Connector housing manufacturers face reformulation mandates for contact surface finishes used in underhood applications. Sealed connector product lines serving premium German OEMs have shifted to tin-zinc and silver-palladium alternatives ahead of compliance deadlines.
Automotive OEM technical sourcing teams now specify connector families by functional safety integrity level rather than standalone component cost. Tier-two suppliers face qualification barriers as Volkswagen Group and Hyundai Motor consolidate approved vendor lists to ISO 26262-certified sources. South Korean battery producers have pioneered this procurement model, extending it to charging infrastructure partners.
Global Automotive Connector Market Segmentation
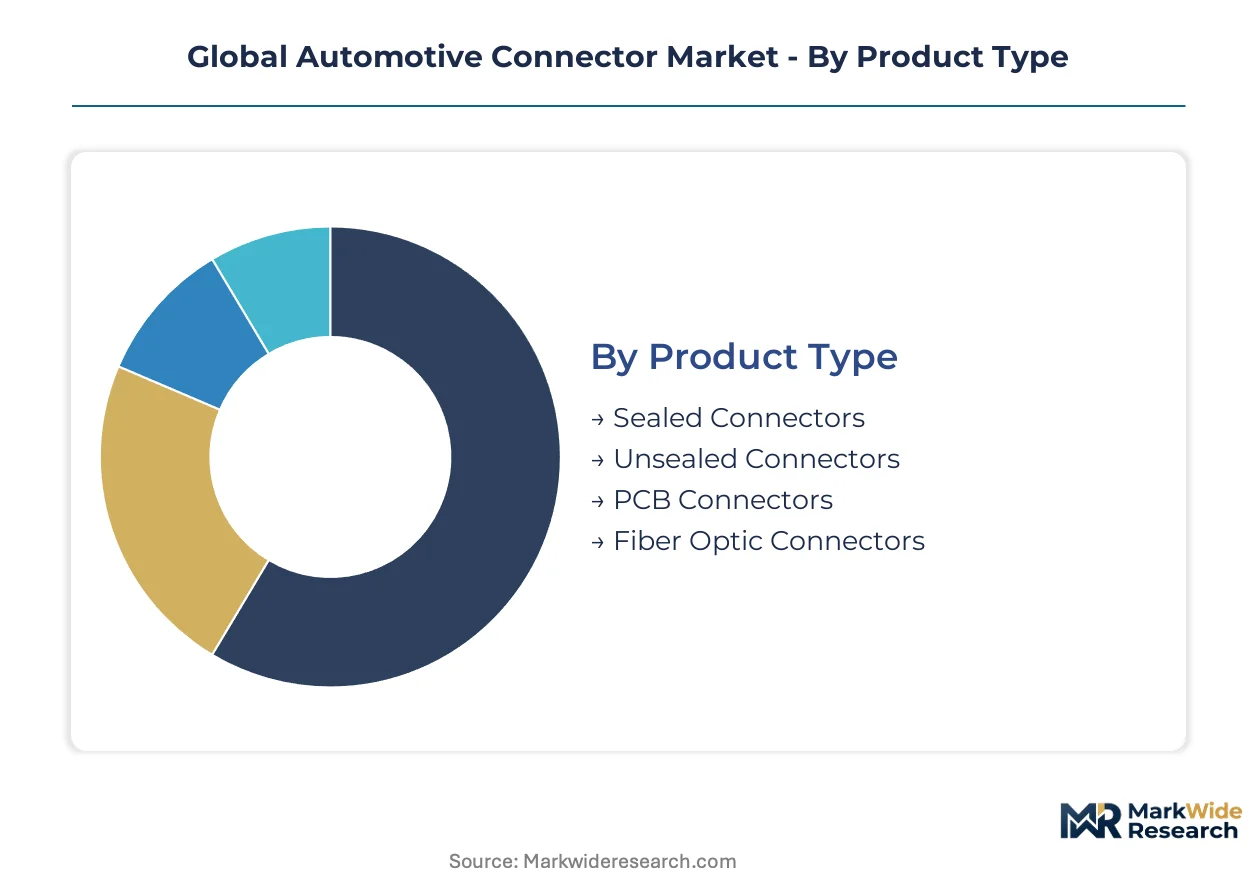
Connector specification fragmentation across voltage tiers and sensor bandwidth requirements forces suppliers to maintain parallel tooling strategies. Segment-level procurement patterns diverge sharply between legacy internal-combustion platforms and 800V EV architectures.
Product Type:
Domestic demand for sealed and PCB variants concentrates in Germany, China, and the United States where EV production clusters operate. Export-led growth characterizes fiber-optic connectors as lidar and camera subsystem suppliers serve multiple regional OEM programs from centralized manufacturing.
- Sealed Connectors:Engineered with IP6K9K-rated polymer housings and multi-point sealing systems to withstand thermal cycling from negative forty to one hundred fifty degrees Celsius. Demand concentrates in battery pack junction boxes and silicon carbide inverter interfaces across German and Chinese OEM platforms, where underhood exposure to coolant spray and road debris mandates ingress protection. Copper-aluminum hybrid terminal designs are compressing package sizes by nearly one-third versus pure copper predecessors.
- PCB Connectors:High-density pin configurations optimized for body electronics modules where cost efficiency and assembly automation dominate procurement criteria. Volume demand localizes near Stuttgart, Detroit, and Shanghai assembly plants serving mass-market vehicle programs. REACH-compliant tin-zinc plating alternatives have displaced legacy nickel finishes across EU-bound production lines.
- Unsealed Connectors:Deployed in cabin-controlled environments with reduced ingress exposure, prioritizing cost minimization over environmental sealing.
- Fiber Optic Connectors:Multi-gigabit optical backbones for lidar and camera perception stacks, expanding most quickly as sensor fusion architectures displace copper coaxial in premium EV programs.
Sealed connectors hold the largest share; momentum sits with fiber optic variants.
Technology:
Cost tier stratification separates mature electrical implementations from premium optical and RF configurations. Hybrid technologies command mid-tier pricing as OEMs balance conductivity requirements against copper weight reduction mandates.
- Hybrid:Bimetal copper-aluminum terminal architectures miniaturizing high-current junctions without conductivity sacrifice. German tier-one harness manufacturers adopted these configurations for 2026 platform releases, freeing battery pack volume for additional cell stacking density.
- Electrical:Mature copper-based signal and power transmission dominating body electronics and legacy 12V architectures. Volume production concentrates in Chinese and Mexican manufacturing zones serving cost-sensitive vehicle programs.
- Optical:Glass fiber transmission for multi-gigabit sensor data backbones in advanced driver-assistance systems.
- RF:Radio-frequency connectors for V2X communication modules and antenna arrays, climbing the fastest as connected vehicle mandates expand across multiple regulatory jurisdictions.
Electrical technology retains volume leadership; steepest expansion trajectory belongs to hybrid designs.
End User:
Customer type determines qualification timelines and contract structures. OEM direct procurement emphasizes functional safety certification while tier-1 suppliers prioritize connector-harness integration efficiency.
- OEMs:Direct technical sourcing teams now specify connector families by ISO 26262 functional safety integrity level rather than standalone component cost. Volkswagen Group and Hyundai Motor have consolidated approved vendor lists to certified sources exclusively.
- Tier-1 Suppliers:Integrated wire-harness manufacturers in Japan and Germany controlling specification lock-in through deep architectural relationships with OEM engineering teams.
- Aftermarket Providers:Replacement and repair channel serving vehicle service networks with reduced qualification barriers.
- Vehicle Assemblers:Final assembly operations sourcing connectors for localized module integration.
OEMs dominate procurement value; tier-1 suppliers capture the fastest-growing channel as outsourcing of harness integration accelerates.
Application:
Application-driven specification divergence intensifies as 800V powertrain electrification forces connector redesigns independent of body electronics refresh cycles. Safety-critical domains impose the strictest qualification protocols.
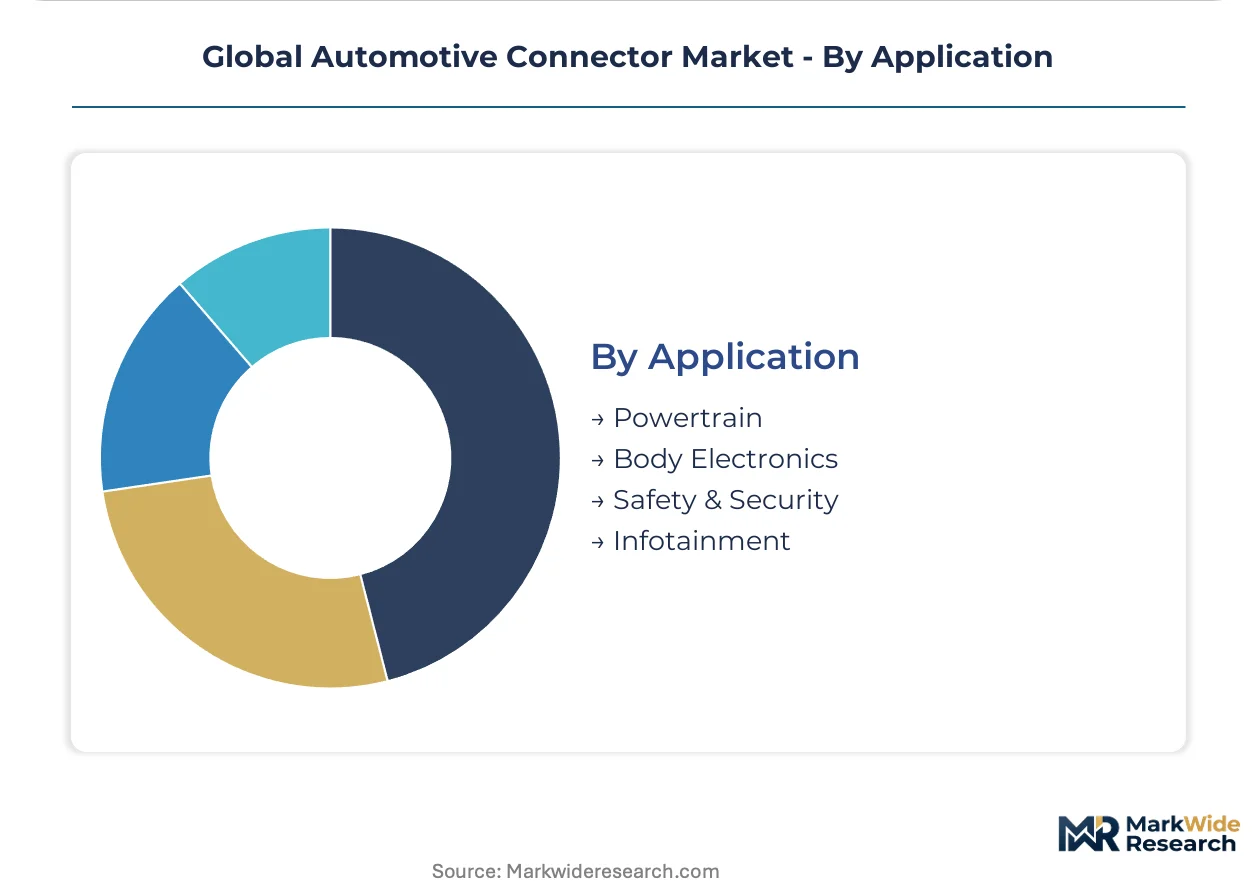
- Powertrain:High-voltage interconnection for battery management systems, inverters, and thermal management circuits requiring simultaneous 400V and 800V compatibility. UL and TÜV validation cycles now extend fourteen to eighteen months for new platform introductions.
- Safety & Security:Airbag deployment and crash sensor connectors with zero-failure tolerance under NHTSA and KBA protocols. Dual-voltage vehicle designs force suppliers to maintain parallel tooling for mature and emerging power domains.
- Body Electronics:Door modules, lighting, and climate control interfaces with mature PCB connector specifications.
- Infotainment:Display and audio subsystem connectivity with escalating bandwidth demands for streaming and navigation integration.
Powertrain applications command the largest revenue pool; safety and security segments impose the most stringent certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA crash-safety protocols and EPA emissions compliance anchor connector durability requirements in the United States, while China's MIIT enforces GB standards for new-energy vehicle electrical architecture. Divergent regional electrification timelines reshape specification harmonization and tooling investment recovery cycles.
United States
Domestic EV platform engineering concentrates in Detroit and California, driving demand for sealed connectors in battery management systems. NHTSA protocols mandate zero-failure tolerance for safety-critical interconnections. The Southeast manufacturing corridor attracts harness suppliers serving BMW and Mercedes-Benz US assembly operations.
Germany
Stuttgart engineering clusters accelerate 800V platform development, compressing connector validation cycles. REACH and RoHS frameworks restrict hazardous substance content in plating compounds. Bavaria hosts tier-one harness manufacturers adopting copper-aluminum hybrid terminal designs for 2026 vehicle releases.
China
State-owned OEM consolidation under MIIT GB/T charging standards reduces tooling fragmentation. Dual carbon goals tighten material standards and push manufacturers toward hybrid conductor designs. The Yangtze River Delta concentration of battery producers pioneers ISO 26262-certified procurement models for connector qualification.
Japan
Integrated wire-harness architectures lock in specification control for three dominant tier-one suppliers. METI industrial policy supports domestic connector-harness integration efficiency. Nagoya and Tokyo engineering centers coordinate with Toyota and Honda electrification timelines.
India
Maruti Suzuki and Tata Motors EV programs attract component localization under the PLI scheme for auto components. BIS standards for automotive electrical systems gain enforcement traction. The Gujarat and Tamil Nadu manufacturing corridors host emerging connector production for export and domestic vehicle assembly.
Global Automotive Connector Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base spans integrated multinational conglomerates, specialized high-voltage interconnection firms, and regional harness-integrated suppliers. Three strategic archetypes dominate: full-line electromechanical component houses, wire-harness-integrated specialists, and optical-RF connectivity pure-plays. Competitive moves concentrate on strategic partnerships for 800V qualification access and portfolio diversification into fiber-optic sensor backbones.
Among Japan-based integrated suppliers, Yazaki Corporation and Sumitomo Electric Industries exemplify the harness-architecture archetype with deep OEM engineering relationships. TE Connectivity anchors the full-line multinational tier with captive manufacturing scale across multiple voltage platforms. These three entities represent distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| TE Connectivity |
| Aptiv PLC |
| Amphenol Corporation |
| Yazaki Corporation |
| Molex |
| Sumitomo Electric Industries |
| Hirose Electric |
| Rosenberger Group |
| Japan Aviation Electronics Industry |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German OEMs and copper-aluminum hybrid connector suppliers lock in volume commitments and price visibility across volatile raw material cycles. These contracts insulate tier-one harness manufacturers from lithium and copper price swings while constraining margin flexibility for component producers serving spot-market buyers.
Pricing Analysis
Geographic price spreads between German and Chinese production clusters reflect divergent labor cost structures and REACH compliance overhead for EU-bound shipments. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 26262 certification grade and volume scale. Cost compression in high-amperage connector families intensifies as long-term supply agreements mature. Aftermarket providers exhibit highest price sensitivity; OEM direct procurement teams prioritize functional safety integrity over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate harness-integrated supply chains serving Stuttgart and Detroit assembly corridors, while strategic stockpiling of copper-aluminum terminal substrates buffers against commodity volatility. Manufacturing concentrates in Germany, China, and Mexico, with raw material feeds drawing from Chilean copper and Australian aluminum smelters. Single-source vulnerability concentrates in Japanese wire-harness supplier networks controlling tier-one assembly capacity. Distribution runs through OEM technical sourcing teams and tier-one harness manufacturers rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connector specification fragmentation across 400V and 800V architectures creates service-layer gaps and white-space opportunities for specialized entrants. Voltage tier proliferation fragments procurement patterns and opens niches for hybrid technology specialists.
For Market Incumbents: Shield market position by deepening captive manufacturing of sealed connectors for powertrain electrification and accelerating ISO 26262 certification investment ahead of Volkswagen Group vendor consolidation. Backward integration into copper-aluminum terminal production mitigates raw material cost volatility threatening gross margins on high-amperage families.
For New Entrants and Emerging Players: Fiber-optic connector technical service gaps in lidar perception stack integration present entry points where TE Connectivity and Amphenol under-serve regional OEM engineering teams. Target Indian PLI scheme beneficiaries Maruti Suzuki and Tata Motors with localized high-voltage interconnection qualification support. Go-to-market leverage rests on 800V platform engineering partnerships rather than component cost positioning.
For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors optical-RF connectivity pure-plays with established ADAS sensor backbone relationships. Five-to-ten year viability hinges on fiber-optic convergence in perception stacks and charging infrastructure standardization. Acquisition target archetype: mid-cap hybrid terminal specialists with MIIT GB/T certification access. Signal to watch: 800V validation cycle compression below twelve months indicating qualification bottleneck relief.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | MIIT GB/T charging harmonization reduces tooling fragmentation across Chinese state-owned OEMs. |
| Battery Supply Agreement | Long-term offtake contracts with Yangtze River Delta producers anchor copper-aluminum terminal demand. |
| Software-Defined Vehicle Investment | Multi-gigabit optical backbones displace copper coaxial in lidar and camera perception stacks. |
| Geographic Manufacturing Footprint | India PLI scheme localization captures Maruti Suzuki and Tata Motors EV program sourcing. |
| Charging Infrastructure Partnership | 800V connector qualification access accelerates through UL and TÜV validation cycle compression. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one harness procurement leads, aftermarket distributors, and high-voltage interconnection specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, vehicle production databases, IHS Markit registration data, and customs trade records. Bottom-up connector demand modeling triangulated against top-down automotive production forecasts.
Segmentation dimensions modeled span product type, technology tier, end-user channel, and application domain across the analysis window. Propulsion architecture differentiation between 400V and 800V platforms, content per vehicle escalation in battery management systems, and regional production cluster concentration informed volume and value projections. CAGRs derived from segment-level growth rate synthesis weighted by revenue contribution.
Forecasts assume regulatory continuity in NHTSA crash-safety protocols, REACH substance restrictions, and MIIT GB standards; material policy shifts would require re-modeling. Revision becomes warranted when lithium and copper price volatility crosses thresholds that invalidate long-term supply agreement pricing assumptions or when 800V validation cycle compression accelerates platform launch timelines beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Smart Crimper Market
Connectors
Hazardous Location Connectors Market
Connectors
Terminal Pins Market
Connectors
Underwater Mate Connectors Market
Connectors
DIN Connectors Market
Connectors
Wire-To-Board Connector Market
Connectors
Filtered Connectors Market
Connectors
Middle East Connector Market
Connectors
Connector Market
Connectors
Latin America Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
Cable Connectors and Adapters Market
Connectors
Pin Retainer Market
Connectors
High-Reliability Connectors Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Asia-Pacific Connector Market