
 Smart Crimper Market | 2026-2036
Smart Crimper Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Crimper Market Analytics
Automotive OEMs are rotating toward smart crimping platforms as EV architectures multiply connector counts per vehicle. TE Connectivity leverages its sensor-integrated crimper portfolio to anchor high-volume contracts with tier-one harness suppliers. Schleuniger Group specializes in precision micro-crimping systems that dominate aerospace qualification programs. Komax Group extends its software-defined crimping footprint through closed-loop quality verification modules.
A smart crimper is an electromechanical or electrohydraulic joining device that compresses terminals onto conductors with force-displacement monitoring, typically achieving pull-force tolerances within ±3% via servo-controlled ram movement and real-time angle encoders. Its primary purpose is to eliminate conductor strand deformation while ensuring gas-tight metallurgical bonds in safety-critical electrical interconnections. Electric crimpers now capture the fastest expansion within product type segmentation as factory electrification programs displace pneumatic infrastructure. IoT-enabled technology segments pull premium pricing through cloud-connected predictive maintenance, while standard configurations retain volume dominance in emerging industrial supplier tiers. Wire harness applications concentrate margin pools due to zero-defect contractual penalties from automotive OEMs.
OSHA lockout-tagout directives and FCC Part 15 emissions compliance shape North American product certification pathways, while CE marking under the EU Machinery Directive governs European market access with mandatory functional safety ratings. Japan's METI energy-efficiency benchmarks for industrial equipment filter import eligibility for non-domestic suppliers. Stakeholders must weigh servo-motor sourcing strategies against rare-earth supply concentration risks before committing to platform architectures.
Market Dynamics
Automotive electrification is compressing crimping cycle times while multiplying quality verification steps per harness assembly. Tier-one suppliers now specify closed-loop force monitoring as a contractual floor for EV platform awards.
Growth Catalysts
- EU Green Deal industrial mandates:Factory electrification programs across Germany, France, and Italy are retiring pneumatic crimping infrastructure in favor of servo-electric systems that cut energy consumption per cycle.
- EV wire harness complexity:Battery electric vehicle architectures require three to four times the connector density of internal combustion platforms, expanding addressable equipment volumes per automotive OEM program.
- Cloud-based predictive maintenance:IoT-enabled crimpers with vibration sensing and edge analytics are reducing unplanned downtime for high-volume harness suppliers in Stuttgart's automotive corridor.
Market Restraints
- Rare-earth magnet supply concentration:Servo motor production depends on neodymium and dysprosium sourcing from concentrated Asian supply chains, exposing equipment manufacturers to input volatility and export restriction risk.
- CE marking functional safety compliance:The EU Machinery Directive's mandatory PLd/SIL2 ratings for safety-critical joining equipment extend certification timelines and engineering overhead for non-European suppliers.
- Pneumatic system sunk costs:Established tier-two harness shops with depreciated pneumatic infrastructure face replacement economics that delay smart crimper adoption despite operational efficiency gains.
Strategic Opportunities
- India PLI scheme for automotive components:Production-linked incentives for advanced manufacturing equipment create a regulatory tailwind for smart crimper localization in Chennai and Pune supplier clusters.
- Renewable energy storage systems:Grid-scale battery installations require high-reliability busbar and cable terminations that match smart crimper force-displacement monitoring capabilities.
- 5G private network integration:Ultra-low latency connectivity is enabling real-time quality data streaming from crimping stations to OEM vendor portals, creating new subscription service revenue pools.
Industry Challenges
- Servo control programming expertise:The shift from pneumatic to electric crimping platforms demands motion control engineers with rare skill combinations in force feedback algorithms and industrial Ethernet protocols.
- Legacy MES integration complexity:Brownfield harness facilities operate mixed-vintage production lines where smart crimper data protocols require custom middleware development to connect with decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Crimper Market |
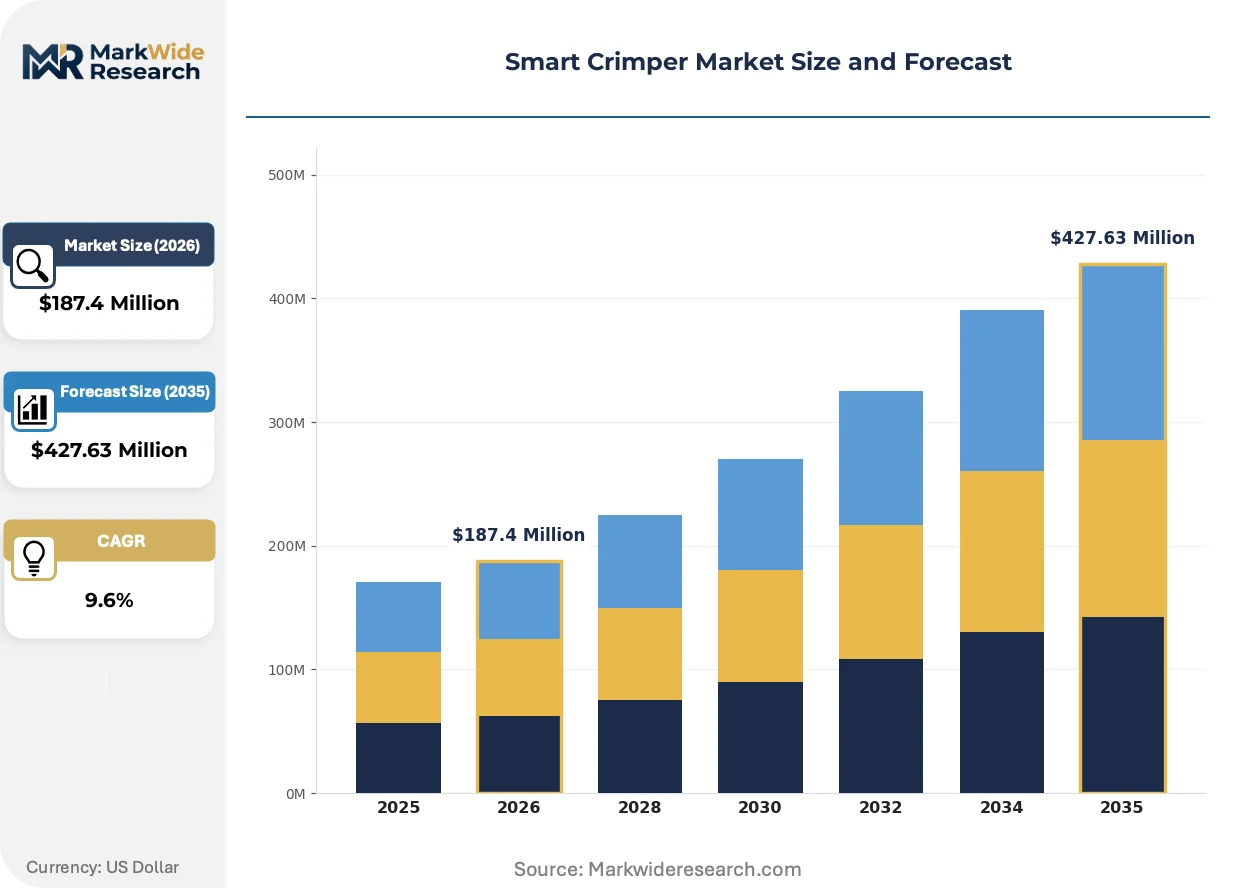
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Crimper, Hydraulic Crimper, Pneumatic Crimper, Electric Crimper Technology: IoT-Enabled, Bluetooth-Connected, Automated, Standard Application: Wire Harness, Cable Assembly, Electronics Manufacturing, Telecommunications End User: Automotive OEMs, Aerospace Manufacturers, Industrial Suppliers, Consumer Electronics |
| Companies Covered | Komax Group, Schleuniger Group, TE Connectivity, Molex, Amada Miyachi, Wezag, Artos Engineering, ShinMaywa Industries, Branson Ultrasonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Crimper Market Evolving Landscape
Smart crimping technology is converging with industrial AI and edge computing to transform quality assurance from post-process inspection to in-cycle intervention. Equipment vendors are racing to embed predictive algorithms that halt defective crimps before metallurgical deformation completes.
Brushless servo motor architectures with integrated torque sensors are supplanting traditional pneumatic actuation in high-volume automotive harness lines. Tier-one suppliers in Germany's supplier corridor are specifying all-electric platforms for new EV program awards. The transition is compressing maintenance intervals and enabling sub-millisecond force feedback loops that pneumatic systems cannot replicate.
The EU Machinery Directive's 2023 update to functional safety standards is mandating redundant position monitoring for safety-critical joining equipment. European automotive OEMs are now requiring PLd certification as a qualification gate for harness supplier equipment purchases. Asian equipment manufacturers are responding by partnering with TÜV-certified design houses to accelerate CE marking timelines.
Automotive OEMs are unbundling equipment procurement from long-term service contracts, shifting toward outcome-based arrangements where suppliers guarantee zero-defect crimp rates per million cycles. Tier-one harness manufacturers in Japan and South Korea are piloting per-crimp pricing models that align vendor compensation with downstream quality metrics. This restructuring concentrates vendor risk while transferring capital burden from balance-sheet-constrained suppliers to equipment financiers.
Smart Crimper Market Segmentation
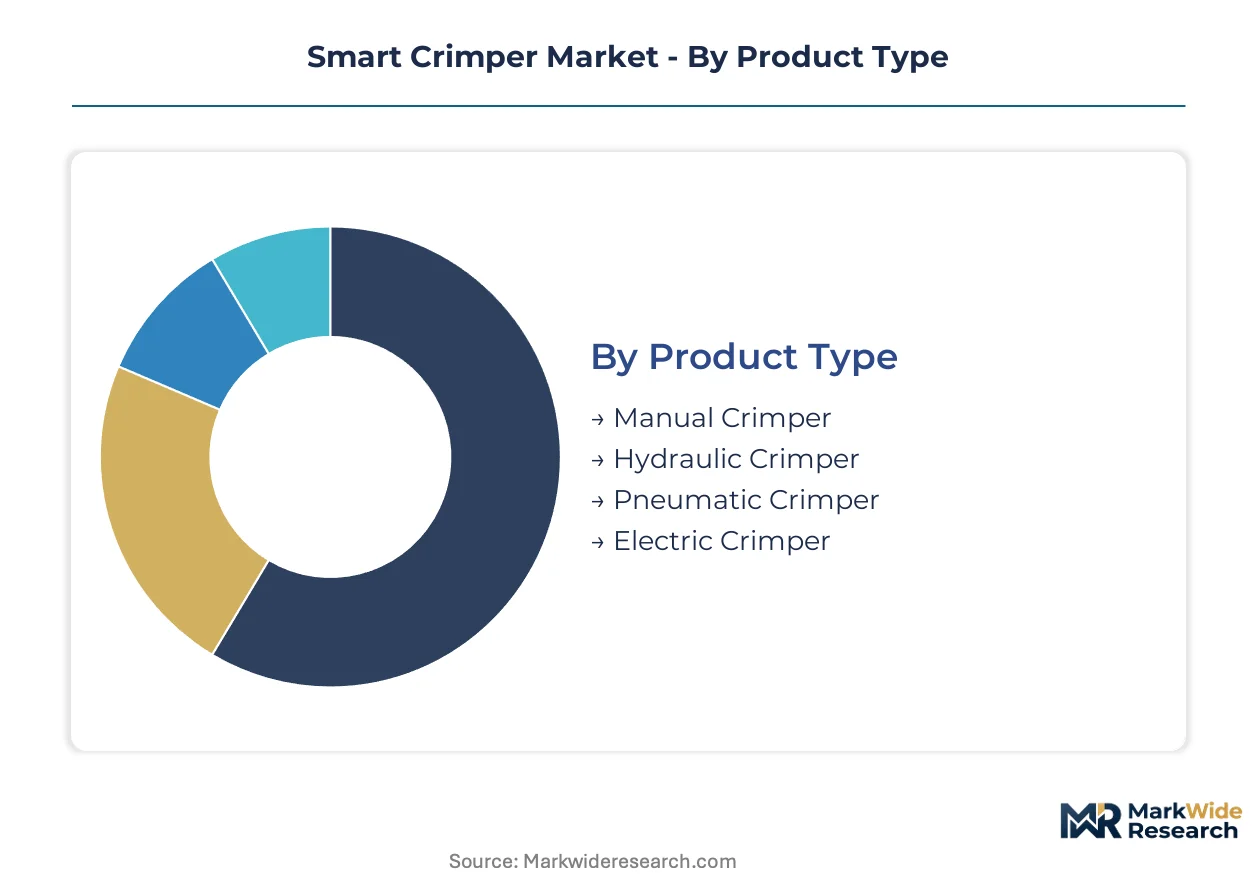
Smart crimper procurement channels vary sharply by segment maturity. Electric and IoT-enabled units flow through direct OEM relationships, while standard equipment dominates distributor networks serving tier-two suppliers.
Product Type:
Channel mix splits between capital-project direct sales for electric platforms and aftermarket distributor routes for legacy pneumatic replacements.
- Electric Crimper:Servo-controlled ram systems with integrated force-displacement monitoring achieve ±3% pull-force tolerance. Stuttgart's automotive supplier corridor is absorbing these units fastest as EV harness complexity multiplies connector density requirements.
- Pneumatic Crimper:Compressed-air actuation dominates depreciated installed bases in tier-two harness shops. Replacement economics delay migration despite energy efficiency penalties under EU Green Deal mandates.
- Hydraulic Crimper:High-force oil-pressure systems retain niche positions in heavy-gauge cable terminations for grid infrastructure.
- Manual Crimper:Hand-operated mechanical units persist in prototype shops and low-volume aerospace qualification programs.
Pneumatic crimpers dominate installed base. Electric crimpers are where expansion concentrates.
Technology:
Margin tiering separates subscription-connected platforms from capital-sale standard configurations.
- IoT-Enabled:Cloud-connected predictive maintenance modules with vibration sensing and edge analytics command premium pricing. Japan's METI energy-efficiency benchmarks filter import eligibility, favoring vendors with localized service infrastructure.
- Automated:Closed-loop quality verification with real-time angle encoders eliminates post-process inspection steps. Aerospace manufacturers in Toulouse and Hamburg specify these for zero-defect contractual environments.
- Bluetooth-Connected:Short-range wireless data logging serves mid-tier suppliers bridging legacy MES systems.
- Standard:Non-connected electromechanical units retain volume dominance in emerging industrial supplier tiers.
Standard configurations anchor volume shipments. IoT-enabled platforms are climbing the fastest.
Application:
Customer concentration varies by defect-cost exposure in downstream assemblies.
- Wire Harness:Multi-conductor assemblies with zero-defect contractual penalties from automotive OEMs concentrate margin pools. Germany's automotive corridor around Wolfsburg drives specification intensity.
- Cable Assembly:Power distribution terminations for renewable energy storage systems demand gas-tight metallurgical bonds matching smart crimper force-displacement capabilities.
- Electronics Manufacturing:Micro-connector precision requirements favor servo-controlled micro-crimping platforms.
- Telecommunications:Fiber and copper network infrastructure sustains mid-tier equipment demand.
Wire harness commands pricing power. Cable assembly is gaining share fastest.
End User:
Procurement sophistication escalates from consumer electronics contract manufacturers to aerospace qualification programs.
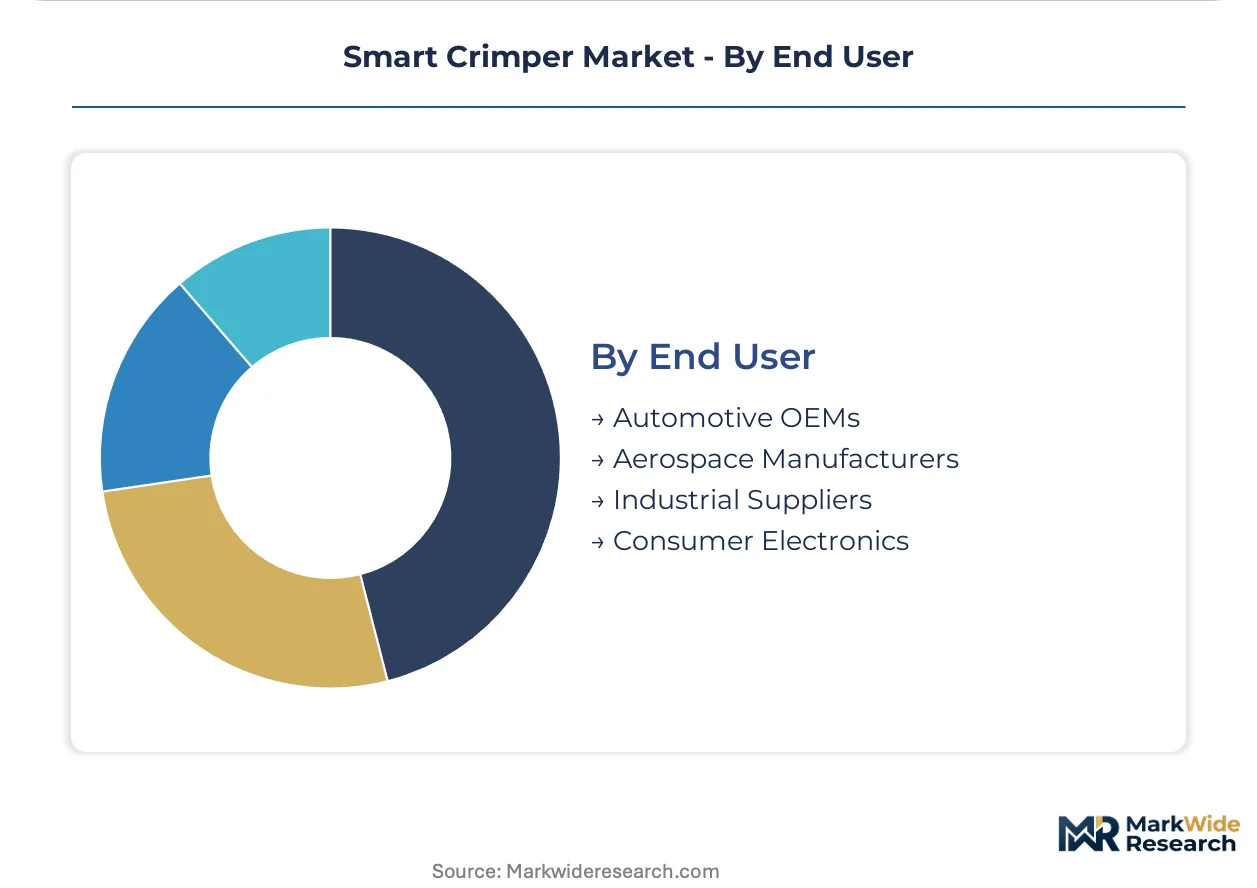
- Automotive OEMs:Tier-one harness suppliers now specify closed-loop force monitoring as a contractual floor for EV platform awards. Battery electric architectures require three to four times the connector density of internal combustion platforms.
- Aerospace Manufacturers:Qualification protocols for safety-critical electrical interconnections demand PLd/SIL2 functional safety ratings under EU Machinery Directive mandates.
- Industrial Suppliers:Mixed-vintage production lines in brownfield facilities require custom middleware for smart crimper data protocol integration.
- Consumer Electronics:High-volume, low-mix production tolerates standard configurations with minimal quality verification overhead.
Automotive OEMs drive specification intensity. Aerospace manufacturers are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing for precision joining systems clusters in industrial corridors with dense automotive and aerospace supply chains. Regulatory pressure on factory electrification and functional safety compliance is reshaping procurement patterns across major manufacturing economies.
Germany
Stuttgart's automotive supplier corridor and Wolfsburg's OEM ecosystem absorb servo-electric crimping platforms fastest as EV harness complexity multiplies connector density requirements. The EU Machinery Directive mandates PLd/SIL2 functional safety ratings for safety-critical joining equipment, extending certification timelines for non-European suppliers. Baden-Württemberg's precision engineering cluster around Karlsruhe concentrates development of closed-loop force monitoring systems.
United States
OSHA lockout-tagout directives and FCC Part 15 emissions compliance shape product certification pathways for automotive wire harness suppliers. Michigan's Detroit-Toledo corridor and Ohio's manufacturing belt drive specification intensity for zero-defect crimping equipment. The Southeast's emerging EV battery and assembly plants are absorbing IoT-enabled predictive maintenance platforms.
Japan
METI energy-efficiency benchmarks for industrial equipment filter import eligibility, favoring vendors with localized service infrastructure. Kanto's Tokyo-Yokohama industrial zone and Chubu's Nagoya automotive cluster concentrate demand for micro-crimping precision systems. Tier-one harness manufacturers in Osaka-Kobe are piloting per-crimp pricing models that align vendor compensation with downstream quality metrics.
China
MIIT industrial upgrading programs and dual carbon goals accelerate displacement of pneumatic crimping infrastructure in Yangtze River Delta manufacturing hubs. The Pearl River Delta's electronics contract manufacturers sustain volume demand for standard electromechanical configurations. Shandong Peninsula's automotive supplier parks are specifying closed-loop quality verification modules for export-oriented harness production.
India
The PLI scheme for automotive components creates regulatory tailwinds for smart crimper localization in Chennai and Pune supplier clusters. BIS certification requirements and state-level industrial incentives concentrate investment in Maharashtra and Tamil Nadu. Gujarat's emerging EV component manufacturing belt is absorbing servo-electric platforms for battery pack wire harness assembly.
Smart Crimper Market Competitive Landscape
Concentration sits with diversified industrial technology conglomerates and precision equipment specialists serving automotive and aerospace qualification programs. The vendor base stratifies across three tiers: integrated connectivity solution providers with captive crimping technology, standalone precision equipment manufacturers with software-defined architectures, and regional fabricators serving distributor networks. Dominant competitive moves include strategic partnerships for functional safety certification acceleration and geographic expansion through localized assembly operations.
Within the integrated connectivity tier, TE Connectivity and Molex occupy positions that span terminal supply through joining equipment specification. Schleuniger Group and Komax Group exemplify standalone precision equipment specialists with differentiated software and quality verification capabilities. Amada Miyachi anchors the Japanese specialist segment with positioning in resistance welding and precision joining technology.
| Leading Market Players |
|---|
| Komax Group |
| Schleuniger Group |
| TE Connectivity |
| Molex |
| Amada Miyachi |
| Wezag |
| Artos Engineering |
| ShinMaywa Industries |
| Branson Ultrasonics |
| Others |
Value Network & Pricing Analysis
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation in smart crimper procurement, as PLd/SIL2 functional safety ratings separate certified premium platforms from uncertified standard configurations while extending engineering overhead that feeds into vendor pricing power.
Pricing Analysis
CE marking dictates the pricing tier structure across the smart crimper market, with three-tier pricing separating IoT-enabled predictive maintenance platforms from automated closed-loop systems from standard electromechanical units. Certification level and after-sales service bundling emerge as the primary price differentiation drivers, as aerospace manufacturers in Hamburg and Toulouse absorb premium positioning for zero-defect contractual environments. Cost compression in standard configurations is intensifying because distributor networks serving tier-two harness shops compete on capital equipment outlay. Tier-two industrial suppliers exhibit the highest price sensitivity, while automotive OEMs prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Inventory cycles for servo motors and rare-earth magnet assemblies now stretch eighteen to twenty-four months, compressing equipment delivery windows for non-integrated vendors. Supply concentrates in Germany, Japan, and China, with Baden-Württemberg's precision engineering cluster, Kanto's industrial zone, and Yangtze River Delta manufacturing hubs anchoring component fabrication. Neodymium and dysprosium sourcing draws from concentrated Asian supply chains, while brushless servo architectures hinge on torque sensor integration from Japanese specialists. Single-source vulnerability around rare-earth magnet supply exposes equipment manufacturers to export restriction risk. Distribution runs through direct OEM relationships for electric and IoT-enabled platforms, with aftermarket distributor routes serving legacy pneumatic replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart crimper market is recovering from a cyclical trough driven by automotive electrification CAPEX cycles, as EV platform ramp-ups reactivate deferred procurement decisions across tier-one harness supplier networks.
For Market Incumbents: Consolidate software-defined crimping capabilities through targeted acquisition of edge analytics specialists, as closed-loop quality verification becomes a contractual floor for Stuttgart corridor awards. Deepen backward integration into servo motor supply chains to mitigate rare-earth concentration exposure. Anchor channel control through long-term service contracts that transfer capital burden from balance-sheet-constrained suppliers. For New Entrants and Emerging Players: Differentiate on 5G private network integration for real-time quality data streaming, as this capability remains underdeveloped among established vendors. Target India's PLI scheme beneficiary clusters in Chennai and Pune, where regulatory tailwinds for automotive component manufacturing create penetrable procurement channels. Pursue a per-crimp pricing go-to-market model that aligns vendor compensation with downstream quality metrics, transferring adoption risk from capital-constrained tier-two suppliers. For Investors and Strategic Acquirers: The EU Machinery Directive's 2023 functional safety update reshapes the acquisition landscape by elevating TÜV-certified design capabilities to strategic scarcity. Long-term viability over a five-to-ten year window favors precision equipment specialists with differentiated software architectures over commodity fabricators. Prioritize acquisition targets with captive predictive maintenance platforms and established CE marking pathways. Monitor METI energy-efficiency benchmark revisions as the critical signal for Japanese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Acceleration | TÜV-certified design partnerships compress CE marking timelines for non-European equipment vendors. |
| Servo Motor Supply Chain Integration | Backward integration into rare-earth magnet sourcing mitigates input volatility from concentrated Asian suppliers. |
| 5G Private Network Platform Development | Ultra-low latency connectivity enables subscription revenue pools from real-time quality data streaming. |
| Localized Assembly Operations | Chennai and Pune facilities capture PLI scheme benefits for automotive component manufacturing equipment. |
| Per-Crimp Pricing Model Pilot | Outcome-based arrangements align vendor compensation with zero-defect rate guarantees demanded by automotive OEMs. |
Research Methodology
A spread of perspectives from OEM procurement directors, tier-one harness supplier plant engineers, aftermarket service heads, and precision equipment R&D directors converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from SEC filings, customs and trade data, vehicle production databases, and industrial equipment registration records. Bottom-up equipment shipment tallies and top-down automotive wire harness demand estimates were triangulated to anchor volume assumptions.
Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user sophistication across the projection horizon. CAGRs were derived from regression analysis against automotive production forecasts and electrification penetration curves. Industry-specific forecast inputs incorporated EV platform connector density multipliers and EU Green Deal industrial electrification timelines.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification CAPEX commitment or rare-earth supply chain stability would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Global Fiber Optic Connectors Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
India Connector Market
Connectors
Cable Connectors and Adapters Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Automotive Data Connectors Market
Connectors
LCP Connectors Market
Connectors
Press Fit Connector Market
Connectors
Australia Connector Market
Connectors
DIN Connectors Market
Connectors
Terminal Pins Market
Connectors
5G Connector Market
Connectors
Space Grade Connectors Market
Connectors
Underwater Connectors Market
Connectors
Relay Sockets Market