
 Blepharitis Treatment Market | 2026-2036
Blepharitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Blepharitis Treatment Market Analysis
Asset-light licensing partnerships between biotech developers and regional distributors is reconfiguring capital deployment across the blepharitis treatment landscape. Tarsus Pharmaceuticals leverages its specialty ophthalmology focus to sustain direct-to-clinic channel control. AbbVie (Allergan) anchors market presence through its established dry-eye and ocular surface disease infrastructure. Novartis AG competes via integrated R&D pipelines spanning anti-inflammatory and antimicrobial modalities.
Blepharitis treatment encompasses pharmacological and mechanical interventions targeting eyelid margin inflammation, typically involving topical azithromycin or metronidazole formulations with anti-demodex activity alongside thermal pulsation and lid hygiene protocols. The primary purpose is restoring meibomian gland function and reducing bacterial or parasitic load to prevent corneal compromise and recurrent ocular surface damage. Topical antibiotics and antiseptic solutions dominate current prescribing patterns, though chronic-stage interventions command premium positioning due to longer treatment durations and higher therapy abandonment rates. Delivery mode segmentation shows ointment and gel formats retaining preference among older demographics, while spray formulations are gaining traction in homecare settings for compliance advantages.
FDA ophthalmic guidance and EPA antimicrobial stewardship frameworks shape formulation standards, with the former mandating sterility assurance levels that raise barrier costs for new entrants. The European Medicines Agency's MDR requirements for ophthalmic devices further complicate cross-border product registration strategies. Stakeholders must monitor evolving reimbursement thresholds for chronic versus acute staging protocols, as payors tighten prior authorization criteria for higher-cost biological interventions.
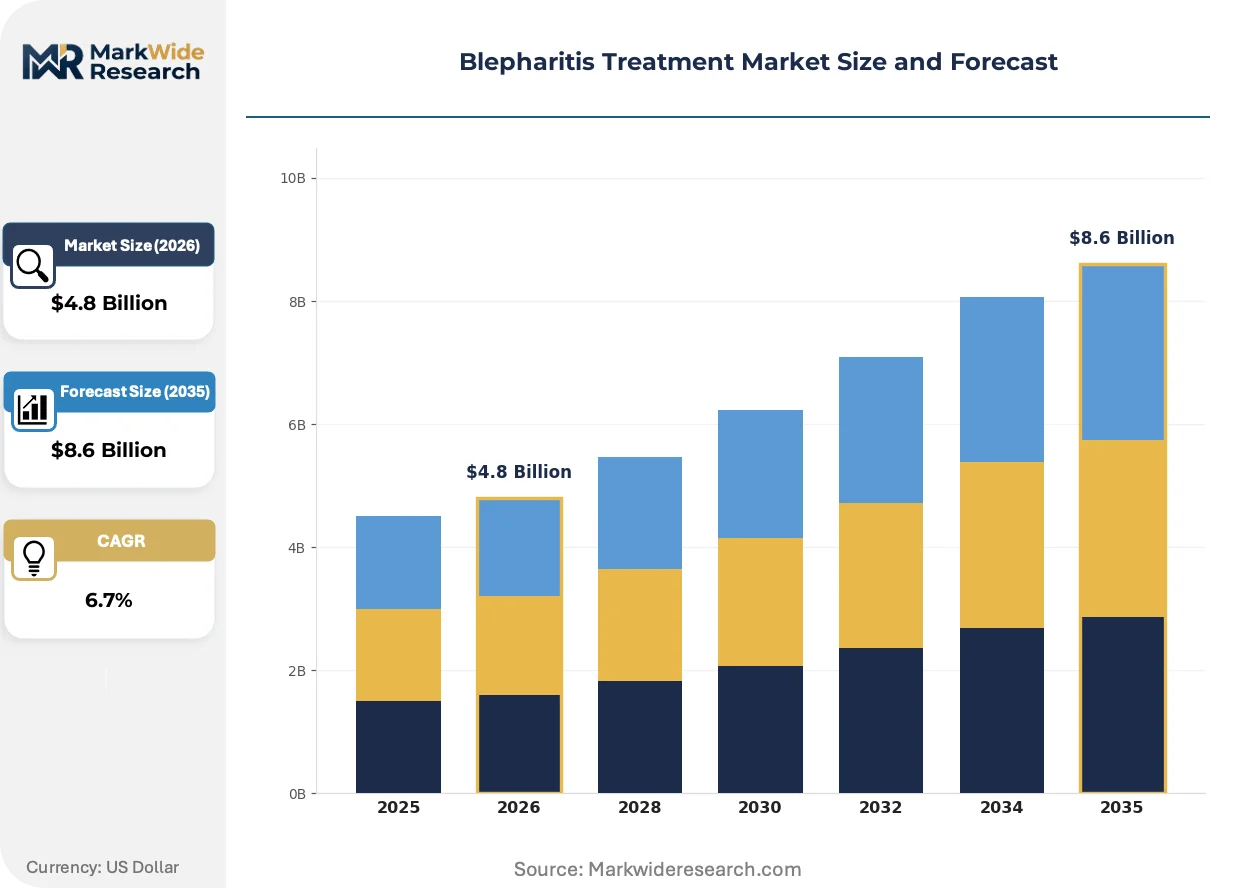
Market Dynamics
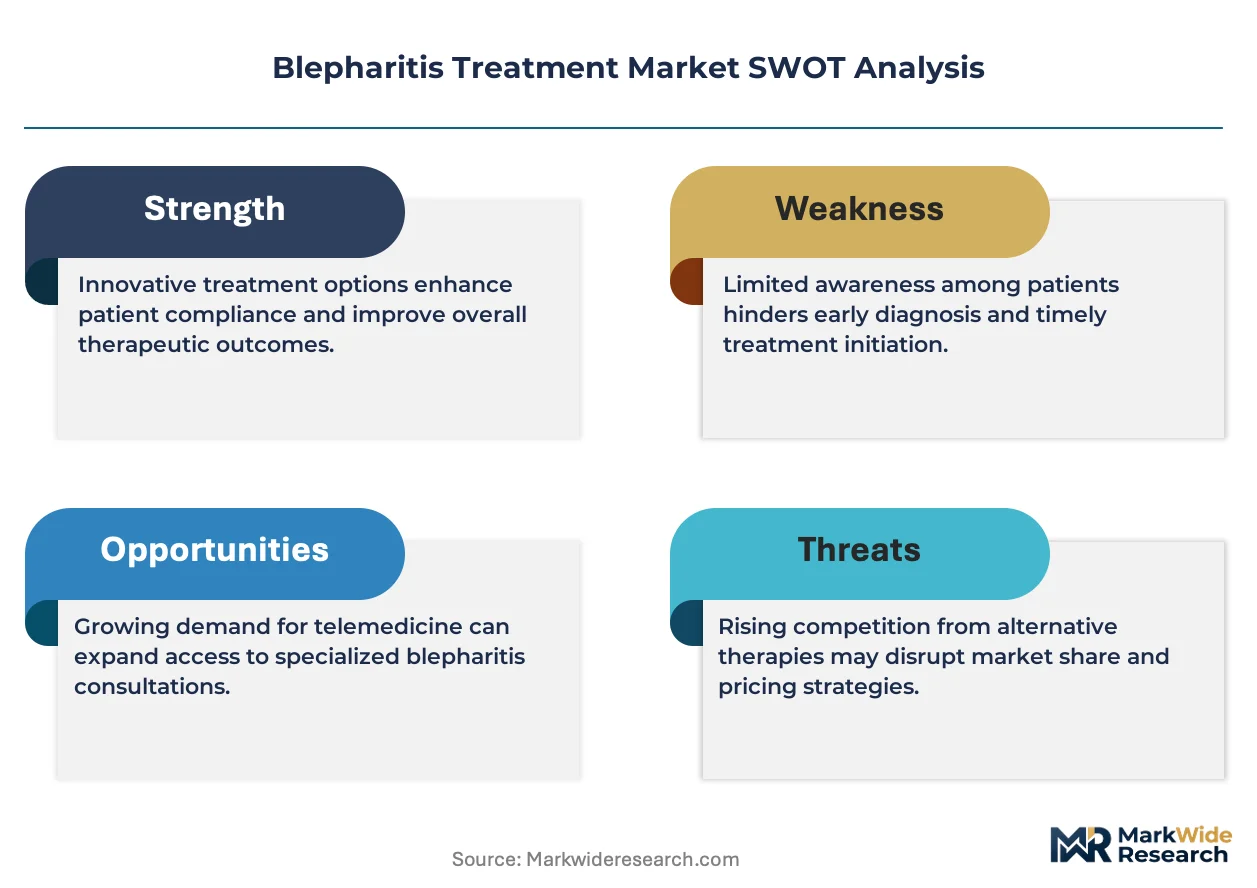
FDA sterility assurance mandates for topical ophthalmic formulations are elevating manufacturing compliance costs, filtering smaller entrants from the blepharitis treatment supply base and consolidating competitive positioning among established pharmaceutical infrastructure holders.
Growth Catalysts
- Chronic disease management protocols:Ophthalmology clinics are expanding dedicated eyelid margin disease programs, creating dedicated reimbursement pathways for thermal pulsation and lid hygiene interventions.
- EPA antimicrobial stewardship frameworks:These guidelines are accelerating adoption of anti-demodex formulations with reduced resistance profiles, favoring azithromycin and metronidazole over legacy broad-spectrum antibiotics.
- Homecare compliance advantages:Spray delivery formats are capturing patient preference for self-administered maintenance therapy, reducing clinic visit burden and extending treatment adherence curves.
Market Restraints
- API supply concentration:Azithromycin active pharmaceutical ingredient production clusters in India and China, exposing formulation sponsors to geopolitical trade friction and import inspection delays.
- EMA MDR device classification:Thermal pulsation systems face elevated clinical evidence requirements under European Medical Device Regulation, extending registration timelines and capital lock-up periods.
- Generic antibiotic substitution:Low-cost oral doxycycline prescriptions for posterior blepharitis compete directly with premium topical formulations, compressing pricing power for novel entrants.
Strategic Opportunities
- Biological intervention white space:Prior authorization tightening for chronic-stage biologicals creates opening for mid-tier anti-inflammatory modalities in the United States specialty eye care networks.
- Integrated R&D convergence:Anti-inflammatory and antimicrobial pipeline combination therapies address polymicrobial blepharitis etiology, differentiating from single-mechanism legacy products.
- Direct-to-clinic channel control:Asset-light licensing partnerships enable biotech developers to bypass distributor margin stacking while retaining formulary influence.
Industry Challenges
- Sterility assurance validation:FDA ophthalmic guidance demands aseptic processing capabilities that require seven-figure cleanroom infrastructure investments, constraining bootstrap development models.
- Meibomian gland function biomarker standardization:Absence of consensus diagnostic endpoints complicates clinical trial design and payer evidence requirements for novel therapeutic claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blepharitis Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antibiotics, Antiseptic Solutions, Warm Compresses, Lid Scrubs Delivery Mode: Ointment, Gel, Spray, Solution End User: Hospitals, Clinics, Homecare, Specialty Eye Care Centers Treatment Stage: Acute, Chronic, Recurrent, Preventive |
| Companies Covered | Tarsus Pharmaceuticals, AbbVie (Allergan), Novartis AG, Bausch Health Companies, Pfizer Inc., Santen Pharmaceutical, Regeneron Pharmaceuticals, Sun Pharmaceutical Industries, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blepharitis Treatment Market Emerging Trajectories
Thermal pulsation technology and spray-based homecare delivery are compressing the traditional clinic-dependent treatment model, while regulatory frameworks on both sides of the Atlantic recalibrate manufacturing and evidence standards for ocular surface interventions.
Intense pulsed light therapy targeting meibomian gland dysfunction is rendering obsolete manual expression and warm compress protocols in premium ophthalmology practices. Academic medical centers and consolidated specialty networks are adopting IPL systems at accelerated replacement cycles for their chronic blepharitis patient flows. This technology shift is compressing service revenue per patient while capturing higher equipment utilization rates.
EMA MDR requirements for ophthalmic devices are forcing thermal pulsation manufacturers to generate prospective clinical data beyond predicate equivalence. European notified bodies are rejecting legacy 510(k) clearance documents as sufficient evidence, extending registration timelines by eighteen to twenty-four months. German and French distributors are prioritizing MDR-certified inventory, creating first-mover advantage for compliant sponsors.
Specialty eye care network consolidation in the United States is compressing vendor count and unbundling after-sales service from device procurement. Purchasing committees at multi-site ophthalmology platforms are demanding outcome-based utilization guarantees from thermal pulsation suppliers. This behavioral shift is most visible in the Southeast and Southwest regional clusters where private equity-backed practice aggregation has concentrated buying power.
Blepharitis Treatment Market Segmentation
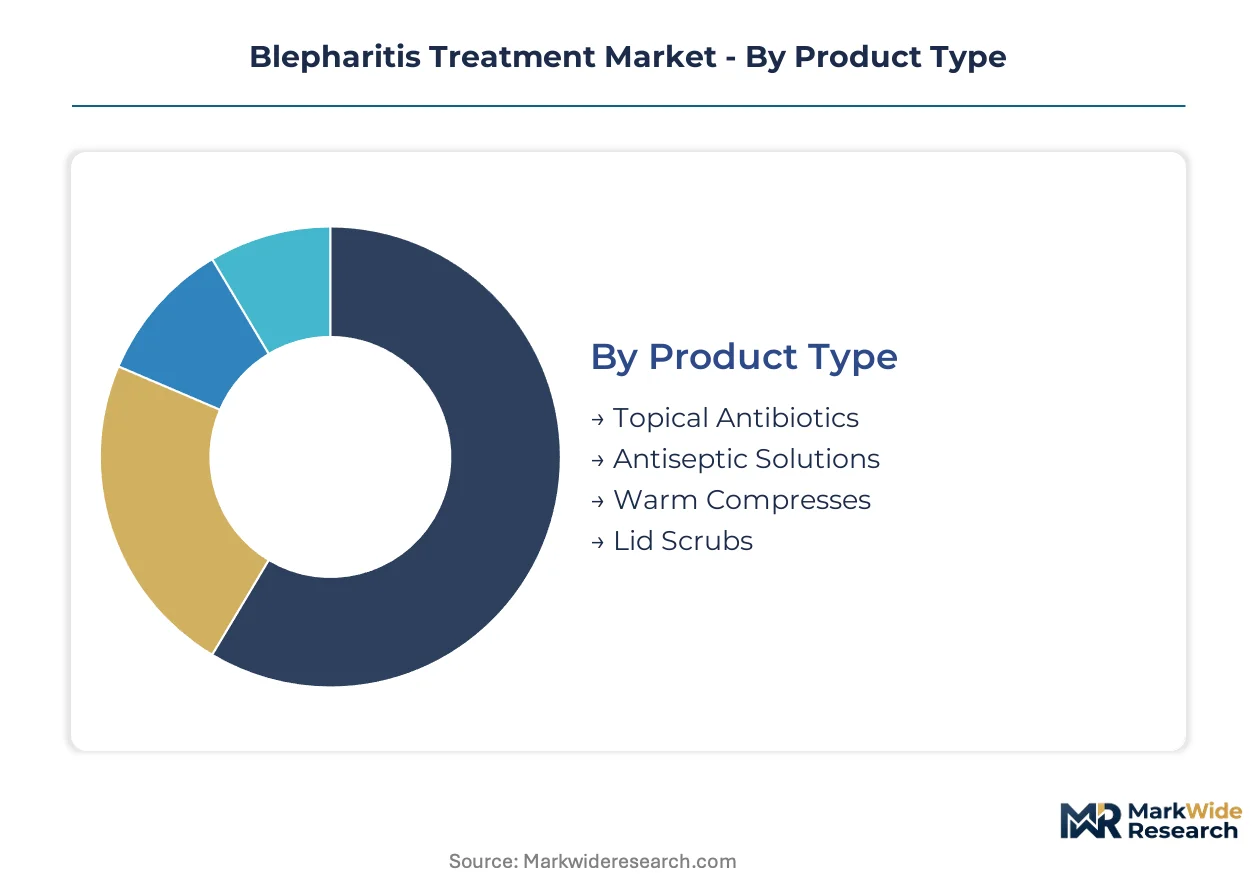
Blepharitis treatment segmentation reflects divergent compliance economics across delivery formats and care settings. Product type and delivery mode choices directly determine sterilization infrastructure requirements and channel margin structures.
Product Type:
After-sales service intensity varies sharply across pharmacological versus mechanical interventions, with device-dependent segments requiring clinical training support and consumable-based segments demanding replenishment logistics.
- Topical Antibiotics:Azithromycin and metronidazole formulations with anti-demodex activity dominate prescribing patterns. Demand concentrates in United States specialty eye care networks where FDA sterility assurance mandates elevate manufacturing barriers and consolidate supplier bases.
- Antiseptic Solutions:Hypochlorous acid and tea tree oil derivatives target bacterial and parasitic load reduction. German and French distributors prioritize MDR-certified inventory, creating registration timeline advantages for compliant sponsors.
- Warm Compresses:Thermal therapy devices for meibomian gland expression require outcome-based utilization guarantees from multi-site ophthalmology platforms.
- Lid Scrubs:Pre-moistened pad formats compete on homecare compliance advantages against spray alternatives.
Topical Antibiotics holds the largest share; momentum sits with Antiseptic Solutions.
Delivery Mode:
Cost tier differentiation separates premium sterile formulations from economy alternatives, with compliance-driven pricing stratification across patient-administered versus clinic-dependent applications.
- Ointment:Petroleum-based and emulsion vehicles with prolonged ocular surface contact time. Retains preference among United States Medicare demographics where gel-to-ointment switching incurs prior authorization friction.
- Gel:Aqueous and carbomer matrices enabling precise lid margin application. Expanding fastest in Southeast and Southwest regional clusters where private equity-backed practice aggregation concentrates formulary decision-making.
- Spray:Metered-dose formats for self-administered maintenance therapy. Capturing patient preference for reduced clinic visit burden.
- Solution:Dropper and wash formulations for acute inflammatory flares. Facing generic substitution pressure from oral doxycycline alternatives.
Ointment retains the dominant position; Spray climbs the fastest on homecare adoption curves.
End User:
Customer type segmentation maps to reimbursement pathway complexity, with institutional purchasers demanding evidence packages that self-pay homecare channels rarely require.
- Hospitals:Inpatient ophthalmology units and emergency departments managing acute infectious blepharitis complications. United States academic medical centers drive thermal pulsation system replacement cycles.
- Clinics:Community ophthalmology and optometry practices delivering first-line mechanical and pharmacological therapy. EPA antimicrobial stewardship frameworks accelerate anti-demodex formulation adoption.
- Homecare:Direct-to-patient delivery of maintenance lid hygiene products. Spray formats reduce adherence abandonment versus ointment protocols.
- Specialty Eye Care Centers:Consolidated multi-site platforms with dedicated eyelid margin disease programs. Purchasing committees unbundle after-sales service from device procurement.
Clinics command the greatest volume; Specialty Eye Care Centers gain share fastest on network consolidation.
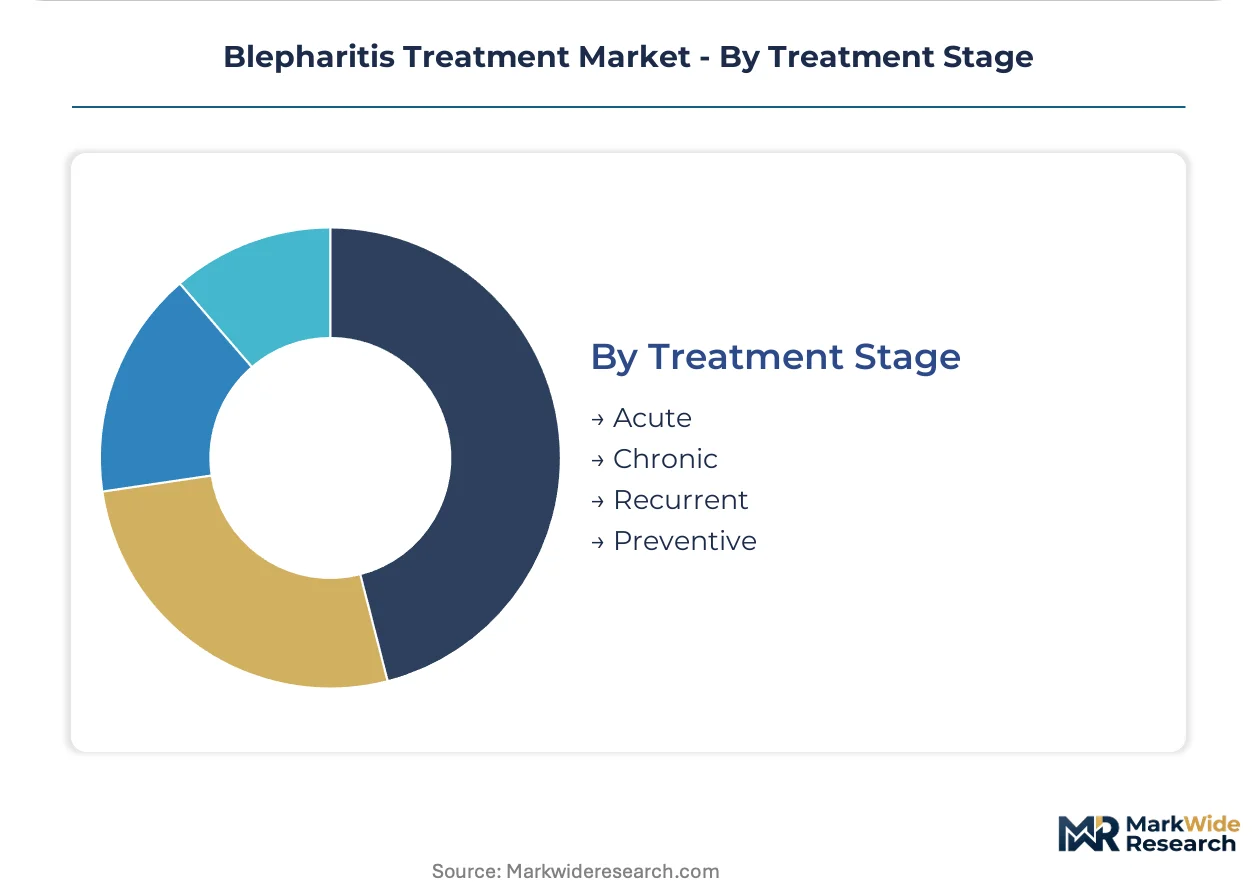
Treatment Stage:
Maturity differentiation separates established acute-stage protocols from emerging chronic-stage biological interventions, with prior authorization tightening creating mid-tier positioning opportunities.
- Acute:Short-course topical antibiotic and antiseptic protocols for inflammatory flares. Generic oral doxycycline competes directly with premium topical formulations.
- Chronic:Extended-duration therapy with thermal pulsation and lid hygiene maintenance. Commands premium positioning due to longer treatment durations and higher abandonment rates.
- Recurrent:Cyclical intervention patterns requiring patient education and compliance monitoring. Intense pulsed light therapy displaces manual expression in premium practices.
- Preventive:Prophylactic lid hygiene for high-risk demographics including rosacea patients and contact lens wearers. Homecare spray formats extend adherence curves.
Chronic-stage interventions generate the highest revenue per patient; Preventive protocols expand most quickly on early detection investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sterility assurance mandates and EPA antimicrobial stewardship frameworks are reshaping national market access conditions. Specialty eye care network consolidation concentrates procurement power in metropolitan clusters. Reimbursement pathway complexity varies sharply across single-payer and multi-payer systems.
United States
Private equity-backed ophthalmology platforms in the Southeast and Southwest regional clusters are unbundling after-sales service from device procurement. FDA ophthalmic guidance elevates barrier costs for topical formulation entrants. Academic medical centers in Boston and New York Metro drive thermal pulsation system replacement cycles.
Germany
Notified bodies under EMA MDR requirements are rejecting legacy 510(k) clearance documents for thermal pulsation systems. German distributors prioritize MDR-certified inventory, creating eighteen-to-twenty-four month registration timeline advantages for compliant sponsors. The Rhine-Ruhr and Bavarian medical technology clusters concentrate ophthalmic device manufacturing.
Japan
PMDA consultation pathways for combination drug-device products are accelerating anti-inflammatory and antimicrobial modality approvals. METI industrial policy supports domestic ophthalmic formulation capabilities. The Kansai region around Osaka anchors precision manufacturing for sterile topical delivery systems.
India
CDSCO streamlined approval processes for ophthalmic generics are expanding access to azithromycin and metronidazole formulations. The country's national pharmaceutical regulator aligns with WHO prequalification standards for export-oriented API production. Gujarat and Maharashtra pharmaceutical corridors supply active pharmaceutical ingredients to global formulation sponsors.
United Kingdom
NICE technology appraisal pathways are tightening evidence requirements for chronic-stage biological interventions. The Medicines and Healthcare products Regulatory Agency post-Brexit divergence from EMA MDR creates parallel registration obligations. London and Southeast England specialty eye care networks consolidate procurement for lid hygiene maintenance protocols.
Blepharitis Treatment Market Vendor Landscape
On the supply side, the industry is consolidating around established pharmaceutical infrastructure holders with aseptic processing capabilities. FDA sterility assurance mandates filter smaller entrants, compressing the vendor base toward tier-one manufacturers with seven-figure cleanroom investments. Three strategic archetypes dominate: specialty ophthalmology pure-plays, diversified ocular surface disease platforms, and integrated R&D conglomerates with anti-inflammatory pipelines. Competitive moves center on direct-to-clinic channel control and asset-light licensing partnerships that bypass distributor margin stacking.
Among specialty ophthalmology pure-plays, Tarsus Pharmaceuticals exemplifies the direct-to-clinic channel control archetype. AbbVie, through its Allergan heritage, anchors the diversified ocular surface disease platform tier with established dry-eye infrastructure. Novartis AG occupies a position within the integrated R&D conglomerate segment, spanning anti-inflammatory and antimicrobial modalities.
| Leading Market Players |
|---|
| Tarsus Pharmaceuticals |
| AbbVie (Allergan) |
| Novartis AG |
| Bausch Health Companies |
| Pfizer Inc. |
| Santen Pharmaceutical |
| Regeneron Pharmaceuticals |
| Sun Pharmaceutical Industries |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply Flow & Price Mechanics
Azithromycin API production concentration in Gujarat and Maharashtra pharmaceutical corridors exposes formulation sponsors to tariff friction and import inspection delays, compressing margin spreads between FDA-certified sterile formulations and economy-grade alternatives while forcing supply chain redundancy investments.
Pricing Analysis
Certification level creates the primary spread between FDA-grade sterile ointments and economy antiseptic solutions. Three-tier pricing structure across premium sterile formulations, standard MDR-certified devices, and economy generic antibiotics reflects sterility assurance validation costs and reimbursement pathway complexity. Pricing pressure stems from generic oral doxycycline substitution for posterior blepharitis, eroding topical antibiotic premiums. Hospital purchasing committees show highest price sensitivity; specialty eye care networks prioritize outcome-based utilization guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing for sterile ophthalmic formulations concentrates among Indian API producers and Japanese precision delivery system manufacturers. Active pharmaceutical ingredient production draws from Gujarat and Maharashtra corridors in India, with sterile fill-finish capacity anchored in the Kansai region around Osaka. Supply chain risk centers on single-source dependency for azithromycin API subject to CDSCO export inspection protocols. Distribution runs through specialty distributor networks serving consolidated ophthalmology platforms rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intense pulsed light therapy displacement of manual expression protocols signals a high-growth disruption phase, with FDA sterility assurance mandates and EMA MDR requirements creating regulatory chokepoints that favor capitalized incumbents.
For Market Incumbents: Build aseptic processing moats through seven-figure cleanroom infrastructure investments that filter bootstrap competitors. Consolidate thermal pulsation device procurement relationships with private equity-backed ophthalmology platforms in the Southeast and Southwest United States. Counter generic antibiotic substitution pressure by bundling after-sales clinical training with device placements. For New Entrants and Emerging Players: Underpenetration in homecare spray delivery formats offers the most accessible entry vector. Target direct-to-patient channels with metered-dose maintenance therapies that reduce clinic visit burden. Pursue asset-light licensing partnerships with regional distributors to bypass formulary committee gatekeeping. For Investors and Strategic Acquirers: EMA MDR compliance deadlines reshape the acquisition landscape toward MDR-certified thermal pulsation sponsors with eighteen-to-twenty-four month registration timeline advantages. Five-to-ten year viability favors integrated R&D pipelines spanning anti-inflammatory and antimicrobial modalities. Monitor EPA antimicrobial stewardship framework enforcement intensity as biological intervention prior authorization inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Sterility Assurance Compliance | Seven-figure cleanroom investments filter competitors and consolidate supplier bases toward tier-one manufacturers. |
| EMA MDR Certification Pathway | Eighteen-to-twenty-four month timeline advantages accrue to thermal pulsation sponsors with prospective clinical data. |
| Direct-to-Clinic Channel Partnership | Asset-light licensing bypasses distributor margin stacking while retaining formulary influence in consolidated networks. |
| Anti-Inflammatory Pipeline Diversification | Combination therapies addressing polymicrobial etiology differentiate from single-mechanism legacy products. |
| Homecare Spray Format Development | Metered-dose self-administration extends adherence curves and captures patient preference for reduced clinic burden. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to converge on segment estimates.
Demand-supply balance across the analysis window reflects ophthalmology clinic expansion rates, thermal pulsation device replacement cycles, and API production capacity in Indian pharmaceutical corridors. Segmentation dimensions include treatment stage, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to prescription volume and device placement trajectories, with inputs from payer prior authorization tightening patterns and antimicrobial stewardship adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian API producers or accelerated IPL therapy adoption by academic medical centers would shift outcomes. Quarterly review of CDSCO export inspection protocols, EPA antimicrobial stewardship enforcement actions, and private equity ophthalmology platform consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Vision Care Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
CNV (Choroidal Neovascularization) Market