
 Europe Biobanks Market | 2026-2036
Europe Biobanks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biobanks Market Foresight
Project finance and public-private partnership structures for large-scale population biobanks is narrowing the competitive field to entities with sovereign-grade balance sheet capacity. Thermo Fisher Scientific Inc. leverages its end-to-end cold chain portfolio to dominate integrated biobank builds across Northern Europe. Qiagen N.V. specializes in automated nucleic acid extraction workflows that anchor sample-processing throughput for national health initiatives. Merck KGaA sustains deep reagent supply agreements that lock in recurring revenue from biobank quality-control protocols.
A biobank constitutes a structured repository of biological specimens—blood, tissue, urine, saliva, and derived biomolecules—maintained under controlled temperature regimes, typically cryopreservation below -150°C or vapor-phase liquid nitrogen, to preserve molecular integrity for longitudinal research. These facilities serve as critical infrastructure for genetic research, epidemiological cohort studies, and therapeutic development pipelines requiring reproducible sample access. Blood samples occupy the largest volume share given their versatility in genomics, proteomics, and metabolomics applications, though tissue samples command premium storage economics due to stringent histological preservation requirements. Research institutions represent the most fragmented end-user segment, while pharmaceutical companies concentrate procurement through multi-year framework agreements that guarantee priority access to rare-disease cohorts.
EMA's Good Clinical Practice guidelines and the EU General Data Protection Regulation impose strict pseudonymization and consent-traceability standards on cross-border sample transfers, compelling biobanks to invest in interoperable data governance architectures. The EU AI Act adds algorithmic accountability layers to AI-driven sample stratification tools, reshaping vendor qualification criteria for computational biobank platforms. Stakeholders must monitor how national implementations of the European Health Data Space regulation redistribute data sovereignty between member-state biobanks and centralized European research infrastructures.
Market Dynamics
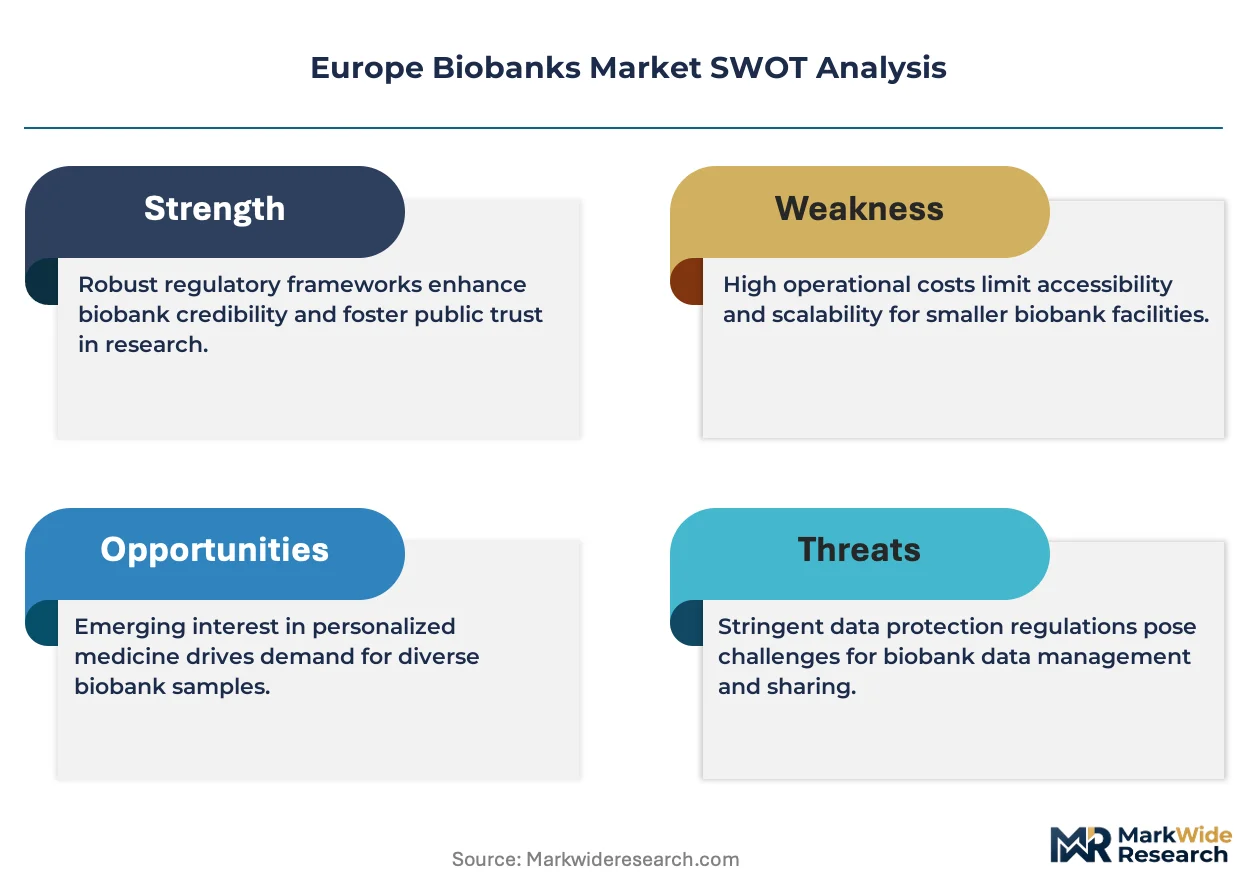
GDPR and the EU AI Act are tightening consent-traceability requirements for genomic data, forcing biobanks to rebuild data governance architectures from sample collection through algorithmic stratification.
Growth Catalysts
- Pharmaceutical longitudinal pipelines:Drug developers are locking multi-year framework agreements that guarantee priority access to rare-disease cohorts, anchoring biobank revenue visibility.
- EMA Good Clinical Practice harmonization:Cross-border pseudonymization standards are enabling sample pooling across member states, expanding research-scale economies.
- Cryopreservation automation:Vapor-phase liquid nitrogen systems with robotic retrieval are cutting sample degradation rates and extending viable storage windows for tissue histology.
Market Restraints
- Liquid nitrogen supply concentration:Industrial gas production clusters in Germany and the Netherlands create single-point vulnerability for cryogenic infrastructure.
- GDPR consent-traceability costs:Retrofitting legacy sample collections with interoperable data governance is absorbing 15-25% of operating budgets at established biobanks.
- Histological preservation complexity:Tissue samples require formalin-fixed paraffin-embedded protocols that demand specialized technician labor unavailable at scale.
Strategic Opportunities
- Eastern European cohort expansion:Poland and Romania hold underexploited population biobank potential with lower land and labor costs for greenfield infrastructure.
- AI-driven sample stratification:Machine learning tools that predict sample utility for specific therapeutic targets are opening premium pricing tiers for annotated collections.
- European Health Data Space implementation:Secondary use provisions for health data will create federated research access models that reduce biobank customer acquisition costs.
Industry Challenges
- Bioinformatics talent scarcity:The intersection of genomic science, data engineering, and GDPR compliance expertise is concentrated at a handful of academic medical centers.
- Legacy LIMS integration:Proprietary laboratory information management systems from the 2000s lack API architectures for modern sample-tracking interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biobanks Market |
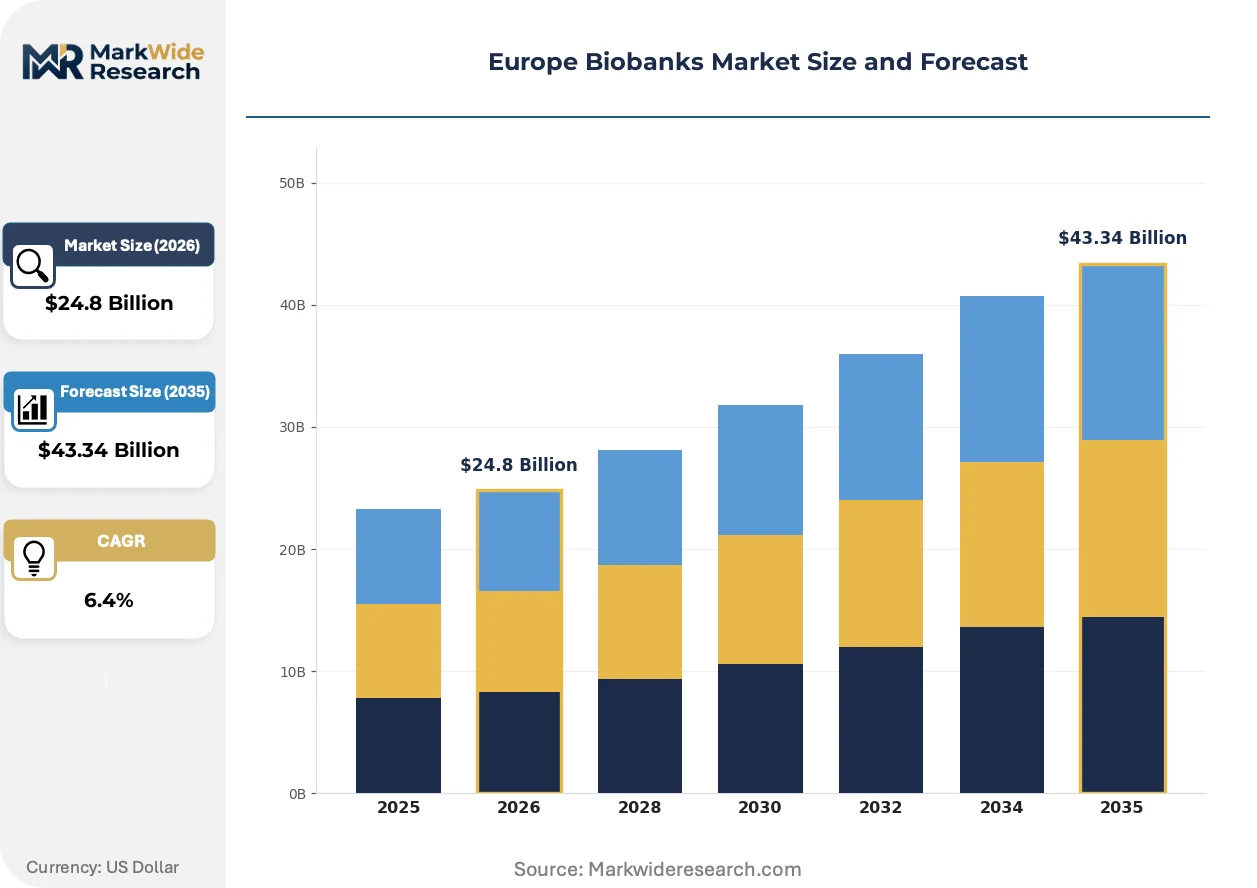
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sample Type: Blood Samples, Tissue Samples, Urine Samples, Saliva Samples End User: Research Institutions, Pharmaceutical Companies, Diagnostics Laboratories, Academic Institutes Storage Technology: Cryopreservation, Ambient Storage, -80°C Freezers, Liquid Nitrogen Tanks Application Area: Genetic Research, Disease Prevention, Drug Development, Personalized Medicine |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Qiagen N.V., Tecan Group AG, Becton Dickinson & Co., Lonza Group AG, Hamilton Company, BioLifeSolutions Inc., Danaher Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biobanks Market Shifts & Advancements
Automation and algorithmic governance are compressing the cost structure of sample processing while regulatory complexity is fragmenting vendor qualification criteria across member states.
Automated nucleic acid extraction workstations are collapsing the labor cost per sample from manual pipetting workflows. National health initiatives in Germany and France are deploying these systems at throughput rates exceeding 10,000 samples daily. The technology is collapsing the competitive advantage of low-wage manual processing locations, reshoring sample preparation to high-regulation jurisdictions.
The EU AI Act's algorithmic accountability requirements are reshaping vendor qualification for computational biobank platforms. Biobanks must now document training data provenance and model drift for AI-driven sample selection tools. Pharmaceutical companies are responding by demanding ISO 27001 certification from biobank software vendors as a baseline procurement filter.
Consortium-based procurement is displacing bilateral biobank-pharma relationships across Northern Europe. Research institutions in Denmark and Sweden are pooling sample access through shared governance structures that reduce per-contract negotiation overhead. This pattern is most visible in oncology cohorts, where multi-site access agreements now outnumber single-biobank contracts by a widening margin.
Europe Biobanks Market Segmentation
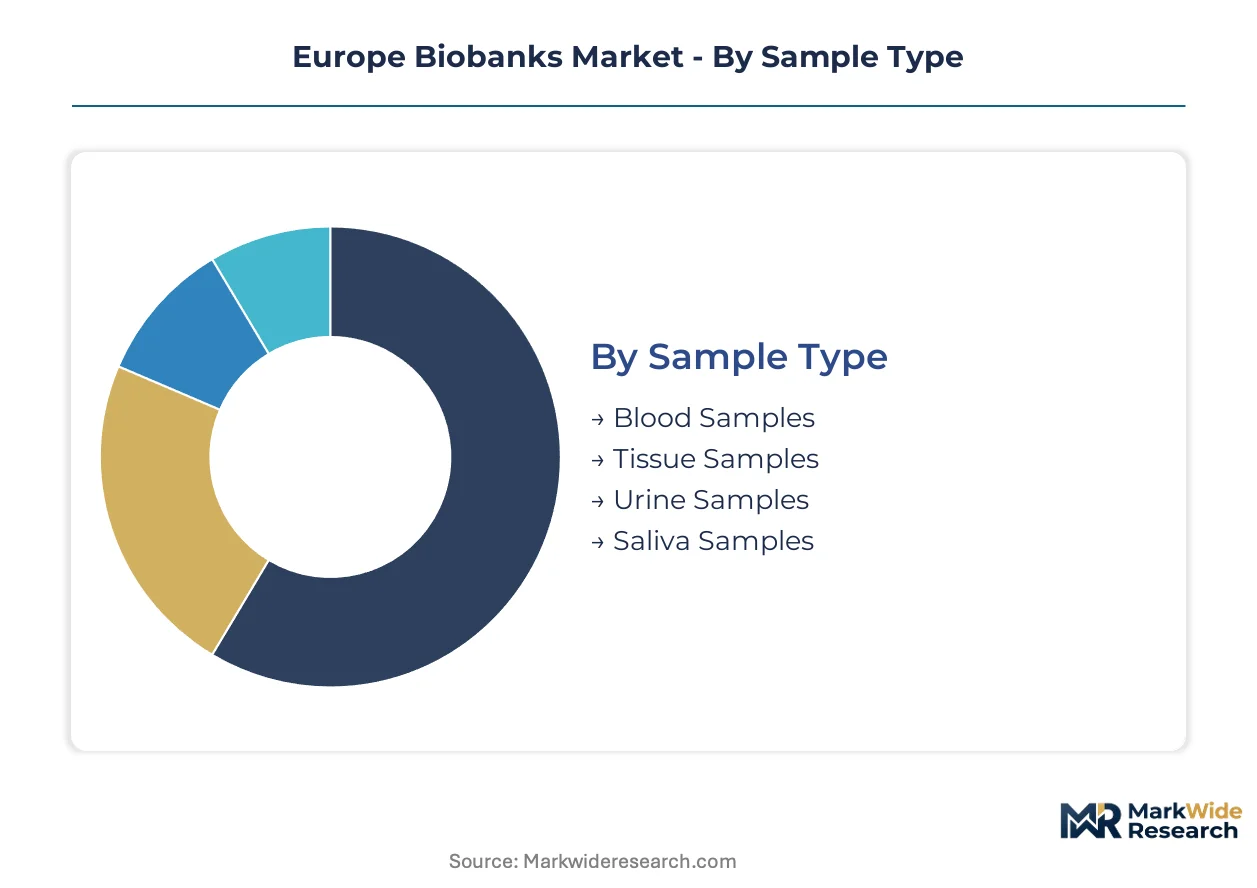
Segmentation in Europe's biobank market reveals how regulatory frameworks and sample complexity reshape procurement priorities across stakeholder groups. Each dimension exposes distinct margin structures, compliance burdens, and partnership models that determine competitive positioning.
Sample Type:
After-sales-service intensity varies sharply across specimen categories, with cryogenic maintenance contracts and quality-audit protocols creating recurring revenue streams that sustain vendor relationships over decades.
- Blood Samples:Serum, plasma, and whole blood collections dominate biobank volumes due to versatility across genomics, proteomics, and metabolomics workflows. German academic medical centers anchor demand for longitudinal cardiovascular cohorts requiring repeated venous draws over multi-decade follow-up periods.
- Tissue Samples:Formalin-fixed paraffin-embedded blocks and fresh-frozen specimens command premium storage economics due to stringent histological preservation requirements. French cancer centers concentrate procurement for oncology biomarker studies, with EMA's Good Clinical Practice guidelines mandating traceable cold-chain documentation for every block.
- Urine Samples:Non-invasive collection and metabolic profiling applications drive adoption in population health initiatives across Nordic countries.
- Saliva Samples:DNA extraction convenience supports direct-to-participant research models, though RNA degradation limits longitudinal utility compared to blood derivatives.
By volume, Blood Samples leads. By growth pace, Tissue Samples is ahead.
End User:
Customer-type concentration determines contract structure, with pharmaceutical procurement favoring multi-year framework agreements while academic users fragment across project-specific purchase orders.
- Research Institutions:Universities and independent research organizations constitute the most fragmented demand pool, with principal investigators securing discrete grants that limit bulk purchasing leverage. Italian and Spanish institutes concentrate activity in rare-disease networks requiring cross-border sample sharing under GDPR pseudonymization protocols.
- Pharmaceutical Companies:Drug developers negotiate priority-access clauses for rare-disease cohorts, locking multi-year commitments that guarantee sample availability for precision pipeline stages. Swiss and Danish headquarters anchor European procurement decisions for global trial portfolios.
- Diagnostics Laboratories:Clinical reference labs seek standardized specimen formats for assay validation studies, with quality-control demands mirroring ISO 15189 accreditation requirements.
- Academic Institutes:Medical school-affiliated biobanks combine research access with clinical training missions, creating hybrid governance structures distinct from pure research or commercial operators.
Pharmaceutical Companies capture the highest contract values per relationship. Research Institutions expand most quickly in absolute site count.
Storage Technology:
Capital intensity and operating cost tiers separate technologies, with vapor-phase liquid nitrogen systems demanding sovereign-grade balance sheet capacity that excludes smaller market entrants.
- Cryopreservation:Controlled-rate freezing below -150°C preserves cellular viability for regenerative medicine applications. German infrastructure providers dominate integrated system builds combining cryogenic hardware with automated inventory management.
- Ambient Storage:Stabilized nucleic acid collection devices enable decentralized sampling without cold-chain logistics, with demand concentrating in Eastern European greenfield biobanks seeking to avoid nitrogen supply vulnerabilities.
- -80°C Freezers:Mechanical ultralow-temperature systems serve DNA and RNA archives where cellular viability preservation is unnecessary, offering lower operating costs than cryogenic alternatives.
- Liquid Nitrogen Tanks:Vapor-phase and liquid-phase systems remain essential for tissue histology and cell-line repositories, with supply concentration in Benelux and German industrial gas clusters creating geographic risk exposure.
By installed base, -80°C Freezers leads. By investment growth, Cryopreservation is climbing the fastest.
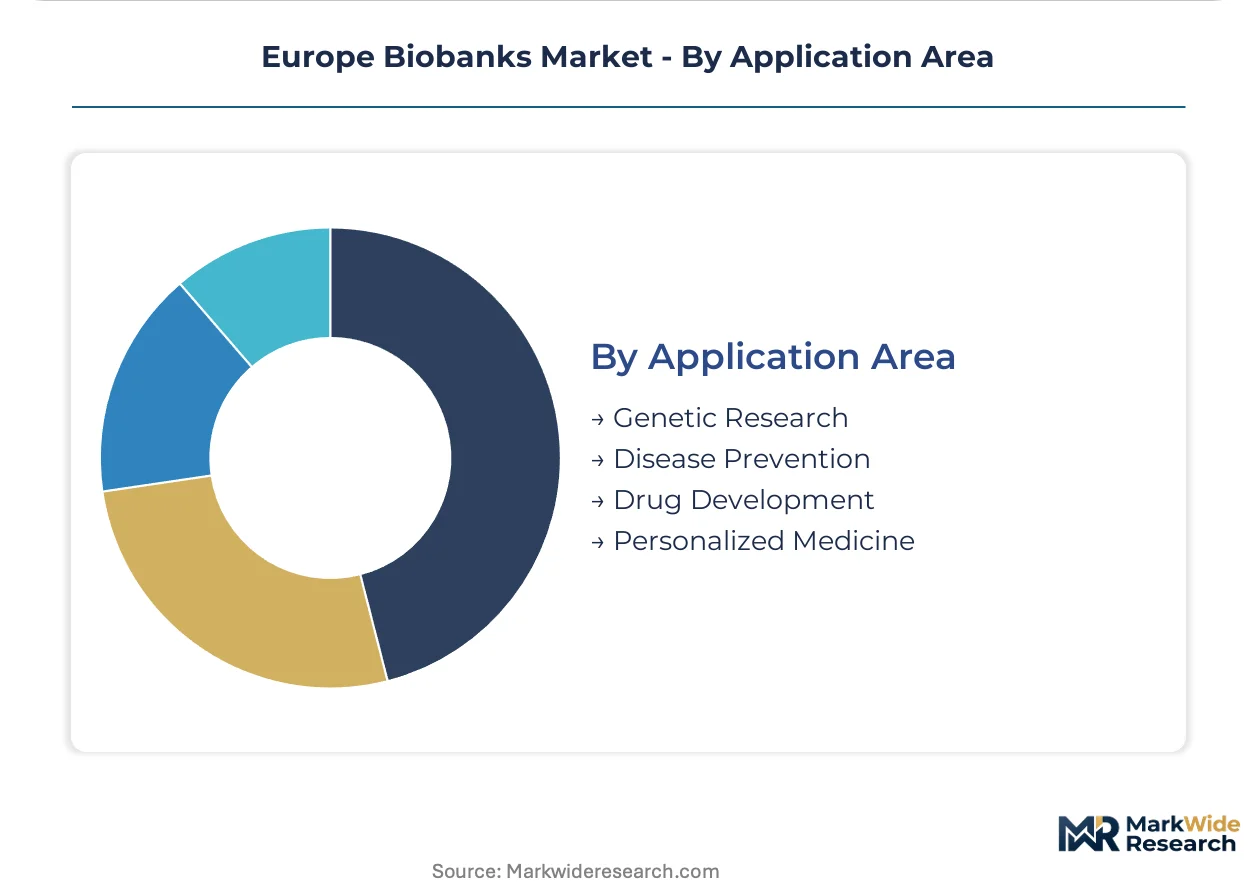
Application Area:
Margin profiles diverge by research objective, with drug-development applications commanding premium pricing for annotated cohorts while population-genetics studies prioritize scale over per-sample revenue.
- Genetic Research:Genome-wide association studies and polygenic risk scoring demand population-scale sample collections with linked electronic health records. UK Biobank and Estonian Genome Center anchor European reference datasets that attract international researcher access fees.
- Drug Development:Target validation and biomarker discovery pipelines require prospectively collected specimens with rich clinical annotation. Pharmaceutical sponsors pay premium access fees for oncology and immunology cohorts with documented treatment response histories.
- Disease Prevention:Screening program biobanks in Finland and the Netherlands support public-health risk stratification models with lower per-sample margins but stable government funding.
- Personalized Medicine:Pharmacogenomic testing and companion diagnostic development create demand for clinically annotated specimens with therapeutic outcome data, with French and German precision medicine initiatives driving infrastructure investment.
Genetic Research holds the deepest sample archives. Personalized Medicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Health Data Space regulation and national precision medicine initiatives are redistributing investment across member states, with funding concentrating where academic medical centers anchor population-scale infrastructure and GDPR-compliant governance frameworks already exist.
Germany
Academic medical centers in Berlin and Munich anchor the continent's largest population cohort infrastructure, with the German National Cohort study driving longitudinal sample collection. The Federal Data Protection Act implements GDPR with additional health-data safeguards that biobanks must navigate for cross-border transfers. Bavaria's Munich biotech cluster concentrates automated cryopreservation system deployment, with Helmholtz Center Munich operating one of Europe's deepest diabetes and metabolic disease sample archives.
United Kingdom
UK Biobank's half-million-participant dataset attracts international researcher access fees and pharmaceutical partnership revenue. The NHS England Genomic Medicine Service mandates standardized sample formats that reduce processing friction for drug developers. London's Francis Crick Institute and Cambridge's Wellcome Sanger Institute form a genomic research corridor with integrated biobank-to-sequencing pipelines that shorten target-validation timelines.
France
French cancer centers concentrate demand for formalin-fixed paraffin-embedded tissue blocks with traceable cold-chain documentation under ANSM guidelines. The national Genomic Medicine 2025 program funds hospital-based biobank expansion for rare-disease diagnostics. Paris-Saclay's research cluster combines Institut Gustave Roussy oncology samples with pharmaceutical R&D partnerships, while Lyon hosts EFS biomaterial banks serving transfusion medicine research.
Sweden
Swedish biobank law enables prospective sample collection with broad consent frameworks that reduce GDPR compliance overhead for longitudinal studies. The LifeGene project and national quality registers create linked health-data architectures prized for epidemiological research. Stockholm's Karolinska Institutet and Uppsala's SciLifeLab operate integrated sample-to-data pipelines that pharmaceutical companies access through consortium-based procurement rather than bilateral contracts.
Netherlands
Dutch population health programs generate stable government funding for screening biobanks with lower per-sample margins but guaranteed volume. The Personalised Medicine Coalition Netherlands coordinates academic hospital sample access for drug developers. Rotterdam's Erasmus MC hosts one of Europe's oldest epidemiological cohorts, with linked biological specimens dating to the 1990s, while Eindhoven's medical technology cluster supplies automated sample processing equipment to domestic and export markets.
Europe Biobanks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: integrated infrastructure providers with sovereign-grade balance sheet capacity, automated workflow specialists capturing national health initiative contracts, and reagent suppliers locking in recurring quality-control revenue. Consolidation pressure favors entities with end-to-end cold chain portfolios and interoperable data governance platforms. Dominant competitive moves include multi-year framework agreements guaranteeing pharmaceutical priority access to rare-disease cohorts, and consortium-based procurement structures reducing per-contract negotiation overhead across Northern European research institutions.
Within the integrated infrastructure tier, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions defined by end-to-end cold chain control and automated sample processing portfolios. Among reagent and quality-control specialists, Merck KGaA exemplifies the archetype of suppliers capturing recurring revenue through long-term supply agreements for biobank validation protocols. Automated nucleic acid extraction specialists including Qiagen N.V. represent the workflow automation tier, anchoring throughput capacity for national health initiatives requiring 10,000-plus daily sample processing rates.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Qiagen N.V. |
| Tecan Group AG |
| Becton Dickinson & Co. |
| Lonza Group AG |
| Hamilton Company |
| BioLifeSolutions Inc. |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Benelux industrial gas clusters determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic risk exposure of cryogenic infrastructure investments across the continent.
Pricing Analysis
Certification level creates the primary spread between pricing tiers, with ISO 27001-certified biobank platforms commanding substantial premiums over uncertified alternatives under EU AI Act procurement filters. Pharmaceutical companies negotiate multi-year framework agreements that lock in priority-access pricing for rare-disease cohorts, while academic research institutions face escalating cost compression due to GDPR retrofitting absorbing operating budgets. Diagnostics laboratories exhibit highest price sensitivity due to ISO 15189 accreditation cost burdens, whereas drug developers prioritize sample quality over unit economics.
Supply Chain Analysis
Tariff exposure between industrial gas producers in Germany and the Netherlands and biobank operators across Eastern Europe dominates supply chain risk assessments for cryogenic infrastructure. Liquid nitrogen production draws from concentrated petrochemical feedstock clusters near Rotterdam and the Ruhr Valley, with vapor-phase system components sourced from Swiss precision manufacturers and automated retrieval robotics from Danish medical technology specialists. Single-source vulnerability in cryogenic logistics creates geographic risk exposure that distribution runs through specialized cold-chain carriers with temperature-validated fleet certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals combining genomic science expertise with GDPR compliance engineering and data architecture skills concentrates competitive advantage at a handful of academic medical centers, creating acquisition premiums for biobanks with captive talent pipelines.
For Market Incumbents: Build switching-cost moats through deep integration of automated nucleic acid extraction workflows with national health initiative contracts, locking in decade-long service relationships. Incumbents should acquire Eastern European greenfield biobank assets before labor cost arbitrage windows close, while investing in interoperable data governance platforms that preempt EU AI Act vendor qualification requirements. Threat of consortium-based procurement displacing bilateral contracts demands early coalition participation. For New Entrants and Emerging Players: Build out ambient storage nucleic acid stabilization capabilities to serve Polish and Romanian greenfield biobanks seeking to bypass nitrogen supply vulnerabilities. The underexploited Eastern European cohort expansion opportunity offers lowest competitive density, with direct-to-participant saliva collection models enabling rapid scale without cryogenic capital intensity. Go-to-market positioning should emphasize AI-driven sample stratification tools that command premium pricing for annotated collections. For Investors and Strategic Acquirers: European Health Data Space implementation reshapes the acquisition landscape toward federated data governance capabilities and cross-border sample access infrastructure. Viable targets combine automated processing throughput with existing GDPR-compliant consent architectures, offering five-to-ten-year revenue visibility through pharmaceutical framework agreements. Monitor national implementations of secondary use provisions as the critical signal for redistributed data sovereignty valuations.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Data Governance Platform Development | EU AI Act mandates algorithmic accountability documentation for AI-driven sample stratification tools used by pharmaceutical sponsors. |
| Automated Cryopreservation System Deployment | Vapor-phase liquid nitrogen infrastructure with robotic retrieval cuts sample degradation rates for German academic medical centers. |
| Eastern European Greenfield Biobank Expansion | Poland and Romania offer lower land and labor costs for population cohort infrastructure outside nitrogen supply chokepoints. |
| Consortium-Based Procurement Structure Formation | Danish and Swedish research institutions pool sample access through shared governance reducing per-contract negotiation overhead. |
| ISO 27001 Certification Investment | Pharmaceutical companies deploy certification as baseline procurement filter for computational biobank platform vendors. |
Research Methodology
Operator-level perspectives from biobank directors, pharmaceutical drug development executives, regulatory affairs leads at EMA and national competent authorities, and hospital procurement managers anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary sources including EMA Good Clinical Practice guideline documentation, GDPR implementation guidance from European Data Protection Board, EU AI Act regulatory text, and national biobank law frameworks across Germany, Sweden, France, and the Netherlands. Bottom-up sample volume estimates by country and segment reconciled with top-down market size validation from public health initiative budget disclosures.
Scenario-bracketing across regulatory implementation timelines and pharmaceutical R&D pipeline prioritization informed the projection framework across the analysis window. Segmentation modeling incorporated sample type complexity tiers, end-user contract structures, storage technology capital intensity, and application area margin profiles. CAGRs derived from historical biobank infrastructure investment patterns and pharmaceutical partnership announcement frequencies, with cross-checks against national precision medicine initiative funding trajectories and cryogenic equipment order backlogs.
Stress conditions across liquid nitrogen supply disruption scenarios, GDPR consent-traceability cost inflation bands, and EU AI Act enforcement intensity gradients were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding pharmaceutical longitudinal pipeline stability and national health data space implementation coherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Ontogenetic Market