
 Neuro Immunoassay Market | 2026-2036
Neuro Immunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro Immunoassay Market Foresight
Academic research laboratories are collapsing as the dominant buyer archetype while clinical laboratories and diagnostics centers capture incremental procurement share. Thermo Fisher Scientific leverages its automated platform portfolio to anchor hospital system contracts across North America. Roche Diagnostics competes through embedded instrument placements that sustain recurring consumable revenue. Meso Scale Diagnostics specializes in multiplex electrochemiluminescence formats that differentiate its offering for biomarker discovery workflows.
Neuro immunoassay denotes antibody-mediated detection methods quantifying neural proteins, neurotransmitters, and autoimmune markers in cerebrospinal fluid, serum, or tissue lysates, typically achieving picogram-per-milliliter sensitivity through chemiluminescent or fluorescent signal amplification. These assays serve primary commercial purposes in Alzheimer's disease differential diagnosis, multiple sclerosis monitoring, and therapeutic antibody pharmacokinetic studies. ELISA formats occupy mature, high-volume positions in clinical reference labs where standardization drives purchasing decisions, while multiplex assays represent the fastest-expanding segment as researchers pursue panel-based biomarker signatures for neurodegenerative conditions. Microfluidics technology commands premium positioning through reduced sample volumes and integrated workflow automation that shrinks turnaround times for time-sensitive neurological emergency evaluations.
FDA premarket review pathways for novel neurological biomarkers and EMA's In Vitro Diagnostic Regulation reshape product development timelines and evidence requirements for market access. ISO 13485 quality management systems and CLIA laboratory certification standards govern manufacturing consistency and analytical validity claims across jurisdictions. Stakeholders must monitor evolving payer coverage determinations for blood-based Alzheimer's assays as these decisions will restructure volume allocation between central labs and point-of-care settings.
Market Dynamics
Clinical laboratories are consolidating purchasing power around automated immunoassay platforms as the FDA and EMA simultaneously tighten biomarker validation standards for neurological diagnostics, forcing vendors to restructure product development timelines and evidence generation strategies.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:The MDR framework mandates higher analytical performance standards that favor established assay manufacturers with robust quality management systems, accelerating replacement cycles in European hospital laboratories.
- Multiplex electrochemiluminescence:Panel-based biomarker detection reduces sample volume requirements and per-test costs for academic medical centers running large-scale neurodegenerative studies.
- Japan's centralized lab networks:Dense metropolitan hospital clusters in Tokyo and Osaka create concentrated procurement volumes that reward vendors with localized technical service capabilities.
Market Restraints
- Antibody raw material concentration:High-affinity neuronal protein antibodies originate from a limited supplier base in the United States and Germany, exposing assay manufacturers to batch-to-batch variability and extended lead times.
- CLIA laboratory certification complexity:The United States requires extensive proficiency testing documentation for novel neurological biomarkers, extending commercialization timelines by 18-24 months for innovative assay formats.
- Luminescence substrate cost volatility:Acridinium ester and ruthenium complex prices fluctuate with rare earth metal markets, compressing gross margins on high-sensitivity chemiluminescent assays.
Strategic Opportunities
- Blood-based Alzheimer's screening:Plasma p-tau217 and NfL assays are penetrating primary care settings in Germany and Japan ahead of United States reimbursement determinations, creating first-mover positioning for platform vendors.
- Microfluidic point-of-care integration:Reduced sample volume requirements enable emergency department deployment for acute stroke biomarker panels, with pilot programs active in academic medical centers across Massachusetts and Bavaria.
- ISO 13485 contract manufacturing:Specialized CDMOs in Switzerland and Singapore offer quality-compliant production capacity for mid-scale assay developers lacking in-house regulatory infrastructure.
Industry Challenges
- Neuroimmunology assay development expertise:Cross-functional scientists combining antibody engineering with neurological disease mechanism knowledge command premium compensation, constraining R&D team scaling for emerging competitors.
- Legacy LIS integration complexity:Hospital information systems in the United States and Germany utilize proprietary data formats that require customized middleware development for automated immunoassay result transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro Immunoassay Market |
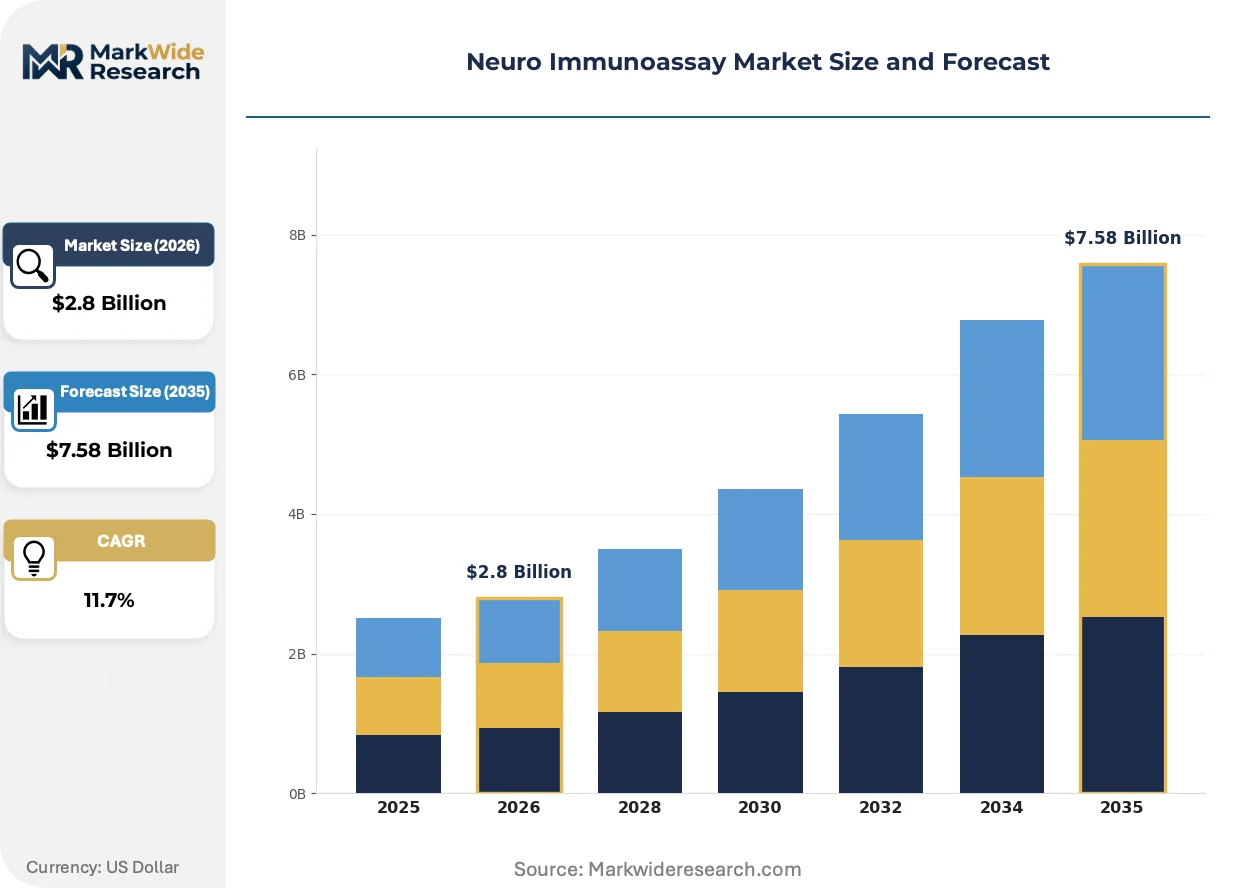
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Western Blot, Rapid Test, Multiplex Assay End User: Academic Research, Clinical Laboratories, Pharmaceutical Companies, Diagnostics Centers Technology: Automated Platforms, Hybrid Systems, Manual Assays, Microfluidics Application: Neurology Research, Biomarker Discovery, Disease Diagnosis, Drug Development |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Siemens Healthineers, Roche Diagnostics, Meso Scale Diagnostics, Merck KGaA, Cell Signaling Technology, Abcam, BioLegend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro Immunoassay Market Shifts & Advancements
Technological convergence between microfluidics and electrochemical detection is compressing assay turnaround times while regulatory pressure on analytical validity is reshaping vendor competitive positioning across major diagnostic markets.
Digital microfluidics platforms are fragmenting the traditional ELISA workflow by enabling programmable droplet manipulation that eliminates manual pipetting steps. Reference laboratories in the United States and Germany are piloting these systems for cerebrospinal fluid biomarker panels. The technology is fragmenting vendor market share by lowering barriers for mid-tier manufacturers to enter high-sensitivity neurological testing.
The FDA's premarket review pathway for novel neurological biomarkers now requires prospective clinical validation studies that demonstrate diagnostic accuracy in intended-use populations. This policy compresses development timelines for blood-based Alzheimer's assays while favoring established manufacturers with existing clinical laboratory relationships. Academic medical centers in California and Massachusetts are responding by consolidating biomarker discovery partnerships around vendors with demonstrated regulatory navigation capabilities.
Hospital system procurement committees are consolidating immunoassay purchasing decisions at the integrated delivery network level rather than individual laboratory autonomy. This behavioral shift concentrates negotiating leverage with large health systems in Texas and Pennsylvania while displacing smaller reference laboratories from direct vendor relationships. The pattern is most visible in the United States where Medicare reimbursement pressure accelerates cost consolidation strategies.
Neuro Immunoassay Market Segmentation
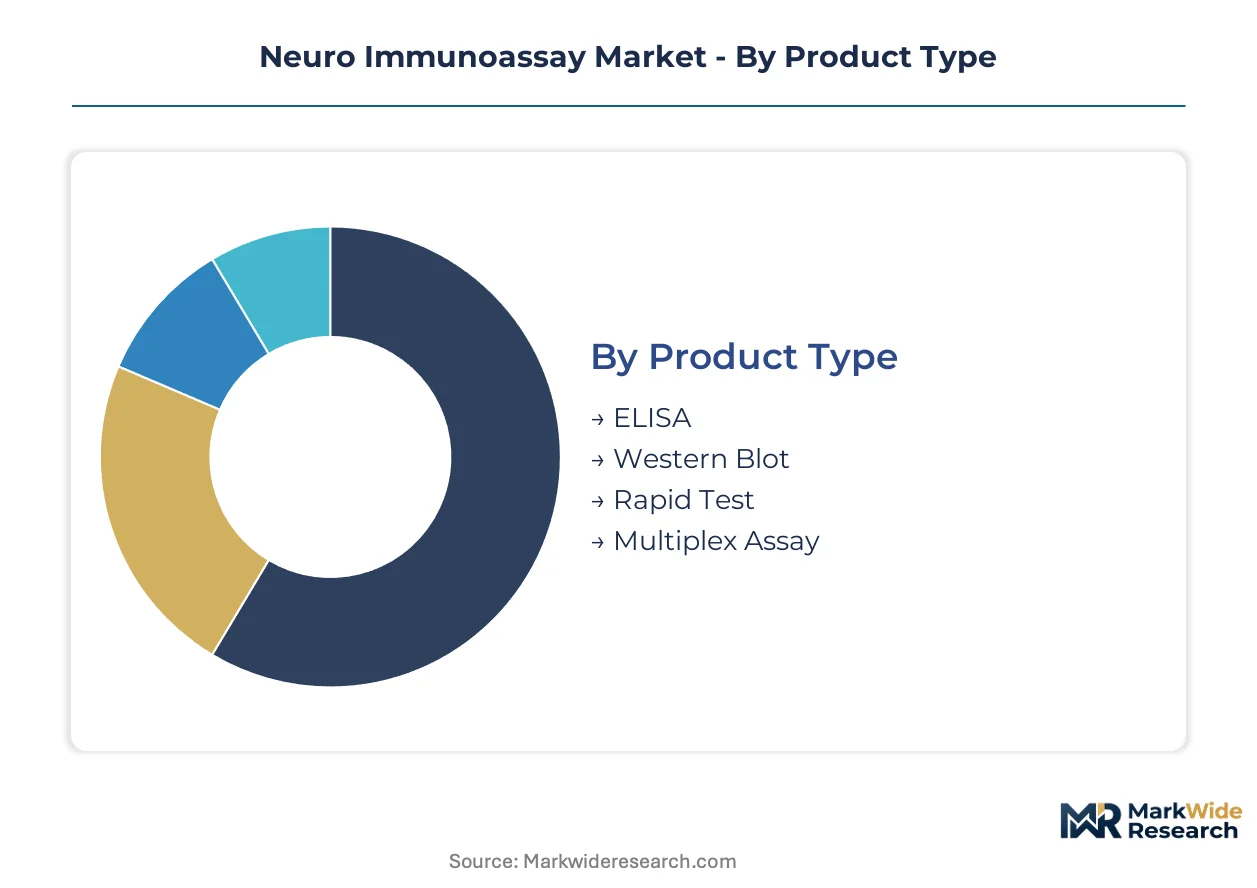
Neuro immunoassay segmentation reveals divergent competitive pressures across product formats, with automation and multiplexing threatening legacy manual workflows while clinical end-users displace academic buyers. Understanding these substitution dynamics helps vendors prioritize R&D investment and channel strategy.
Product Type:
Substitution pressure intensifies most acutely against single-analyte formats as laboratories consolidate purchasing around panel-capable platforms that reduce per-test economics.
- ELISA:Enzyme-linked immunosorbent assays rely on colorimetric or chemiluminescent signal generation with 96-well microplate standardization. Clinical reference laboratories in the United States and Germany anchor procurement volumes where CLIA and ISO 15189 accreditation requirements favor proven analytical validity over novel format experimentation.
- Multiplex Assay:Electrochemiluminescence and bead-based suspension arrays enable simultaneous quantification of 10-100 analytes from single sample volumes. Academic medical centers in Massachusetts and Bavaria concentrate demand as researchers pursue composite biomarker signatures for Alzheimer's differential diagnosis.
- Western Blot:Semi-quantitative protein separation and antibody detection persists in research settings requiring molecular weight confirmation.
- Rapid Test:Lateral flow immunoassays deliver qualitative results at point-of-care with limited sensitivity for neurological applications.
ELISA anchors the volume base while Multiplex Assay gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive automated platform adopters from budget-constrained research laboratories dependent on manual workflows.
- Clinical Laboratories:High-throughput analyzers with integrated sample handling and LIS connectivity serve hospital networks processing 500+ neurological samples daily. Centralized lab networks in Japan's Tokyo-Osaka corridor concentrate procurement volumes that reward vendors with localized field service engineering.
- Diagnostics Centers:Independent reference laboratories and hospital-affiliated testing facilities pursue CLIA-certified assay menus that attract outpatient neurology referrals. Germany's statutory health insurance reimbursement framework shapes test panel composition through positive coverage determinations for CSF biomarker analysis.
- Academic Research:University laboratories and neuroscience institutes prioritize assay flexibility and publication-grade sensitivity over regulatory compliance speed.
- Pharmaceutical Companies:Contract research organizations and sponsor internal bioanalytical groups support therapeutic antibody pharmacokinetic studies with GLP-validated methods.
Clinical Laboratories command the largest revenue share while Diagnostics Centers expand most quickly through outpatient neurology network consolidation.
Technology:
Application urgency determines technology selection, with emergency neurological evaluations demanding microfluidic speed while research workflows tolerate manual throughput limitations.
- Automated Platforms:Random-access analyzers with continuous loading and walkaway operation reduce labor cost per test for high-volume neurological biomarker panels. Roche Diagnostics and Thermo Fisher Scientific instrument placements in United States health systems sustain recurring consumable revenue through reagent rental agreements.
- Microfluidics:Digital droplet manipulation and integrated microchannel networks achieve 10-100 microliter sample volumes with sub-hour turnaround times. Academic medical centers across Massachusetts and Bavaria pilot these systems for acute stroke biomarker triage in emergency departments.
- Hybrid Systems:Semi-automated workflows combine manual sample preparation with automated detection and data reduction.
- Manual Assays:Pipette-intensive ELISA and Western blot protocols persist in low-throughput research settings with limited capital equipment budgets.
Automated Platforms dominate installed base value while Microfluidics climbs fastest through emergency department pilot conversions.
Application:
Customer maturity separates regulated diagnostic applications from exploratory research workflows with divergent evidence requirements and commercial timelines.
- Disease Diagnosis:FDA-cleared and EMA-CE-marked assays for Alzheimer's differential diagnosis and multiple sclerosis monitoring require prospective clinical validation studies. Blood-based p-tau217 and NfL assays penetrate primary care settings in Germany and Japan ahead of United States coverage determinations.
- Biomarker Discovery:Exploratory panel development for novel neurodegenerative signatures demands high-plex screening capacity with minimal sample consumption. Academic consortia in California and Massachusetts concentrate demand around vendors with demonstrated regulatory navigation capabilities.
- Neurology Research:Mechanistic studies of neuroinflammation and synaptic dysfunction prioritize assay sensitivity over clinical diagnostic specificity.
- Drug Development:Pharmacokinetic and pharmacodynamic biomarker support for CNS therapeutic trials follows ICH M10 bioanalytical method validation guidelines.
Disease Diagnosis generates the revenue foundation while Biomarker Discovery shows the steepest expansion trajectory through blood-based Alzheimer's assay development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German assay manufacturers export automated immunoassay platforms to hospital networks across the United States and Japan, while Japanese consumable suppliers ship specialized antibodies to European reference laboratories.
United States
Academic medical centers in Massachusetts and California drive multiplex assay procurement for Alzheimer's biomarker discovery. FDA premarket review pathways for novel neurological biomarkers extend commercialization timelines by 18-24 months for innovative formats. Hospital system procurement committees in Texas and Pennsylvania consolidate purchasing decisions at the integrated delivery network level.
Germany
Statutory health insurance reimbursement frameworks shape CSF biomarker test panel composition through positive coverage determinations. EMA In Vitro Diagnostic Regulation mandates higher analytical performance standards that accelerate replacement cycles in European hospital laboratories. Dense metropolitan hospital clusters in Munich and Heidelberg create concentrated procurement volumes.
Japan
Centralized lab networks in Tokyo and Osaka anchor procurement volumes that reward vendors with localized technical service capabilities. METI standards govern quality management systems for diagnostic device manufacturing. Blood-based Alzheimer's screening assays penetrate primary care settings ahead of United States reimbursement determinations.
Switzerland
Specialized CDMOs in Basel and Zurich offer ISO 13485 contract manufacturing capacity for mid-scale assay developers lacking in-house regulatory infrastructure. Swissmedic oversees diagnostic device quality compliance across cantonal hospital networks. Precision medicine initiatives in Geneva concentrate biomarker validation expertise.
United Kingdom
NHS England's diagnostic transformation programs consolidate neurological testing into regional laboratory hubs. MHRA post-Brexit regulatory pathways reshape biomarker validation requirements for market access. London's academic medical centers partner with vendors on blood-based p-tau217 assay development.
Neuro Immunoassay Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with embedded diagnostic divisions, creating a tiered structure where platform scale separates market tiers. Multinational instrument manufacturers with automated analyzer portfolios occupy the premium tier, while specialized assay developers concentrate in the mid-market biomarker discovery segment. Dominant competitive moves include strategic partnerships between platform vendors and academic medical centers for clinical validation studies, alongside reagent rental agreements that lock in recurring consumable revenue.
Among diversified conglomerates, Thermo Fisher Scientific and Roche Diagnostics exemplify platform-scale archetypes with instrument placement strategies sustaining long-term consumable streams. Meso Scale Diagnostics occupies a specialized position within the multiplex electrochemiluminescence segment, differentiating through panel-based biomarker detection formats. Siemens Healthineers anchors the European-based tier with embedded health system relationships across German hospital networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Roche Diagnostics |
| Meso Scale Diagnostics |
| Merck KGaA |
| Cell Signaling Technology |
| Abcam |
| BioLegend |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates both supplier qualification and price tier placement simultaneously, as manufacturers lacking this quality management system cannot serve clinical laboratories in Germany, Japan, or the United States regardless of cost position.
Pricing Analysis
Next-generation microfluidic platforms command 40-60% premiums over automated ELISA workhorses, while legacy manual formats face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic assays from research-grade reagents and unvalidated antibody pairs. Cost compression in the manual assay tier intensifies because academic research laboratories are losing procurement share to centralized health systems. Clinical laboratories exhibit lowest price sensitivity due to reagent rental agreements that bundle instrument placement with consumable commitments.
Supply Chain Analysis
Antibody raw material concentration in the United States and Germany exposes assay manufacturers to batch-to-batch variability and extended lead times. High-affinity neuronal protein antibodies draw from a limited supplier base centered on California and Bavaria, while acridinium ester and ruthenium complex luminescence substrates hinge on rare earth metal processing in China. Single-source vulnerability concentrates in the antibody supply tier where hybridoma cell line ownership fragments across academic licensors. Distribution runs through specialized life science distributors with cold-chain capabilities serving hospital networks and reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs that lock hospital systems into validated assay platforms for multi-year contract cycles.
For Market Incumbents: Fortify embedded instrument positions through reagent rental agreements that extend consumable revenue visibility. Expand ISO 13485 contract manufacturing capacity in Switzerland to capture mid-scale assay developer demand. Prioritize CLIA laboratory certification support services as emerging competitors face 18-24 month commercialization delays.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks blood-based Alzheimer's screening assays into primary care settings ahead of reimbursement determinations. White-space concentrates in microfluidic point-of-care integration for emergency department stroke biomarker panels. Target academic medical center pilot programs in Massachusetts and Bavaria as validation springboards for hospital system procurement committees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated platform manufacturing as FDA premarket review pathways demand prospective clinical validation studies. Acquisition candidates with demonstrated regulatory navigation capabilities and existing hospital system relationships offer strongest long-term viability through the projection horizon. Monitor payer coverage determinations for plasma p-tau217 assays as the inflection signal restructuring volume allocation between central labs and point-of-care settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Agreement Expansion | Thermo Fisher Scientific and Roche Diagnostics lock hospital systems into recurring consumable revenue through embedded instrument placements. |
| FDA Breakthrough Device Pathway | Meso Scale Diagnostics accelerates blood-based Alzheimer's assay commercialization ahead of Medicare coverage determinations. |
| ISO 13485 Contract Manufacturing Scale-Up | Swiss CDMOs capture mid-tier assay developer demand lacking in-house regulatory infrastructure. |
| Microfluidic Emergency Department Pilot | Academic medical centers in Massachusetts and Bavaria validate acute stroke biomarker panels for health system procurement committees. |
| Multiplex Panel Biomarker Discovery Partnership | California and Massachusetts research consortia consolidate around vendors with demonstrated EMA navigation capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA CE marking databases, hospital procurement records, and CLIA laboratory certification registries. Primary interviews engaged diagnostic platform executives, hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists across the United States, Germany, and Japan. Secondary validation drew from SEC 10-K instrument revenue disclosures, Medicare coverage determination databases, and ISO 13485 certification registries. Bottom-up assay volume estimates triangulated against top-down health system spending analysis.
Segmentation dimensions modeled include product format, end-user category, technology tier, application purpose, and regional regulatory cluster across the analysis window. Growth trajectories derived from instrument placement velocity, reagent consumption patterns, and biomarker validation pipeline progression. Forecast inputs incorporated FDA premarket review timeline assumptions, EMA In Vitro Diagnostic Regulation compliance cost estimates, and payer coverage probability weightings for blood-based neurological diagnostics.
Underlying assumptions cover regulatory pathway stability, antibody supplier base continuity, and hospital procurement consolidation velocity, with deviation risk concentrated in Medicare reimbursement determinations for novel biomarkers and rare earth metal price volatility affecting luminescence substrate costs. Practitioners should keep alternative scenarios live as blood-based Alzheimer's assay coverage policies and microfluidic platform clinical validation outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Global RNA-Interference (Rnai) Market