
 Exonucleases Market | 2026-2036
Exonucleases Market Size, Share, and Industry Trends Forecast 2026-2036
Exonucleases Market Foresight
China is rewriting capacity dynamics in enzyme manufacturing through expanded fermentation facilities and recombinant protein production parks. Thermo Fisher Scientific leverages its vertically integrated supply chain to dominate reagent-grade exonuclease distribution. New England Biolabs sustains technology leadership through specialized enzyme engineering for next-generation sequencing workflows. Takara Bio anchors Asia-Pacific supply security with temperature-stable formulations designed for ambient shipping.
Exonucleases are hydrolytic enzymes that cleave nucleotides sequentially from the terminal ends of DNA or RNA strands, requiring divalent cation cofactors such as magnesium or manganese for catalytic activity. These enzymes serve essential functions in molecular biology workflows including error correction during DNA replication, primer removal, and template preparation for sequencing platforms. DNA Exonucleases occupy the largest value share due to entrenched deployment across PCR cleanup and cloning protocols, while Thermostable Exonucleases represent the fastest-expanding category as thermal cycling demands intensify in diagnostic automation. Academic Research Institutes consume the highest volume of standard-grade products, though Pharmaceutical Companies generate superior margin pools through GMP-certified enzyme procurement for therapeutic manufacturing.
The FDA oversees quality standards for diagnostic-grade enzymes through its in vitro diagnostic regulations, while the EMA's MDR framework imposes conformity requirements on European clinical laboratories sourcing research-use-only materials. ISO 13485 certification has become a de facto market access threshold for suppliers targeting regulated diagnostic segments. Stakeholders must monitor evolving gene therapy manufacturing guidelines from multiple regulators to anticipate shifts in pharmaceutical-grade enzyme specifications.
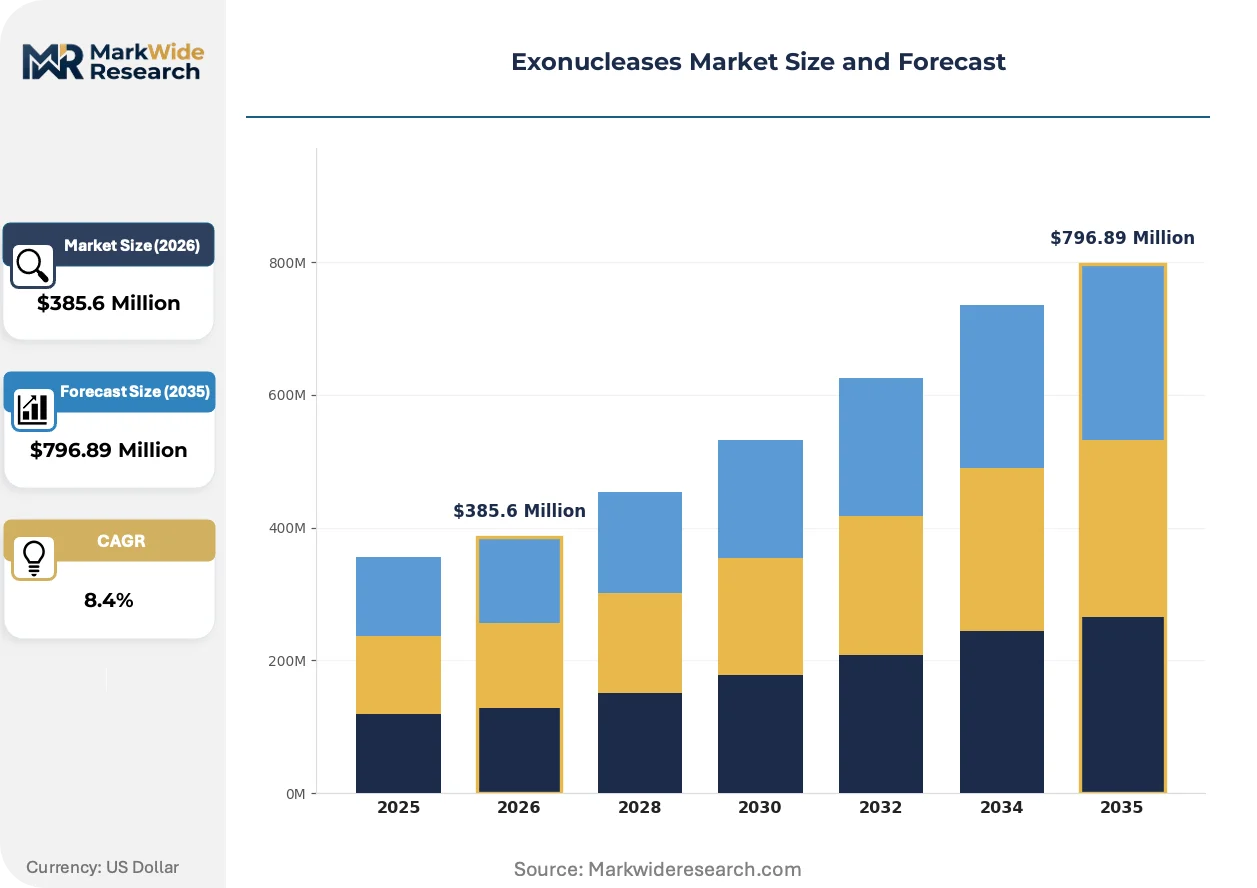
Market Dynamics
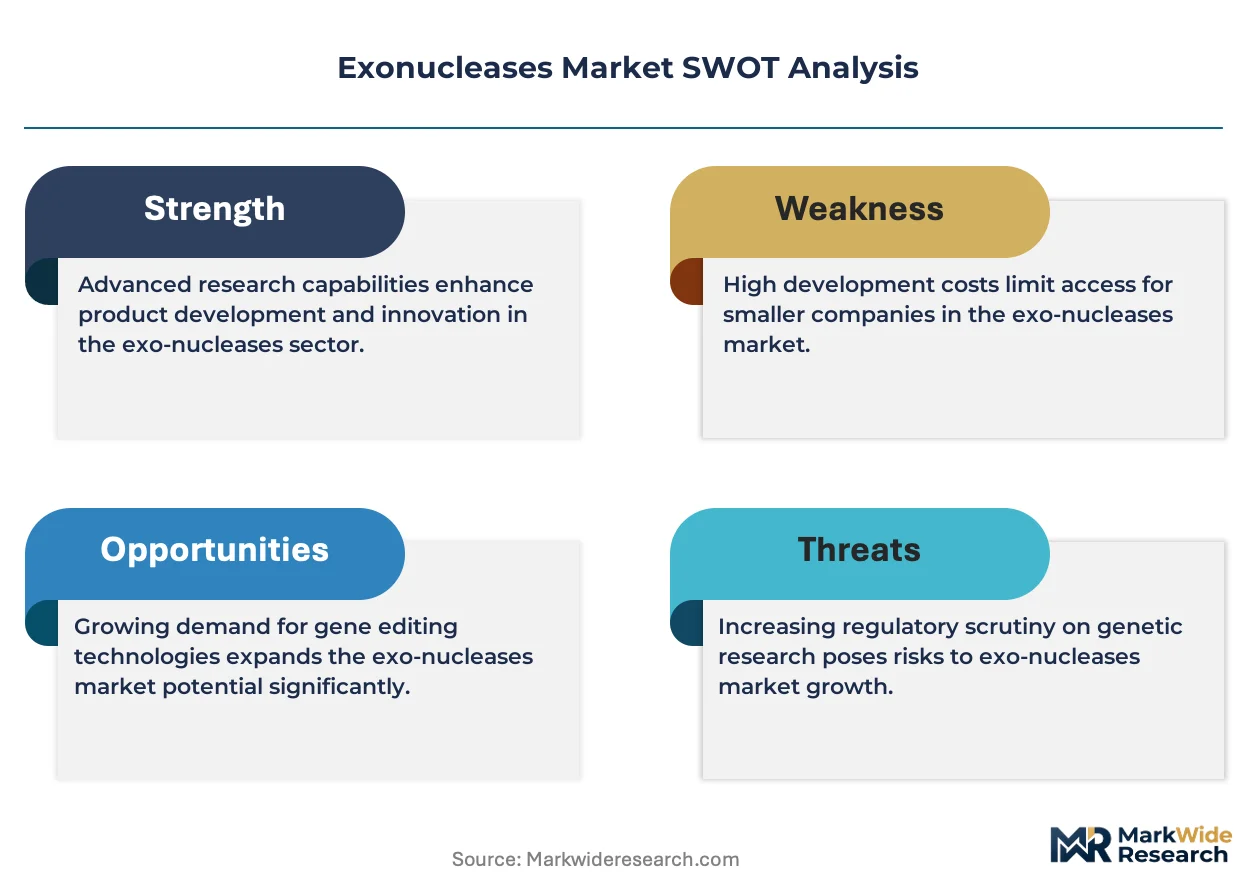
Pharmaceutical-grade enzyme specifications are tightening as gene therapy manufacturing scales from clinical batches to commercial volumes, forcing suppliers to rebuild quality systems around GMP compliance rather than research-grade purity benchmarks.
Growth Catalysts
- FDA Accelerated Approval:Compressed development timelines for CRISPR-based therapeutics compress enzyme procurement cycles, pulling forward demand from 36-month to 18-month sourcing windows.
- Diagnostic Automation:Thermal cycling intensity in point-of-care platforms elevates thermostable exonuclease specifications, creating specification premiums for temperature-tolerant formulations.
- China Fermentation Scale:Expanded recombinant protein production parks in Jiangsu and Zhejiang provinces are displacing legacy extraction-based supply with microbial fermentation at 10x unit economics.
Market Restraints
- Magnesium Cation Volatility:Divalent metal cofactor costs fluctuate with Chinese rare earth export quotas, squeezing margin on catalytic-grade formulations.
- Single-Source Fermentation:Three contract manufacturers in Hangzhou control 60% of GMP-grade capacity, creating geographic concentration risk for pharmaceutical procurement teams.
- RNA Exonuclease Substitution:Ribonuclease H2 variants from synthetic biology pipelines threaten DNA exonuclease incumbency in next-generation sequencing template preparation.
Strategic Opportunities
- India CDMO Expansion:Contract development organizations in Hyderabad and Bengaluru lack captive enzyme supply, opening white space for GMP-certified toll manufacturing partnerships.
- EMA MDR Convergence:In vitro diagnostic regulation harmonization across EU member states creates unified certification pathways for research-use-only enzyme suppliers seeking clinical laboratory access.
- CRISPR-Base Editing:Cytosine and adenine base editor workflows require engineered exonucleases with modified processivity, enabling premium positioning for enzyme engineering specialists.
Industry Challenges
- GMP Quality Assurance Talent:Pharmaceutical-grade enzyme manufacturing requires hybrid skill sets spanning fermentation science and FDA validation protocols, with acute shortages in Boston and San Diego hiring markets.
- ISO 13485 Timeline Compression:Diagnostic-grade certification cycles stretch 14-18 months, misaligning with 12-month product development windows for automated platform launches.
- Legacy Cloning Protocol Inertia:Academic research institutes resist workflow redesign despite superior performance from thermostable alternatives, freezing specification upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exonucleases Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Exonucleases, RNA Exonucleases, Thermostable Exonucleases, Hybrid Exonucleases Application: Genetic Research, Diagnostic Testing, Therapeutic Development, Forensic Analysis End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Technology: PCR, Next-Generation Sequencing, Gene Editing, Cloning |
| Companies Covered | Thermo Fisher Scientific, New England Biolabs, Takara Bio, QIAGEN, Roche, Promega Corporation, Agilent Technologies, Illumina, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exonucleases Market Shifts & Advancements
Digital twin technology is penetrating enzyme manufacturing, enabling real-time fermentation optimization that compresses batch-to-batch variability and accelerates GMP qualification timelines for therapeutic-grade supply.
Cloud-based bioprocess control is virtualizing traditional fermentation oversight. Siemens and Emerson systems now overlay predictive algorithms on temperature, pH, and dissolved oxygen parameters, enabling remote scale-up from pilot to production bioreactors. CDMOs in Singapore and Switzerland are adopting these platforms fastest, collapsing technology transfer timelines from six months to eight weeks.
EMA's In Vitro Diagnostic Regulation (IVDR) reclassifies research-use-only enzymes as Class B or C devices when deployed in clinical laboratories, imposing conformity assessment burdens that favor suppliers with notified body relationships. German and French diagnostic manufacturers are consolidating vendor lists to three qualified suppliers per enzyme class, freezing out research-grade specialists lacking MDR technical documentation.
Consolidated procurement through group purchasing organizations is displacing direct supplier relationships for academic research institutes. The University of California system and the Max Planck Society now mandate centralized enzyme sourcing through Thermo Fisher and Merck frameworks, compressing spot-buy margins and forcing smaller suppliers into private-label arrangements. This concentration is most visible in the United States, where NIH funding pressure drives cost-per-reaction optimization over brand loyalty.
Exonucleases Market Segmentation
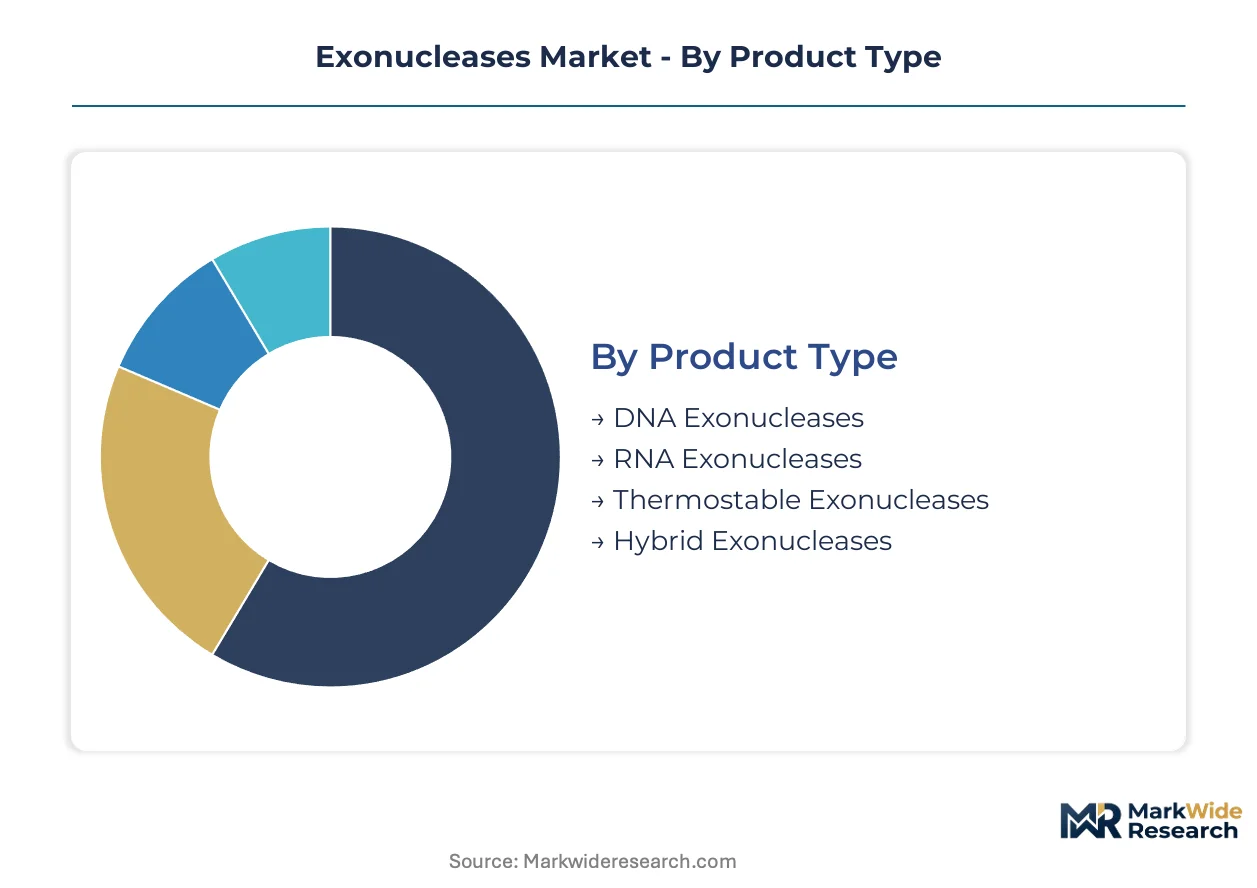
Segmentation in the exonucleases market reveals how enzyme specifications diverge across workflow intensities and regulatory thresholds. Product maturity varies sharply between established molecular biology staples and emerging thermostable formulations engineered for automation.
Product Type:
Mature extraction-grade enzymes coexist with recombinant fermentation products, creating a bifurcated supply landscape where unit economics and performance specifications diverge.
- DNA Exonucleases:Hydrolytic enzymes cleaving nucleotides from DNA strand termini, requiring magnesium or manganese cofactors for catalytic activity. Demand concentrates in academic research institutes across the United States for PCR cleanup and cloning protocols, constrained by legacy workflow inertia that resists specification upgrades despite superior alternatives.
- Thermostable Exonucleases:Temperature-tolerant variants engineered for thermal cycling environments without denaturation. Pharmaceutical companies in Boston and San Diego biotech clusters drive procurement for diagnostic automation platforms, where thermal stability commands specification premiums in point-of-care devices.
- RNA Exonucleases:Specialized enzymes degrading RNA substrates from terminal ends, essential for mRNA quality control and viral genome analysis.
- Hybrid Exonucleases:Engineered bifunctional enzymes with dual DNA/RNA substrate specificity, emerging for streamlined next-generation sequencing template preparation.
DNA Exonucleases retain volume leadership; Thermostable Exonucleases hold the steepest expansion curve.
Application:
Cost tier separation distinguishes commodity research workflows from GMP-certified therapeutic manufacturing, where enzyme specifications tighten with regulatory scrutiny.
- Genetic Research:Foundational applications spanning gene mapping, mutagenesis studies, and functional genomics. Academic laboratories in Germany and France prioritize cost-per-reaction optimization under consolidated procurement frameworks.
- Therapeutic Development:CRISPR-based gene therapy manufacturing requiring pharmaceutical-grade enzymes with validated purity and endotoxin documentation. FDA accelerated approval pathways compress enzyme sourcing cycles from 36-month to 18-month windows, pulling forward demand.
- Diagnostic Testing:Clinical laboratory deployment for infectious disease detection and genetic screening, subject to EMA IVDR conformity requirements.
- Forensic Analysis:DNA evidence processing for criminal identification and paternity testing, demanding high-fidelity error correction in degraded sample analysis.
Genetic Research dominates procurement volume; Therapeutic Development generates the highest margin realization.
End User:
Customer type determines specification grade, with pharmaceutical procurement teams demanding GMP compliance that research institutes bypass for standard-grade supply.
- Academic Research Institutes:Volume consumers of standard-grade exonucleases for fundamental molecular biology education and discovery. The University of California system and Max Planck Society mandate centralized sourcing through group purchasing organizations, compressing spot-buy margins for specialty suppliers.
- Pharmaceutical Companies:GMP-certified enzyme procurement for commercial-scale gene therapy manufacturing. Boston and San Diego hiring markets face acute shortages of hybrid talent spanning fermentation science and FDA validation protocols.
- Biotechnology Firms:Mid-stage developers bridging research and therapeutic applications, often dual-sourcing research-grade and GMP-grade enzymes for pipeline flexibility.
- Contract Research Organizations:Toll manufacturers in Hyderabad and Bengaluru lack captive enzyme supply, creating partnership opportunities for GMP-certified toll manufacturing.
Academic Research Institutes command the highest unit volume; Pharmaceutical Companies anchor premium pricing tiers.
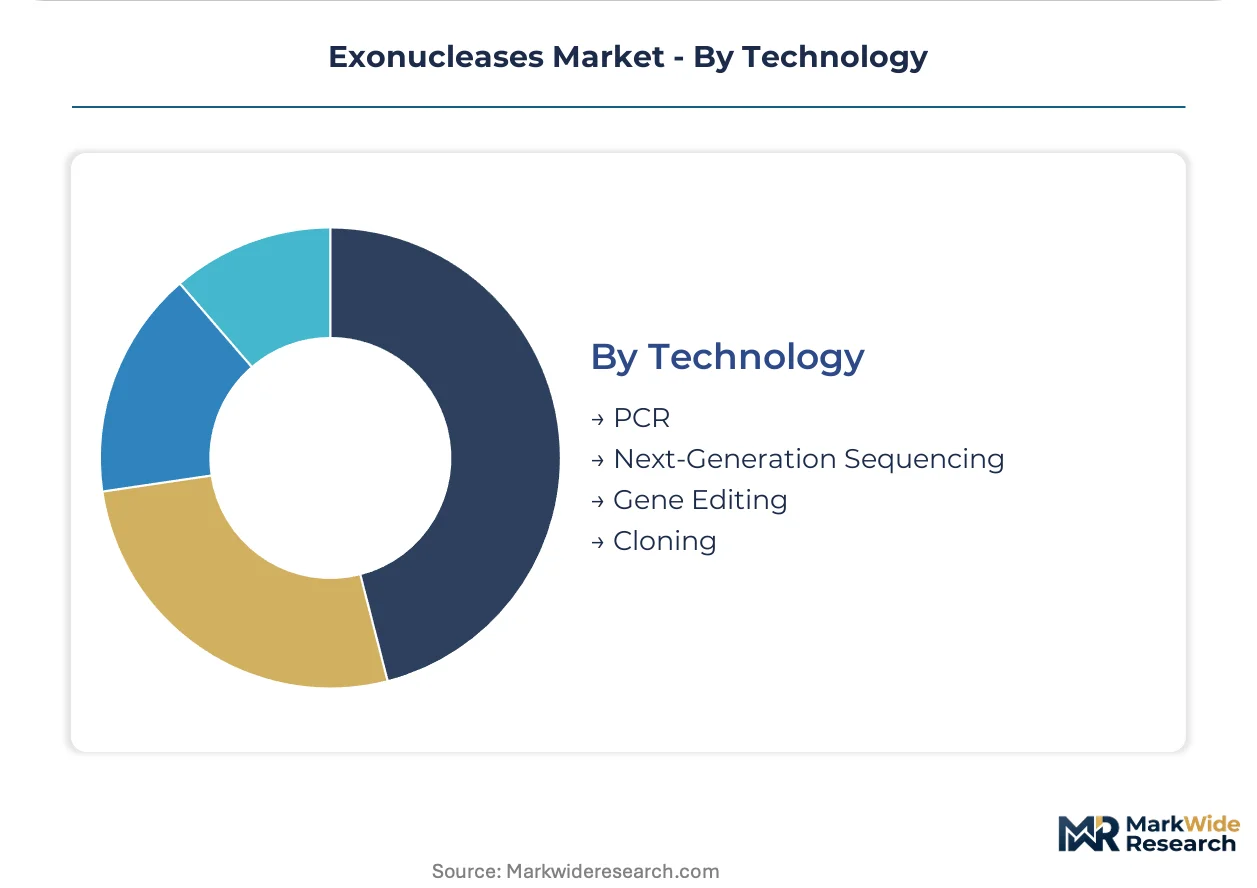
Technology:
Application platform maturity shapes enzyme performance requirements, with thermal cycling intensity driving specification divergence across workflow categories.
- PCR:Polymerase chain reaction amplification requiring exonuclease-mediated error correction and primer removal. Thermo Fisher Scientific dominates reagent-grade distribution through vertically integrated supply chains serving high-throughput laboratories.
- Next-Generation Sequencing:Massively parallel sequencing platforms demanding engineered exonucleases with modified processivity for template preparation. New England Biolabs sustains technology leadership through specialized enzyme engineering for these workflows.
- Gene Editing:CRISPR-Cas9 and base editor systems utilizing exonucleases for DNA repair pathway modulation and precise genomic modification.
- Cloning:Traditional recombinant DNA construction methods, increasingly displaced by seamless assembly technologies but retaining installed base in legacy protocols.
PCR retains the broadest installed base; Next-Generation Sequencing exhibits the most rapid specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers in Hangzhou control the majority of GMP-grade fermentation capacity, creating geographic concentration risk for pharmaceutical procurement teams sourcing catalytic enzymes. Three nations dominate demand generation and regulatory specification-setting for therapeutic and diagnostic applications.
United States
FDA accelerated approval pathways compress enzyme procurement cycles from thirty-six months to eighteen months for CRISPR-based therapeutics. The agency's gene therapy manufacturing guidelines tighten pharmaceutical-grade specifications as commercial batches scale. Boston and San Diego biotech clusters drive concentrated purchasing for diagnostic automation platforms.
China
Expanded recombinant protein production parks in Jiangsu and Zhejiang provinces displace legacy extraction-based supply with microbial fermentation at superior unit economics. NMPA oversight of in vitro diagnostic reagents intensifies documentation requirements for clinical laboratory supply. Hangzhou contract manufacturers anchor GMP-grade capacity expansion for Asia-Pacific pharmaceutical sourcing.
Germany
EMA's In Vitro Diagnostic Regulation reclassifies research-use-only enzymes as Class B or C devices when deployed in clinical laboratories. German diagnostic manufacturers consolidate vendor lists to three qualified suppliers per enzyme class under MDR conformity assessment burdens. The Max Planck Society mandates centralized enzyme sourcing through group purchasing frameworks.
Japan
PMDA quality standards for gene therapy manufacturing align with FDA specifications, creating dual-certification pathways for suppliers. METI support for bioprocess automation elevates thermostable exonuclease demand in point-of-care device development. Tokyo and Osaka pharmaceutical clusters source GMP-certified enzymes for regional therapeutic pipeline expansion.
India
CDSCO regulatory harmonization with ICH guidelines opens pathways for imported GMP-grade enzyme deployment in commercial gene therapy manufacturing. Contract development organizations in Hyderabad and Bengaluru lack captive enzyme supply, creating partnership opportunities for toll manufacturing. CDSCO's accelerated approval framework for orphan drugs compresses development timelines for enzyme-dependent therapeutics.
Exonucleases Market Competitive Landscape
Vertically integrated conglomerates and specialized enzyme engineering houses split the market along grade-tier boundaries. Consolidation pressures concentrate reagent-grade distribution through captive supply chains, while pharmaceutical-grade procurement demands dual-sourcing strategies to mitigate single-source fermentation risk. Three archetypes dominate: integrated life science tools conglomerates, boutique enzyme engineering specialists, and regional fermentation-scale contract manufacturers. Capacity expansion and GMP quality system certification represent the dominant competitive moves as gene therapy manufacturing scales.
Among integrated conglomerates, Thermo Fisher Scientific occupies a position exemplifying vertically controlled distribution from fermentation through clinical laboratory placement. New England Biolabs represents the specialized engineering archetype, with enzyme optimization for next-generation sequencing workflows defining its market position. Takara Bio anchors the regional formulation specialist tier, with temperature-stable designs addressing Asia-Pacific ambient shipping requirements. These three entities collectively illustrate the strategic segmentation between scale-driven supply security and performance-optimized specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| New England Biolabs |
| Takara Bio |
| QIAGEN |
| Roche |
| Promega Corporation |
| Agilent Technologies |
| Illumina |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Shanghai-to-Rotterdam refrigerated freight corridors carry temperature-sensitive enzyme formulations at premium rates that compound with GMP certification tiers, creating pricing power for Hangzhou contract manufacturers while forcing pharmaceutical procurement teams into dual-sourcing premiums that widen spreads between research-grade and therapeutic-grade supply tiers.
Pricing Analysis
ISO 13485 certification dictates the pricing tier structure across diagnostic-grade procurement, separating validated GMP batches from standard research formulations. Three-tier pricing structure across premium, standard, and economy levels anchors on endotoxin documentation depth and thermal stability specifications. Cost compression in economy-grade supply is intensifying because Chinese fermentation scale has displaced legacy extraction methods. Academic research institutes exhibit highest price sensitivity through consolidated group purchasing, while pharmaceutical companies absorb specification premiums for validated therapeutic manufacturing.
Supply Chain Analysis
Magnesium and manganese feedstock markets in Jiangxi and Inner Mongolia feed catalytic-grade enzyme production with pricing volatility tied to export quota announcements. Manufacturing concentrates in China, the United States, and Germany, with Hangzhou contract manufacturers anchoring GMP-grade capacity. Supply chain risk centers on single-source fermentation dependence, as three Hangzhou facilities control majority pharmaceutical-grade output. Distribution runs through vertically integrated life science tools conglomerates for reagent-grade supply, while therapeutic-grade procurement favors direct manufacturer relationships with validated quality systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing expansion is driving a cyclical recovery in pharmaceutical-grade enzyme demand, with FDA accelerated approval pathways compressing procurement cycles and pulling forward capacity investments across GMP-certified fermentation facilities.
For Market Incumbents: Pre-empt Ribonuclease H2 substitution threats by accelerating engineered exonuclease development for next-generation sequencing workflows. Deepen backward integration into magnesium cofactor supply through offtake agreements with Jiangxi rare earth processors. Lock in Boston and San Diego talent pipelines through university partnership programs addressing GMP quality assurance shortages. For New Entrants and Emerging Players: Pursue toll manufacturing partnerships with Hyderabad and Bengaluru CDMOs lacking captive enzyme supply, exploiting white space in India commercial gene therapy manufacturing. Target EMA IVDR conformity assessment services for research-use-only suppliers seeking clinical laboratory access, leveraging notified body relationship gaps. Lead with ISO 13485 certification bundling to compress 14-18 month timeline risks for diagnostic platform launches. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underoptimized enzyme divisions lacking GMP quality system focus. Long-term viability favors specialized enzyme engineering houses with CRISPR-base editing application pipelines over commodity reagent-grade suppliers facing Thermo Fisher consolidation pressure. Watch PMDA-FDA dual-certification completion rates as inflection indicator for Asia-Pacific pharmaceutical-grade supply security.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Quality System Certification | FDA validation protocols enable commercial gene therapy batch release for pharmaceutical procurement. |
| Fermentation Capacity Expansion | Jiangsu and Zhejiang production parks displace extraction-based supply at superior unit economics. |
| Engineered Enzyme Development | Modified processivity variants capture CRISPR-base editing workflow specifications from New England Biolabs. |
| EMA Notified Body Partnership | IVDR Class B and C device conformity assessment opens clinical laboratory access for research-grade suppliers. |
| Digital Twin Bioprocess Implementation | Siemens and Emerson predictive algorithms collapse GMP qualification timelines for therapeutic-grade supply. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation science directors, pharmaceutical procurement managers, diagnostic platform engineers, and regulatory affairs leads, and refined through secondary validation against FDA gene therapy manufacturing guidelines, EMA IVDR technical documentation, NMPA in vitro diagnostic reagent filings, and ISO 13485 certification databases. Bottom-up enzyme demand modeling triangulated against top-down gene therapy pipeline capacity projections.
Demand-supply balance dynamics across the analysis window integrated product type segmentation by catalytic specification, application tier by regulatory threshold, end-user archetype by certification requirement, and technology platform by thermal cycling intensity. CAGRs derived from iterative reconciliation of academic procurement volume trends, pharmaceutical GMP-grade sourcing cycle compression, and diagnostic automation platform deployment rates.
Sensitivities concentrate around Chinese rare earth export quota volatility, Ribonuclease H2 substitution velocity in sequencing workflows, and EMA MDR harmonization timeline execution. Cross-checking against FDA gene therapy manufacturing guideline revision frequency is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Transfection Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Global Automated Cell Cultures Market