
 Dissolving Microneedles Market | 2026-2036
Dissolving Microneedles Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolving Microneedles Market Outlook
A shift from single-source polymer supply to multi-source biocompatible material procurement is repositioning how manufacturers secure hyaluronic acid and polyvinylpyrrolidone feedstocks. CosMED Pharmaceutical Co., Ltd. leverages captive fermentation capacity to stabilize active pharmaceutical ingredient costs. Raphas Co., Ltd. anchors its competitive stance through proprietary dissolving matrix formulations. Micron Biomedical, Inc. specializes in thermostable vaccine-loaded patches for low-resource settings.
Dissolving microneedles are solid projections of water-soluble polymers and active ingredients, typically 25–2000 micrometers in length, that fully dissolve in the skin's interstitial fluid to release payloads without generating sharps waste. Their primary commercial purpose centers on painless, self-administered transdermal delivery of biologics, vaccines, and cosmeceuticals. Biodegradable microneedles command the deepest R&D investment pipelines due to their compatibility with temperature-sensitive biologics. Cosmetic treatments represent the fastest-expanding application segment as dermatology clinics adopt at-home rejuvenation protocols. Transdermal delivery mode dominates volume deployment, though intramuscular configurations are gaining traction in veterinary and pediatric indications.
The FDA's combination product regulations and the EMA's Medical Device Regulation classification criteria jointly determine whether dissolving microneedles face pharmaceutical or device approval pathways, directly influencing development timelines and capital requirements. Health Canada and Japan's PMDA are harmonizing quality standards for polymer purity and needle fracture resistance, tightening market access for non-compliant suppliers. Stakeholders must monitor how regulatory divergence between the FDA and EMA on dissolution-rate testing methodologies reshapes geographic launch sequencing and partnership structures.
Market Dynamics
Polymer supply chain consolidation is forcing manufacturers to renegotiate hyaluronic acid and polyvinylpyrrolidone sourcing contracts as fermentation capacity concentrates among Asian suppliers. This feedstock bottleneck is compressing margins and accelerating backward integration strategies across the competitive landscape.
Growth Catalysts
- FDA combination product pathway clarification:The agency's evolving guidance on transdermal delivery systems is reducing regulatory uncertainty for sponsors pursuing biologics approval through dissolving microneedle platforms.
- Homecare vaccination protocols:Hospital systems are expanding self-administered immunization programs that eliminate cold-chain requirements and sharps disposal infrastructure.
- Thermostable formulation advances:Sugar-glass stabilization technologies are enabling room-temperature distribution of mRNA and protein-based vaccines to low-resource settings.
Market Restraints
- Hyaluronic acid feedstock volatility:Pharmaceutical-grade HA supply concentrates among Chinese and Korean fermentation producers, exposing manufacturers to input cost swings and quota restrictions.
- EMA Medical Device Regulation friction:Classification disputes over whether dissolving microneedles constitute devices or pharmaceuticals are extending approval timelines and duplicating clinical requirements.
- Conventional autoinjector substitution:Established needle-syringe and pen-injector platforms retain reimbursement advantages and physician familiarity in chronic disease management.
Strategic Opportunities
- Pediatric and veterinary intramuscular configurations:Modified needle geometries targeting livestock vaccination and infant immunization are opening addressable markets beyond human dermatology.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting contract development organizations to establish regional fill-finish capacity for export markets.
- Cosmeceutical channel expansion:Dermatology clinics are piloting subscription-based at-home rejuvenation protocols that bypass traditional pharmacy distribution.
Industry Challenges
- Dissolution-rate metrology standardization:Divergent FDA and EMA testing methodologies for polymer degradation kinetics are forcing sponsors to run parallel validation studies.
- Polymer science talent scarcity:Formulation chemists with expertise in both biodegradable matrices and biologic stability are commanding premium compensation and extending hiring cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolving Microneedles Market |
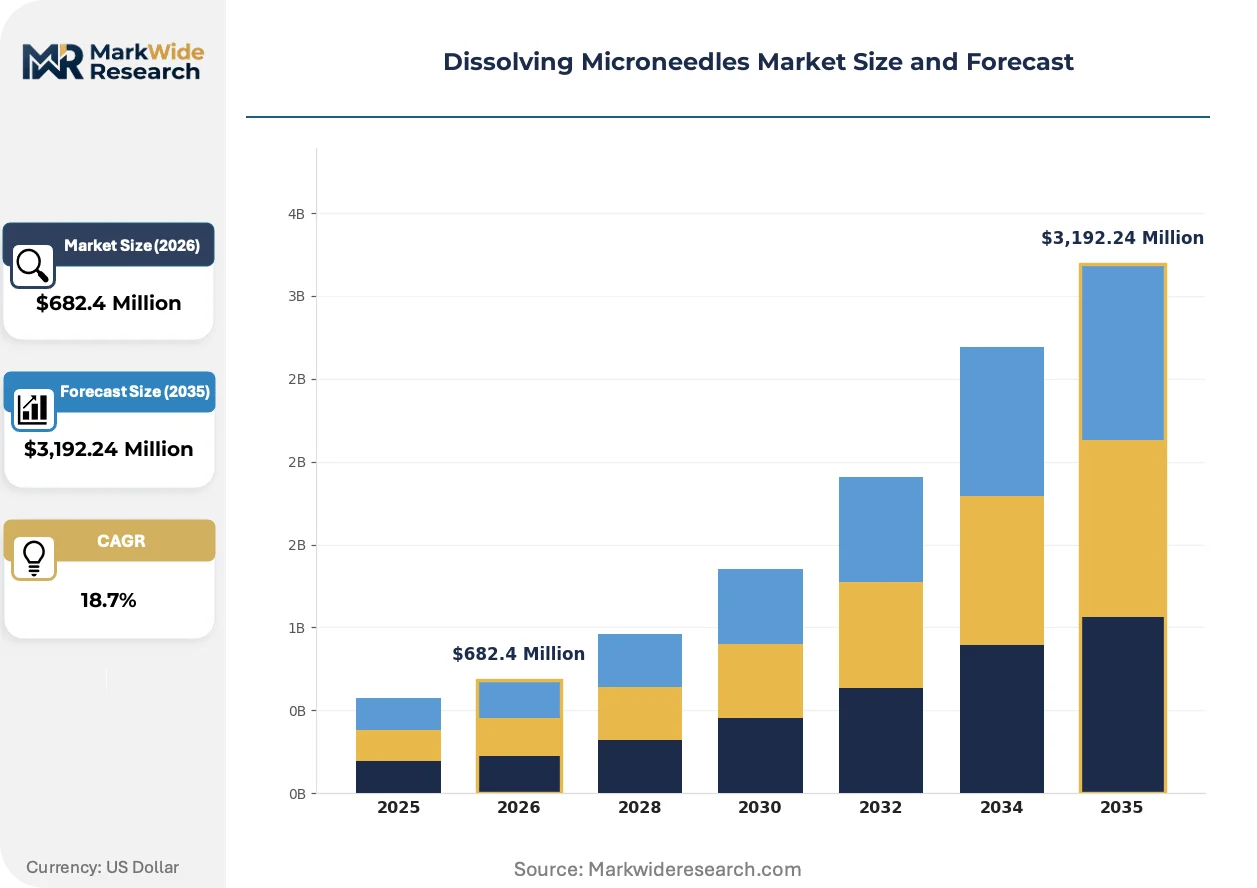
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $3,192.24 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Microneedles, Coated Microneedles, Hollow Microneedles, Biodegradable Microneedles Application: Vaccination, Drug Delivery, Dermal Applications, Cosmetic Treatments End User: Hospitals, Clinics, Homecare Settings, Research Laboratories Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Transdermal |
| Companies Covered | CosMED Pharmaceutical Co., Ltd., Micron Biomedical, Inc., Raphas Co., Ltd., Nissha Co., Ltd., Vaxess Technologies, Inc., 3M, Becton, Dickinson and Company, Micropoint Technologies, QuadMedicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolving Microneedles Market Strategic Shifts
Formulation science is converging with digital manufacturing to enable patient-specific dosing geometries, while regulatory science struggles to keep pace with platform evolution.
Thermostable sugar-glass matrices are overtaking conventional lyophilization for vaccine stabilization in dissolving microneedles. UNICEF and Gavi-affiliated procurement bodies are accelerating qualification of these patches for tropical distribution. This platform shift is compressing the addressable market for refrigerated vial-based supply chains in sub-Saharan Africa and Southeast Asia.
Japan's PMDA and Health Canada are harmonizing polymer purity specifications and needle fracture resistance standards under revised quality guidelines. Manufacturers seeking dual-market approval must now demonstrate compliance with unified extractables and leachables testing protocols. Early movers with pre-submission meetings in both Tokyo and Ottawa are securing priority review designations.
Hospital procurement committees are consolidating supplier lists around vertically integrated partners offering fill-finish, sterilization, and packaging under single quality agreements. Group purchasing organizations are displacing fragmented vendor relationships with multi-year sole-source contracts. This concentration is most visible in United States academic medical centers consolidating annual spend for influenza and COVID-19 booster campaigns.
Dissolving Microneedles Market Segmentation
Segmentation in dissolving microneedles reveals how polymer chemistry, clinical setting, and anatomical target jointly determine commercial viability. Each dimension carries distinct regulatory pathways and manufacturing constraints that shape go-to-market strategy.
Product Type:
Upgrade cycles in dissolving microneedles track polymer innovation timelines, with manufacturers replacing first-generation platforms as biodegradable matrices mature.
- Biodegradable Microneedles:These water-soluble polymer projections fully dissolve in interstitial fluid, eliminating sharps waste while releasing encapsulated biologics. Demand clusters in United States hospital systems piloting self-administered influenza programs where cold-chain elimination justifies premium procurement.
- Solid Microneedles:Non-dissolving metal or silicon arrays pierce stratum corneum for sustained-release reservoirs. United States dermatology clinics favor these for at-home cosmetic protocols where patient compliance hinges on visible, reusable applicators.
- Coated Microneedles:Drug-coated metal shafts dissolve surface films without full matrix degradation.
- Hollow Microneedles:Microfluidic channels enable bolus injection through dissolvable sleeves.
Volume placements concentrate in biodegradable formats; the faster expansion belongs to solid configurations.
Application:
Cost tiering separates emergency stockpiling from elective consumption, with institutional buyers prioritizing vaccine platforms over cosmetic offerings.
- Vaccination:Thermostable sugar-glass matrices stabilize mRNA and protein antigens for room-temperature distribution. UNICEF procurement in sub-Saharan Africa and Gavi-affiliated programs in Southeast Asia are qualifying these patches for tropical deployment.
- Cosmetic Treatments:Hyaluronic acid and peptide-loaded arrays target dermal rejuvenation without clinic visits. United States dermatology practices are piloting subscription-based home delivery that bypasses pharmacy distribution entirely.
- Drug Delivery:Biologic-loaded polymers achieve sustained release for chronic conditions.
- Dermal Applications:Localized dermatologic treatments address psoriasis and eczema patches.
Institutional procurement concentrates in vaccination; cosmetic treatments are climbing the fastest.
End User:
Customer type determines packaging complexity, with homecare settings demanding single-unit sterile pouches that multiply per-dose costs.
- Homecare Settings:Self-administered platforms require intuitive applicators and pictographic instructions. United States health systems expanding post-discharge immunization programs are driving FDA combination product submissions for influenza and COVID-19 boosters.
- Research Laboratories:Custom geometries and small-batch formulations support preclinical validation. Academic medical centers in Boston and San Francisco are consolidating supplier lists around partners offering fill-finish, sterilization, and packaging under unified quality agreements.
- Hospitals:Inpatient administration of acute therapies through staff-applied platforms.
- Clinics:Outpatient procedures with supervised patient application.
Procurement volume clusters in homecare settings; research laboratories show the steepest expansion trajectory.
Delivery Mode:
Anatomical targeting dictates needle geometry and dissolution kinetics, with transdermal platforms commanding the broadest addressable population.
- Transdermal:Arrays penetrate 150-1000 micrometers into viable epidermis for systemic absorption. United States, Japanese, and German regulators are harmonizing dissolution-rate testing protocols under revised quality guidelines.
- Intramuscular:Modified geometries achieve deeper penetration for livestock vaccination and infant immunization where conventional needle phobia compromises coverage.
- Subcutaneous:Intermediate-depth targeting for insulin and hormone delivery.
- Intravenous:Dissolvable sleeves for vascular access remain preclinical.
Deployment concentrates in transdermal delivery; intramuscular configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for pharmaceutical-grade hyaluronic acid concentrates in South Korea and China, creating feedstock dependencies that reshape geographic procurement strategies for dissolving microneedle manufacturers worldwide.
United States
Hospital systems in Boston and San Francisco are consolidating supplier lists around partners offering unified fill-finish and sterilization services. FDA combination product pathway clarification is reducing regulatory uncertainty for sponsors pursuing biologics approval through microneedle platforms. Academic medical centers in these clusters are driving clinical translation of self-administered influenza and COVID-19 booster programs.
South Korea
Captive fermentation capacity for hyaluronic acid feedstocks stabilizes active pharmaceutical ingredient costs for domestic manufacturers. The MFDS is harmonizing polymer purity specifications with Health Canada under revised quality guidelines. Seoul-based suppliers are securing priority review designations through pre-submission meetings in Tokyo and Ottawa.
Japan
PMDA quality guidelines for needle fracture resistance are tightening market access for non-compliant foreign suppliers. METI is coordinating with Health Canada on unified extractables and leachables testing protocols. Osaka pharmaceutical clusters are anchoring regional demand for thermostable vaccine-loaded patches targeting tropical distribution.
Germany
EMA Medical Device Regulation classification disputes are extending approval timelines for sponsors pursuing pharmaceutical versus device pathways. REACH compliance for polymer feedstocks is reshaping sourcing contracts with Asian fermentation producers. Bavarian dermatology clinics are piloting subscription-based at-home rejuvenation protocols that bypass traditional pharmacy distribution.
India
PLI scheme incentives for medical devices are attracting contract development organizations to establish regional fill-finish capacity for export markets. CDSCO is streamlining quality standards alignment with WHO prequalification requirements. Gujarat and Maharashtra manufacturing corridors are concentrating backward integration strategies for polyvinylpyrrolidone procurement.
Dissolving Microneedles Market Competitive Environment
Backward integration into fermentation capacity dominates the current landscape as manufacturers renegotiate hyaluronic acid and polyvinylpyrrolidone sourcing contracts. The vendor base fragments between vertically integrated polymer producers and specialized formulation houses dependent on external feedstock. Three archetypes occupy distinct positions: captive fermentation operators securing input cost stability, proprietary matrix formulators differentiating through dissolution kinetics, and thermostable patch specialists targeting low-resource distribution. Capacity expansion and strategic partnerships represent the dominant competitive moves, with sponsors securing multi-year sole-source contracts through group purchasing organizations.
Within the captive fermentation tier, CosMED Pharmaceutical Co., Ltd. exemplifies upstream control strategies that stabilize active pharmaceutical ingredient exposure. Raphas Co., Ltd. occupies a position among proprietary matrix formulators leveraging dissolving polymer expertise. Micron Biomedical, Inc. represents the thermostable specialization vector targeting UNICEF and Gavi-affiliated procurement programs. These three anchors illustrate how feedstock security, formulation differentiation, and distribution channel selection collectively determine competitive positioning in this market.
| Leading Market Players |
|---|
| CosMED Pharmaceutical Co., Ltd. |
| Micron Biomedical, Inc. |
| Raphas Co., Ltd. |
| Nissha Co., Ltd. |
| Vaxess Technologies, Inc. |
| 3M |
| Becton, Dickinson and Company |
| Micropoint Technologies |
| QuadMedicine |
| Others |
Value Chain & Pricing Dynamics
Group purchasing organizations at United States academic medical centers command pricing leverage through multi-year sole-source contracts that compress margins for non-integrated suppliers. These procurement committees reward partners offering unified fill-finish, sterilization, and packaging under single quality agreements, creating a contract-based pricing structure that favors vertically integrated manufacturers over fragmented vendors.
Pricing Analysis
Service bundling separates sterilization-validated supply agreements from unbundled component sales, with the former commanding substantial premiums. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and polymer purity specifications, with pharmaceutical-grade hyaluronic acid arrays priced distinctly from cosmetic-grade formulations. Cost compression in standard tiers is intensifying because fermentation capacity concentrates among Korean and Chinese suppliers. Research laboratories exhibit the highest price sensitivity due to small-batch procurement volumes, while UNICEF-affiliated programs demonstrate lowest sensitivity given total-cost-of-ownership advantages from cold-chain elimination.
Supply Chain Analysis
Single-source vulnerability sits with pharmaceutical-grade hyaluronic acid fermentation capacity concentrated in South Korea and China, exposing manufacturers to quota restrictions and input cost swings. Polyvinylpyrrolidone feedstocks draw from similar Asian fermentation hubs, while sugar-glass stabilizers for thermostable formulations rest on specialized carbohydrate suppliers. Tariff exposure on imported polymers from China threatens margin structures for United States and European formulators lacking captive production. Distribution runs through hospital procurement committees and group purchasing organizations that consolidate annual spend around vertically integrated partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity for pharmaceutical-grade hyaluronic acid operates at effective utilization limits, propping input costs and rewarding manufacturers with captive supply or long-term offtake agreements. This supply-constrained structure favors incumbents with backward integration and creates barriers for entrants dependent on spot market procurement.
For Market Incumbents: Lock in multi-year sole-source contracts with group purchasing organizations before India's PLI scheme matures additional regional capacity. Secure captive fermentation assets or joint ventures with Korean suppliers to defend against polymer price volatility. Prioritize FDA combination product pathway investments that extend regulatory moats against emerging solid microneedle substitutes. For New Entrants and Emerging Players: Launch via cosmeceutical subscription channels that bypass pharmacy distribution and hospital procurement committees entirely. Target India's domestic manufacturing incentives to establish regional fill-finish capacity for export markets. Veterinary intramuscular configurations for livestock vaccination represent the most penetrable white space given limited incumbent focus outside human dermatology. For Investors and Strategic Acquirers: The window for entry favors proprietary matrix formulators with demonstrated dissolution kinetics expertise over commodity polymer converters. Thermostable patch specialists targeting UNICEF and Gavi procurement programs offer the strongest long-term viability given tropical distribution tailwinds. Watch for FDA-EMA harmonization on dissolution-rate testing methodologies as the signal for accelerated geographic consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive hyaluronic acid production insulates CosMED Pharmaceutical from Korean supplier quota volatility. |
| FDA Combination Product Submission | Clarified regulatory pathway accelerates Micron Biomedical's thermostable influenza patch approval timeline. |
| UNICEF Prequalification Pursuit | Gavi-affiliated procurement access opens sub-Saharan African distribution for sugar-glass vaccine platforms. |
| India PLI Scheme Utilization | Domestic manufacturing incentives attract contract development organizations to Gujarat fill-finish corridors. |
| EMA-PMDA Harmonization Alignment | Unified extractables testing protocols secure priority review for Seoul suppliers in Tokyo and Ottawa. |
Study Parameters
Independent corroboration across formulation scientists at Raphas and Micron Biomedical, procurement directors at United States academic medical centers, and regulatory affairs leads with FDA combination product experience underwrites the qualitative findings. Secondary validation draws from FDA 510(k) and BLA filings, EMA Medical Device Regulation classification guidance, MFDS quality guideline revisions, and UNICEF vaccine prequalification databases. Bottom-up polymer demand modeling and top-down vaccination program spend analysis triangulate volume estimates.
Comparable-period anchoring to historical influenza patch pilot programs and COVID-19 booster campaign procurement data establishes baseline adoption curves across the projection horizon. Segmentation dimensions include polymer chemistry class, clinical setting tier, anatomical delivery mode, and regional regulatory cluster complexity. CAGRs derive from fitted adoption curves applied to institutional procurement cycle timelines and cosmeceutical channel expansion rates. Thermostable formulation qualification status and Gavi procurement pipeline positioning serve as industry-specific forecast inputs.
Polymer feedstock supply disruptions, EMA-FDA regulatory divergence on dissolution testing, and conventional autoinjector reimbursement retention are the dominant revision risks. Forecasts reflect assumptions on fermentation capacity expansion rates and hospital self-administration program adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market