
 Global Artificial Intelligence (AI) Hardware Market | 2026-2036
Global Artificial Intelligence (AI) Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) Hardware Market Foresight
The capital-intensity divergence between foundry-dependent designers and vertically integrated fabricators is collapsing as advanced node costs exceed $20,000 per wafer. NVIDIA sustains leadership through CUDA ecosystem lock-in and full-stack optimization from silicon to software. TSMC anchors global supply with its CoWoS packaging monopoly for AI accelerators. AMD competes aggressively on price-performance in data center GPUs while expanding its MI300 series footprint.
Global Artificial Intelligence (AI) Hardware encompasses specialized semiconductor devices and systems architected to execute machine learning workloads with high throughput and energy efficiency, typically fabricated on sub-5nm process nodes with high-bandwidth memory integration and advanced interposer-based packaging. These systems serve primarily to train large neural networks and run inference at scale for commercial AI services. Graphics Processing Units dominate current revenue due to their programmability and mature software stacks, while Application-Specific Integrated Circuits command premium margins in hyperscaler deployments where workload specificity justifies custom silicon investment. Edge Computing represents the fastest-expanding technology segment as latency-sensitive applications migrate inference from centralized clouds to distributed endpoints.
The US CHIPS and Science Act and the EU Chips Act are redirecting subsidy flows toward domestic AI semiconductor fabrication, altering where capital equipment deploys and which facilities qualify for preferential treatment. China's SAMR enforces data localization and export control compliance that shapes chip architecture decisions for vendors serving that market. ISO/IEC 42001 establishes AI management system standards that hardware suppliers must address in enterprise procurement cycles. Stakeholders must monitor how divergent national semiconductor strategies reshape cost structures and supply chain reliability across their AI infrastructure investments.
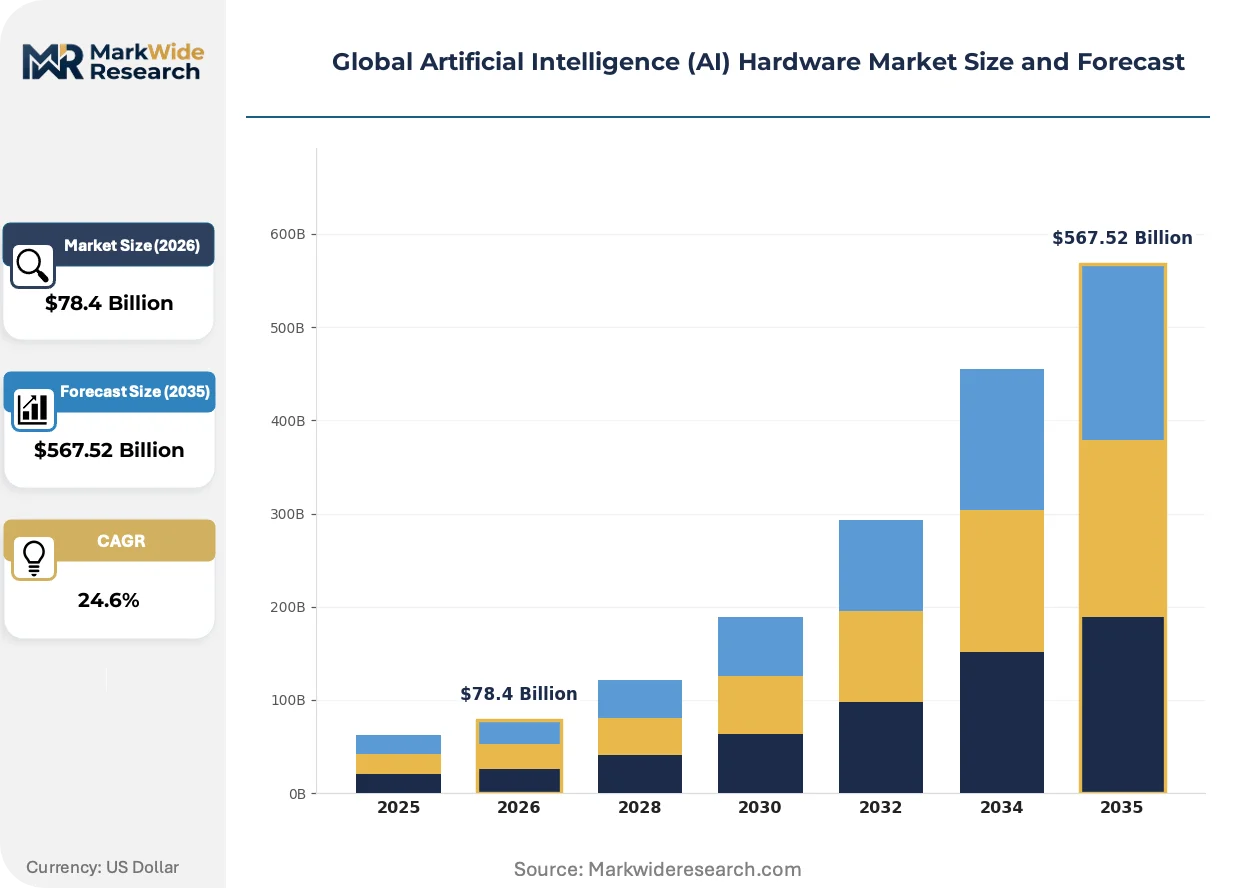
Market Dynamics
CoWoS packaging capacity constraints at TSMC are creating allocation bottlenecks that force AI accelerator designers to redesign around interposer availability, fundamentally restructuring how silicon, memory, and substrate vendors coordinate roadmaps.
Growth Catalysts
- EU AI Act conformity mandates:Hardware certification requirements for high-risk systems are accelerating demand for traceable, auditable accelerator architectures in European enterprise deployments.
- Generative inference workload expansion:Cloud service providers are scaling procurement of dedicated inference silicon to serve latency-sensitive large language model applications.
- Taiwan foundry concentration:TSMC's advanced packaging dominance and leading-edge node availability are pulling design activity and capital toward Taiwanese manufacturing clusters.
Market Restraints
- Advanced node cost escalation:Sub-5nm wafer costs exceeding twenty thousand dollars per unit are compressing design economics for all but the largest volume players.
- High-bandwidth memory supply concentration:Three vendors control HBM3E supply, creating single-source vulnerability for AI accelerator production ramps.
- Export control fragmentation:Divergent US BIS and China SAMR compliance regimes are forcing architecture bifurcation that inflates R&D overhead.
Strategic Opportunities
- Edge inference localization:India's PLI scheme for electronics manufacturing is attracting chip design houses to develop low-power accelerators for domestic smart city and industrial automation deployments.
- Photonic interconnect convergence:Co-packaged optics with silicon photonics are opening bandwidth scaling paths beyond electrical retimer limits for next-generation training clusters.
- US CHIPS Act fabrication incentives:Subsidy-qualified domestic foundry capacity in Arizona and Texas is enabling captive supply strategies for national security-sensitive AI workloads.
Industry Challenges
- 3D packaging thermal engineering:Chiplet stacking complexity is outpacing available simulation talent, extending validation cycles for multi-die accelerators.
- ISO/IEC 42001 certification timelines:Hardware suppliers face six-to-twelve-month audit queues to satisfy enterprise procurement mandates for AI management system compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) Hardware Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $567.52 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Processing Units, Tensor Processing Units, Field Programmable Gate Arrays, Application-Specific Integrated Circuits, Digital Signal Processors Technology: Edge Computing, Neuromorphic Computing, Optical Processing, Quantum Computing, FPGA Acceleration Application: Natural Language Processing, Autonomous Vehicles, Fraud Detection, Predictive Maintenance, Facial Recognition End User: Research Laboratories, Cloud Service Providers, Telecommunication Firms, Government Agencies, Financial Institutions |
| Companies Covered | Google, Qualcomm, NVIDIA, TSMC, Broadcom, AMD, Amazon, Cerebras Systems, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) Hardware Market Shifts & Advancements
Silicon photonics, chiplets, and in-memory computing are converging to redefine performance-per-watt trajectories, with packaging innovation now outpacing transistor scaling as the primary vector for accelerator differentiation.
Co-packaged photonic interconnects are replacing electrical SerDes for rack-scale AI clusters, with hyperscalers adopting the technology to cut interconnect power draw by half. The shift is compressing optical component supply chains and forcing collaboration between foundries and photonics specialists. Advanced packaging is miniaturizing transceiver footprints to enable direct optical attachment to accelerator dies.
China's SAMR data localization enforcement is mandating onshore processing for sensitive AI inference, compelling foreign hardware vendors to architect China-specific silicon variants with partitioned security enclaves. Domestic cloud operators are accelerating qualification of locally fabricated accelerators. This regulatory divergence is fragmenting previously unified product roadmaps into jurisdiction-specific branches.
Hyperscaler procurement teams are unbundling hardware acquisition from managed service contracts, shifting toward direct silicon sourcing with self-operated software stacks. This disintermediation is compressing traditional OEM margins and forcing component vendors to build direct field engineering capabilities. The pattern is most pronounced in North American cloud regions where vertical integration appetite is strongest.
Global Artificial Intelligence (AI) Hardware Market Segmentation
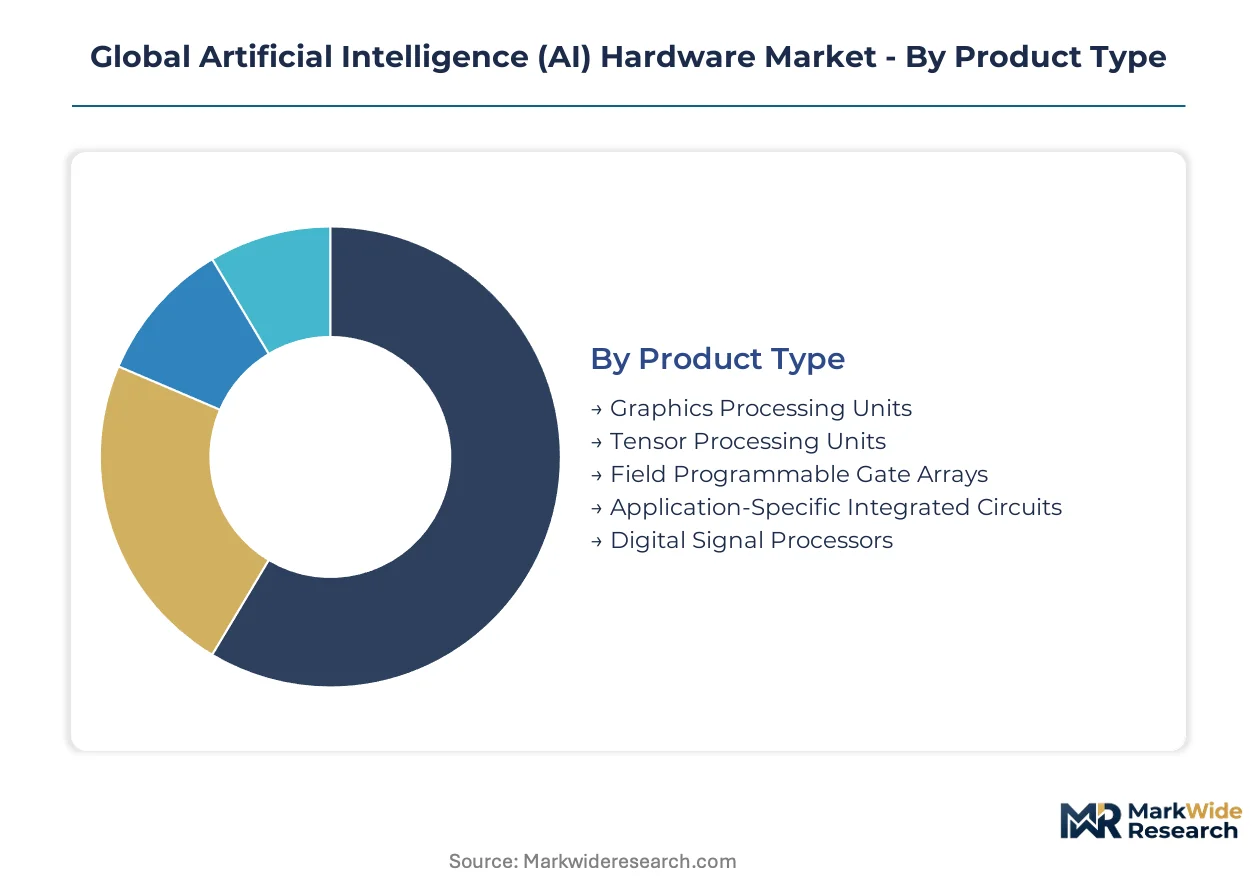
AI hardware segmentation reveals divergent commercial logics across compute paradigms. Product architecture choices lock vendors into distinct margin structures and customer relationships. Application specificity determines whether volume economics or premium customization wins.
Product Type:
Domestic procurement dominates for government-qualified accelerators, while export flows concentrate in programmable devices serving multinational cloud operators.
- Graphics Processing Units:Parallel processing architectures with mature CUDA and ROCm software ecosystems. Cloud service providers in the United States and Taiwan account for the majority of procurement, driven by generative model training clusters. NVIDIA's ecosystem lock-in sustains premium pricing despite AMD price-performance competition.
- Tensor Processing Units:Google-designed matrix multiply engines optimized for TensorFlow workloads. Demand concentrates at Google's internal cloud infrastructure and select enterprise licensees, constrained by narrow framework compatibility outside Alphabet's stack.
- Field Programmable Gate Arrays:Reconfigurable logic fabrics enabling workload-specific optimization. Financial institutions in London and Singapore deploy these for low-latency trading algorithms.
- Application-Specific Integrated Circuits:Custom silicon designs for fixed neural network architectures. Hyperscalers in Seattle and Shenzhen commission these for inference at scale.
- Digital Signal Processors:Specialized arithmetic units for streaming data preprocessing. Telecommunication firms integrate these into 5G baseband processing.
Graphics Processing Units hold the largest share; momentum sits with Application-Specific Integrated Circuits.
Technology:
Cost tier separation runs from commodity edge nodes to billion-dollar quantum systems, with neuromorphic architectures occupying an uncertain middle ground.
- Edge Computing:Distributed inference nodes with sub-10W power envelopes and on-chip memory integration. Smart city deployments in India and industrial automation in Germany are pulling design activity toward low-latency, offline-capable accelerators.
- Neuromorphic Computing:Spiking neural network chips mimicking biological synaptic efficiency. Intel's Loihi and IBM's TrueNorth anchor research laboratory procurement.
- Optical Processing:Photonic matrix multipliers using interferometric meshes for analog compute. Lightmatter and Luminous Computing serve niche hyperscaler evaluation contracts.
- Quantum Computing:Superconducting and trapped-ion qubit systems for optimization and simulation workloads. IBM and Google dominate research laboratory installations.
- FPGA Acceleration:Vendor-neutral reconfigurable computing layer above fixed-function silicon. Telecommunication firms adopt these for 5G signal processing flexibility.
Edge Computing commands the highest volume; Quantum Computing captures the steepest expansion trajectory in absolute investment terms.
Application:
Customer type fragmentation separates defense-cleared vendors from commercial suppliers, with dual-use applications facing the most complex certification requirements.
- Natural Language Processing:Transformer-optimized accelerators handling trillion-parameter model inference. Cloud service providers deploy these across Frankfurt, Singapore, and Virginia data centers.
- Autonomous Vehicles:Safety-certified edge compute meeting ISO 26262 functional safety standards. German automotive OEMs and California robotaxi operators drive qualification timelines.
- Fraud Detection:Real-time transaction scoring on encrypted financial data. Swiss and Singaporean banks mandate on-premise deployment.
- Predictive Maintenance:Vibration and thermal sensor fusion for industrial equipment. German and Japanese manufacturers integrate these into Industry 4.0 deployments.
- Facial Recognition:Specialized convolution accelerators with liveness detection. Government agencies in the Middle East and Southeast Asia dominate procurement.
Natural Language Processing absorbs the most silicon area; Autonomous Vehicles face the longest validation cycles.
End User:
Volume concentration tilts toward cloud service providers, while margin capture favors research laboratories with patient capital and bespoke requirements.
- Research Laboratories:Academic and national laboratory procurement emphasizing peak performance over efficiency. CERN, Argonne, and RIKEN operate petascale AI training clusters.
- Cloud Service Providers:Hyperscalers optimizing total cost of ownership across millions of inference queries. AWS, Azure, and Google Cloud drive foundry roadmaps.
- Telecommunication Firms:Edge infrastructure operators deploying AI at cell towers and central offices. Jio in India and Deutsche Telekom in Germany lead regional buildouts.
- Government Agencies:Defense and intelligence customers requiring supply chain provenance and export-controlled architectures. The Pentagon's JAIC and China's military-civil fusion programs shape dual-use markets.
- Financial Institutions:Banks and hedge funds deploying AI for risk modeling and algorithmic execution. Goldman Sachs and HSBC operate proprietary inference infrastructure.
Cloud Service Providers hold the largest share; Government Agencies are gaining share fastest through classified workload expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Cloud hyperscalers in the United States deploy training clusters at scale, while European enterprises prioritize inference localization under regulatory pressure. Asian manufacturing hubs concentrate advanced packaging capacity that shapes global accelerator availability.
United States
Hyperscaler procurement drives demand for high-throughput training accelerators, with cloud service providers operating multi-billion-dollar infrastructure deployments. The CHIPS and Science Act directs subsidy flows toward domestic foundry construction in Arizona and Texas. Intel's fabrication expansion in Chandler anchors national security-sensitive AI workload capacity.
China
Domestic cloud operators accelerate qualification of locally fabricated accelerators as SAMR enforces data localization for sensitive inference workloads. Export control compliance regimes force architecture bifurcation that inflates R&D overhead for foreign vendors. Shanghai and Shenzhen manufacturing clusters concentrate design activity for partitioned security enclave variants.
Germany
Automotive OEMs drive demand for safety-certified edge compute meeting ISO 26262 functional safety standards for autonomous vehicle platforms. The EU AI Act mandates conformity assessments for high-risk systems that reshape hardware certification requirements. Stuttgart and Munich industrial clusters anchor Industry 4.0 predictive maintenance accelerator integration.
Japan
Telecommunication firms deploy AI at cell towers and central offices for 5G baseband processing with stringent latency requirements. METI coordinates national semiconductor strategy to secure supply chain resilience for critical AI infrastructure. The Kyushu region concentrates advanced packaging research with TSMC's Kumamoto facility expansion.
India
Smart city and industrial automation deployments pull design activity toward low-power edge accelerators with sub-10W power envelopes. The PLI scheme for electronics manufacturing attracts chip design houses to develop domestic inference solutions. Bengaluru and Hyderabad technology clusters concentrate fabless design talent for localized accelerator development.
Global Artificial Intelligence (AI) Hardware Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across architectural approaches. The upper tier commands ecosystem lock-in through full-stack optimization from silicon to software, while specialists compete on workload-specific customization. Two strategic archetypes dominate: vertically integrated fabricators controlling advanced node production, and fabless designers leveraging foundry partnerships for rapid scaling. Competitive moves center on capacity reservation agreements for CoWoS packaging and strategic partnerships to secure high-bandwidth memory allocation.
Within the integrated fabrication tier, TSMC anchors global supply through advanced packaging dominance, while NVIDIA exemplifies ecosystem-led market position through CUDA software lock-in. Among fabless competitors, AMD occupies a price-performance positioning in data center GPU deployment. These three companies represent the structural concentration that shapes accelerator availability and pricing dynamics across cloud service provider procurement cycles.
| Leading Market Players |
|---|
| Qualcomm |
| NVIDIA |
| TSMC |
| Broadcom |
| AMD |
| Amazon |
| Cerebras Systems |
| Intel |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with CoWoS packaging providers lock in both supply access and price visibility for AI accelerator designers, creating a bifurcated market where volume commitments determine allocation priority at TSMC's Taiwanese facilities.
Pricing Analysis
Long-term offtake contracts dominate procurement between hyperscalers and foundry partners, with pricing stratifying across premium, standard, and economy tiers based on HBM3E memory configuration and interposer complexity. NVIDIA's CUDA ecosystem sustains premium positioning against AMD's aggressive price-performance positioning in data center deployments. Cost compression in mid-tier inference accelerators is intensifying because cloud service providers are unbundling hardware from managed service contracts. Government agencies exhibit lowest price sensitivity due to national security qualification requirements, while Indian smart city deployments show highest sensitivity to unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites critical rare earth and specialty chemical flows for advanced semiconductor manufacturing, creating logistical vulnerability that shapes inventory strategies across the ecosystem. Taiwan, South Korea, and the United States concentrate leading-edge fabrication and advanced packaging capacity. HBM3E memory, CoWoS interposers, and EUV photoresist chemicals constitute critical input dependencies. Single-source vulnerability runs through TSMC's packaging monopoly, with any disruption propagating across NVIDIA, AMD, and Google accelerator roadmaps. Distribution feeds from foundry direct sales to cloud service provider procurement teams, bypassing traditional OEM channels in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity mandate represents a regulatory inflection that will reshape hardware certification requirements, accelerating demand for traceable accelerator architectures across European enterprise deployments.
For Market Incumbents: Compound ecosystem lock-in through CUDA and ROCm software stack deepening while securing multi-year CoWoS capacity reservations at TSMC's Arizona and Taiwanese facilities. Threat from custom silicon initiatives at Amazon and Google demands defensive R&D expansion into chiplet-based inference accelerators. Certification investment for EU AI Act compliance is essential for maintaining European cloud service provider relationships. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized electronics manufacturing corridor for low-power edge accelerator development targeting smart city and industrial automation procurement cycles. The most penetrable segment sits in sub-10W inference devices for telecom edge infrastructure, where incumbent software ecosystems hold weaker lock-in. Direct field engineering partnerships with Jio and Deutsche Telekom offer viable go-to-market pathways. For Investors and Strategic Acquirers: Photonic interconnect specialists with co-packaged optics capabilities represent the highest-conviction acquisition archetype for next-generation training cluster bandwidth scaling. Long-term viability hinges on whether silicon photonics can displace electrical SerDes for rack-scale AI infrastructure. Watch hyperscaler evaluation contract announcements from Lightmatter and Luminous Computing as inflection indicators for technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Reservation | TSMC allocation priority determines accelerator production ramps for cloud service providers. |
| HBM3E Supply Agreement | SK Hynix and Samsung long-term contracts secure memory for multi-die training chips. |
| EU AI Act Certification | Conformity assessment investment unlocks European enterprise and government procurement. |
| Silicon Photonics Partnership | Co-packaged optics collaboration cuts interconnect power for next-generation clusters. |
| India PLI Manufacturing Entry | Domestic production qualification attracts smart city and industrial automation demand. |
Research Methodology
A standing panel of semiconductor fabrication executives, cloud infrastructure procurement leads, AI accelerator platform engineers, and foundry capacity planners provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings, hyperscaler capital expenditure disclosures, TSMC investor presentations, and EU regulatory filings. Bottom-up unit economics modeling triangulated against top-down market sizing from trade flow analysis and foundry utilization data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, technology paradigm, application workload, and end-user procurement archetype. CAGRs derived from fitted growth curves incorporating foundry capacity expansion schedules, memory supply constraints, and regulatory compliance timeline impacts. Forecast inputs included CoWoS packaging capacity ramps, HBM3E yield improvements, and export control regime evolution.
Material uncertainties — foundry yield volatility, geopolitical trade restriction expansion, and alternative compute paradigm breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained hyperscaler infrastructure investment and incremental packaging technology scaling. Revision becomes warranted when TSMC advanced packaging utilization crosses thresholds indicating sustained supply-demand imbalance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Chatbot Market