
 AI in Retail Market | 2026-2036
AI in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Retail Market Analysis
The EU AI Act is restructuring the cost-of-entry calculus for retail AI vendors serving European retail chains. Microsoft leverages its Azure cloud infrastructure to sustain enterprise-grade deployment pipelines for inventory management and demand forecasting. Amazon anchors its competitive stance through in-house production of custom silicon and fulfillment-optimized computer vision systems.
Artificial intelligence in retail encompasses machine learning models, natural language processing engines, and computer vision systems that process transactional, behavioral, and visual data to automate merchandising decisions, optimize logistics networks, and personalize consumer interactions at scale. Recommendation engines and customer analytics capture disproportionate margin pools because they directly influence conversion rates and basket size across e-commerce platforms and retail chains. Machine learning and predictive analytics dominate technology adoption, while supply chain optimization and personalization applications attract the largest implementation budgets from enterprise buyers.
The EU AI Act, GDPR, and FDA guidelines for AI-enabled health-adjacent retail products collectively shape product standards, data governance requirements, and market access conditions across multiple jurisdictions. China's SAMR enforces algorithmic transparency rules for recommendation engines operating on domestic e-commerce platforms, adding a second compliance layer for multinational vendors. Stakeholders must monitor divergence between risk-tiered regulatory frameworks in Europe and outcome-based enforcement patterns in Asia-Pacific to align R&D roadmaps with emerging compliance boundaries.
Market Dynamics
Computer vision deployment at grocery checkout lanes is compressing labor cost structures while triggering EU AI Act compliance investments that reshape vendor economics across European retail chains.
Growth Catalysts
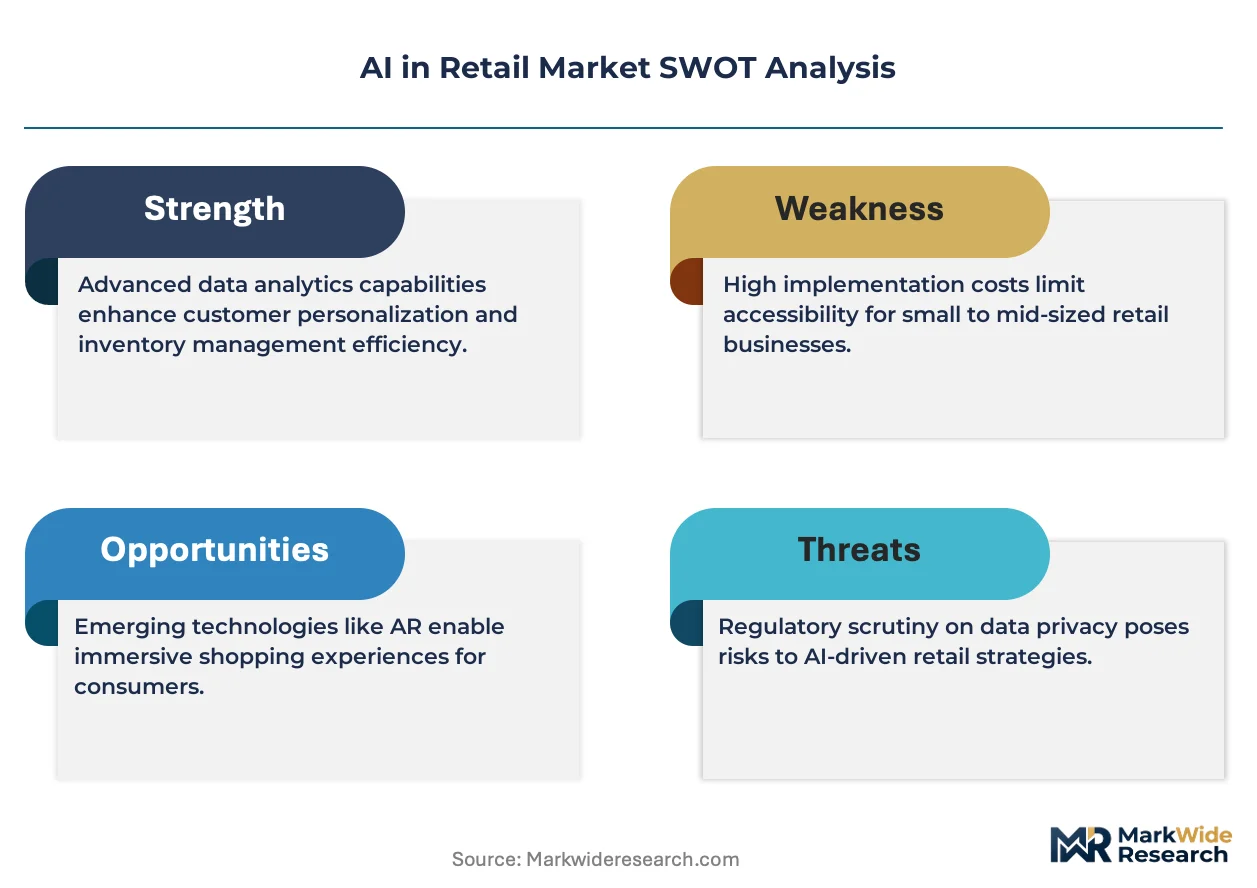
- EU AI Act risk-tiered obligations:High-stakes retail algorithms face mandatory conformity assessments, creating sustained demand for governance tooling and audit services among European grocery and fashion chains.
- Edge AI hardware maturation:On-device inference chips enable real-time inventory tracking and loss prevention without cloud latency, accelerating adoption in big-box formats with thin network infrastructure.
- China SAMR algorithmic transparency mandates:Domestic e-commerce platforms must disclose recommendation engine parameters, forcing multinational retailers to rebuild personalization stacks for compliance.
Market Restraints
- GPU supply concentration:Training infrastructure for large retail models depends on a narrow supplier base concentrated in Taiwan and South Korea, creating procurement bottlenecks.
- GDPR data localization friction:Cross-border customer analytics pipelines require territorial data residency, fragmenting model training datasets and raising infrastructure costs.
- Legacy POS integration complexity:Decades-old transaction systems in established retail chains resist API-native AI overlays, extending deployment timelines.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Incentive structures for semiconductor and hardware assembly attract retail AI device production away from traditional East Asian hubs.
- Generative AI convergence with computer vision:Multimodal models that synthesize product imagery and natural language descriptions enable automated catalog generation for marketplace vendors.
- Pharmacy retail AI:FDA guidelines for AI-enabled diagnostic and wellness products create a regulated channel for health-adjacent retail applications with premium pricing headroom.
Industry Challenges
- ML operations talent scarcity:Production-grade model monitoring and drift detection require specialized engineering functions that outstrip supply in mid-market retail organizations.
- ISO 42001 AI management system certification:Emerging standards for responsible AI governance impose documentation burdens that extend vendor onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Retail Market |
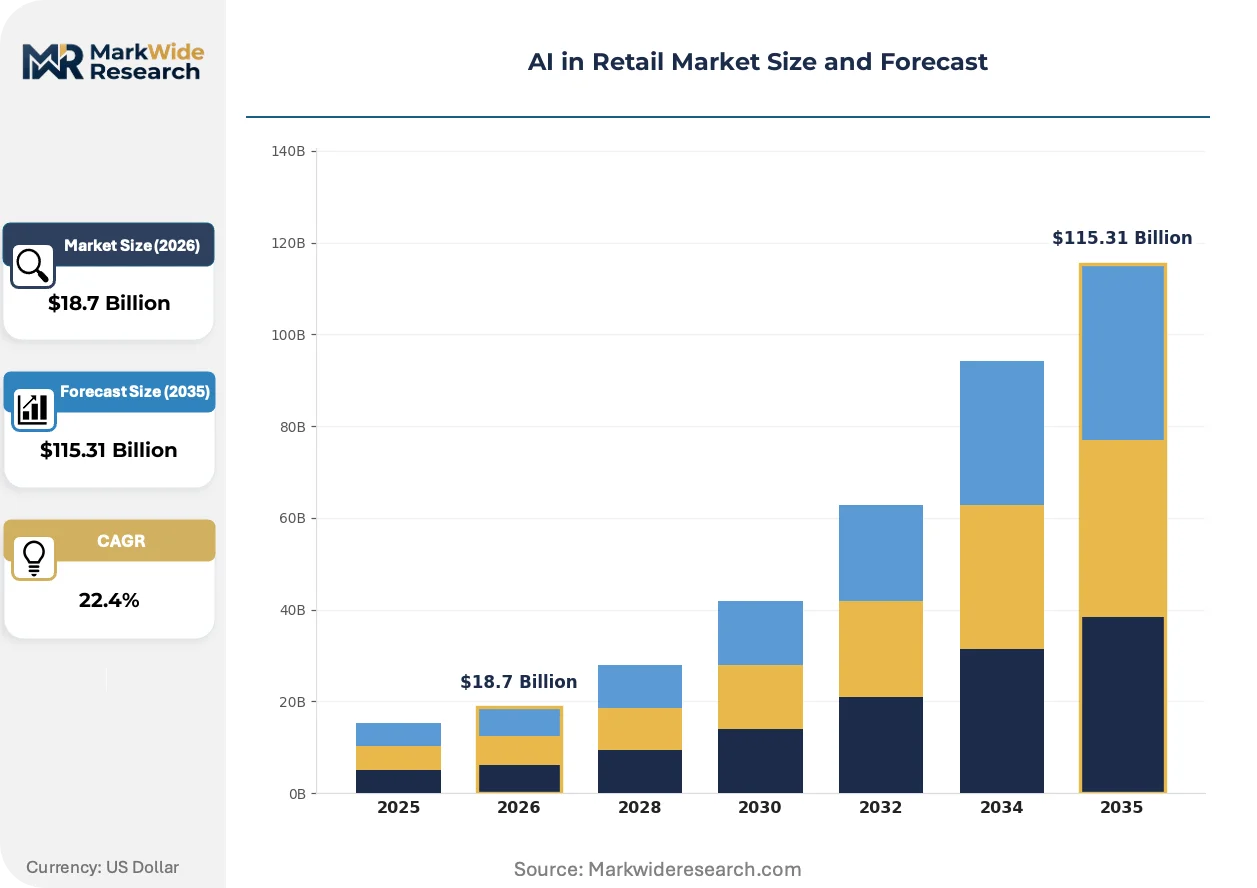
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Inventory Management, Recommendation Engines, Customer Analytics End User: E-commerce Platforms, Brick-and-Mortar Stores, Wholesalers, Retail Chains Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics Application: Personalization, Supply Chain Optimization, Fraud Detection, Demand Forecasting |
| Companies Covered | Microsoft, Amazon, Google, IBM, Oracle, Salesforce, SAP, NVIDIA, Alibaba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Retail Market Emerging Trajectories
Foundation models trained on retail-specific multimodal data are compressing the traditional machine learning deployment pipeline from months to weeks, forcing incumbent vendors to reposition around orchestration rather than model development.
Vision-language models that parse shelf imagery and generate restock alerts are electrifying inventory management workflows. Mass merchandisers with extensive store networks are deploying these systems across thousands of locations simultaneously. The technology is electrifying competitive dynamics by collapsing the cost advantage of centralized distribution centers against store-level fulfillment.
The EU AI Act's high-risk system designation for biometric identification in retail environments is forcing European chains to maintain dual technology stacks. Systems deployed in France and Germany require human-in-the-loop overrides that add latency compared to US implementations. Grocery self-checkout lanes in the Netherlands and Belgium are removing facial recognition capabilities entirely to avoid conformity assessment costs.
Enterprise buyers are unbundling AI procurement from legacy ERP contracts, creating direct relationships with specialized vendors. Retailers with mature data science functions are licensing foundation models and fine-tuning internally rather than purchasing end-to-end solutions. This pattern is most visible among US-based department store chains with dedicated innovation labs in Austin and Seattle.
AI in Retail Market Segmentation
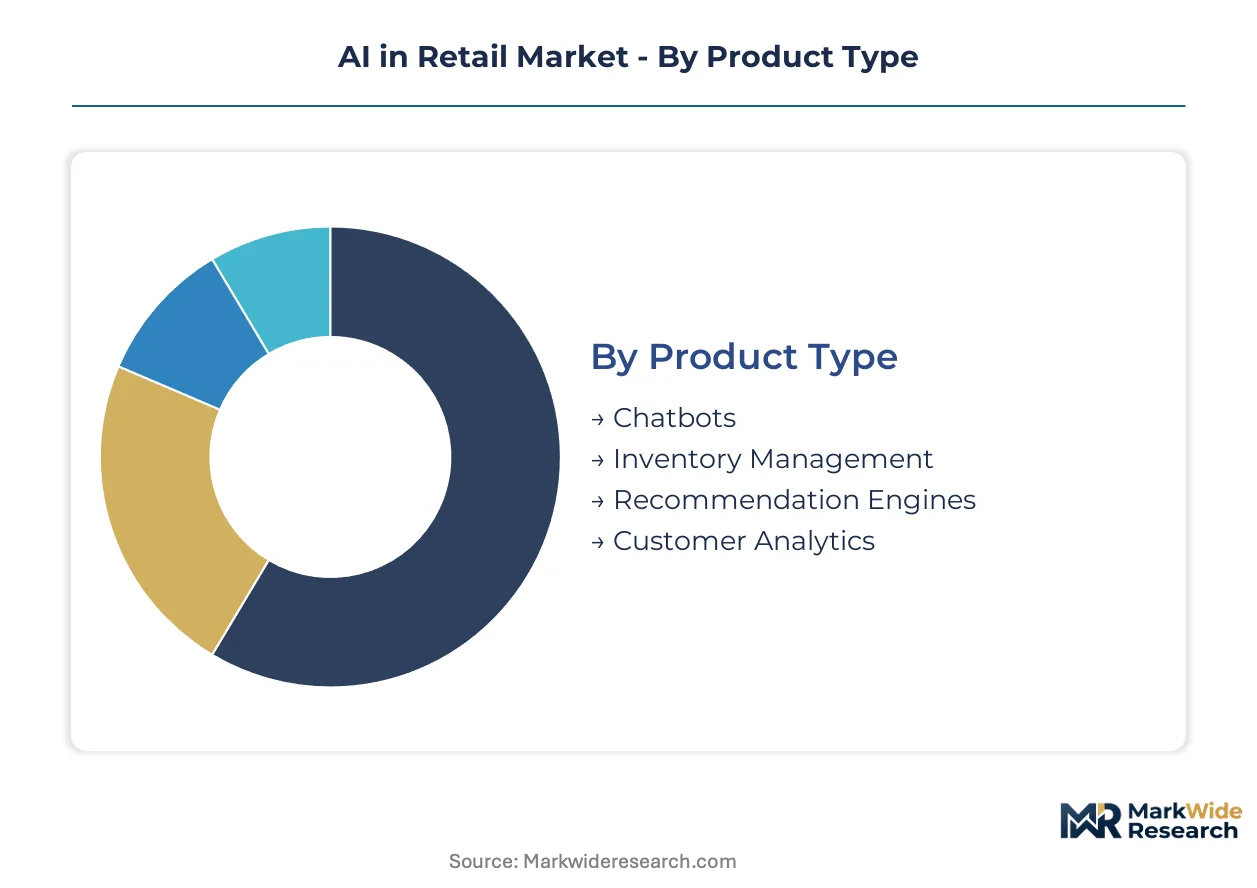
AI in retail exhibits divergent deployment economics across product types and end users. Standardized SaaS modules compete against bespoke implementations. Technology choices cascade through compliance obligations, particularly under the EU AI Act's risk-tiered framework.
Product Type:
Customization intensity varies sharply — chatbots deploy as configurable templates while customer analytics demand proprietary data pipelines.
- Recommendation Engines:Collaborative filtering and deep learning architectures process behavioral signals to surface product assortments. E-commerce platforms in the United States concentrate procurement here, driven by conversion rate optimization mandates from Walmart and Target.
- Customer Analytics:Segmentation models and lifetime value predictors ingest transactional histories across channels. European retail chains face GDPR friction that fragments training datasets and elevates infrastructure costs relative to North American deployments.
- Chatbots:Natural language interfaces handle order inquiries and returns processing through pre-trained transformer models.
- Inventory Management:Demand forecasting and automated replenishment systems synchronize stock levels across distribution nodes.
Leading the category by volume: Recommendation Engines. Expanding most quickly: Customer Analytics.
End User:
Procurement scale and integration complexity separate enterprise buyers from mid-market adopters.
- E-commerce Platforms:Cloud-native architectures enable rapid model deployment and A/B testing at scale. Amazon anchors enterprise demand through in-house silicon production and fulfillment-optimized computer vision systems.
- Retail Chains:Hybrid online-offline operations require unified customer data platforms that reconcile digital behavior with in-store transactions. Grocery chains deploy computer vision for checkout automation, compressing labor cost structures while triggering EU AI Act compliance investments.
- Brick-and-Mortar Stores:Point-of-sale integration and shelf-monitoring systems demand edge hardware with thin network tolerance.
- Wholesalers:B2B order automation and vendor-managed inventory protocols dominate technology priorities.
Dominating procurement budgets: Retail Chains. Steepest adoption climb: E-commerce Platforms.
Technology:
Foundation model maturation is collapsing traditional development timelines from months to weeks.
- Machine Learning:Supervised and unsupervised algorithms power demand forecasting, price optimization, and churn prediction. Predictive analytics and personalization applications attract the largest implementation budgets from enterprise buyers.
- Computer Vision:Shelf inspection, checkout automation, and loss prevention systems process visual data through on-device inference chips. Edge AI hardware maturation enables real-time inventory tracking without cloud latency.
- Natural Language Processing:Sentiment analysis and conversational interfaces extract intent from customer service interactions.
- Predictive Analytics:Time-series models and regression techniques project sales patterns and inventory requirements.
Widest deployment footprint: Machine Learning. Gaining share fastest: Computer Vision.
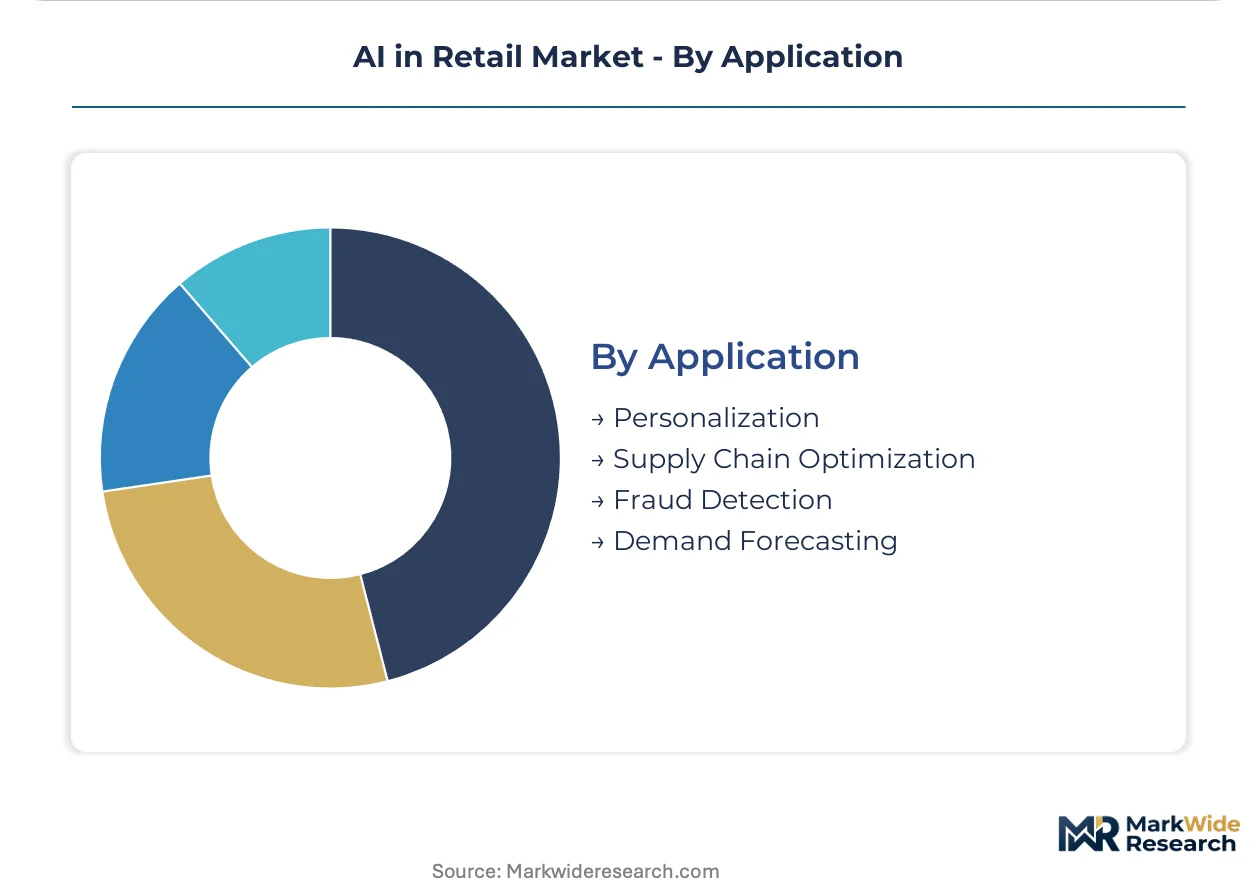
Application:
Margin capture potential separates customer-facing personalization from back-office optimization.
- Personalization:Real-time product recommendations and dynamic pricing engines directly influence conversion rates and basket size. Recommendation engines and customer analytics capture disproportionate margin pools across e-commerce platforms.
- Supply Chain Optimization:Route planning, warehouse automation, and vendor selection algorithms reduce fulfillment costs. Supply chain optimization and personalization applications attract the largest implementation budgets from enterprise buyers.
- Fraud Detection:Anomaly detection models flag payment irregularities and return abuse patterns.
- Demand Forecasting:Seasonal adjustment and promotional lift models inform procurement and merchandising decisions.
Highest margin capture: Personalization. Climbing fastest: Supply Chain Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Hangzhou anchor Asia-Pacific concentration for retail AI hardware assembly, while enterprise software procurement clusters in Seattle and Redmond drive North American demand density.
United States
Walmart and Target anchor enterprise AI procurement through dedicated innovation labs in Austin and Seattle. The FTC enforces algorithmic transparency rules for recommendation engines operating across interstate commerce. Seattle's cloud corridor sustains Azure-based deployment pipelines for inventory management and demand forecasting.
China
Domestic e-commerce platforms from Alibaba and JD.com drive multimodal foundation model adoption for automated catalog generation. SAMR enforces algorithmic disclosure mandates for recommendation engines, forcing stack rebuilds for compliance. Shenzhen's electronics manufacturing belt concentrates edge AI chip production for shelf-monitoring systems.
Germany
Aldi and Lidl deploy computer vision for checkout automation across dense store networks, compressing labor cost structures. The EU AI Act imposes risk-tiered conformity assessments on biometric identification systems, mandating human-in-the-loop overrides. Berlin's retail tech cluster hosts governance tooling vendors serving pan-European grocery chains.
India
Reliance Retail and Tata's digital commerce arms scale machine learning for personalization across fragmented consumer markets. The PLI scheme for electronics manufacturing attracts semiconductor assembly away from traditional East Asian hubs. Bengaluru's enterprise software corridor supplies MLOps talent to mid-market retail organizations.
United Kingdom
Tesco and Sainsbury's unify online-offline customer data platforms to reconcile digital behavior with in-store transactions. GDPR data localization requirements fragment cross-border analytics pipelines, elevating infrastructure costs relative to North American deployments. London's fintech-retail convergence zone incubates fraud detection model providers.
AI in Retail Market Vendor Landscape
United States producers anchor the cloud infrastructure tier; Chinese specialists hold hardware-optimized computer vision systems. The vendor base splits between consolidated hyperscalers with captive silicon production and fragmented point-solution vendors serving compliance-heavy European deployments. Three archetypes dominate: hyperscale cloud providers with vertical integration into custom chips, ERP incumbents unbundling AI modules from legacy contracts, and computer vision specialists targeting grocery automation. Competitive moves concentrate on M&A for MLOps talent and strategic partnerships for edge hardware distribution.
Within the hyperscale tier, Microsoft and Amazon exemplify divergent vertical integration strategies. Microsoft leverages Azure infrastructure to sustain enterprise-grade deployment pipelines, while Amazon anchors competitive positioning through in-house silicon production and fulfillment-optimized vision systems. NVIDIA occupies a position as the dominant training infrastructure supplier, though GPU supply concentration in Taiwan and South Korea creates procurement bottlenecks for retail model development.
| Leading Market Players |
|---|
| Microsoft |
| Amazon |
| IBM |
| Oracle |
| Salesforce |
| SAP |
| NVIDIA |
| Alibaba |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's risk-tiered conformity assessments gate qualified supply for high-stakes retail algorithms, restricting premium-tier pricing access to vendors with documented governance tooling and audit capabilities. This regulatory filter concentrates pricing power among compliant hyperscalers while fragmenting procurement economics for mid-market European chains.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid deployment capabilities with premium positioning, while spot inventory of pre-trained models trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and customization depth. Pricing pressure stems from GPU supply concentration compressing training margins for non-hyperscale vendors. Mid-market retail chains exhibit highest price sensitivity, whereas Walmart-class enterprise buyers prioritize compliance bundling over unit economics.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea concentrate advanced GPU production, while Shenzhen and Hangzhou anchor edge AI chip assembly for shelf-monitoring systems. Training infrastructure draws from NVIDIA's foundry partnerships and domestic Chinese silicon alternatives. Single-source vulnerability in advanced node semiconductor fabrication elevates procurement risk for model development pipelines. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI in retail is consolidating around compliance-capable hyperscalers, with the EU AI Act's conformity assessment costs forcing weaker point-solution vendors toward acquisition or exit.
For Market Incumbents: Extend governance tooling capabilities to capture EU AI Act audit services demand from pan-European grocery chains. Acquire MLOps talent clusters in Bengaluru and Berlin to defend against ERP incumbents unbundling AI modules. Vertical integration into edge hardware distribution secures channel control against computer vision specialists. For New Entrants and Emerging Players: The price-point gap between Azure-tier premium deployments and open-source economy stacks opens white space in ISO 42001-certified mid-market orchestration. Target Indian retail chains scaling under PLI scheme incentives with vendor-managed inventory automation. Lead with pharmacy retail AI applications where FDA guidelines create regulated channel barriers. For Investors and Strategic Acquirers: Foundation model licensing deals with US department store chains are the leading indicator that enterprise buyers are unbundling from legacy ERP contracts. Five-to-ten-year viability favors computer vision specialists with grocery automation deployments and documented EU AI Act compliance pathways. Watch for SAMR-mandated stack rebuilds in China as signal of multinational vendor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | MLOps talent scarcity in mid-market organizations drives consolidation toward governance-capable targets. |
| Platform Integration | Unified customer data platforms reconcile digital behavior with in-store transactions for hybrid retailers. |
| Geographic Expansion | India's PLI scheme attracts semiconductor assembly away from East Asian concentration zones. |
| Strategic Partnership | Edge hardware distribution alliances with big-box formats bypass cloud latency constraints. |
| Product Launch | Vision-language models for shelf inspection collapse centralized distribution cost advantages. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and EU regulatory databases formed the secondary backbone, supplemented by customs records tracking edge AI hardware flows. Primary interviews with retail CTOs, grocery chain innovation leads, and MLOps engineers validated deployment timelines and procurement patterns. Bottom-up and top-down triangulation reconciled vendor revenue disclosures with enterprise buyer budget allocations.
Bottom-up modeling of adoption curves across deployment models, organization size tiers, and regional regulatory clusters anchored the analytical framework. Top-down constraints from cloud infrastructure spending patterns and GPU supply forecasts bounded the projection horizon. CAGRs derived from segmented penetration rates and technology substitution dynamics, with foundation model maturation timelines and compliance cost trajectories as key inputs.
Inputs from primary interviews and secondary regulatory filings were available through the study window; gaps in private company deployment metrics introduce uncertainty bands around mid-market adoption timelines. Forecasts reflect documented assumptions regarding EU AI Act implementation pacing and SAMR enforcement intensity. Material deviation in GPU supply availability or foundation model licensing terms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market