
 Global Artificial Intelligence in Law Market | 2026-2036
Global Artificial Intelligence in Law Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence in Law Market Foresight
Mid-sized law firms is collapsing the historical dominance of AmLaw 100 firms in AI procurement, as subscription-based tools democratize access to predictive analytics and contract intelligence. LexisNexis leverages its vast legal database infrastructure to anchor enterprise deployments across North America and Europe. Harvey specializes in large language model applications for elite firms, while Luminance competes on rapid contract review automation in due diligence workflows.
Artificial intelligence in law encompasses machine learning systems, natural language processing engines, and generative models trained on statutory texts, case law, and transactional documents to automate legal reasoning, extract contractual obligations, and forecast judicial outcomes with quantified confidence intervals. Cloud-based deployment leads adoption among corporate counsel seeking scalable API integration with existing matter management systems, while predictive analytics and contract analysis command the fastest expansion as general counsels prioritize spend visibility and obligation tracking. On-premise solutions retain footholds in government agencies and judiciary settings where data sovereignty requirements restrict external hosting.
The EU AI Act imposes risk-tiered obligations on legal AI systems, compelling vendors to document training data provenance and human oversight protocols for high-risk judicial applications. The SEC in the United States enforces disclosure standards for AI-generated investment advice, while China's SAMR reviews algorithmic recommendation systems affecting commercial arbitration platforms. Stakeholders must monitor evolving liability frameworks that assign responsibility between software vendors and supervising attorneys when automated analyses inform client strategy.
Market Dynamics
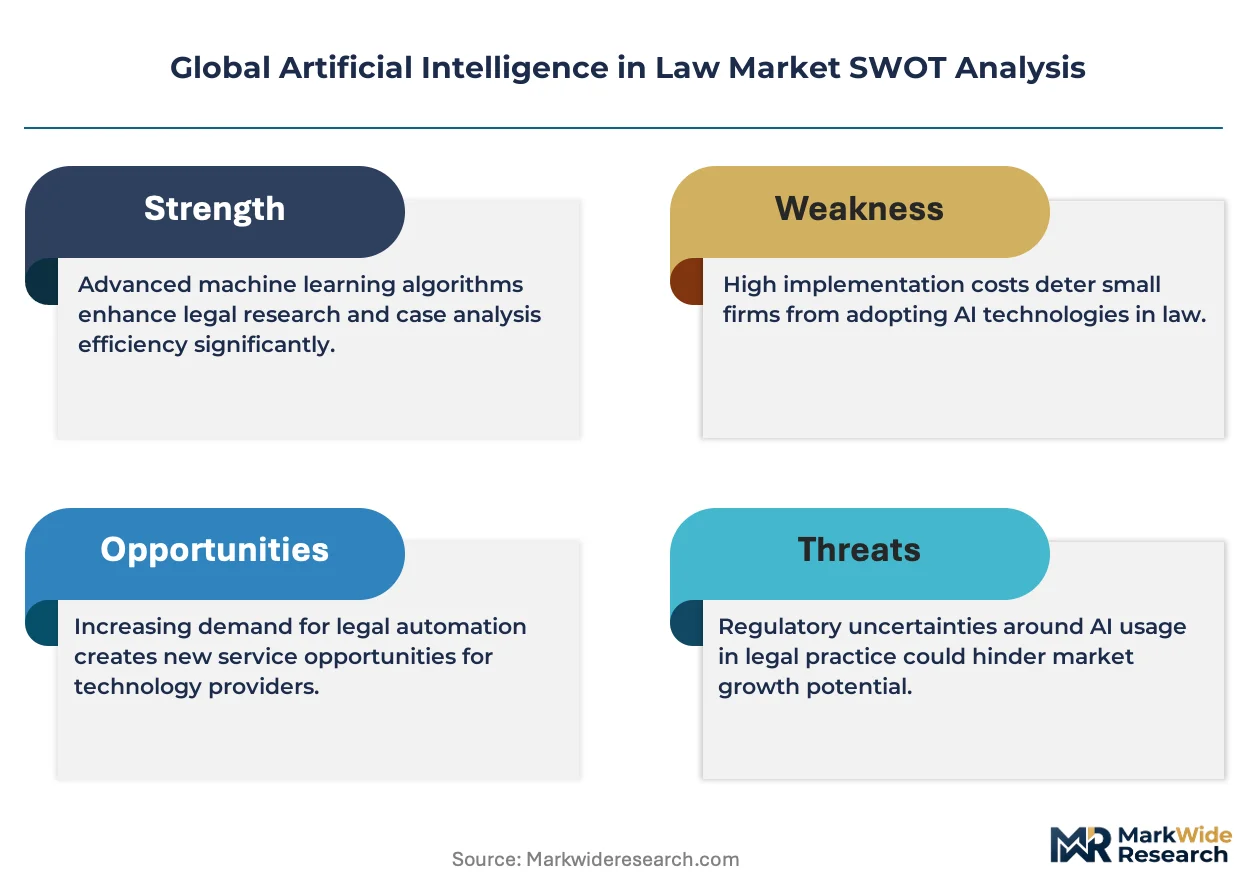
Generative AI is fragmenting the traditional hierarchy between elite law firms and mid-market competitors by compressing the cost differential for sophisticated legal analysis. This technology shift erodes the historical moat of premium hourly billing models.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered obligations for high-risk judicial applications compel legal departments to upgrade algorithmic governance infrastructure.
- Contract intelligence automation:Natural language processing engines trained on transactional documents accelerate due diligence timelines for private equity and M&A advisory.
- United States:SEC disclosure standards for AI-generated investment advice drive demand for auditable legal reasoning systems in financial services compliance.
Market Restraints
- Training data scarcity:Proprietary case law and sealed settlement agreements remain inaccessible, constraining model accuracy for litigation prediction.
- Cloud infrastructure concentration:Reliance on hyperscale providers in the United States creates data sovereignty conflicts for European judiciary deployments.
- Professional liability ambiguity:Bar associations in multiple jurisdictions have not clarified malpractice boundaries when attorneys delegate analysis to automated systems.
Strategic Opportunities
- India:Underpenetrated corporate legal departments present white space for contract lifecycle management platforms localized to common law frameworks.
- Small law firm cooperatives:Shared AI infrastructure models enable collective procurement of predictive analytics previously reserved for AmLaw 100 budgets.
- Convergence of blockchain and smart contracts:Self-executing agreements require automated legal interpretation engines for dispute resolution protocols.
Industry Challenges
- Prompt engineering expertise gap:Legal professionals lack training in structured query design for large language model outputs, degrading result reliability.
- Legacy matter management integration:Decades-old practice management databases resist API connectivity with modern AI platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence in Law Market |
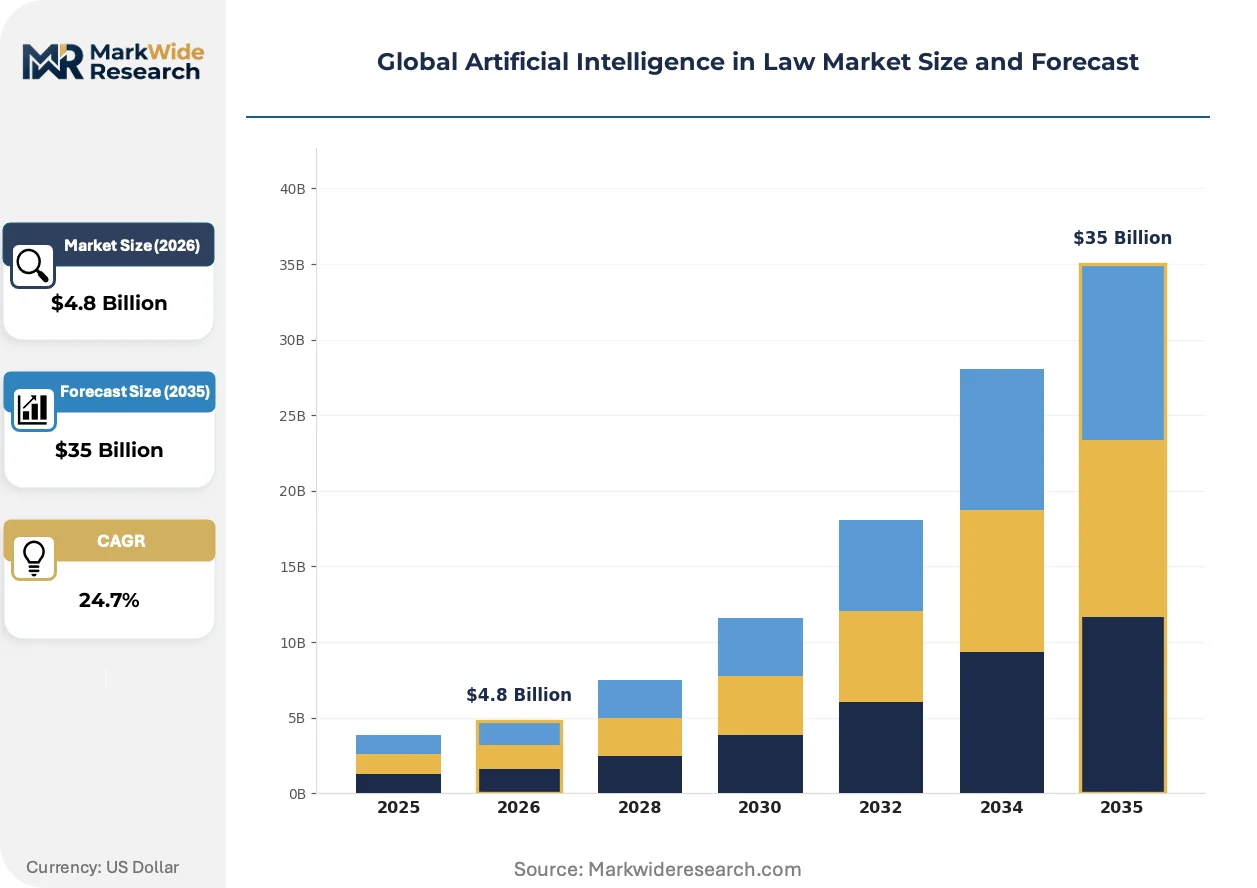
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Document Automation, Predictive Analytics, Legal Research, Contract Analysis, E-Discovery, Compliance Monitoring Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, API Integration End User: Corporate Counsel, Law Firms, Government Agencies, Legal Process Outsourcing, Judiciary, Legal Publishers Application: Litigation Support, Contract Management, Case Prediction, Risk Assessment, Intellectual Property Management, Due Diligence |
| Companies Covered | Everlaw, Clio, Brightflag, Casetext, LexisNexis, Harvey, Ironclad, Luminance, Relativity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence in Law Market Shifts & Advancements
Foundation models trained on statutory corpora are compressing the research-to-brief cycle from weeks to hours. This acceleration is reshaping staffing ratios and fee structures across litigation and transactional practices.
Retrieval-augmented generation architectures are fragmenting the dominance of monolithic legal databases by enabling law firms to query proprietary document repositories alongside public case law. Boutique litigation practices in London and Singapore deploy these hybrid systems to match research depth at elite firms. The technology is fragmenting traditional information asymmetries between specialist and generalist practitioners.
China's SAMR algorithmic recommendation reviews are extending to commercial arbitration platforms, compelling vendors to document decision logic for dispute resolution AI. This regulatory expansion forces architecture redesigns for cross-border legal tech deployments. Vendors serving Greater China now maintain separate model versions to satisfy explainability mandates.
General counsel purchasing patterns now prioritize API-first platforms over integrated suites, unbundling research, drafting, and analytics into best-of-breed subscriptions. Corporate legal departments in Germany and the Netherlands lead this modular procurement approach. The shift pressures incumbent providers to expose functionality through microservices rather than monolithic licenses.
Global Artificial Intelligence in Law Market Segmentation
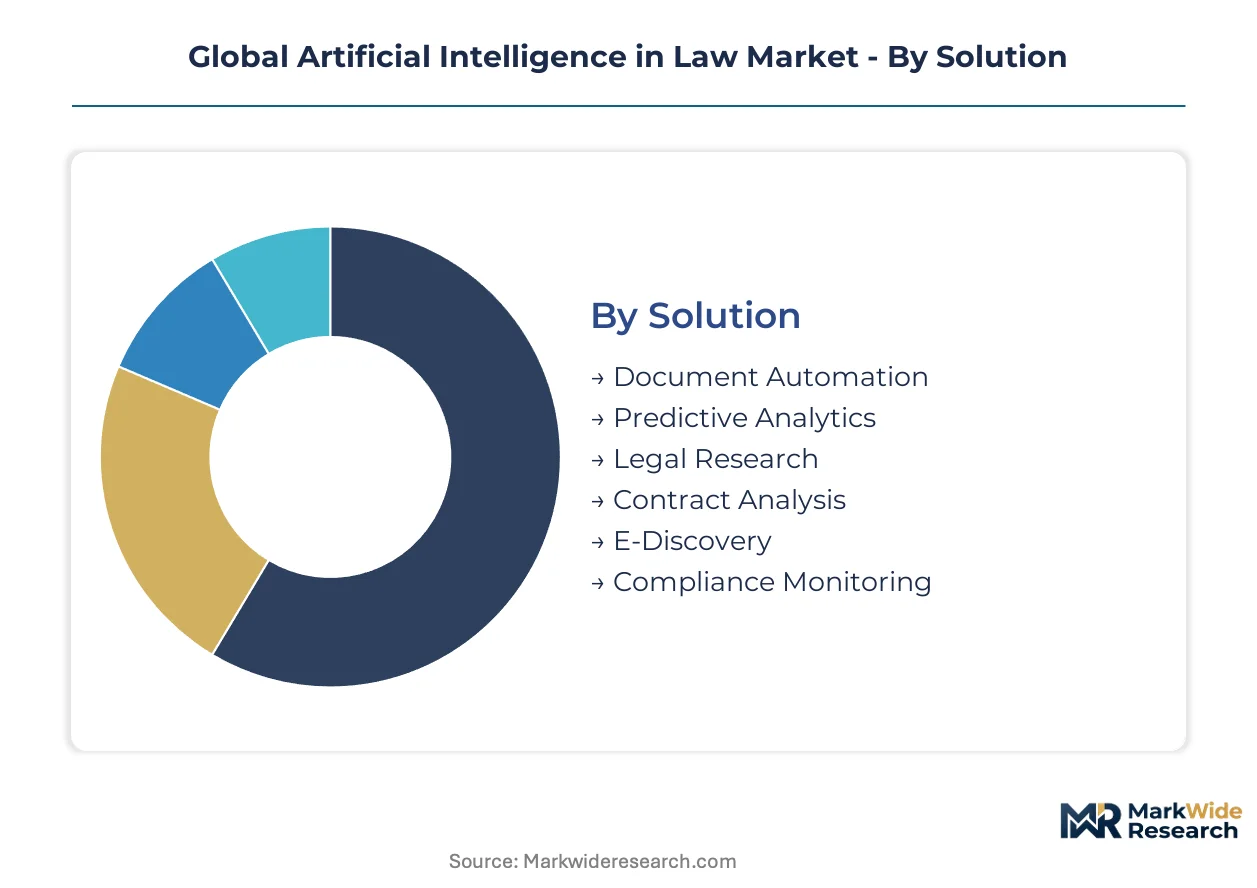
Segmentation reveals how legal AI procurement concentrates around specific workflow pain points and infrastructure constraints. Understanding these divisions exposes where vendors capture premium pricing versus where commoditization pressures dominate.
Solution:
Margin pools concentrate in applications that compress high-stakes decision timelines and reduce dependency on senior attorney hours.
- Document Automation:Natural language generation engines produce first-draft contracts, pleadings, and regulatory filings from structured templates and precedent libraries. Demand clusters in United Kingdom financial services compliance teams facing MiFID II documentation burdens.
- Predictive Analytics:Machine learning models trained on docket data forecast judicial outcomes, settlement ranges, and motion success probabilities with quantified confidence intervals. United States litigation departments in insurance and employment law deploy these tools most aggressively to optimize reserve allocations and early-case assessment.
- Legal Research:Semantic search and citation analysis platforms accelerate statutory and case law retrieval.
- Contract Analysis:NLP engines extract obligations, risks, and deviations from standard positions in transactional documents.
- E-Discovery:Technology-assisted review prioritizes document relevance for regulatory investigations and complex litigation.
- Compliance Monitoring:Continuous surveillance systems flag regulatory changes and contractual breaches across enterprise document repositories.
The dominant share belongs to Contract Analysis, while Predictive Analytics is closing the gap fastest as general counsel prioritize spend predictability in litigation budgeting.
Deployment:
Customer infrastructure maturity and data sovereignty requirements split procurement between flexible cloud access and controlled on-premise environments.
- Cloud-Based:Scalable compute resources enable elastic processing of large document volumes without capital expenditure. Corporate legal departments in Germany and the Netherlands favor this model for API integration with existing matter management systems.
- SaaS:Subscription licensing delivers pre-configured workflows with minimal IT involvement. Mid-sized law firm cooperatives in the United States leverage shared SaaS procurement to access capabilities previously reserved for AmLaw 100 budgets.
- On-Premise:Local hardware deployment satisfies judiciary and government agency requirements for data residency and air-gapped security.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud scale for non-confidential workloads.
- API Integration:Microservices expose specific AI functions for embedding within legacy practice management platforms.
Cloud-Based deployment commands the largest installed base, though API Integration is expanding most quickly as general counsel unbundle integrated suites into best-of-breed subscriptions.
End User:
Budget authority and risk tolerance vary sharply across user types, with corporate buyers prioritizing ROI metrics and government purchasers emphasizing auditability.
- Corporate Counsel:In-house legal departments with direct P&L accountability drive fastest adoption of contract lifecycle management and spend analytics. United States technology and pharmaceutical sectors lead procurement volume.
- Law Firms:Partnership structures create complex adoption dynamics where efficiency gains threaten hourly billing models. Elite firms deploy generative AI for client-facing differentiation while mid-market competitors use subscription tools to compress cost differentials.
- Government Agencies:Procurement offices and regulatory bodies require explainable outputs and documented training data provenance to satisfy oversight requirements.
- Judiciary:Courts and administrative tribunals pilot AI for case management and sentencing support under strict human oversight protocols mandated by the EU AI Act.
- Legal Process Outsourcing:Third-party providers integrate AI to maintain margin pressure on commoditized document review and due diligence services.
- Legal Publishers:Traditional research database vendors embed generative layers atop statutory and case law corpora to defend subscription renewals.
Corporate Counsel account for the dominant procurement volume, while Law Firms are gaining share fastest as partnership resistance to efficiency tools weakens under competitive pressure from alternative legal service providers.
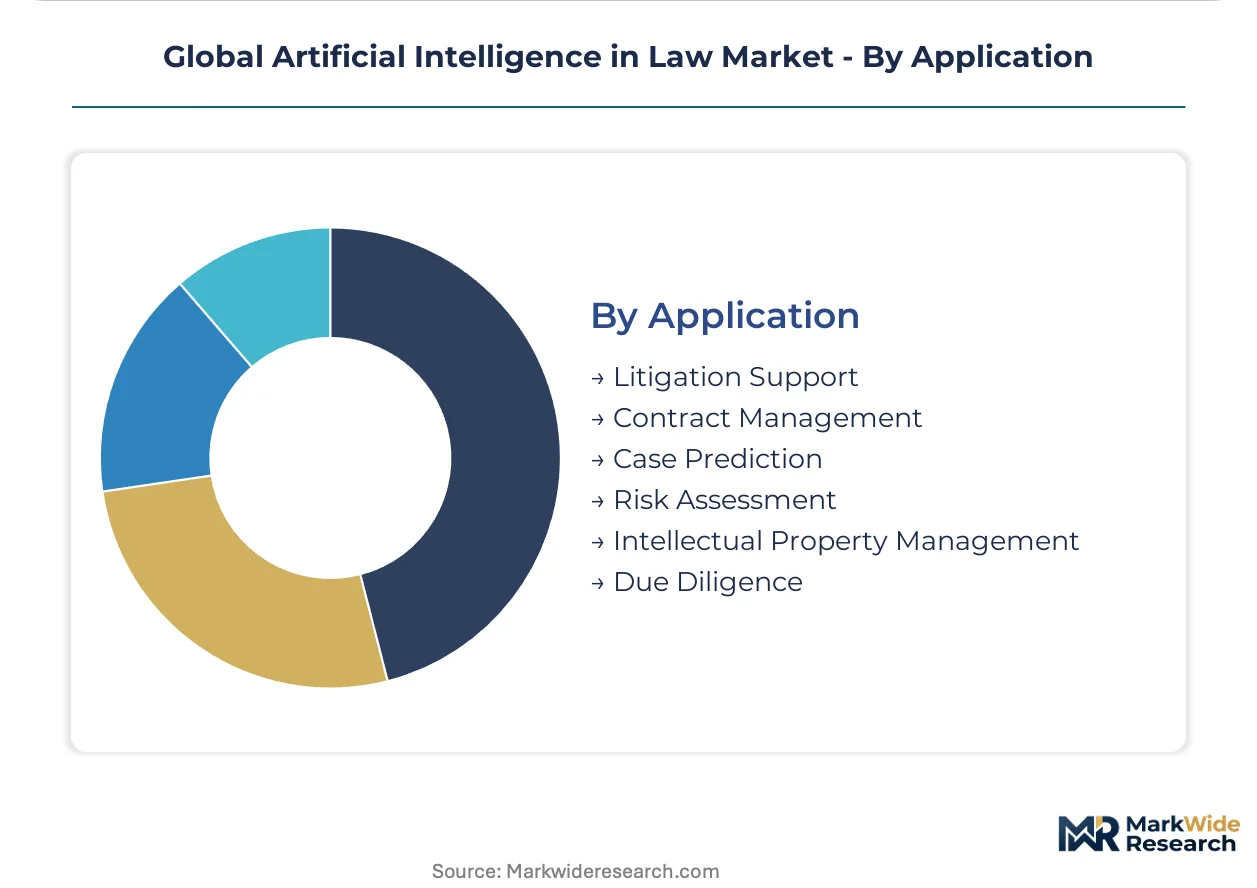
Application:
Workflow automation potential and error cost profiles determine where AI delivers measurable value versus where human judgment retains primacy.
- Contract Management:End-to-end platforms spanning drafting, negotiation, execution, and obligation monitoring. Private equity and M&A advisory teams in London and New York deploy these systems to accelerate transaction timelines and reduce post-close liability exposure.
- Due Diligence:Automated extraction and risk flagging across target company document populations. Chinese cross-border acquisition teams use these tools to navigate SAMR disclosure requirements and foreign investment screening.
- Litigation Support:Evidence organization, timeline construction, and strategy simulation for contested proceedings.
- Case Prediction:Outcome forecasting for settlement negotiation and resource allocation decisions.
- Risk Assessment:Proactive identification of regulatory, contractual, and operational exposures across enterprise operations.
- Intellectual Property Management:Prior art search, portfolio analysis, and infringement monitoring for patent and trademark assets.
Contract Management holds the dominant position, while Due Diligence is climbing the fastest as transaction velocity recovers and deal complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Legal technology exports flow predominantly from the United States to the United Kingdom and European Union jurisdictions, with secondary corridors connecting Chinese vendors to Southeast Asian markets. This trade pattern reflects concentration of venture capital funding and cloud infrastructure in specific metropolitan clusters.
United States
Corporate legal departments in New York and San Francisco drive procurement of contract intelligence platforms, with insurance and employment law practices deploying predictive analytics for reserve optimization. SEC disclosure standards for AI-generated investment advice compel financial services compliance teams to adopt auditable reasoning systems. The Boston-Washington corridor houses concentrated vendor development activity for litigation support tools.
United Kingdom
Magic Circle firms and financial services compliance teams in London accelerate adoption of document automation engines to satisfy MiFID II documentation burdens. The EU AI Act risk-tiered obligations reshape procurement specifications for high-risk judicial applications. Legal technology clusters in Manchester and Edinburgh specialize in e-discovery and contract lifecycle management for mid-market law firms.
Germany
Corporate counsel in Frankfurt and Munich prioritize API-first platforms for integration with existing matter management systems, unbundling integrated suites into modular subscriptions. The EU AI Act mandates documented training data provenance for algorithmic decision-making tools. Berlin hosts emerging legal tech startups focused on compliance monitoring for cross-border transactions.
China
Cross-border acquisition teams in Shanghai and Beijing deploy due diligence automation to navigate SAMR disclosure requirements and foreign investment screening. SAMR algorithmic recommendation reviews extend to commercial arbitration platforms, forcing architecture redesigns for explainability mandates. Shenzhen vendors develop separate model versions to satisfy domestic regulatory requirements distinct from export configurations.
India
Underpenetrated corporate legal departments in Mumbai and Delhi present expansion opportunities for contract lifecycle management platforms localized to common law frameworks. The country's national technology regulator evaluates AI governance standards for judicial and advisory applications. Bangalore technology company legal teams pilot predictive analytics for intellectual property portfolio management.
Global Artificial Intelligence in Law Market Competitive Landscape
Player mix skews toward specialized legal technology vendors rather than generalist enterprise software providers, creating a tiered structure with distinct capability concentrations. Incumbent legal research database operators defend subscription renewals through generative layer integration, while venture-backed startups capture growth in contract automation and litigation prediction. Two strategic archetypes dominate: infrastructure-heavy incumbents leveraging proprietary data corpora, and agile specialists deploying large language models for specific workflow verticals. Competitive moves concentrate on strategic partnerships with cloud hyperscalers and portfolio diversification into adjacent compliance automation.
Among established legal information providers, LexisNexis anchors enterprise deployments across North America and Europe through database infrastructure integration. Harvey occupies a position exemplifying large language model specialization for elite firm workflows. Luminance represents rapid contract review automation archetypes in due diligence applications. These three entities illustrate the competitive spectrum from incumbent scale to targeted workflow disruption.
| Leading Market Players |
|---|
| Everlaw |
| Clio |
| Brightflag |
| Casetext |
| LexisNexis |
| Harvey |
| Ironclad |
| Luminance |
| Relativity |
| Others |
Supply & Pricing Matrix
Ninety-day implementation cycles for enterprise legal AI deployments compress vendor negotiation windows and concentrate pricing power with cloud hyperscalers serving United States and European Union jurisdictions. This lead-time compression amplifies cost differentials between API-first platforms and legacy on-premise installations while rewarding vendors with pre-certified EU AI Act compliance documentation.
Pricing Analysis
Prior-generation rule-based contract review tools command legacy subscription rates that next-generation large language model platforms undercut by standard-economy pricing differentiation. SaaS-tiered structures dominate procurement, with per-seat licensing anchored in data processing volumes and API call frequency. Price differentiation rests on explainability certification depth and human-in-the-loop audit trails. Cost compression in mid-market tiers intensifies because Harvey and Luminance force competitive repricing. Corporate legal departments exhibit highest price sensitivity, while Magic Circle firms prioritize capability over cost.
Supply Chain Analysis
Inbound logistics costs for specialized GPU clusters through Rotterdam and Singapore ports constrain deployment velocity for European judiciary buyers requiring air-gapped infrastructure. Supply concentrates in United States, Ireland, and Germany for foundation model training infrastructure. Raw material dependencies span high-bandwidth memory modules, custom ASIC accelerators, and proprietary legal corpora licensing. Single-source vulnerability persists in NVIDIA's datacenter GPU allocation protocols. Distribution runs through hyperscaler marketplaces and direct vendor sales teams serving enterprise legal departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent legal technology vendors face substitution pressure from generalist enterprise AI platforms repurposing horizontal large language models for legal workflows. This threat demands defensive repositioning around proprietary data moats and regulatory certification depth.
For Market Incumbents: Fortify market position by deepening backward integration into exclusive case law and sealed settlement repositories unavailable to horizontal AI competitors. Accelerate EU AI Act high-risk system certification for judicial applications before generalist platforms achieve compliance parity. Prioritize API ecosystem lock-in through matter management system partnerships that raise switching costs for corporate legal departments. For New Entrants and Emerging Players: Anchor in India and Southeast Asia's underpenetrated corporate legal departments where localized common law platforms lack established incumbents. Target contract lifecycle management for mid-sized law firm cooperatives seeking collective procurement leverage against AmLaw 100 pricing benchmarks. Pursue white-label embedding strategies through existing practice management software channels rather than direct enterprise sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence in AI governance creates persistent demand for multi-compliant architecture. Acquisition targets should display documented training data provenance and established human oversight protocols satisfying EU AI Act mandates. Monitor SAMR algorithmic recommendation enforcement intensity as inflection signal for Greater China market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | High-risk judicial system designation unlocks premium pricing in European judiciary procurement. |
| Retrieval-Augmented Generation Integration | Hybrid architectures enable boutique firms to match elite firm research depth without proprietary database investments. |
| API-First Platform Unbundling | Microservices exposure captures procurement shifts in Germany and Netherlands toward modular best-of-breed subscriptions. |
| Training Data Provenance Documentation | Documented source transparency satisfies SEC disclosure standards for AI-generated investment advice in financial services. |
| Smart Contract Legal Interpretation Engines | Self-executing agreement dispute resolution protocols address emerging blockchain-arbitration convergence demand. |
Research Methodology
Desk research of regulatory filings with SEC, EU AI Act implementation guidance, and SAMR algorithmic governance notices preceded structured interviews with general counsel at Fortune 500 technology and pharmaceutical companies, legal technology procurement officers at Magic Circle and AmLaw 100 firms, and compliance leads at financial services institutions. Secondary validation drew from court system technology procurement databases, legal publisher subscription disclosures, and venture capital funding records for contract automation and litigation prediction startups. Bottom-up deployment estimates triangulated against top-down legal technology spending benchmarks across corporate legal departments and law firm partnership structures.
Variance decomposition across solution type, deployment model, end-user category, and application workflow shaped analytical framework construction throughout the projection horizon. Segmentation dimensions modeled encompassed natural language processing engine architecture, cloud infrastructure residency requirements, and jurisdiction-specific regulatory compliance tier. CAGRs derived from elasticity-adjusted adoption curves calibrated to historical legal technology procurement cycles and generative AI capability inflection points. Forecast inputs included EU AI Act enforcement trajectory and SEC disclosure standard implementation pace for AI-generated advisory outputs.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory fragmentation and hyperscaler cloud concentration; material deviation in AI governance harmonization or training data accessibility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market