
 Affective Computing Market | 2026-2036
Affective Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Affective Computing Market Intelligence
ISO/IEC 30150-1 certification for emotion-aware computing systems is rotating vendor eligibility toward firms with dedicated biometric ethics programs. Affectiva leverages its automotive emotion AI heritage to sustain software licensing across in-cabin monitoring platforms. Microsoft Corporation anchors enterprise demand through Azure cognitive services that integrate sentiment analysis into customer relationship workflows. Intel competes at the silicon layer with neuromorphic chips optimized for real-time facial expression classification at the edge.
Affective computing denotes the interdisciplinary field where computer systems detect, interpret, process, and simulate human emotional states through multimodal inputs including facial electromyography, galvanic skin response, vocal prosody, and text sentiment scoring, with primary commercial purpose centered on human-machine interaction optimization across customer service, clinical diagnostics, and immersive entertainment environments. Machine learning architectures dominate technology deployment due to their capacity for continuous model refinement against labeled emotional datasets, while wearable sensors represent the fastest-expanding segment as biosignal-capturing devices shrink toward earbud and wristband form factors. Natural language processing retains mature margins in call-center sentiment analysis where deployment patterns favor cloud-based infrastructure for elastic compute scaling across seasonal demand cycles.
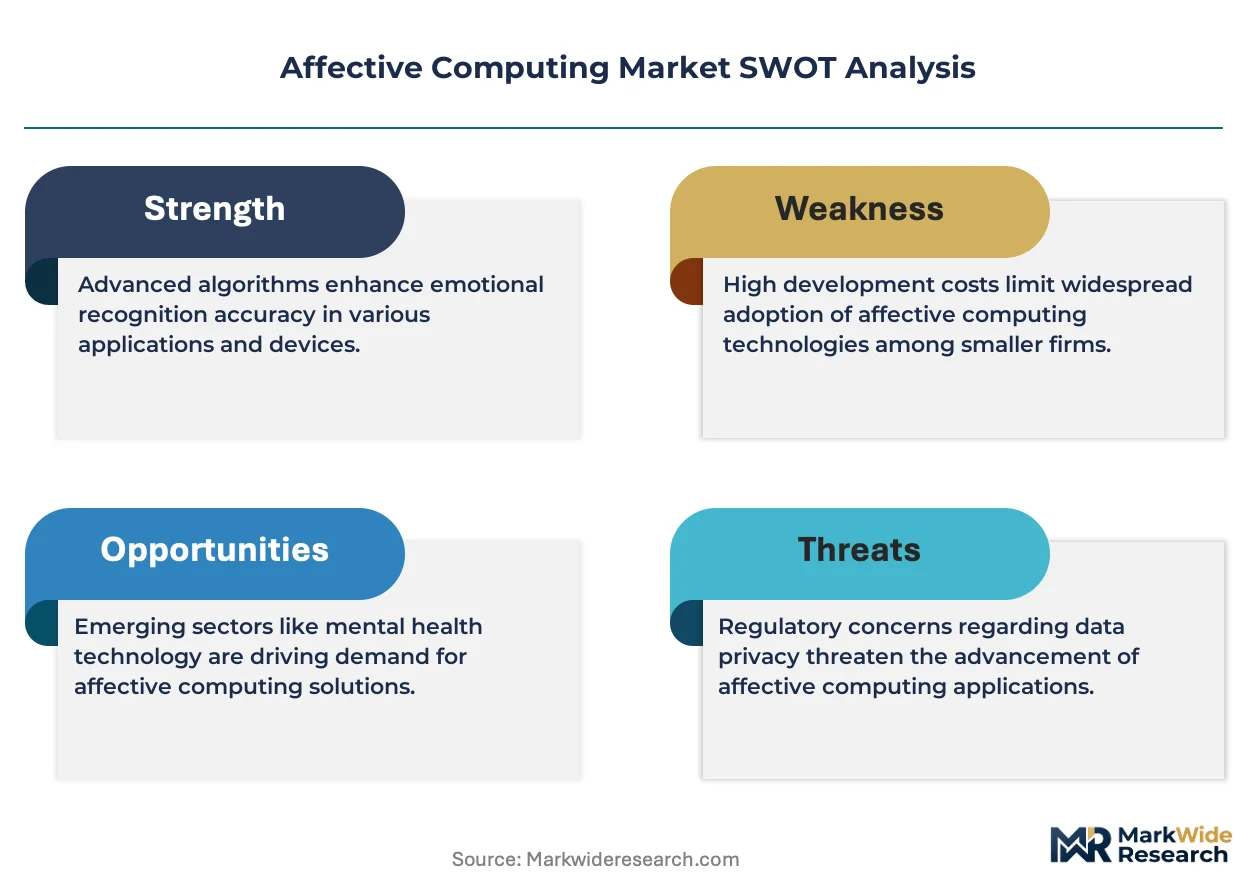
The EU AI Act classifies emotion recognition in workplace and educational settings as high-risk, mandating conformity assessments before CE marking and market entry. FDA digital health guidance requires clinical validation for affective computing tools deployed in mental health monitoring by healthcare providers. China's SAMR algorithmic recommendation provisions and GB standards for personal information security on mobile applications impose additional compliance layers for cross-border emotion data processing. Stakeholders must monitor divergence between permissive and restrictive regulatory blocs when architecting geographic deployment strategies and data residency frameworks.
Market Dynamics
Regulatory classification of emotion recognition systems as high-risk under the EU AI Act is compressing vendor timelines for conformity assessments while simultaneously opening procurement pathways for certified incumbents in healthcare and automotive verticals.
Growth Catalysts
- FDA Digital Health Guidance:Clinical validation requirements for mental health monitoring tools create procurement pull from US healthcare providers seeking reimbursable diagnostic workflows.
- Automotive Safety Mandates:Driver monitoring systems for drowsiness detection are becoming standard fitment in European and Chinese vehicle certification schemes.
- Neuromorphic Silicon:Edge-optimized chips enable real-time facial expression classification without cloud latency, expanding deployment in privacy-sensitive environments.
Market Restraints
- Biometric Sensor Cost Volatility:Galvanic skin response and facial electromyography hardware remains concentrated among Asian contract manufacturers, exposing margins to component pricing swings.
- Algorithmic Bias Liability:Cross-cultural emotion classification errors create litigation exposure under GDPR automated decision-making provisions and emerging US state biometric privacy laws.
- Substitute Modalities:Text-based sentiment analysis using large language models offers lower deployment friction for call-center applications, pressuring multimodal system pricing.
Strategic Opportunities
- Underpenetrated Clinical Settings:Post-operative pain assessment and pediatric emotion monitoring in India present whitespace for regulatory-first entrants with CDSCO pathway experience.
- Wearable Form Factor Convergence:Earbud-integrated biosignal capture combining heart rate variability with vocal prosody analysis opens consumer wellness subscription revenue streams.
- EU AI Act Certification Services:Third-party conformity assessment bodies for high-risk emotion recognition systems represent an emerging B2B services layer with recurring audit revenue.
Industry Challenges
- Multimodal Data Integration:Synchronizing facial expression, physiological, and linguistic signals requires specialized machine learning engineering talent scarce outside major technology clusters.
- ISO/IEC 30150-1 Certification Timelines:Emotion-aware computing system validation cycles extend 18-24 months, delaying product launches and freezing development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Affective Computing Market |
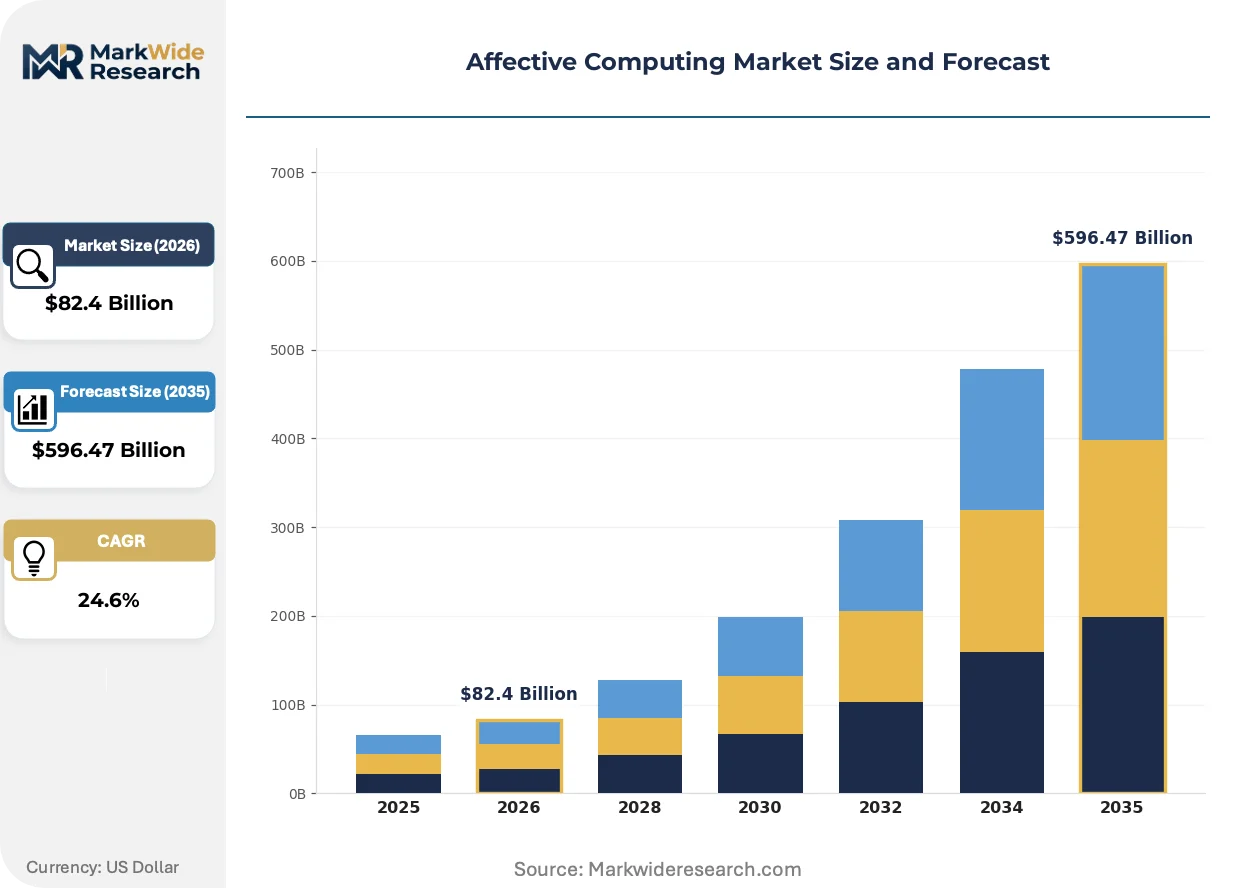
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $596.47 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Emotion Recognition, Sentiment Analysis, Affective Gaming, Mental Health Monitoring Technology: Machine Learning, Natural Language Processing, Facial Recognition, Wearable Sensors End User: Healthcare Providers, Educational Institutions, Gaming Companies, Retailers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Affectiva, IBM Corporation, Microsoft Corporation, Apple, Qualcomm, Intel, Nuance Communications Inc., Kairos AR Inc., NuraLogix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Affective Computing Market Strategic Shifts & Innovations
Edge-native processing architectures and regulatory compliance automation are displacing cloud-dependent emotion AI deployments across privacy-sensitive sectors.
Multimodal sensor fusion is fragmenting the dominant position of camera-only emotion recognition systems. Automotive OEMs in Germany and Japan are integrating galvanic skin response steering wheel sensors with infrared facial tracking, compressing the addressable market for pure-play computer vision vendors while expanding total system value per vehicle. Tier-1 suppliers with captive biosensor capabilities are capturing margin previously allocated to software licensing.
The EU AI Act's high-risk classification for workplace emotion recognition is redirecting vendor development resources toward clinical and automotive exemptions. CE marking requirements for algorithmic transparency documentation are extending product development cycles by 30-40 percent for European market entry. Affected vendors are establishing Dublin and Amsterdam compliance hubs to manage conformity assessment body relationships.
Subscription-based emotion analytics procurement is displacing perpetual software licenses in enterprise call-center deployments. North American financial services and telecommunications buyers are unbundling sentiment analysis from broader customer relationship management suites, creating direct procurement relationships with specialized affective computing vendors. This shift compresses vendor sales cycles while increasing annual churn risk.
Affective Computing Market Segmentation
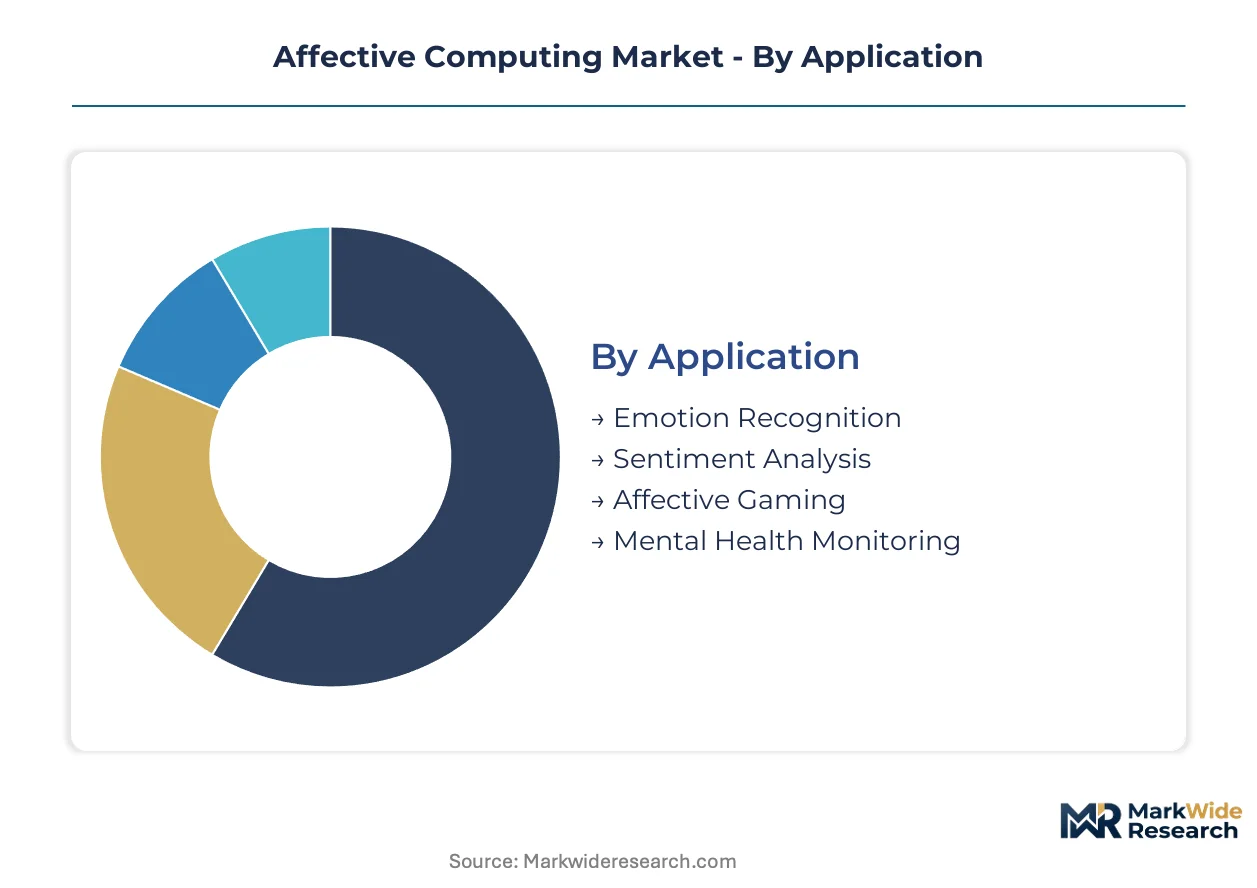
Affective computing vendors configure product portfolios across four intersecting dimensions. Application focus determines regulatory exposure, while technology choice governs margin structure and deployment feasibility.
Application:
Substitution pressure from general-purpose AI tools is most acute in sentiment analysis, where large language models commoditize text-based emotion detection.
- Emotion Recognition:Multimodal systems process facial expressions, vocal prosody, and physiological signals simultaneously. Automotive OEMs in Germany and Japan deploy these for driver drowsiness monitoring under KBA and METI certification schemes. EU AI Act high-risk classification for workplace deployment is compressing vendor timelines for conformity assessments.
- Sentiment Analysis:Natural language processing extracts emotional valence from text streams in customer service workflows. North American financial services and telecommunications buyers are unbundling these tools from broader customer relationship management suites, creating direct procurement relationships with specialized vendors.
- Affective Gaming:Real-time biometric feedback adjusts gameplay intensity based on player arousal levels. Japanese publishers lead integration of galvanic skin response peripherals into immersive entertainment environments.
- Mental Health Monitoring:Clinical-grade systems track depression and anxiety indicators through passive smartphone sensor analysis. FDA digital health guidance requires validation studies for reimbursable diagnostic workflows in US healthcare settings.
Emotion recognition anchors the volume base while mental health monitoring gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive hardware sensing from software-only deployment models.
- Machine Learning:Supervised and reinforcement architectures enable continuous model refinement against labeled emotional datasets. Cloud infrastructure supports elastic compute scaling for training pipelines, though edge migration is accelerating for privacy-sensitive use cases.
- Natural Language Processing:Transformer-based models dominate text sentiment classification with mature deployment tooling. Call-center applications favor this modality for lower implementation friction compared to multimodal alternatives.
- Facial Recognition:Computer vision systems classify micro-expressions through infrared and visible spectrum cameras. Pure-play vendors face margin pressure as automotive OEMs integrate these capabilities in-house.
- Wearable Sensors:Biosignal-capturing devices shrink toward earbud and wristband form factors combining heart rate variability with galvanic skin response. Consumer wellness subscription revenue streams are emerging around continuous affect monitoring.
Natural language processing holds the largest installed base while wearable sensors expand most quickly.
End User:
Customer type determines procurement sophistication, with healthcare and automotive buyers demanding certified systems versus retail's price-sensitive experimentation.
- Healthcare Providers:Hospitals and clinics deploy emotion recognition for patient monitoring and pain assessment. CDSCO pathway experience in India creates whitespace for regulatory-first entrants in post-operative and pediatric applications.
- Educational Institutions:Learning analytics platforms measure student engagement through attention and frustration indicators. EU AI Act restrictions on workplace and educational emotion recognition are redirecting vendor development resources toward exempt verticals.
- Gaming Companies:Publishers integrate affective feedback loops to personalize narrative pacing and difficulty curves. Japanese and South Korean studios lead hardware-software integration for immersive entertainment.
- Retailers:Brick-and-mortar operators test facial expression analysis for shopper sentiment tracking. GDPR automated decision-making provisions create litigation exposure for cross-cultural classification errors.
Healthcare providers command premium pricing while gaming companies drive steepest volume expansion.
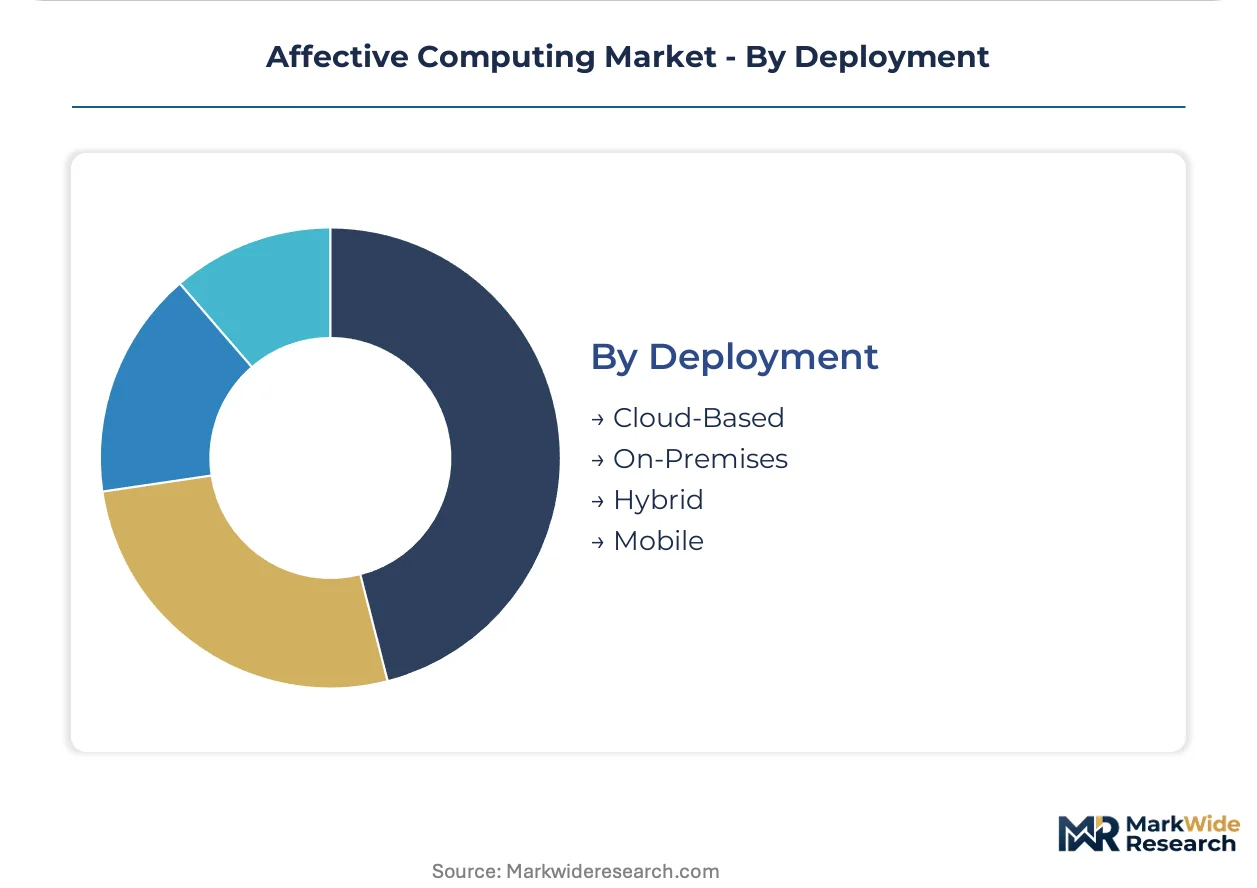
Deployment:
Data residency requirements and latency constraints are fragmenting architecture preferences across geographies and use cases.
- Cloud-Based:Elastic infrastructure supports seasonal demand cycles in call-center sentiment analysis. European buyers increasingly require EU-sovereign data processing to satisfy GDPR localization expectations.
- On-Premises:Air-gapped installations serve classified government and defense applications with strict information security protocols. Higher capital expenditure and operational complexity limit addressable market scope.
- Hybrid:Edge preprocessing with cloud model refinement balances latency and computational depth. Automotive safety systems favor this architecture for real-time drowsiness alerts with over-the-air improvement.
- Mobile:Smartphone-native processing leverages onboard sensors for continuous passive monitoring. Mental health applications in the United States are pioneering FDA-cleared mobile diagnostic workflows.
Cloud-based deployment retains the largest revenue share while mobile architectures climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems and automotive OEMs dominate procurement across major economies, with regulatory certification becoming the primary vendor selection filter rather than price.
United States
FDA digital health guidance drives clinical validation requirements for mental health monitoring tools deployed by hospitals and telemedicine platforms. HIPAA compliance frameworks govern cross-border emotion data processing for multinational healthcare providers. Boston and San Francisco anchor development clusters where startups pursue FDA-cleared mobile diagnostic workflows.
Germany
KBA certification mandates for driver monitoring systems create standardized procurement pathways for automotive Tier-1 suppliers. EU AI Act high-risk classification for workplace emotion recognition redirects vendor resources toward exempt automotive and clinical verticals. Stuttgart and Munich host engineering centers where OEMs integrate galvanic skin response sensors with infrared facial tracking.
China
SAMR algorithmic recommendation provisions and GB standards for personal information security impose compliance layers on emotion AI deployments in consumer applications. NMPA pathway requirements affect clinical-grade systems for hospital patient monitoring. Shenzhen and Beijing concentrate hardware manufacturing for wearable biosignal devices while Shanghai drives software development for sentiment analysis platforms.
Japan
METI certification schemes for automotive safety systems accelerate fitment of drowsiness detection technology in domestic and export vehicle programs. PMDA consultation procedures guide developers of emotion-based diagnostic tools for psychiatric applications. Tokyo and Osaka studios lead integration of affective feedback loops into immersive entertainment hardware for gaming publishers.
India
CDSCO regulatory pathways for software-as-medical-device create whitespace for entrants in post-operative pain assessment and pediatric emotion monitoring. Healthcare provider procurement concentrates in metropolitan hospital chains seeking reimbursable diagnostic workflows. Bangalore and Hyderabad development hubs focus on cost-optimized wearable form factors combining heart rate variability with vocal prosody analysis.
Affective Computing Market Key Industry Players
Player mix skews toward technology conglomerates with cloud infrastructure assets and specialized emotion AI boutiques with vertical-specific certification experience. Market structure shows moderate consolidation at the platform layer alongside fragmentation in application-specific tooling. Two strategic archetypes dominate: horizontal platform providers leveraging existing enterprise relationships, and vertical specialists capturing automotive and healthcare certification moats. Competitive moves center on M&A for biometric sensor capabilities and strategic partnerships for regulatory compliance automation.
Within the technology conglomerate tier, Microsoft Corporation and Intel exemplify platform-scale positioning through cloud cognitive services and edge-optimized silicon architectures respectively. Affectiva occupies a specialist position reflecting its automotive heritage and sustained software licensing presence across in-cabin monitoring platforms. These three entities represent distinct competitive vectors: enterprise workflow integration, hardware-layer performance optimization, and vertical certification depth.
| Leading Market Players |
|---|
| Affectiva |
| IBM Corporation |
| Microsoft Corporation |
| Apple |
| Qualcomm |
| Intel |
| Nuance Communications Inc. |
| Kairos AR Inc. |
| NuraLogix Corporation |
| Others |
Cost & Logistics Intelligence
Eighteen-month ISO/IEC 30150-1 certification cycles concentrate pricing power among incumbent vendors with established conformity assessment relationships, while Asian contract manufacturers capture margin through galvanic skin response and facial electromyography sensor supply. Component lead-time volatility feeds directly into tiered licensing structures that separate automotive OEMs willing to absorb certification premiums from price-sensitive retail buyers seeking commoditized sentiment analysis tools.
Pricing Analysis
Cost-plus contracts with Asian foundry indexation anchor hardware pricing for biosignal sensors, while software licensing stratifies across premium, standard, and economy tiers based on ISO/IEC 30150-1 certification grade and vertical integration depth. Price differentiation separates FDA-cleared mental health monitoring suites from unvalidated workplace emotion detection tools facing EU AI Act liability exposure. Cost compression in camera-only computer vision tiers is intensifying because automotive OEMs are bringing facial recognition capabilities in-house. Healthcare providers exhibit the lowest price sensitivity due to reimbursable diagnostic workflows, whereas retailers testing shopper sentiment tracking demand economy-tier solutions with minimal compliance overhead.
Supply Chain Analysis
Inventory cycles stretching 90-120 days for neuromorphic silicon reflect concentration in Taiwan, South Korea, and the United States for edge-optimized chip fabrication. Raw material dependencies center on indium tin oxide for transparent conductive films, gallium arsenide for infrared emitters, and specialized polymers for galvanic skin response electrodes. Single-source vulnerability pervades facial electromyography sensor supply where Japanese and German component specialists maintain process IP. Distribution runs through Tier-1 automotive suppliers and hospital GPO contracts rather than open-channel electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory blocs creates niche opportunities for vendors with geography-specific certification expertise, as divergent EU AI Act, FDA, and SAMR compliance requirements prevent platform-scale dominance.
For Market Incumbents: Shield installed base relationships through captive supply of wearable biosensor hardware and accelerated ISO/IEC 30150-1 certification for next-generation multimodal systems. Large language model substitution threatens text-based sentiment analysis margins, making vertical integration into earbud-integrated sensor manufacturing the priority defensive lever. Channel control through exclusive hospital GPO contracts and automotive Tier-1 supplier partnerships limits entrant access to price-insensitive buyer segments. For New Entrants and Emerging Players: Lead with CDSCO pathway expertise in Indian post-operative pain assessment and pediatric emotion monitoring where regulatory-first positioning outcompetes unvalidated imports. Underpenetrated clinical settings in metropolitan hospital chains offer the most penetrable whitespace, particularly when bundled with cost-optimized wearable form factors combining heart rate variability with vocal prosody capture. Direct SaaS procurement relationships with North American financial services buyers bypass incumbent CRM suite bundling. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory moat play because certification timelines and conformity assessment body relationships compound competitive advantage over five-to-ten year horizons. Acquisition targets should display vertical integration into biometric sensor hardware alongside established automotive or healthcare certification dossiers. Watch FDA breakthrough device designation velocity for mental health monitoring tools as the signal indicating inflection toward reimbursable clinical adoption.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30150-1 Certification Acceleration | Compresses 18-24 month validation cycles to capture EU AI Act high-risk system procurement. |
| Neuromorphic Silicon Partnership | Secures edge-optimized chip supply from Intel and Qualcomm for real-time facial expression classification. |
| Automotive Tier-1 Integration | Captures steering wheel sensor margin through galvanic skin response hardware-software bundling. |
| Healthcare GPO Contracting | Locks hospital procurement pathways for FDA-cleared mental health monitoring diagnostic workflows. |
| Earbud Form Factor Development | Opens consumer wellness subscription revenue through continuous biosignal capture convergence. |
Research Approach
The analysis maps emotion recognition, sentiment analysis, affective gaming, and mental health monitoring sub-sectors, each validated through CTOs at enterprise software vendors, biomedical engineers at hospital systems, automotive platform engineers at Tier-1 suppliers, and regulatory affairs leads at certification bodies. Primary interview findings triangulate against FDA 510(k) filings, EU AI Act implementation guidance, SAMR algorithmic recommendation provisions, and hyperscaler cognitive service capex disclosures. Bottom-up sensor shipment and software licensing data reconcile with top-down healthcare IT and automotive electronics spend estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models deployment architecture, application vertical, technology modality, and end-user procurement sophistication as core segmentation dimensions. CAGRs derive from logistic diffusion curves fitted to regulatory adoption timelines and clinical validation study completion rates. Neuromorphic silicon foundry capacity expansion and CDSCO software-as-medical-device approval velocity serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU AI Act high-risk classification, FDA digital health guidance, and SAMR personal information security GB standards; material policy shifts would require re-modeling adoption curves and compliance cost structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Artificial Intelligence of Things (Aiot) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Content Automation AI Tools Market