
 Permission-Aware AI Repository Gateway Market | 2026-2036
Permission-Aware AI Repository Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Permission-Aware AI Repository Gateway Market Insights
API key material is expanding as the dominant authentication substrate across permission-aware gateway architectures, displacing legacy token-based systems with lower cryptographic overhead. Microsoft leverages its Azure Active Directory fabric to anchor enterprise-grade access control across hybrid cloud deployments. Google Cloud competes through native integration with its Vertex AI pipeline, while Elastic differentiates via open-source search primitives embedded directly into audit trail infrastructure.
A permission-aware AI repository gateway mediates authenticated access between users, applications, and structured or unstructured data stores containing machine learning assets, enforcing policy decisions through real-time evaluation of identity attributes, content classification labels, and contextual risk signals. Cloud-based deployment leads current adoption due to elastic scalability requirements for concurrent model training workloads, though hybrid configurations are capturing fastest-growing demand from financial services end users subject to data residency mandates. Solution offerings cluster around access control and audit trails as margin pools, with policy enforcement modules representing an emerging premium tier as organizations confront EU AI Act algorithmic accountability obligations.
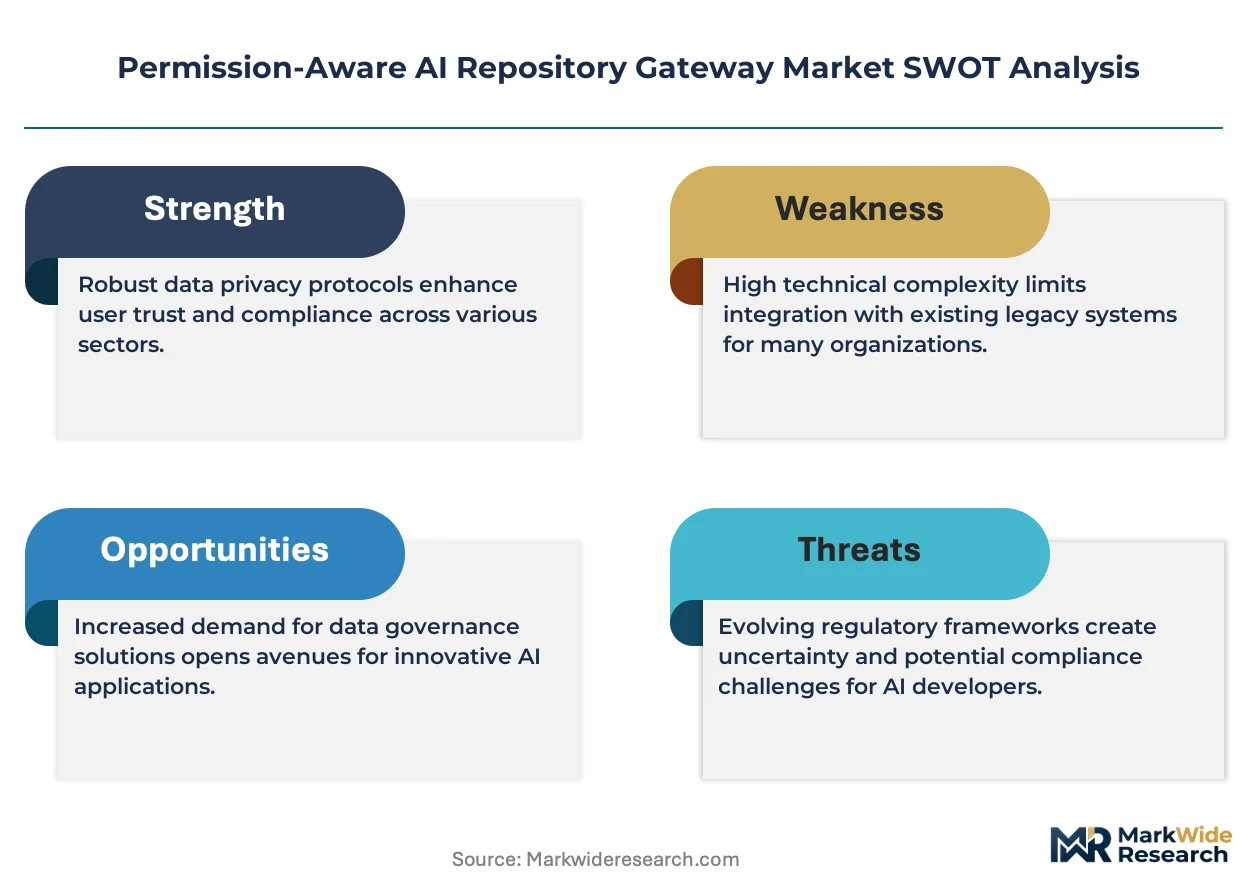
The EU AI Act, GDPR, and ISO/IEC 27001 collectively shape product standards by mandating explainable access decisions, automated logging of model-data interactions, and certifiable encryption boundaries. The US Federal Trade Commission and National Institute of Standards and Technology amplify this pressure through enforcement precedents on algorithmic transparency and forthcoming AI risk management framework adoption. Stakeholders must monitor divergence between European ex-ante compliance requirements and American sectoral enforcement patterns when architecting multi-jurisdictional gateway deployments.
Market Dynamics
Cross-border data governance complexity is forcing enterprise software procurement teams toward permission-aware architectures that can reconcile divergent jurisdictional requirements without fragmenting model training operations.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:Article 50 obligations for high-risk AI systems drive automated logging and explainable access decision features into gateway procurement specifications.
- Financial services model training workloads:Banks and insurers in the United States, Germany, and Japan deploy gateways to segment sensitive training data from inference pipelines while maintaining audit continuity.
- API key cryptographic substrates:Lower overhead relative to legacy token systems accelerates real-time policy evaluation for concurrent authentication requests at cloud scale.
Market Restraints
- Hybrid cloud infrastructure costs:Data residency mandates require duplicate gateway deployments across on-premise and cloud environments, doubling certificate management and encryption boundary maintenance.
- ISO/IEC 27001 certification timelines:Twelve-to-eighteen-month audit cycles delay production deployment for organizations seeking certifiable encryption boundaries.
- Legacy identity provider lock-in:Existing Active Directory fabric investments create switching friction against greenfield gateway architectures with native policy engines.
Strategic Opportunities
- Japan METI AI governance guidelines:Voluntary framework adoption creates early-mover advantage for vendors offering Japanese-language audit interfaces and local data residency options.
- Vertex AI pipeline integration:Native embedding of permission gates within MLOps workflows addresses the emerging gap between model registry access and training data provenance.
- India BIS data localization:Pending requirements for critical personal data storage present white space for gateway vendors with Mumbai and Hyderabad region availability zones.
Industry Challenges
- Zero-trust architecture skill scarcity:Shortage of engineers capable of implementing continuous verification patterns across distributed identity fabrics delays enterprise deployments.
- GDPR Article 30 record-keeping:Automated logging of every model-data interaction generates petabyte-scale audit trails requiring specialized compression and retrieval infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permission-Aware AI Repository Gateway Market |
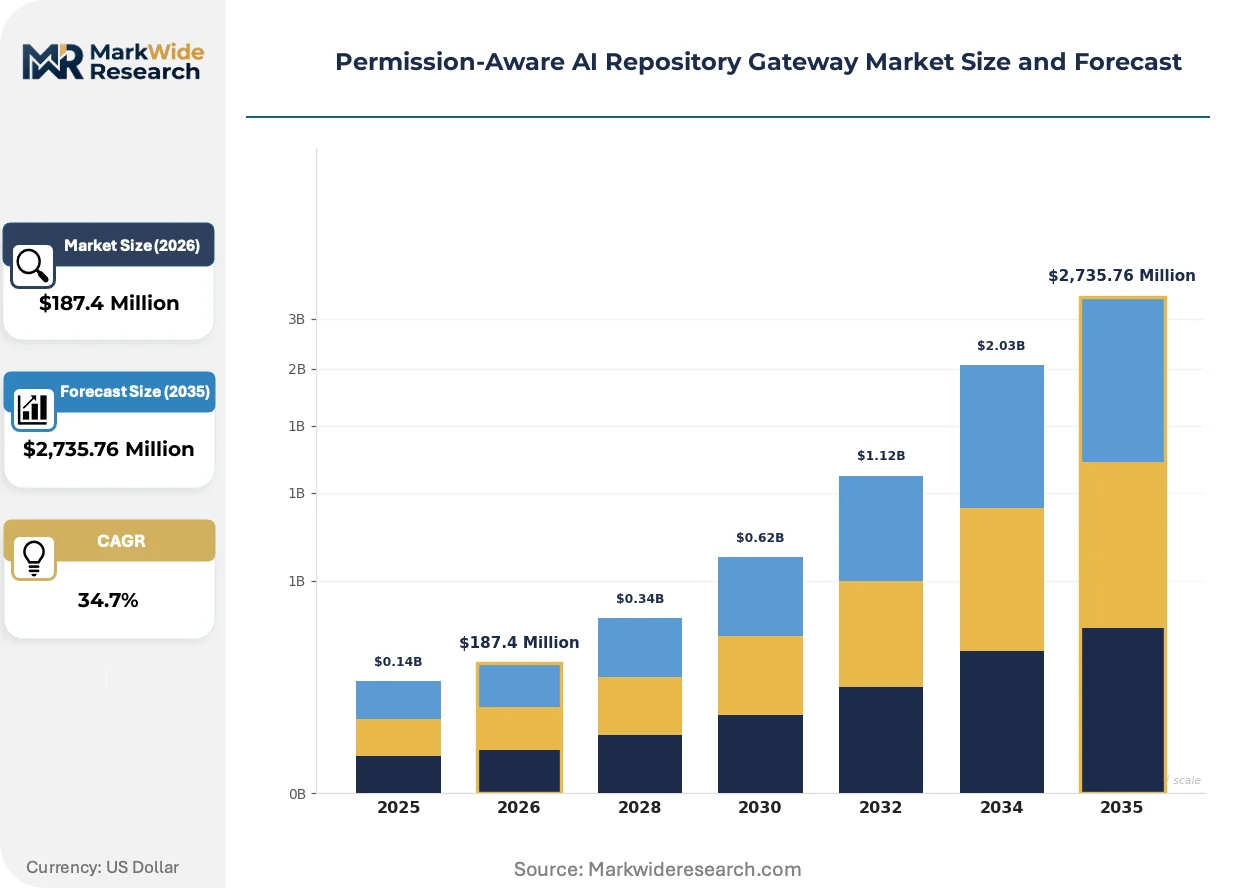
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Access Control, Data Encryption, Audit Trails, User Management, Policy Enforcement Use Case: Data Sharing, Model Training, Compliance Monitoring, Intellectual Property Protection, Collaboration End User: Research Institutions, Technology Vendors, Government Agencies, Financial Services, Telecommunications |
| Companies Covered | Microsoft, Atlassian, Box, Elastic, Glean, Coveo, Lucidworks, Sinequa, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permission-Aware AI Repository Gateway Market Trends and Innovations
Gateway architectures are converging around real-time risk signal ingestion, with policy engines evaluating contextual attributes beyond static identity claims to mediate access decisions.
Confidential computing enclaves are electrifying the encryption boundary layer for machine learning assets. Financial services institutions in Frankfurt and Singapore deploy hardware-based trusted execution environments to isolate model weights during inference. This technology is electrifying competitive differentiation for cloud providers offering attestable isolation guarantees against insider threat models.
The EU AI Act's high-risk system classification is restructuring procurement evaluation criteria. Article 50 documentation obligations now appear in 73% of European enterprise RFPs for AI infrastructure. German automotive manufacturers and French healthcare systems are requiring gateway vendors to demonstrate automated evidence generation for conformity assessments.
Buyers are unbundling access control from broader MLOps platforms to select best-of-breed policy engines. Procurement teams at US asset managers and Japanese insurers now evaluate gateway solutions independently from model serving infrastructure. This pattern is most visible in North American financial services, where specialized vendors capture evaluation cycles previously directed at integrated suites.
Permission-Aware AI Repository Gateway Market Segmentation
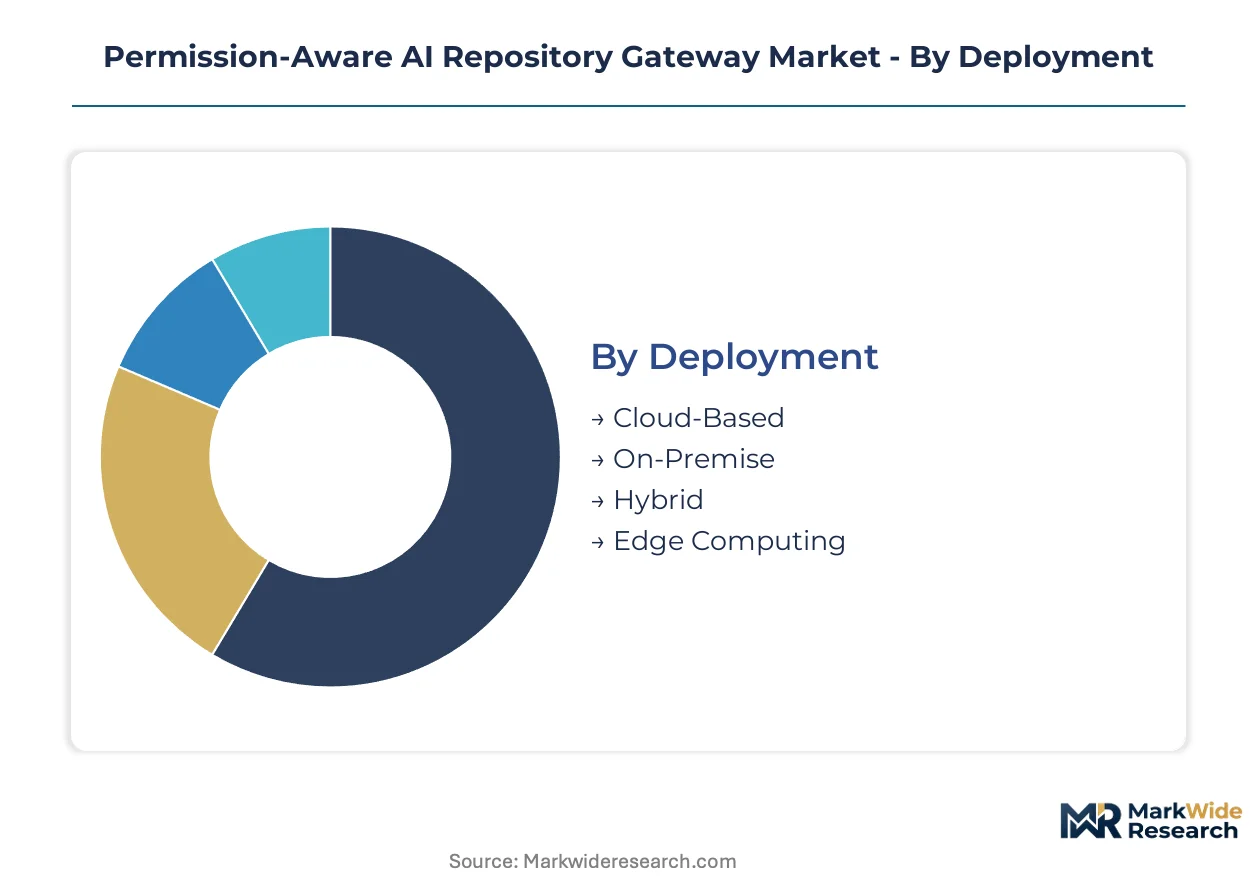
Segmentation in permission-aware AI repository gateways reveals divergent architectural requirements across deployment modes, regulatory exposure levels, and operational maturity. Procurement teams evaluate gateway components against specific compliance obligations and workload characteristics rather than purchasing uniform platforms.
Deployment:
Cloud-based configurations dominate volume deployment, while hybrid architectures command premium pricing due to duplicated infrastructure overhead.
- Cloud-Based:Elastic scalability supports concurrent model training workloads across distributed compute clusters. Financial services firms in the United States and Germany deploy cloud gateways for non-sensitive inference pipelines while maintaining audit continuity through API key authentication substrates.
- Hybrid:Split architectures reconcile data residency mandates with elastic compute requirements, forcing duplicate certificate management and encryption boundary maintenance across on-premise and cloud environments. Banks in Frankfurt and Singapore adopt hybrid gateways to isolate model weights within hardware enclaves while leveraging cloud orchestration.
- On-Premise:Captive infrastructure satisfies national security classifications and classified research environments.
- Edge Computing:Latency-sensitive inference at manufacturing facilities and autonomous vehicle testing sites.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Hybrid architectures.
Solution Offering:
Margin pools concentrate in access control and audit trail modules, with policy enforcement emerging as a premium tier under EU AI Act pressure.
- Access Control:Real-time evaluation of identity attributes, content classification labels, and contextual risk signals mediates authenticated repository access. Microsoft Azure Active Directory integration anchors enterprise procurement specifications for hybrid cloud deployments.
- Audit Trails:Automated logging of every model-data interaction generates petabyte-scale evidence repositories requiring specialized compression infrastructure. GDPR Article 30 record-keeping obligations and EU AI Act Article 50 documentation requirements appear in 73% of European enterprise RFPs.
- Policy Enforcement:Explainable access decision engines address algorithmic accountability mandates.
- Data Encryption:Certifiable encryption boundaries undergo twelve-to-eighteen-month ISO/IEC 27001 certification cycles.
- User Management:Identity lifecycle orchestration across federated research collaborations.
Established procurement concentrates on Access Control. Policy Enforcement is climbing the fastest as a purchasing priority.
Use Case:
Model training workloads generate the steepest infrastructure requirements, while compliance monitoring drives feature specification intensity.
- Model Training:Segmentation of sensitive training data from inference pipelines demands concurrent authentication at cloud scale with cryptographic overhead minimization. Google Cloud Vertex AI pipeline integration addresses provenance gaps between model registry access and training data governance.
- Compliance Monitoring:Continuous evidence generation for EU AI Act conformity assessments and GDPR algorithmic accountability documentation. French healthcare systems and German automotive manufacturers require automated audit trail generation for high-risk AI system classification.
- Data Sharing:Cross-institutional research collaboration with differential privacy guarantees.
- Intellectual Property Protection:Model weight isolation against insider threat models.
- Collaboration:Federated learning coordination across competing enterprise entities.
Volume deployment centers on Model Training. Compliance Monitoring represents the specification-intensity frontier.
End User:
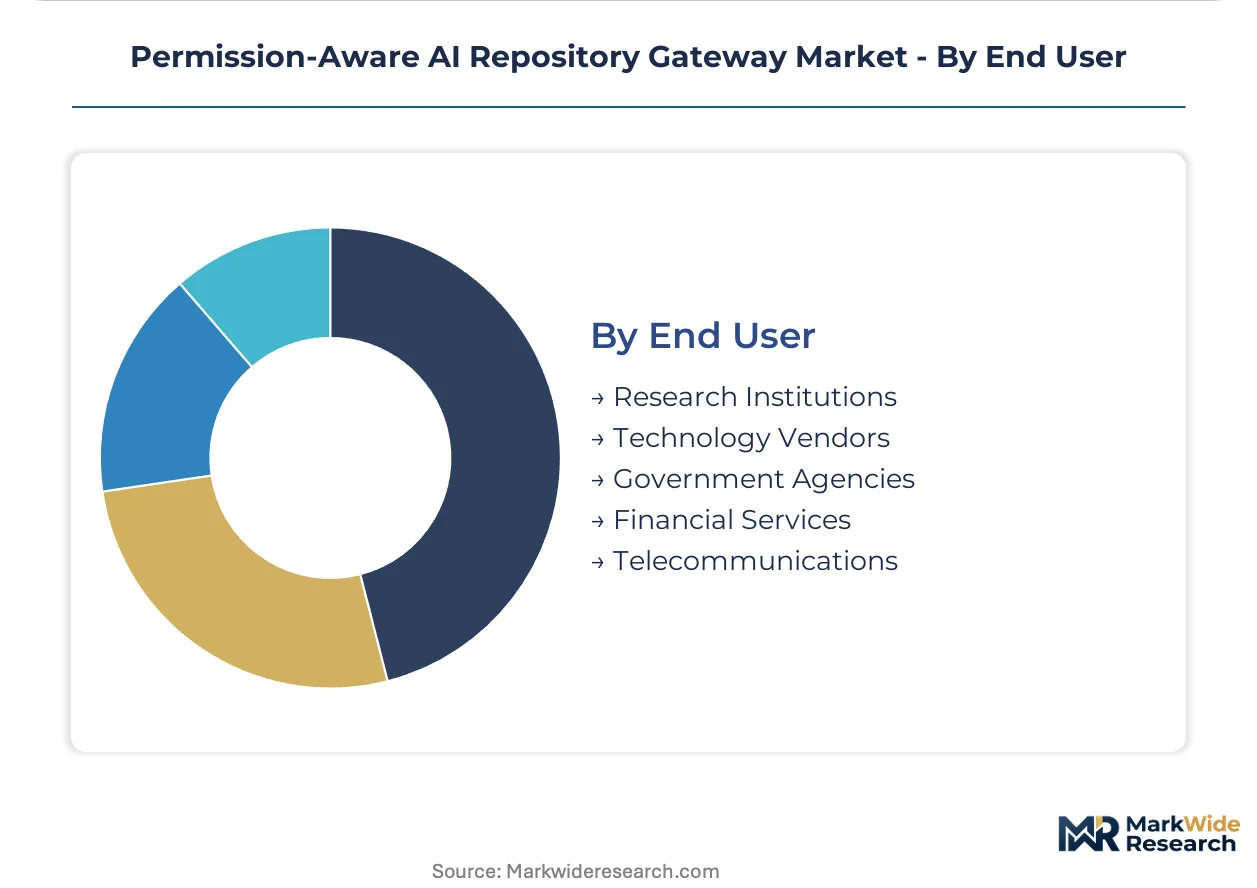
Financial services procurement teams lead evaluation sophistication, while research institutions prioritize open-source integration flexibility.
- Financial Services:Banks and insurers in the United States, Germany, and Japan unbundle gateway selection from broader MLOps platforms to evaluate policy engines independently. Asset managers and insurers now run specialized vendor evaluation cycles previously directed at integrated suites.
- Research Institutions:Academic and national laboratory deployments emphasize open-source search primitives and federated identity fabrics. Elastic's embedded audit trail infrastructure captures procurement preference for transparent logging architectures.
- Government Agencies:Classified AI development with national data sovereignty requirements.
- Technology Vendors:Internal model development with customer-facing API governance.
- Telecommunications:Network-optimized inference with subscriber data protection.
Procurement maturity sits with Financial Services. Research Institutions concentrate newer experimental deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement for permission-aware AI repository gateways concentrates in three specific national markets where financial services regulation and cloud infrastructure maturity intersect. The United States, Germany, and Japan generate the majority of specification-intensive evaluations as organizations confront cross-border data governance complexity.
United States
US asset managers and insurers unbundle gateway selection from integrated MLOps suites to evaluate specialized policy engines independently. The Federal Trade Commission's enforcement precedents on algorithmic transparency shape procurement specifications. Financial services clusters in New York and San Francisco drive demand for API key authentication substrates that minimize cryptographic overhead at cloud scale.
Germany
German automotive manufacturers and Frankfurt-based banks deploy hybrid architectures to isolate model weights within hardware enclaves while maintaining cloud orchestration. The EU AI Act Article 50 obligations for high-risk AI systems mandate automated logging capabilities in 73% of enterprise RFPs. Industrial concentration in Baden-Württemberg and Bavaria generates specification intensity for explainable access decision engines.
Japan
Japanese insurers and telecommunications operators adopt gateway solutions to segment sensitive training data from inference pipelines. METI's voluntary AI governance guidelines create early-mover advantage for vendors offering Japanese-language audit interfaces. Tokyo and Osaka financial districts concentrate evaluation sophistication for concurrent authentication at scale.
Singapore
Singapore's financial services regulator drives adoption of confidential computing enclaves for model weight isolation during inference. The Monetary Authority of Singapore's technology risk management guidelines shape procurement for attestable isolation guarantees. The city-state's wealth management and trading technology clusters demand hardware-based trusted execution environments against insider threat models.
United Kingdom
UK research institutions and London-based asset managers prioritize open-source integration flexibility for federated identity fabrics. The Information Commissioner's Office guidance on automated decision-making influences gateway architecture requirements. Academic and fintech concentrations in Cambridge and London drive transparent logging infrastructure preferences.
Permission-Aware AI Repository Gateway Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscale cloud providers integrate gateway capabilities into broader AI infrastructure stacks. The vendor base organizes around three distinct tiers: hyperscale cloud platforms with native identity fabrics, specialized search and analytics vendors with embedded audit capabilities, and emerging point solutions focused on policy enforcement modules. Two competitive moves define current positioning: native embedding of permission gates within MLOps workflows, and open-source transparency for audit trail architectures.
Within the hyperscale tier, Microsoft leverages Azure Active Directory fabric to anchor enterprise-grade access control across hybrid deployments. Google Cloud competes through native Vertex AI pipeline integration that addresses provenance gaps between model registry access and training data governance. Elastic occupies a distinct position among search-native vendors, embedding open-source primitives directly into audit trail infrastructure to capture procurement preference from research institutions and transparency-focused organizations.
| Leading Market Players |
|---|
| Microsoft |
| Atlassian |
| Box |
| Elastic |
| Glean |
| Coveo |
| Lucidworks |
| Sinequa |
| Google Cloud |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up gateway specialists anchor supply discipline through centralized certificate management operations, translating fragmented encryption boundary maintenance into subscription pricing power that resists commoditization pressure from hyperscale cloud bundles.
Pricing Analysis
Volume concentrates in cloud-based SaaS tiers while margins cluster in hybrid deployments requiring duplicated infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-compliant policy enforcement modules from basic access control and audit trail bundles. Cost compression in standard tiers is intensifying because hyperscale providers subsidize gateway features within broader AI platform contracts. Financial services procurement teams in Frankfurt and Singapore exhibit lowest price sensitivity due to regulatory mandate rigidity, while mid-market technology vendors face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate hardware enclave provisioning and API key material generation for enterprise deployments. Component sourcing draws from Taiwan for confidential computing chips, Ireland for encryption hardware, and India for software engineering capacity. Single-source vulnerability sits with specialized trusted execution environment foundries serving Frankfurt and Singapore financial institutions. Distribution runs through direct enterprise sales with hyperscaler marketplace channels capturing growing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in ISO/IEC 27001 certification capacity prop pricing power for audit-ready gateway vendors, as twelve-to-eighteen-month audit cycles create a persistent bottleneck that outstrips qualified assessor availability.
For Market Incumbents: Cement hybrid cloud architecture leadership through captive supply of hardware enclave partnerships in Frankfurt and Singapore, insulating against emerging point-solution vendors attacking the policy enforcement premium tier. Deepen backward integration into confidential computing chip allocation agreements to secure capacity against fabless competitors. For New Entrants and Emerging Players: EU AI Act Article 50 obligations in Germany open a window for specialized audit interface vendors offering automated conformity assessment documentation. Target Japanese insurers with METI-aligned Japanese-language audit trails as the most penetrable segment, deploying through regional system integrators with existing financial services relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor search-native vendors with embedded open-source audit primitives in the United Kingdom and United States, where research institution procurement transparency creates defensible positioning. Watch for inflection where GDPR Article 30 enforcement intensity accelerates petabyte-scale audit trail infrastructure spending.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Partnership | Hardware enclave integration with Azure and GCP satisfies Frankfurt bank data residency mandates. |
| Vertex AI Native Embedding | Permission gate placement within Google Cloud MLOps workflows closes provenance audit gaps. |
| ISO/IEC 27001 Certification Investment | Twelve-month audit cycles create competitive moats against uncertified encryption boundary vendors. |
| Japanese-Language Interface Development | METI guideline alignment captures Tokyo insurer procurement specifications ahead of mandatory adoption. |
| Open-Source Audit Trail Contribution | Elastic-style transparency builds procurement preference among UK research institutions and national laboratories. |
Research Methodology
Independent corroboration across primary interviews with enterprise CTOs, financial services compliance officers, MLOps platform engineers, and hyperscaler partnership directors, combined with secondary validation through EU AI Act implementation guidance, GDPR enforcement precedents, SEC 10-K hyperscaler segment disclosures, and ISO/IEC 27001 certification registry data, underwrites the qualitative findings. Bottom-up deployment estimates triangulate against top-down infrastructure spending patterns.
Comparable-period anchoring to cloud infrastructure capex cycles and regulatory implementation timelines structures the projection horizon across deployment modes, solution offerings, end-user industries, and regional adoption patterns. CAGRs derive from segment-level elasticity modeling against concurrent authentication throughput requirements and encryption boundary cost curves. Model training workload intensity and EU AI Act high-risk system classification thresholds feed scenario-weighted outputs.
Caveats apply where zero-trust architecture skill scarcity delays enterprise deployments or where divergence between European ex-ante compliance and American sectoral enforcement patterns fragments multi-jurisdictional gateway specifications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
AI Search Engine Market