
 Asia-Pacific Generative AI Market | 2026-2036
Asia-Pacific Generative AI Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Generative AI Market Analytics
China's dual carbon goals and the EU AI Act's extraterritorial compliance pressure on multinational technology deployments is realigning procurement criteria across the Asia-Pacific. NVIDIA leverages its dominant position in AI training silicon to sustain premium pricing for data center accelerators. Baidu anchors its Ernie platform within domestic cloud ecosystems, while Samsung Electronics competes through on-device generative AI integration in consumer electronics.
Generative AI in the Asia-Pacific encompasses transformer-based neural architectures, diffusion models, and large language model systems that synthesize text, imagery, code, and multimodal outputs from probabilistic training on vast datasets. These systems operate through billions of parameters requiring specialized tensor processing units and high-bandwidth memory subsystems, serving industrial automation, creative production, and software engineering workflows. Natural Language Processing occupies the most mature revenue position among technology segments, while Image Synthesis commands expanding creative industry budgets. Cloud-Based deployment captures the dominant infrastructure share as hyperscalers extend platform services, though Edge Computing differentiates latency-sensitive manufacturing and autonomous systems applications.
China's MIIT governs algorithmic recommendation provisions and deep synthesis regulations that mandate content provenance labeling, while Japan's METI coordinates industrial AI standards through its AI Governance Guidelines. India's TRAI and BIS are developing data localization and AI system certification frameworks that will shape market access conditions. Stakeholders must monitor evolving cross-border data governance regimes and sovereign compute investments that will determine which national markets permit foreign platform participation.
Market Dynamics
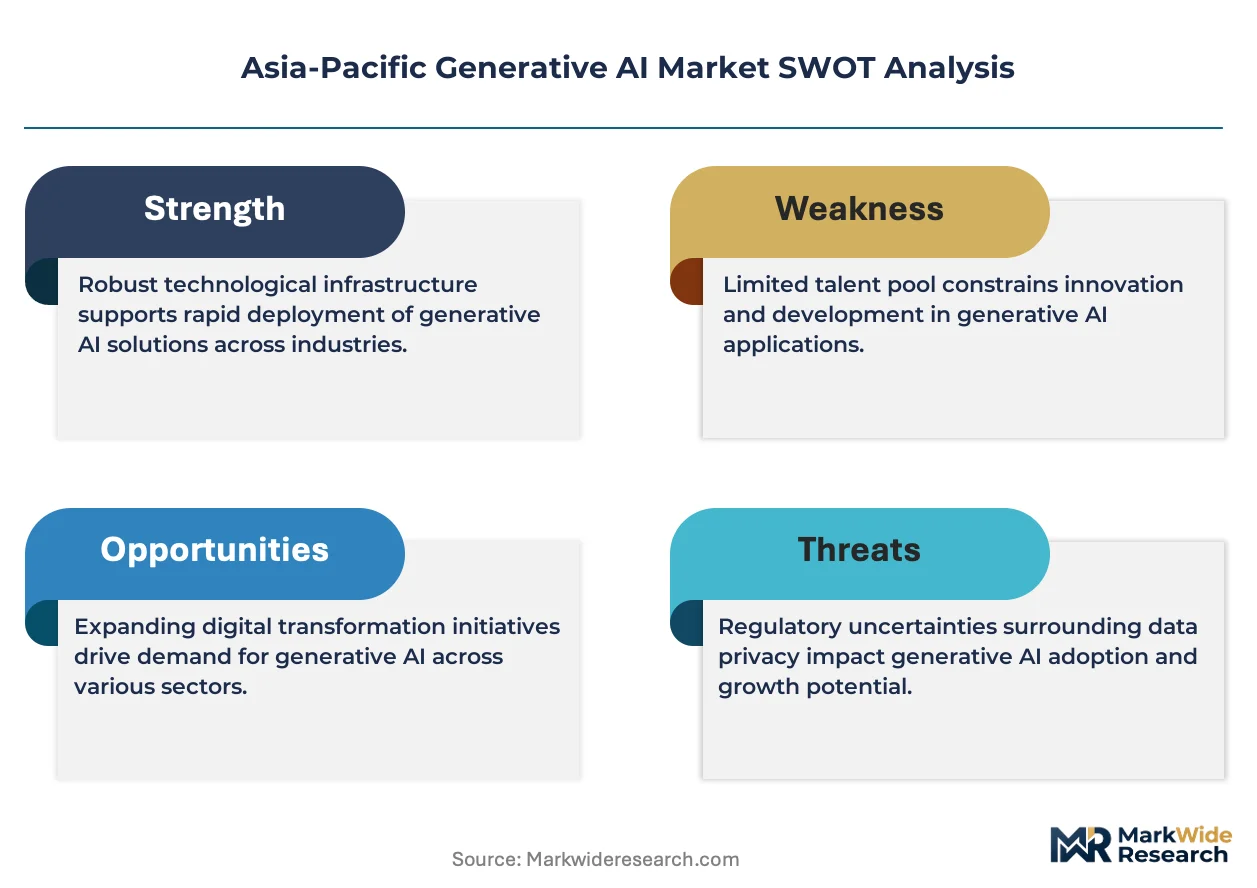
China's sovereign AI investments are redrawing compute infrastructure allocation across the Asia-Pacific, as domestic cloud platforms capture enterprise workloads previously routed through international hyperscalers. This reconfiguration is compressing foreign vendor access windows while accelerating localized model development.
Growth Catalysts
- MIIT Deep Synthesis Regulations:China's content provenance mandates are driving enterprise procurement of domestic generative AI platforms that embed compliant watermarking and traceability features.
- Financial Services Automation:Banks and insurers across Singapore, Hong Kong, and Sydney are deploying transformer-based document synthesis for contract analysis and regulatory reporting.
- Diffusion Model Proliferation:Creative industries in South Korea and Japan are integrating image synthesis tools into production pipelines for advertising and entertainment content.
Market Restraints
- High-Bandwidth Memory Supply Concentration:AI accelerator production remains constrained by HBM3E supply from Korean semiconductor fabricators, creating allocation bottlenecks for Chinese and Japanese data center operators.
- EU AI Act Extraterritorial Compliance:Multinational enterprises deploying generative AI across European and Asia-Pacific operations face dual certification burdens that extend procurement timelines.
- Tensor Processing Unit Cost Structure:Specialized AI training silicon commands premium pricing that restricts mid-market enterprise adoption in India and Southeast Asia.
Strategic Opportunities
- India's PLI Scheme for AI Hardware:Domestic manufacturing incentives are attracting assembly investment for edge inference devices serving agriculture and healthcare applications.
- On-Device Generative AI Convergence:Smartphone and automotive OEMs in South Korea and Japan are integrating quantized large language models directly into consumer electronics.
- Cross-Border Data Governance Gaps:Fragmented ASEAN data localization requirements create openings for compliant multi-jurisdictional AI service architectures.
Industry Challenges
- Transformer Architecture Specialist Scarcity:The region faces acute shortages of engineers capable of optimizing billion-parameter models for Mandarin, Japanese, and Korean linguistic structures.
- Legacy System Integration Complexity:Enterprises in Australia's mining and Japan's manufacturing sectors struggle to embed generative AI into decades-old operational technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Generative AI Market |
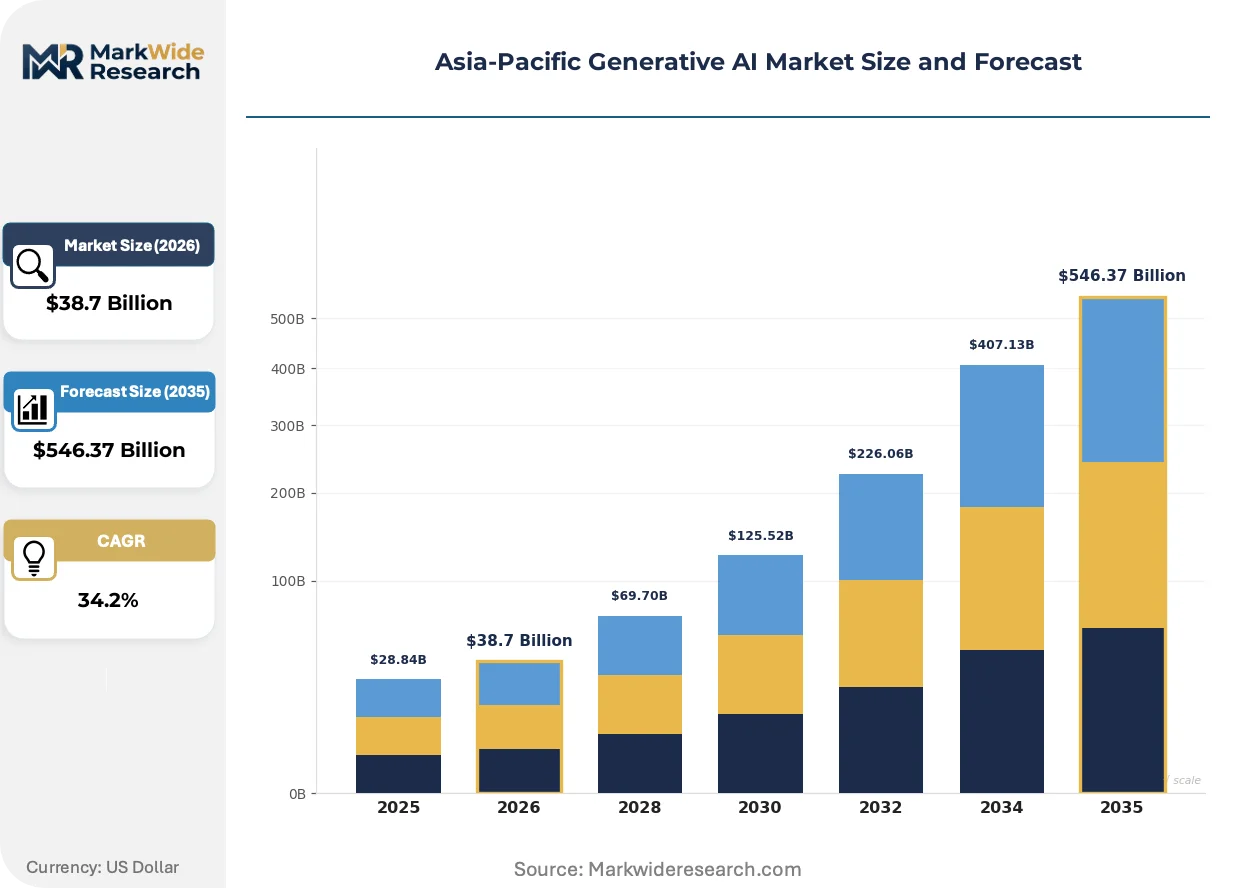
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $546.37 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
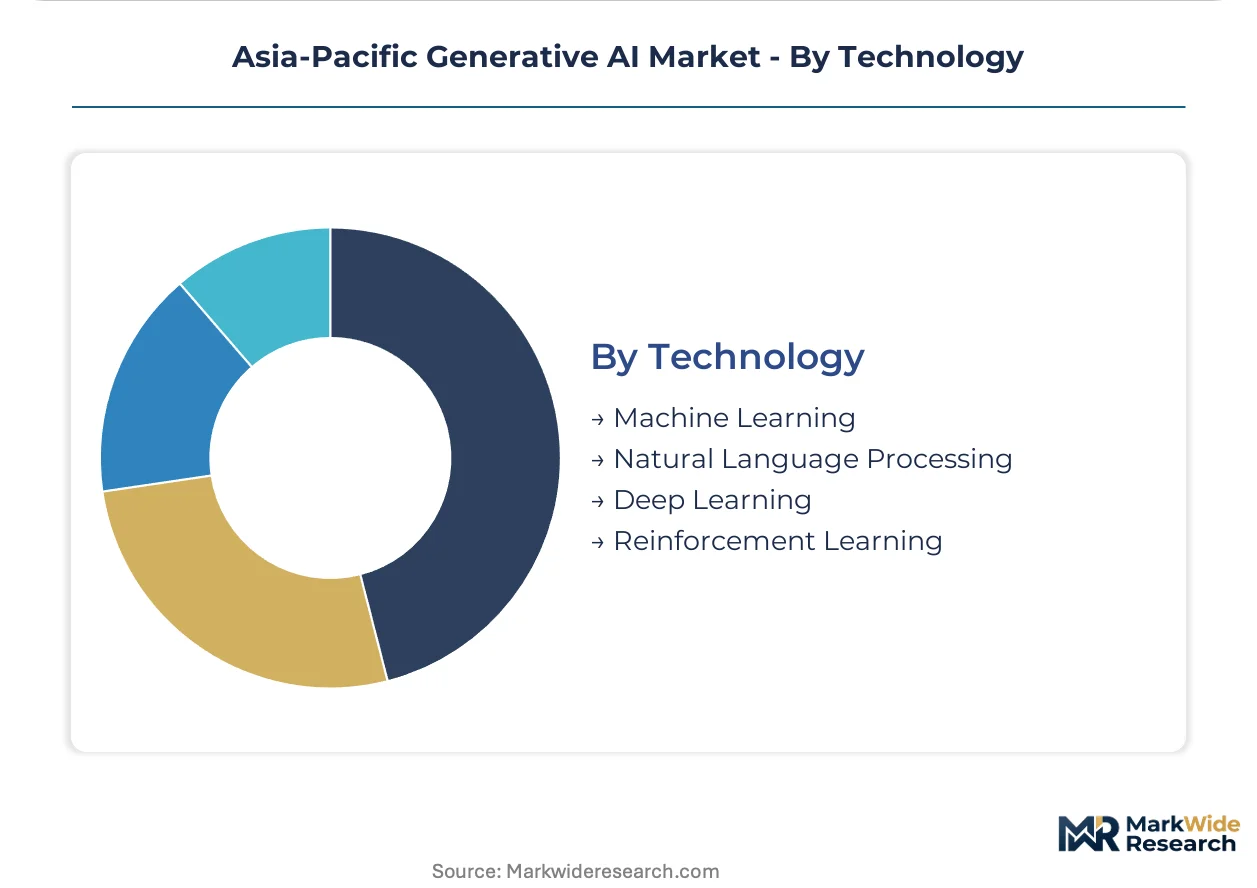
| Segmentation | Application: Content Generation, Image Synthesis, Data Augmentation, AI-Assisted Design End User: Enterprises, Startups, Educational Institutions, Research Organizations Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: Machine Learning, Natural Language Processing, Deep Learning, Reinforcement Learning |
| Companies Covered | Samsung Electronics, Baidu, Alibaba Cloud, Huawei, SenseTime, NVIDIA, Appier, Yellow.ai, Tata Consultancy Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Generative AI Market Evolving Landscape
Multimodal foundation models are compressing previously separate AI application categories into unified inference platforms, collapsing vendor fragmentation while raising the bar for specialized performance.
Retrieval-augmented generation architectures are automating enterprise knowledge management by grounding large language model outputs in proprietary document corpora. Japanese automotive suppliers and Australian legal services firms are deploying these systems to reduce hallucination rates in customer-facing applications. The technology is automating tier-one support and contract drafting functions that previously required dedicated analyst teams.
Japan's METI AI Governance Guidelines are mandating explainability documentation for high-risk industrial AI deployments, forcing model developers to retrofit interpretability layers into existing transformer architectures. Manufacturing automation vendors in Osaka and Nagoya are restructuring product roadmaps to accommodate human-in-the-loop validation requirements. Heavy industry adopters are delaying full autonomy projects pending compliance certification.
Enterprise software procurement in Singapore and Hong Kong is pivoting toward consumption-based API pricing for generative AI capabilities, displacing perpetual license models for content generation tools. Systems integrators are unbundling implementation services from platform subscriptions to capture margin from customization complexity. This pattern is most visible in financial services, where compliance-driven configuration requirements resist standardization.
Asia-Pacific Generative AI Market Segmentation
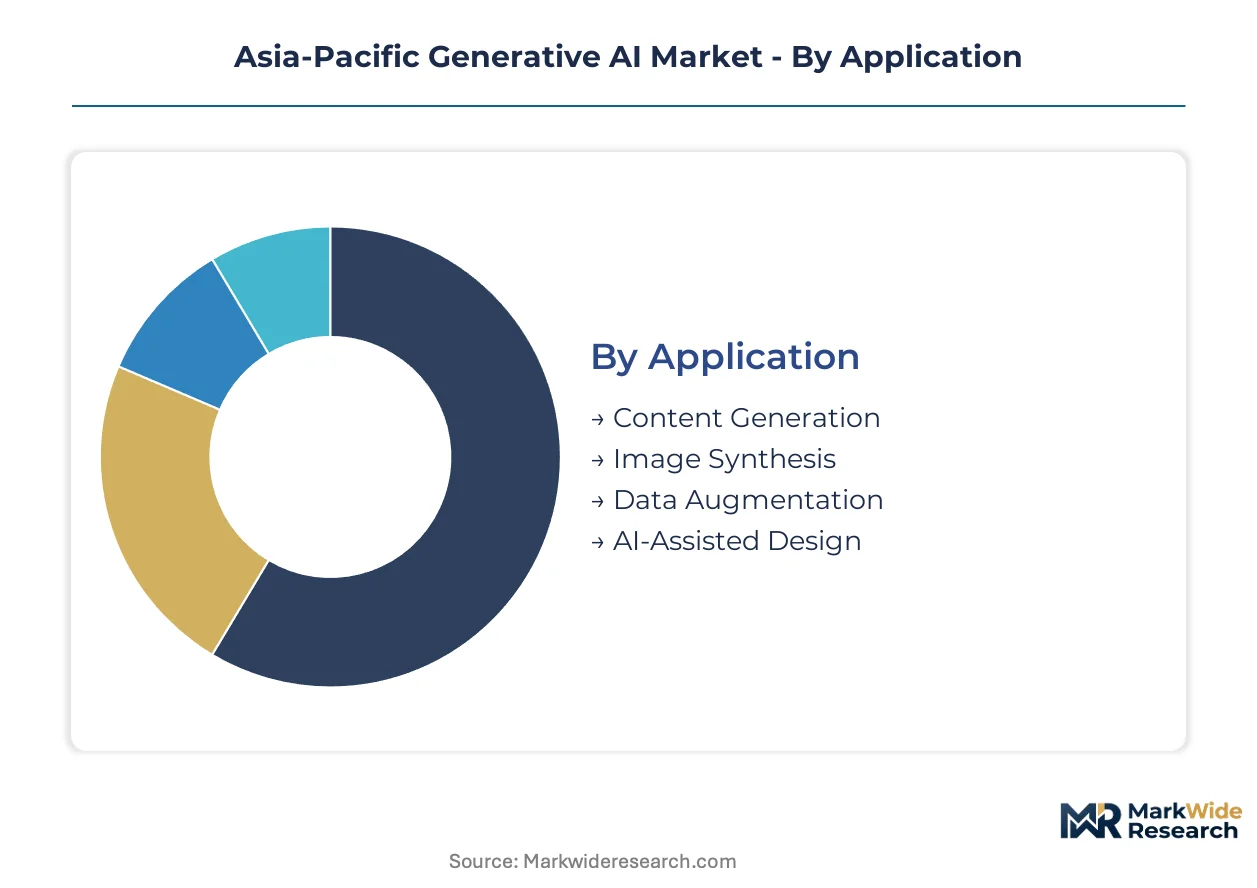
Asia-Pacific generative AI procurement patterns diverge sharply across deployment architectures and end-user sophistication. Technology buyers in China, Japan, and South Korea weight sovereign data control against latency requirements differently than their counterparts in Southeast Asia and Australia.
Application:
Transformer architectures and diffusion models define the functional boundaries between use cases, with compute intensity and output fidelity driving platform selection.
- Content Generation:Large language model systems synthesize marketing copy, code documentation, and multilingual communications across financial services and e-commerce operations in Singapore and Hong Kong. Banks in Sydney deploy these tools for regulatory filing preparation, though MIIT content provenance mandates in China restrict foreign platform usage.
- Image Synthesis:Diffusion-based generation pipelines serve advertising production and entertainment pre-visualization in Seoul and Tokyo. South Korean creative agencies integrate these tools into broadcast workflows, while Japanese gaming studios apply them for concept art acceleration.
- Data Augmentation:Synthetic training data generation supports computer vision model development for manufacturing quality control in Osaka and autonomous vehicle perception systems in Beijing.
- AI-Assisted Design:Generative CAD tools accelerate industrial prototyping for automotive suppliers in Nagoya and electronics manufacturers in Shenzhen.
Mature deployment sits with Content Generation. Newer deployment is concentrated in Image Synthesis.
End User:
Budget scale and compliance capability separate procurement tiers, with regulatory readiness determining platform access more than technical requirements.
- Enterprises:Multinational corporations in Singapore and Hong Kong operate dual-stack deployments to satisfy EU AI Act extraterritorial obligations alongside domestic Asian regulatory frameworks. These organizations command sufficient capital for dedicated infrastructure and specialized compliance staffing.
- Startups:Venture-backed firms in Bangalore and Jakarta consume API-based generative AI through cloud marketplaces, prioritizing speed-to-market over data sovereignty. India's PLI scheme for AI hardware is attracting domestic edge inference device assembly to serve this tier.
- Educational Institutions:Universities in Tokyo and Beijing deploy generative AI for research acceleration and curriculum development, with Chinese institutions restricted to domestic models under MIIT algorithmic recommendation provisions.
- Research Organizations:National laboratories in Tsukuba and Seoul pursue foundation model development with government funding, concentrating talent in transformer architecture optimization for Korean and Japanese linguistic structures.
Research Organizations anchor frontier model development. Startups represent the fastest-scaling consumption tier.
Deployment:
Infrastructure location determines latency, data residency compliance, and operational cost structure for Asia-Pacific implementations.
- Cloud-Based:Hyperscaler platforms from Alibaba Cloud and Baidu capture Chinese enterprise workloads previously routed through international providers. Financial services automation in Sydney and Singapore relies on these deployments for elastic compute scaling during peak regulatory reporting periods.
- On-Premises:Sovereign AI requirements in China's technology corridors and defense-adjacent applications in Japan and South Korea mandate captive infrastructure. High-bandwidth memory supply constraints from Korean fabricators limit accelerator allocation for these deployments.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud inference for non-critical workloads, common among Australian mining operators and Japanese automotive suppliers.
- Edge Computing:Quantized model deployment directly onto manufacturing equipment and autonomous systems addresses latency requirements in Osaka's industrial automation sector and Seoul's robotics clusters.
Cloud-Based infrastructure commands current investment volume. Edge Computing is climbing the fastest as on-device generative AI converges in consumer electronics.
Technology:
Algorithmic approach determines training cost, inference efficiency, and suitability for specific output modalities.
- Machine Learning:Classical supervised and unsupervised methods underpin recommendation systems and predictive maintenance in legacy industrial deployments across Australia's mining sector.
- Natural Language Processing:Transformer-based architectures with billions of parameters dominate text synthesis and semantic analysis, representing the most commercially mature revenue position in the region. Financial services in Hong Kong and Singapore deploy these systems for contract analysis and regulatory reporting automation.
- Deep Learning:Multi-layer neural networks enable image and video generation through diffusion and GAN architectures, with South Korean entertainment studios and Japanese advertising agencies driving creative industry budgets.
- Reinforcement Learning:Human feedback integration improves model alignment for customer-facing applications, with Japanese automotive suppliers deploying these techniques to reduce hallucination rates in tier-one support systems.
Natural Language Processing anchors current enterprise procurement. Reinforcement Learning is gaining share fastest as explainability requirements intensify under Japan's METI AI Governance Guidelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of regional compute capacity while South Korea and Taiwan supply critical memory and silicon components. Japan anchors industrial AI deployment. India and Southeast Asian markets scale consumption through cloud API adoption.
China
Domestic cloud platforms capture enterprise workloads previously routed through international hyperscalers under MIIT deep synthesis regulations. Beijing-Tianjin-Hebei and Yangtze River Delta technology corridors concentrate sovereign AI investments. Shanghai-based financial institutions deploy transformer-based document synthesis for regulatory reporting compliance.
Japan
Automotive suppliers and manufacturing automation vendors drive demand for explainable AI systems under METI governance guidelines. Osaka and Nagoya industrial clusters retrofit interpretability layers into existing transformer architectures. Heavy industry adopters delay full autonomy projects pending compliance certification.
South Korea
Creative industries in Seoul integrate diffusion-based image synthesis into broadcast and advertising production pipelines. Samsung Electronics competes through on-device generative AI integration in consumer electronics. Busan-Ulsan manufacturing clusters address high-bandwidth memory supply constraints for regional data center operators.
India
Venture-backed firms in Bangalore consume API-based generative AI through cloud marketplaces prioritizing speed-to-market. TRAI and BIS develop data localization and AI system certification frameworks. Domestic manufacturing incentives under the PLI scheme attract assembly investment for edge inference devices serving agriculture and healthcare.
Australia
Mining operators in Western Australia deploy hybrid architectures processing sensitive data locally while leveraging cloud inference. Sydney financial services automate contract analysis and regulatory filing preparation. Legacy operational technology stacks in extraction industries complicate generative AI integration timelines.
Asia-Pacific Generative AI Market Competitive Landscape
The competitive structure tilts toward hyperscaler-dominated platform provision. Domestic cloud operators capture sovereign workloads while international silicon vendors sustain premium positioning in training infrastructure. Three archetypes define the field: vertically integrated technology conglomerates, specialized AI chip designers, and cloud-native platform providers. Capacity expansion in domestic memory fabrication and strategic partnerships for model distribution dominate competitive maneuvering.
Among China-based technology conglomerates, Baidu and Alibaba Cloud occupy positions anchoring domestic cloud ecosystems. Samsung Electronics exemplifies the vertically integrated archetype competing through consumer electronics distribution. NVIDIA represents the specialized silicon tier sustaining premium accelerator pricing. These three entities illustrate how geographic origin and structural positioning shape competitive access to enterprise procurement budgets across divergent regulatory environments.
| Leading Market Players |
|---|
| Samsung Electronics |
| Baidu |
| Alibaba Cloud |
| Huawei |
| SenseTime |
| NVIDIA |
| Appier |
| Yellow.ai |
| Tata Consultancy Services |
| Others |
Value Network & Pricing Analysis
Chinese financial services institutions and state-backed enterprises anchor procurement volume, concentrating negotiating power with domestic cloud platforms that embed MIIT-compliant watermarking into subscription tiers. This buyer concentration compresses foreign vendor margins while elevating premium pricing for sovereign-certified infrastructure.
Pricing Analysis
Cost-down pressure on mid-market deployments accelerates because tensor processing unit premiums restrict access for Indian and Southeast Asian enterprises. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler platform subscriptions from on-premises perpetual licenses and API consumption models. Price differentiation traces to certification grade under Japan's METI guidelines and volume scale commitments to Alibaba Cloud or Baidu. Startups in Bangalore exhibit highest price sensitivity; multinational banks in Singapore demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from Japanese automotive suppliers and Australian mining operators mandate qualified allocation from both Korean HBM3E fabricators and domestic memory assembly under India's PLI scheme. Geographic supply concentration centers on Taiwan for advanced logic silicon, South Korea for high-bandwidth memory, and China for mature node packaging. Raw material dependencies include specialized photoresists, rare earth substrates for laser annealing, and cobalt-based interconnect metals. Single-source vulnerability in Korean HBM3E output creates allocation bottlenecks for Chinese data center expansion. Distribution runs through direct hyperscaler procurement for cloud deployments and systems integrator channels for hybrid on-premises implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation favors hyperscalers and silicon specialists with captive supply chains, as MIIT content provenance mandates and HBM allocation constraints force smaller platform vendors toward acquisition or exit.
For Market Incumbents: Anticipate regulatory fragmentation by pre-certifying architectures under Japan's METI explainability requirements and China's deep synthesis provisions simultaneously. Defend position through backward integration into high-bandwidth memory supply via strategic partnerships with Korean fabricators. Prioritize edge inference optimization for automotive and manufacturing verticals where latency requirements resist pure cloud displacement. For New Entrants and Emerging Players: The premium-to-economy price gap in on-device generative AI creates entry opportunity for quantized model specialists serving South Korean smartphone OEMs and Japanese robotics manufacturers. White-space concentration sits with agricultural automation in India and healthcare diagnostics at the district hospital tier. Target API-based consumption in Jakarta and Manila through cloud marketplace listings that bypass sovereign infrastructure requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor transformer architecture teams with Mandarin or Korean linguistic optimization expertise in Beijing and Seoul technology corridors. Long-term viability hinges on regulatory compliance capability rather than raw model scale. Monitor MIIT algorithmic recommendation enforcement intensity as inflection indicator for foreign platform access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Ernie or Tongyi Qianwen into Alibaba Cloud enterprise stacks captures MIIT-compliant procurement. |
| Acquisition of Specialist Firm | Absorbing Korean transformer optimization teams addresses METI explainability retrofit requirements. |
| Geographic Expansion | Establishing edge inference assembly in India under PLI incentives serves agricultural automation demand. |
| Strategic Partnership | Alliances with Samsung Electronics distribute quantized models through consumer electronics channels. |
| Product Launch | Retrieval-augmented generation platforms reduce hallucination rates for Tokyo legal services firms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cloud platform engineers, enterprise IT procurement officers, semiconductor supply chain managers, and compliance consultants at financial institutions in Singapore and Hong Kong validated demand-side assumptions. Secondary sources included MIIT algorithmic recommendation filings, METI AI Governance Guidelines documentation, hyperscaler capex disclosures, and import records for AI accelerator hardware. Bottom-up enterprise deployment estimates triangulated against top-down infrastructure investment flows across the analysis window.
Data-stream reconciliation across deployment model, end-user sophistication tier, technology segment, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure capacity expansion schedules. Forecast inputs incorporated sovereign AI investment commitments from China's technology corridors and high-bandwidth memory supply allocation forecasts from Korean fabricators.
Inputs from regulatory agencies and hyperscaler disclosure filings were available through the study window; gaps in private cloud deployment metrics at Chinese state-owned enterprises introduce uncertainty bands around on-premises infrastructure estimates. Deviation in HBM3E supply allocation or MIIT enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Artificial Intelligence Based Personalization Market
Artificial Intelligence (AI)
Edge AI Market