
 Japan Edge AI Market | 2026-2036
Japan Edge AI Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Edge AI Market Insights
OEM-direct procurement is tilting toward specialized silicon vendors in the Japan Edge AI landscape. NVIDIA Corporation leverages its CUDA ecosystem to anchor high-performance inference deployments across automotive tier-1s. Preferred Networks, Inc. competes through in-house processor design tied to robotics and factory automation. Fujitsu Limited sustains enterprise channel control via its Fugaku-derived edge architectures and domestic systems integrator relationships.
Edge AI denotes neural network inference executed on localized compute nodes rather than centralized cloud infrastructure, typically requiring sub-10 millisecond latency and thermal envelopes below 15 watts for industrial deployment. Its primary purpose centers on real-time decision autonomy for mission-critical physical systems. Hardware dominates installed value owing to custom ASIC and FPGA requirements for power-constrained environments, while machine learning tooling captures expanding margin pools as Japanese manufacturers seek retrainable models without cloud dependency. Computer vision leads application deployment in factory inspection and autonomous logistics.
METI, PMDA, and JIS standards collectively shape Japan Edge AI product certification, data handling protocols, and interoperability benchmarks for healthcare and industrial endpoints. METI's semiconductor subsidy frameworks directly steer domestic foundry capacity toward edge-optimized nodes, tightening market access for non-compliant foreign platforms. Stakeholders must monitor evolving JIS cybersecurity mandates and METI supply-chain reshoring incentives to calibrate localization investments against export-restricted process technologies.
Market Dynamics
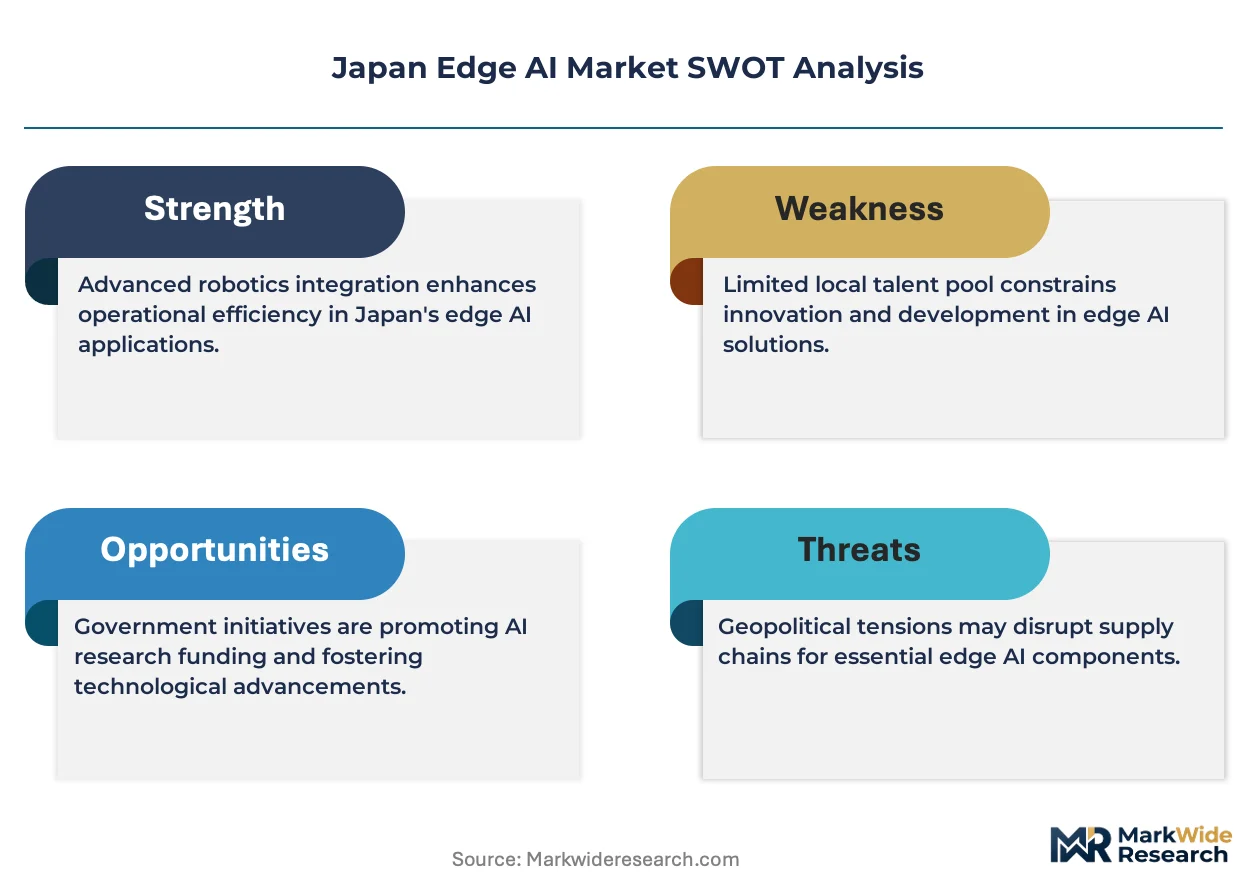
Domestic semiconductor reshoring under METI's subsidy frameworks is compressing supply timelines for edge-optimized ASICs while locking out non-compliant foreign silicon vendors from automotive and robotics procurement channels.
Growth Catalysts
- Smart manufacturing retrofit mandates:Osaka and Nagoya factory clusters deploy predictive maintenance systems requiring sub-10 millisecond inference latency, pulling specialized edge hardware into production lines.
- METI Society 5.0 semiconductor roadmap:Direct capital allocation to domestic foundry capacity for 22nm and 12nm edge-optimized nodes accelerates local chip design and data sovereignty compliance.
- Automotive tier-1 integration requirements:Real-time analytics for autonomous logistics and quality inspection drive neural network inference at the factory edge without cloud dependency.
Market Restraints
- Wafer supply concentration:Domestic foundry capacity for power-constrained 15-watt thermal envelopes remains concentrated in legacy node transitions, creating allocation bottlenecks for custom ASIC tape-outs.
- JIS cybersecurity certification timelines:Evolving industrial endpoint security mandates extend product validation cycles by 8-14 months for foreign platform vendors seeking market access.
- FPGA cost structure:Field-programmable gate arrays for retrainable factory models carry 3-4x unit economics penalty versus fixed-function ASICs at volume deployment scales.
Strategic Opportunities
- Kyushu-Tokyo corridor underpenetration:Semiconductor packaging and test facilities in Kyushu lack localized edge AI software tooling, creating channel openings for machine learning platform vendors.
- PMDA medical device edge inference:Regulatory pathways for on-device diagnostic AI in imaging equipment create certification-driven demand for 5-watt neural accelerators in healthcare OEM supply chains.
- Digital twin convergence with edge inference:Factory automation buyers seek unified architectures where physical asset monitoring feeds directly into simulation models without cloud round-trips.
Industry Challenges
- Embedded systems firmware talent scarcity:Domestic universities produce insufficient engineers fluent in both neural network optimization and real-time operating systems for 15-watt thermal constraints.
- Legacy MES integration complexity:Manufacturing execution systems from the 1990s lack API-native architectures, forcing custom middleware development for edge AI data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Edge AI Market |
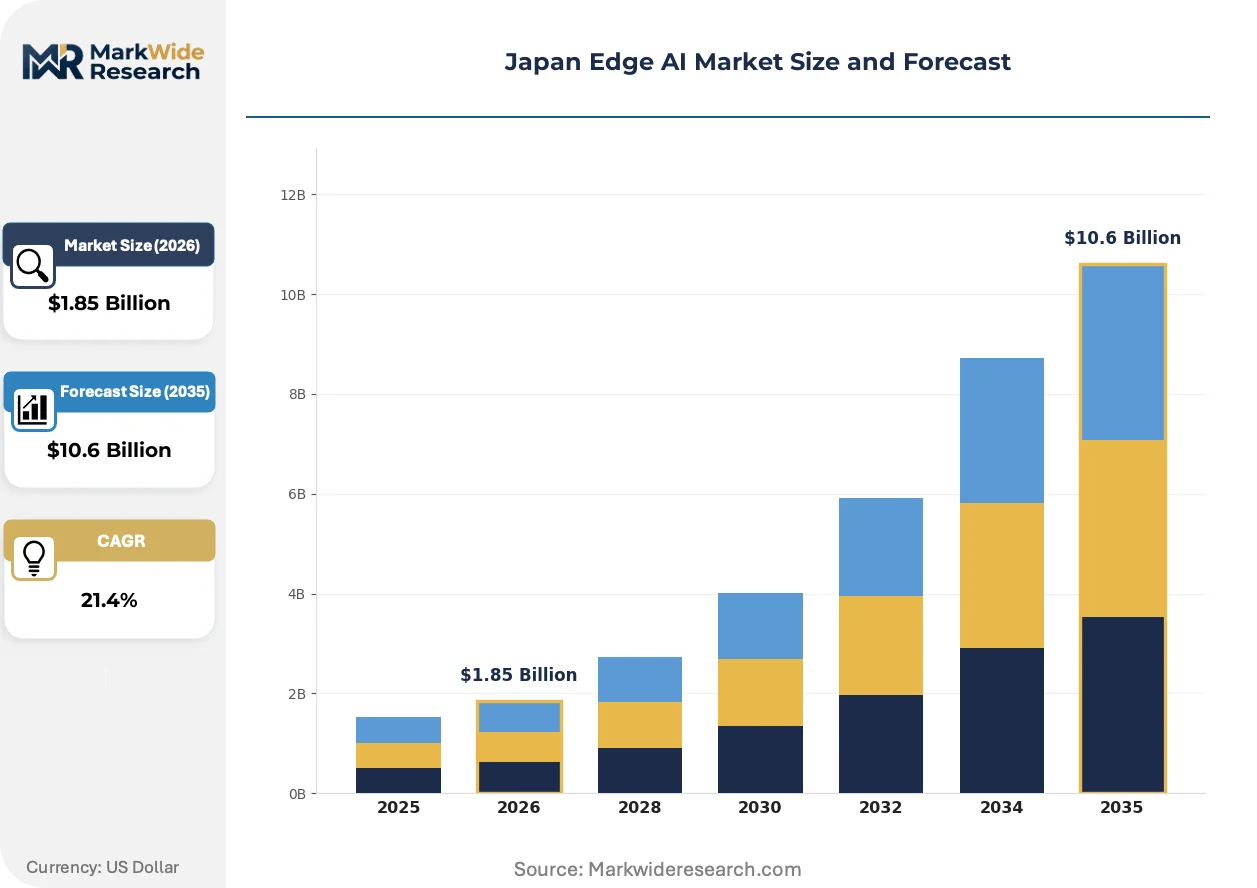
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Platform Technology: Machine Learning, Deep Learning, Computer Vision, Natural Language Processing End User: Manufacturing, Healthcare, Retail, Transportation Application: Predictive Maintenance, Smart Surveillance, Autonomous Vehicles, Real-Time Analytics |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Qualcomm Technologies Inc., Preferred Networks, Inc., Fujitsu Limited, NEC Corporation, Sony Group Corporation, NTT Data Corporation, EdgeCortix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Edge AI Market Trends and Innovations
Neural architecture search automation and domestic foundry process node maturation are compressing the traditional 18-month edge silicon development cycle while tightening vendor lock-in around proprietary toolchains.
Structured pruning and quantization algorithms are collapsing the gap between cloud-trained model accuracy and edge-deployable inference performance. Automotive tier-1 suppliers in Aichi Prefecture now demand 95%+ accuracy retention at under 8-bit precision for vision inspection pipelines. This compression is eliminating the historical trade-off between model complexity and thermal envelope compliance in factory robotics.
METI's Data Free Flow with Trust framework and JIS X 8341 accessibility mandates are reshaping product certification requirements for industrial edge endpoints. Domestic OEMs must demonstrate on-device data residency and interoperable API standards to qualify for subsidy-backed procurement programs. Healthcare robotics manufacturers face the steepest compliance ramp as PMDA device registration converges with cybersecurity attestation requirements.
Buyer consolidation among Japanese automotive keiretsu is shortening vendor qualification cycles from 24 months to 14 months while raising the technical bar for direct silicon procurement. Tier-1 suppliers now require proof-of-concept deployments in Nagoya or Osaka factory environments before contract award, displacing traditional reference architecture sales. This behavioral shift favors vendors with captive systems integrator relationships and domestic field engineering presence.
Japan Edge AI Market Segmentation
Edge AI deployment in Japan fragments across four intersecting dimensions that determine procurement priorities and vendor qualification pathways. Product type and technology choices lock in thermal envelope constraints and data sovereignty compliance, while end-user verticals and applications dictate latency requirements and regulatory exposure.
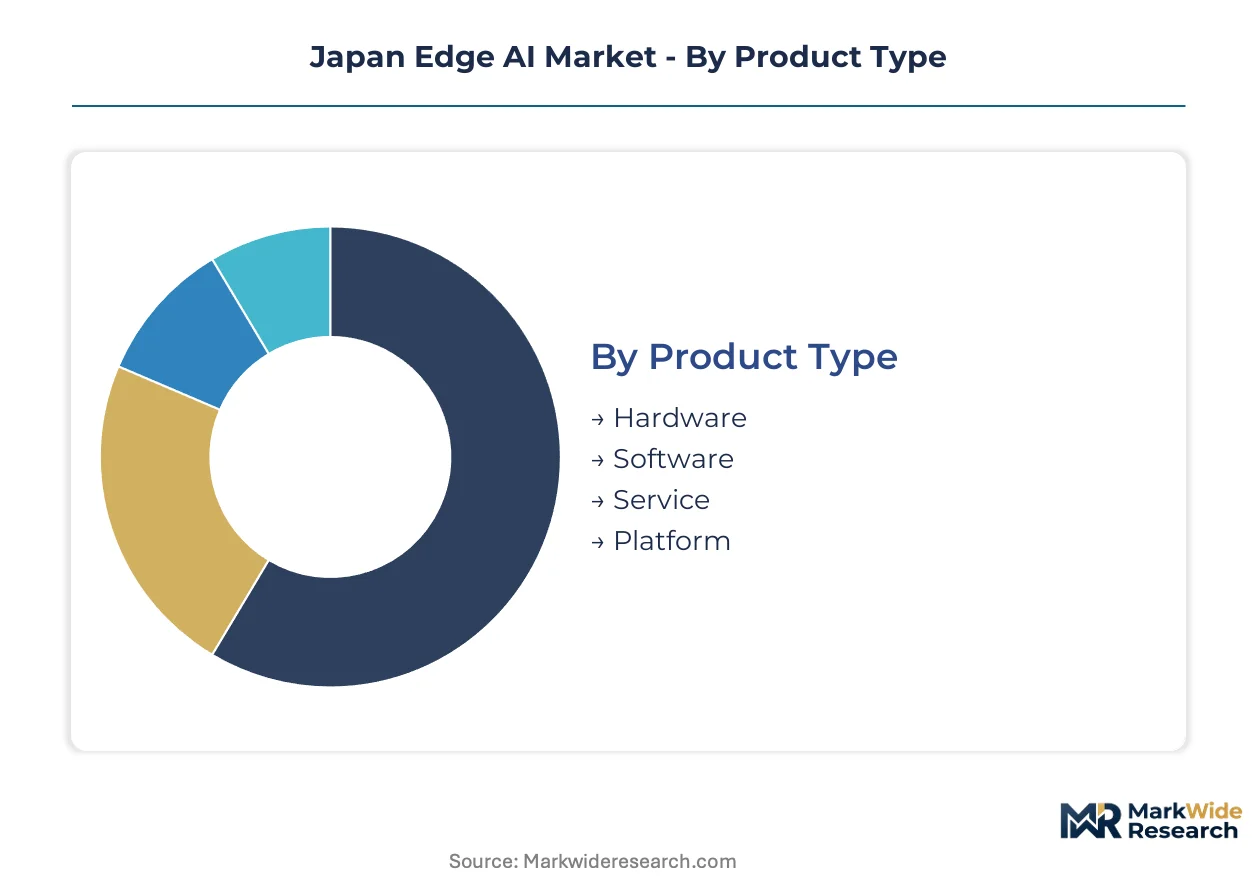
Product Type:
Mature hardware categories dominate installed value, though software and platform layers capture expanding margin pools as manufacturers seek retrainable models without cloud dependency.
- Hardware:Custom ASICs and FPGAs for power-constrained environments constitute the foundational spend layer. Osaka and Nagoya factory clusters drive demand for sub-15-watt neural accelerators in predictive maintenance deployments. Thermal envelope compliance and METI semiconductor subsidy eligibility filter vendor access.
- Software:Machine learning toolchains enabling on-device model optimization and quantization are gaining procurement priority. Automotive tier-1s in Aichi Prefecture require 8-bit precision pipelines with 95%+ accuracy retention for vision inspection systems. JIS cybersecurity certification timelines extend validation cycles for foreign platform vendors.
- Service:Systems integration and field engineering support for legacy MES integration commands premium pricing.
- Platform:Unified edge-to-cloud orchestration layers with data residency guarantees attract healthcare robotics manufacturers facing PMDA device registration requirements.
Hardware retains volume leadership; platform solutions hold the steepest expansion curve.
Technology:
Cost tier stratification separates established inference methods from emerging modalities requiring specialized silicon investment.
- Machine Learning:Structured pruning and quantization algorithms compress cloud-trained models for edge deployment. Factory automation buyers in Kyushu-Tokyo corridor demand retrainable frameworks without cloud round-trips.
- Deep Learning:Neural architecture search automation accelerates silicon development cycles while tightening vendor lock-in around proprietary toolchains. METI's domestic foundry subsidies steer tape-out capacity toward edge-optimized nodes.
- Computer Vision:Real-time inference for quality inspection and autonomous logistics dominates automotive and robotics procurement. Sub-10-millisecond latency requirements eliminate cloud-dependent architectures.
- Natural Language Processing:On-device diagnostic AI in medical imaging equipment creates certification-driven demand for 5-watt accelerators under PMDA pathways.
Computer vision commands the largest deployment base; natural language processing shows the most rapid adoption acceleration in healthcare endpoints.
End User:
Application intensity varies sharply across verticals, with manufacturing and healthcare presenting divergent regulatory and latency profiles.
- Manufacturing:Smart manufacturing retrofit mandates in Osaka and Nagoya pull specialized edge hardware into production lines. Predictive maintenance systems require sub-10-millisecond inference latency with 15-watt thermal compliance.
- Healthcare:PMDA medical device edge inference regulations create certification-driven procurement for diagnostic AI in imaging equipment. Data residency requirements under METI's Data Free Flow with Trust framework constrain vendor selection.
- Retail:Smart surveillance and inventory analytics drive moderate-volume deployments with less stringent thermal constraints.
- Transportation:Autonomous logistics systems in factory environments demand real-time decision autonomy without cloud dependency.
Manufacturing anchors current deployment volume; healthcare presents the most demanding compliance ramp and margin expansion potential.
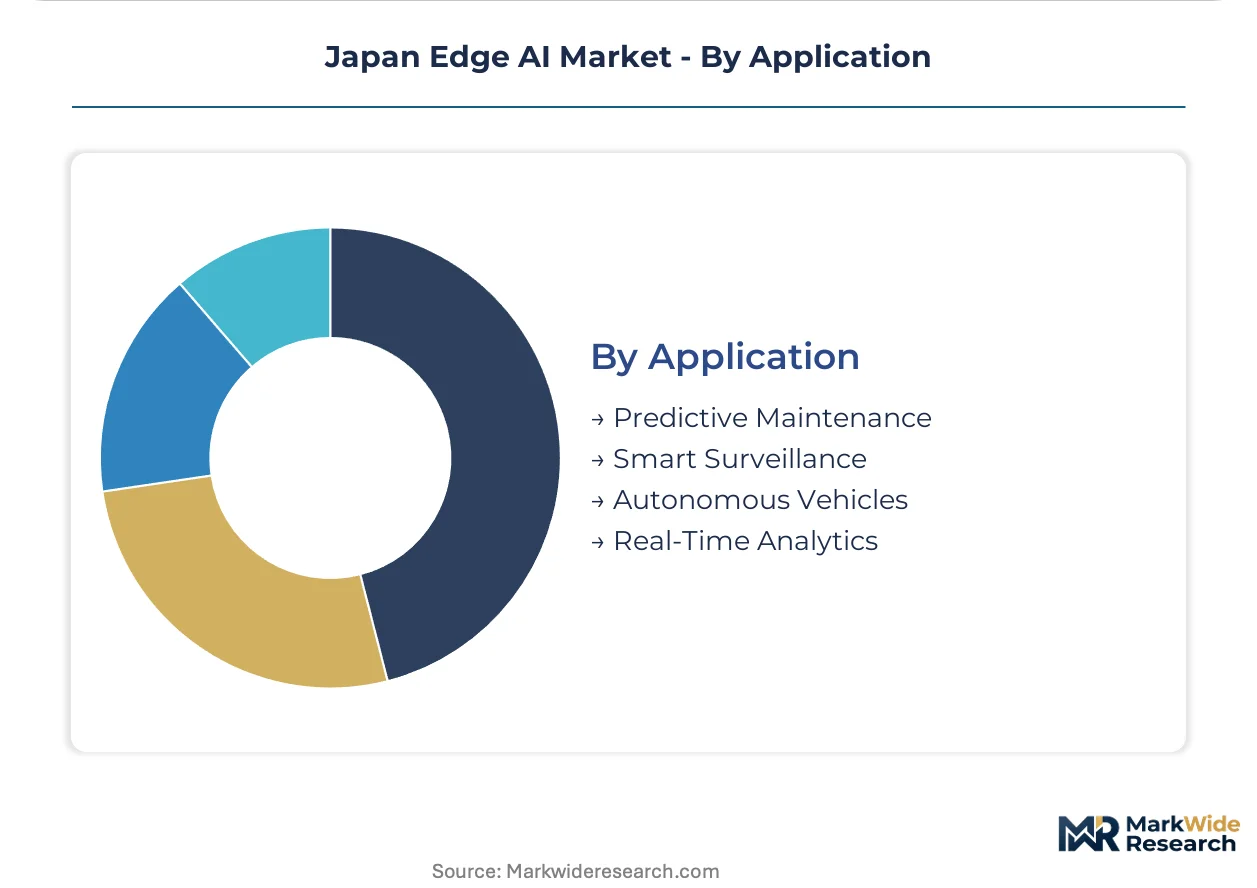
Application:
Customer type segmentation separates mission-critical physical systems from monitoring and analytics workloads with tolerance for higher latency.
- Predictive Maintenance:Real-time equipment monitoring in Osaka and Nagoya factory clusters drives the largest hardware procurement volumes. Legacy MES integration complexity forces custom middleware development for data ingestion.
- Smart Surveillance:Factory inspection and security applications deploy computer vision at scale with moderate thermal constraints.
- Autonomous Vehicles:Factory logistics and material handling systems require neural network inference with sub-10-millisecond latency guarantees.
- Real-Time Analytics:Digital twin convergence with edge inference enables unified architectures where physical asset monitoring feeds simulation models without cloud round-trips.
Predictive maintenance retains the deepest installed base; real-time analytics demonstrates the strongest convergence momentum with digital twin investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Kanto/Tokyo outstrips Kyushu by roughly 40% for equivalent edge AI deployments, reflecting the capital region's concentration of automotive keiretsu headquarters and METI subsidy administration.
Kanto/Tokyo
Automotive tier-1 suppliers and robotics OEMs drive premium procurement volumes. METI's Society 5.0 semiconductor roadmap channels direct capital allocation to domestic foundry capacity. Yokohama and Kawasaki industrial corridors anchor high-performance inference deployments for factory automation.
Kansai/Osaka
Smart manufacturing retrofit mandates pull specialized edge hardware into legacy production lines. JIS cybersecurity certification timelines extend validation cycles for foreign platform vendors. Osaka factory clusters demand sub-10 millisecond inference latency for predictive maintenance systems.
Chubu/Nagoya
Aichi Prefecture automotive suppliers require 95%+ accuracy retention at under 8-bit precision for vision inspection pipelines. PMDA medical device regulations create certification-driven demand for 5-watt neural accelerators. Toyota-supplier keiretsu dominate procurement channels.
Kyushu
Semiconductor packaging and test facilities lack localized edge AI software tooling, creating channel openings for machine learning platform vendors. Domestic foundry capacity for power-constrained thermal envelopes remains concentrated in legacy node transitions. Fukuoka and Kumamoto fabrication sites drive ASIC tape-out demand.
Tohoku
Sendai-based precision equipment manufacturers deploy edge inference for quality inspection with moderate thermal constraints. METI supply-chain reshoring incentives steer localization investments toward regional industrial parks. Legacy MES integration complexity forces custom middleware development.
Japan Edge AI Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower but defensible positioning. The vendor base stratifies across three layers: silicon architects with captive foundry relationships, software toolchain vendors with quantization expertise, and systems integrators bridging legacy MES architectures. Two dominant competitive moves define current dynamics: domestic semiconductor reshoring partnerships locking in METI subsidy eligibility, and vertical integration into edge-optimized ASIC design to escape FPGA cost penalties.
Within the domestic silicon tier, Preferred Networks, Inc. and Fujitsu Limited occupy positions shaped by METI's domestic foundry subsidies and keiretsu procurement channels. NVIDIA Corporation anchors the foreign platform vector through CUDA ecosystem penetration. These three exemplify divergent responses to JIS cybersecurity mandates and thermal envelope requirements.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Qualcomm Technologies Inc. |
| Preferred Networks, Inc. |
| Fujitsu Limited |
| NEC Corporation |
| Sony Group Corporation |
| NTT Data Corporation |
| EdgeCortix |
| Others |
Pricing and Supply Chain Analysis
Kyushu's semiconductor packaging clusters anchor domestic wafer supply for edge-optimized ASICs, concentrating foundry capacity allocation power among METI-subsidized domestic vendors and compressing margin capture for foreign platform suppliers lacking compliant tape-out partnerships.
Pricing Analysis
Configured-to-order pricing for custom neural accelerators commands 40-60% premiums over standard FPGA modules in Japanese automotive procurement. Three-tier pricing structure across premium ASIC, standard FPGA, and economy merchant silicon levels stratifies by thermal envelope compliance and JIS cybersecurity certification tier. Pricing pressure stems from METI's domestic foundry subsidies tilting procurement toward local silicon vendors with cost-competitive 22nm and 12nm nodes. Tier-1 automotive suppliers in Aichi Prefecture exhibit lowest price sensitivity due to keiretsu loyalty obligations, while mid-tier factory automation buyers in Kyushu demonstrate highest elasticity.
Supply Chain Analysis
Silicon feedstock for Japanese edge AI hardware draws from Taiwan, South Korea, and domestic Kyushu foundry capacity, with advanced packaging materials sourced from specialized chemical suppliers in Osaka and Yokohama. Wafer supply, thermal substrate components, and neural accelerator IP cores constitute critical input dependencies. Single-source vulnerability concentrates in legacy node transitions for 15-watt thermal envelope devices, where domestic foundry allocation bottlenecks threaten ASIC tape-out timelines. Distribution runs through captive systems integrator relationships and direct OEM procurement channels, with METI subsidy eligibility filtering vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated automotive keiretsu and smart manufacturing clusters in Osaka and Nagoya, shortening vendor qualification cycles while raising technical barriers for market access.
For Market Incumbents: Build certification moats around JIS cybersecurity attestation and PMDA medical device pathways to lock out foreign platform competitors. Deepen captive foundry relationships with METI-subsidized domestic nodes to secure allocation priority during wafer supply crunches. Acquire embedded systems firmware talent scarce in domestic universities to defend against emerging silicon vendors with integrated software stacks. For New Entrants and Emerging Players: Build out machine learning tooling presence in Kyushu's underpenetrated packaging corridor, where semiconductor test facilities lack localized edge AI software capabilities. Target healthcare robotics OEMs facing PMDA diagnostic AI compliance ramps as the most penetrable vertical entry point. Pursue proof-of-concept deployments in Nagoya factory environments to satisfy tier-1 supplier qualification requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors with unified edge-to-cloud orchestration layers and data residency guarantees. Long-term viability favors acquisition targets with proprietary quantization toolchains and domestic systems integrator relationships rather than pure-play hardware vendors. Watch for inflection when METI's Society 5.0 semiconductor roadmap accelerates domestic foundry node maturation beyond 12nm.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Partnership | Secures METI subsidy eligibility and wafer allocation priority for automotive tier-1 supply chains. |
| JIS Cybersecurity Certification | Unlocks procurement channels in Osaka and Nagoya smart manufacturing retrofit programs. |
| Quantization Toolchain Development | Captures margin expansion as Aichi Prefecture suppliers demand 8-bit precision pipelines. |
| Healthcare Robotics Platform Integration | Addresses PMDA medical device edge inference requirements for diagnostic AI imaging equipment. |
| Legacy MES Middleware Acquisition | Overcomes integration complexity blocking edge AI data ingestion in 1990s manufacturing execution systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with edge AI silicon architects, automotive tier-1 procurement officers, factory automation engineers, and METI policy specialists; and secondary validation through METI semiconductor subsidy disclosures, JIS standard certification databases, PMDA medical device registration filings, and domestic foundry capacity announcements. Bottom-up triangulation across hardware shipment estimates and top-down reconciliation against METI's Society 5.0 investment frameworks anchored value projections.
Forecast inputs spanned product type segmentation across hardware, software, service, and platform layers; technology tiers from machine learning through computer vision and natural language processing; and end-user verticals including manufacturing, healthcare, retail, and transportation. CAGRs were derived from weighted regression across adoption intensity curves and subsidy-driven procurement timelines. Industry-specific inputs included thermal envelope compliance thresholds, JIS cybersecurity certification cycle durations, and keiretsu vendor qualification behavioral shifts.
Stress conditions across wafer supply allocation bottlenecks, METI subsidy policy revisions, and PMDA regulatory pathway extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about domestic foundry node maturation and automotive keiretsu procurement consolidation. Cross-checking against METI's published semiconductor investment disbursements and tier-1 supplier capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Global Conversational Systems Market