
 Italy OTC Drugs Market | 2026-2036
Italy OTC Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Italy OTC Drugs Market Foresight
Self-medication among Italy's aging population is consolidating demand around trusted pharmacy channels and familiar brands. Bayer AG leverages its heritage analgesic portfolio to sustain shelf dominance across Italian farmacie. Angelini Pharma anchors its position through specialized gastrointestinal and pediatric formulations tailored to local prescribing habits.
Over-the-counter drugs comprise non-prescription pharmaceutical preparations regulated for direct consumer purchase without physician authorization, typically standardized to defined active-ingredient concentrations and stability profiles for self-administered symptom relief. Analgesics and cold medicines occupy the largest revenue pools given their high purchase frequency and brand loyalty, while online distribution channels represent the fastest-expanding access point as digital pharmacy platforms gain regulatory acceptance. Tablet and capsule formulations lead volume due to manufacturing scalability and consumer convenience, though liquid formats retain importance in pediatric and senior customer segments where swallowing difficulties drive preference.
AIFA, Italy's national pharmaceutical regulator, governs OTC classification switches and advertising standards, while Ministry of Health decrees align with EU-wide MDR and F-Gas Regulation requirements for product safety and environmental compliance. These frameworks shape market access timelines and formulation choices, particularly for inhalant and aerosol cold remedies. Stakeholders must monitor AIFA's reclassification pipeline and evolving e-pharmacy enforcement to anticipate portfolio expansion opportunities and channel strategy adjustments.
Market Dynamics
AIFA's accelerated reclassification procedures are compressing time-to-market for prescription-to-OTC switches, while pharmacy chains simultaneously expand self-care footprints to capture preventive health spending from Italy's aging demographic.
Growth Catalysts
- Regulatory Streamlining:AIFA's simplified switch protocols reduce approval timelines for analgesic and respiratory reclassifications, enabling faster portfolio expansion by domestic manufacturers.
- Channel Density:Lombardy and Veneto's concentrated pharmacy networks support premium OTC penetration through personalized pharmacist recommendations and immediate product access.
- Preventive Health Pivot:Italian consumers aged 55-plus increasingly self-manage chronic conditions with vitamins, supplements, and gastrointestinal remedies before physician consultation.
Market Restraints
- Active Ingredient Concentration Limits:EU MDR stability requirements constrain formulation innovation for combination cold remedies and multi-symptom analgesics.
- Pharmacy Channel Dependency:Italy's restrictive e-pharmacy enforcement under AIFA guidelines limits direct-to-consumer growth and caps price transparency.
- Generic Substitution Pressure:Unbranded ibuprofen and paracetamol alternatives erode margin pools in high-volume analgesic categories.
Strategic Opportunities
- Underpenetrated South:Calabria, Sicily, and Puglia present whitespace for pharmacy chain expansion and targeted pediatric formulation launches.
- Digital Pharmacy Integration:Regulatory acceptance of verified e-pharmacy platforms enables click-and-collect models and subscription-based chronic care management.
- Pediatric Liquid Formats:Swallowing difficulties among Italy's senior population and children drive demand for palatable, dose-precise liquid alternatives to tablets.
Industry Challenges
- Pharmacist Training Gaps:Expanded self-care sections require retraining 25,000-plus Italian farmacie staff on preventive counseling and cross-selling protocols.
- Legacy IT Integration:Independent pharmacies struggle to connect inventory systems with emerging e-pharmacy verification platforms mandated by AIFA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy OTC Drugs Market |
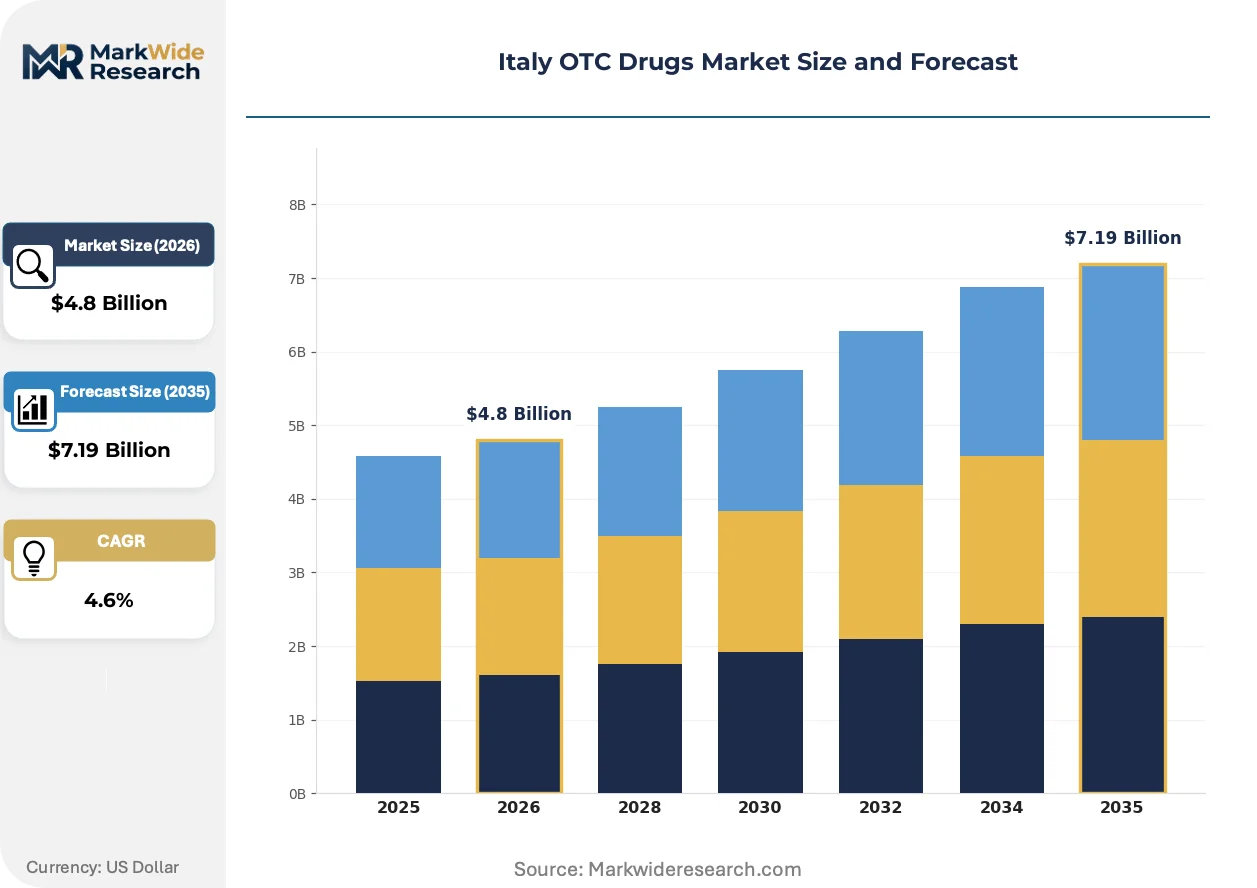
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Cold & Cough Medicines, Gastrointestinal Drugs, Vitamins Distribution Channel: Pharmacy, Supermarket, Online, Health Stores Customer Type: Adults, Children, Seniors, Pregnant Women Formulation: Tablets, Capsules, Liquids, Ointments |
| Companies Covered | Pfizer Inc, Reckitt Benckiser Group plc, Bayer AG, Angelini Pharma, Novartis AG, GlaxoSmithKline plc, Sanofi, Boehringer Ingelheim GmbH, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy OTC Drugs Market Shifts & Advancements
Digital pharmacy infrastructure and formulation science are converging to reshape how Italian consumers access and administer non-prescription therapies, with regulatory adaptation lagging slightly behind technological capability.
Sustained-release tablet technologies are overtaking immediate-release formats in the analgesic segment. Patients managing chronic pain conditions across Northern Italy's industrial corridors prefer 12-hour dosing intervals that align with work schedules. This shift is compressing demand for traditional four-hour ibuprofen regimens and forcing reformulation investments.
Italy's alignment with EU MDR and F-Gas Regulation is reshaping inhalant cold remedy portfolios. Manufacturers must eliminate specific propellant categories and redesign delivery mechanisms for environmental compliance. The respiratory OTC segment bears the highest compliance burden, with aerosol suppliers accelerating dry-powder inhaler transitions.
Subscription-based chronic care models are fragmenting traditional pharmacy foot traffic. Consumers in Milan and Turin increasingly schedule recurring deliveries for hypertension monitoring kits and vitamin regimens through verified digital platforms. This behavioral pivot is most pronounced among dual-income households with limited weekday pharmacy access windows.
Italy OTC Drugs Market Segmentation
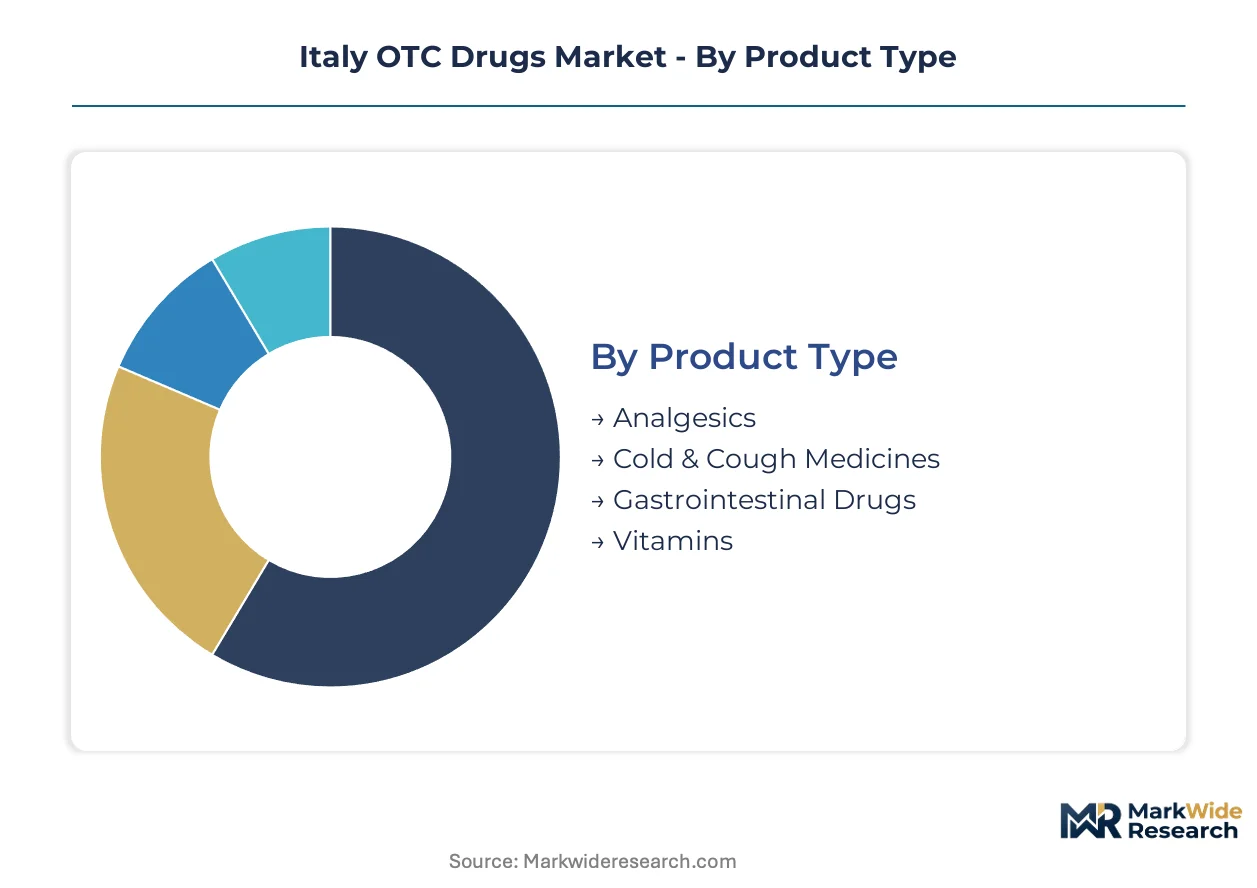
Italy's OTC market fragments across four dimensions that determine pricing power, channel strategy, and formulation investment. Product type and distribution channel together shape margin structures, while customer demographics and dosage forms dictate R&D priorities for domestic manufacturers.
Product Type:
Standardization dominates commodity analgesics while gastrointestinal and vitamin segments reward specialized positioning tailored to Italian prescribing traditions.
- Analgesics:Ibuprofen and paracetamol formulations constitute the volume foundation, with sustained-release tablets capturing chronic pain management demand across Lombardy's industrial workforce. Northern pharmacy chains promote 12-hour dosing regimens that align with factory shift patterns.
- Cold & Cough Medicines:Combination therapies face reformulation pressure under EU F-Gas Regulation as manufacturers phase out specific propellant categories. Dry-powder inhaler transitions are concentrating investment among aerosol suppliers serving Veneto pharmacy networks.
- Gastrointestinal Drugs:Proton pump inhibitors and antacids tailored to Mediterranean dietary patterns anchor Angelini Pharma's domestic portfolio.
- Vitamins:Preventive supplementation regimens target Italy's aging demographic through pharmacist-recommended protocols in dense Northern retail networks.
Most installed capacity flows through Analgesics. Expansion is steepest in Vitamins.
Distribution Channel:
Channel selection determines regulatory exposure and customer relationship depth across Italy's pharmacy-dependent retail landscape.
- Pharmacy:Italy's 25,000-plus farmacie maintain legal primacy for OTC dispensing, with personalized pharmacist recommendations driving premium brand loyalty in Lombardy and Veneto. AIFA verification requirements constrain competitor channel migration.
- Online:Verified e-pharmacy platforms gain regulatory acceptance for click-and-collect models, though AIFA enforcement limits pure direct-to-consumer growth. Milan and Turin dual-income households favor subscription-based chronic care deliveries.
- Supermarket:Limited to lowest-concentration analgesic categories under Italian pharmaceutical law, constraining assortment breadth.
- Health Stores:Supplement-adjacent positioning captures preventive health spending outside formal pharmacy networks, particularly for vitamin categories.
Pharmacy retains dominant volume flow. Online channels are expanding most quickly.
Customer Type:
Demographic targeting shapes formulation complexity and counseling requirements across the Italian market.
- Adults:Working-age consumers in Northern industrial corridors drive sustained-release analgesic demand and self-managed chronic condition protocols.
- Seniors:Italy's 55-plus population concentrates gastrointestinal and vitamin purchases through trusted pharmacist relationships, with swallowing difficulties driving liquid format preference.
- Children:Palatable liquid formulations and precise dosing requirements reward specialized pediatric portfolios in family-dense Veneto municipalities.
- Pregnant Women:Restricted ingredient lists and pharmacist-supervised selection protocols create advisory-intensive purchase journeys.
Seniors command the deepest per-capita spending. Pediatric segments are gaining share fastest.
Formulation:
Dosage form selection balances manufacturing scale against physiological accessibility constraints.
- Tablets:Immediate-release and sustained-release solid dosages dominate analgesic production for cost efficiency and supply chain scalability.
- Liquids:Pediatric and senior applications in Calabria and Sicily drive demand for palatable, dose-precise alternatives to solid forms.
- Capsules:Enteric-coated and modified-release variants serve gastrointestinal drug categories requiring targeted delivery.
- Ointments:Topical analgesic and dermatological applications occupy niche positioning within pharmacy self-care sections.
Tablet production absorbs most manufacturing capacity. Liquid formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage across Italian sub-regions exploits gaps in pharmacy network density and disposable income distribution. AIFA's uniform regulatory framework masks significant regional compliance cost differentials that reward localized manufacturing footprints.
Lombardy
Milan's industrial workforce drives sustained-release analgesic demand aligned with factory shift schedules. The regional health authority coordinates with AIFA on pharmacy network modernization grants. Dense pharmacy clusters in Bergamo and Brescia support premium OTC penetration through personalized pharmacist counseling.
Veneto
Family-dense municipalities around Verona and Padua concentrate pediatric formulation purchases. Regional pharmaceutical associations lobby AIFA for streamlined reclassification timelines. Venice-Treviso pharmacy corridors experiment with subscription-based chronic care delivery models.
Piedmont
Turin's dual-income households favor verified e-pharmacy platforms for recurring vitamin deliveries. The regional government aligns subsidy programs with EU MDR compliance requirements. Pharmaceutical manufacturing in Novara anchors gastrointestinal drug production for northwestern distribution.
Emilia-Romagna
Bologna's aging demographic concentrates vitamin and supplement self-management protocols. Regional health agencies coordinate pharmacist retraining initiatives with Ministry of Health directives. Parma's food-pharma crossover expertise supports specialized digestive health formulation development.
Sicily
Palermo and Catania present whitespace for pharmacy chain expansion and liquid format launches. Southern regional authorities negotiate AIFA enforcement flexibility for digital pharmacy pilot programs. Limited pharmacy density in Calabrian-adjacent zones constrains immediate premium product penetration.
Italy OTC Drugs Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers hedge against generic substitution pressure in commoditized analgesic categories. Market structure consolidates around three strategic tiers: heritage pharmaceutical conglomerates with analgesic legacies, specialized gastrointestinal and pediatric formulators, and diversified consumer health divisions of major pharma groups. Archetypes include prescription-to-OTC switch specialists, regional pharmacy channel integrators, and digital-first chronic care platform operators. M&A activity concentrates on acquiring validated reclassification pipelines, while capacity expansion targets liquid formulation facilities for senior and pediatric segments.
Among heritage pharmaceutical conglomerates, Bayer AG and Novartis AG occupy positions exemplifying analgesic portfolio depth and regulatory navigation expertise. Angelini Pharma represents the specialized formulator archetype with concentrated gastrointestinal and pediatric capabilities. These three anchors demonstrate how divergent strategic postures—broad portfolio leverage versus targeted therapeutic specialization—coexist within AIFA's unified regulatory environment.
| Leading Market Players |
|---|
| Pfizer Inc |
| Reckitt Benckiser Group plc |
| Bayer AG |
| Angelini Pharma |
| Novartis AG |
| GlaxoSmithKline plc |
| Sanofi |
| Boehringer Ingelheim GmbH |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance gates qualified supply and premium-tier pricing access for Italian inhalant cold remedy manufacturers, forcing reformulation investments that stratify cost structures between compliant and non-compliant suppliers. AIFA's verification requirements for pharmacy channel access further segment pricing power, with certified domestic producers commanding margin premiums over import-dependent competitors facing regulatory friction.
Pricing Analysis
Pharmacy retail markup layers dominate Italy's OTC pricing architecture, with personalized pharmacist recommendations sustaining brand premiums in Lombardy and Veneto. Price differentiation separates heritage analgesic portfolios from generic ibuprofen substitutes, with swallowing-difficulty-driven liquid formats capturing margin premiums in pediatric and senior segments. Pricing pressure stems from unbranded paracetamol substitution in high-volume categories, eroding margin pools for commoditized tablet manufacturers. Independent pharmacy operators exhibit highest price sensitivity due to inventory carrying costs, while chain-affiliated farmacie absorb premium positioning through centralized procurement scale.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Chinese API suppliers for ibuprofen and paracetamol active ingredients, constraining formulation flexibility for domestic Italian manufacturers. Raw material dependencies extend to propellant chemicals facing EU F-Gas phase-out schedules, specialized coating materials for sustained-release tablets, and palatability additives for pediatric liquid development. Supply chain risk centers on regulatory restriction exposure from AIFA reclassification timelines that delay new product introductions. Distribution runs through Italy's 25,000-plus farmacie network, with verified e-pharmacy platforms emerging as secondary channels constrained by enforcement variability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's OTC drugs market reads as a late-cycle quality story, with preventive health management among aging consumers shifting demand toward pharmacist-recommended premium specifications and specialized formulation portfolios.
For Market Incumbents: Lock in shelf dominance across Northern pharmacy corridors through exclusive sustained-release analgesic formulations aligned with industrial workforce dosing preferences. Deepen backward integration into liquid formulation capacity for senior and pediatric segments before generic competitors replicate palatability technologies. Defend against digital pharmacy disintermediation by embedding subscription-based chronic care protocols within existing pharmacist relationships. For New Entrants and Emerging Players: AIFA's streamlined reclassification procedures in Italy open a window for prescription-to-OTC switch specialists to capture whitespace in proton pump inhibitor and respiratory combination categories. Target Calabria, Sicily, and Puglia pharmacy expansion zones where chain density remains below Northern benchmarks and localized pediatric liquid launches face limited incumbent saturation. Pursue verified e-pharmacy platform partnerships as the primary go-to-market angle, leveraging click-and-collect models to bypass traditional farmacie gatekeeper friction. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmacy chain consolidators because AIFA verification requirements create regulatory moats that protect acquired storefront networks from pure digital competition. Platform viability extends through a multi-year window as preventive health spending consolidates around trusted pharmacist channels resistant to pure e-commerce substitution. Monitor AIFA's reclassification pipeline velocity as the critical inflection signal—accelerated switch approvals will unlock acquisition premiums for validated prescription-to-OTC development programs.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | AIFA reclassification petitions compress time-to-market for switched analgesic and respiratory assets. |
| Manufacturing Scale-Up | Liquid formulation capacity expansion in Southern Italy addresses pediatric and senior swallowing difficulty demand. |
| Distribution Channel Expansion | Verified e-pharmacy platform integration captures Milan and Turin dual-income household subscription revenue. |
| Pipeline Diversification | Gastrointestinal drug development aligned with Mediterranean dietary patterns reinforces Angelini Pharma's domestic positioning. |
| Sustainability Repositioning | Dry-powder inhaler transitions eliminate EU F-Gas propellant exposure for Veneto aerosol suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmacy chain procurement directors, AIFA regulatory affairs specialists, formulary committee members at regional health authorities, and gastrointestinal drug development executives with secondary validation. Sources included AIFA reclassification filings, Ministry of Health decrees, EU MDR compliance databases, pharmacy network density statistics, and regional health authority subsidy program records. Bottom-up demand modeling from patient population segments and top-down market sizing from manufacturer shipment data were triangulated for convergence.
Historical reference periods anchored the forecast window to established growth trajectories in analgesic, cold medicine, gastrointestinal, and vitamin categories. Segmentation dimensions modeled included product type, distribution channel, customer demographic, and formulation technology alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for AIFA policy velocity and pharmacy network expansion schedules. Forecast inputs incorporated AIFA reclassification pipeline depth, e-pharmacy regulatory acceptance curves, and sustained-release formulation adoption rates among Northern industrial workforces.
Revisions become necessary when AIFA enforcement posture on digital pharmacy platforms shifts, EU environmental regulations accelerate propellant phase-out timelines, or generic substitution pressure in analgesic categories exceeds modeled erosion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market