
 Global Trace Minerals in Feed Market | 2026-2036
Global Trace Minerals in Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trace Minerals in Feed Market Outlook
Precision nutrition subscription services is pivoting how trace mineral premixes reach livestock operations. Cargill, Incorporated leverages its global distribution infrastructure to bundle mineral analytics with recurring feed formulation updates. Zinpro Corporation anchors its competitive position through specialized organic trace mineral research and veterinary technical support programs. DSM-Firmenich AG differentiates via integrated vitamin-mineral premix capabilities that reduce procurement complexity for large feed manufacturers.
Trace minerals in feed constitute bioavailable elemental nutrients—zinc, copper, manganese, iron, selenium, and cobalt—delivered in inorganic salts, organic complexes, or chelated forms at inclusion rates typically between 0.01% and 0.05% of total feed weight, functioning primarily to catalyze enzymatic reactions and support immune competence in production animals. Organic trace minerals command premium positioning due to superior absorption coefficients and reduced environmental excretion, while chelated minerals represent the fastest-growing product class as aquaculture operations seek to replace inorganic forms in sensitive marine species diets. Ruminant feed applications maintain the largest volume base, though aquaculture feed exhibits the steepest trajectory driven by expanding shrimp and salmon production systems.
The European Food Safety Authority (EFSA) and the US Food and Drug Administration (FDA) enforce maximum tolerable levels for selenium and copper in complete feeds, compelling manufacturers to reformulate premixes and validate analytical certificates for cross-border shipments. China's Ministry of Agriculture and Rural Affairs (MARA) and the GB standards system impose additional registration requirements on imported organic trace mineral sources, creating a dual-track compliance burden for suppliers serving multiple production geographies. Stakeholders must monitor evolving maximum residue limits and invest in region-specific regulatory dossiers to sustain market access across fragmented approval regimes.
Market Dynamics
Precision nutrition platforms are compressing traditional mineral premix procurement cycles, forcing suppliers to embed real-time formulation analytics directly into recurring service relationships rather than transactional ingredient sales.
Growth Catalysts
- Chelated mineral bioavailability:Aquaculture operations in Norway and Chile are replacing inorganic zinc and copper with protein-bound chelates to reduce water-column contamination and improve salmonid growth performance.
- REACH purity mandates:The EU's tightening contaminant thresholds for heavy metals in feed-grade minerals are accelerating laboratory certification investments among premix manufacturers seeking cross-border market access.
- Brazilian integrated operations:São Paulo and Paraná poultry complexes are standardizing precision mineral dosing across grow-out facilities, creating concentrated demand for customized premix subscription programs.
Market Restraints
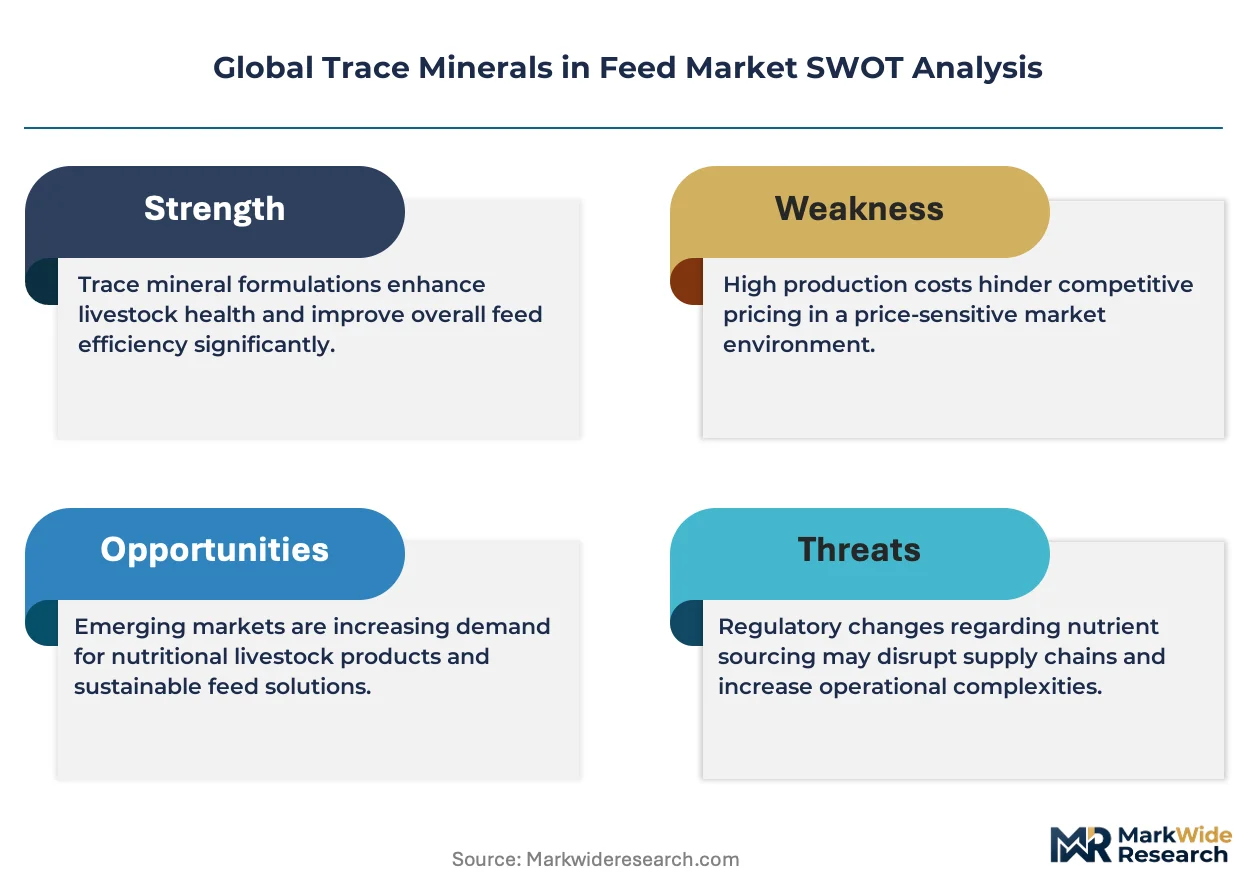
- Sulfate salt price volatility:Inorganic trace mineral feedstocks—zinc sulfate, copper sulfate—track London Metal Exchange pricing, compressing premix margins during commodity spikes.
- Organic mineral supply concentration:Amino acid chelate production clusters in China and select European facilities, exposing buyers to single-source dependency risks.
- Selenium maximum tolerable levels:FDA and EFSA caps on total selenium in complete feeds restrict formulation flexibility for high-performance genetic lines.
Strategic Opportunities
- Underpenetrated African poultry:South Africa and Nigeria's emerging broiler sectors lack precision mineral programs, presenting first-mover positioning for analytics-integrated suppliers.
- Carbon accounting integration:The EU Green Deal's feed carbon footprint disclosure requirements create service revenue streams for mineral premix vendors with lifecycle assessment capabilities.
- Shrimp aquaculture expansion:Southeast Asian intensive shrimp farms in Vietnam and Indonesia are adopting chelated mineral protocols to replace water-quality-stressing inorganic forms.
Industry Challenges
- Analytical chemist scarcity:Validating organic mineral chelation rates and cross-referencing against EFSA/FDA maximum limits requires specialized laboratory talent that premix manufacturers struggle to recruit.
- Dual-track regulatory dossiers:Suppliers serving both EU REACH jurisdictions and China's MARA registration system must maintain parallel compliance documentation, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trace Minerals in Feed Market |
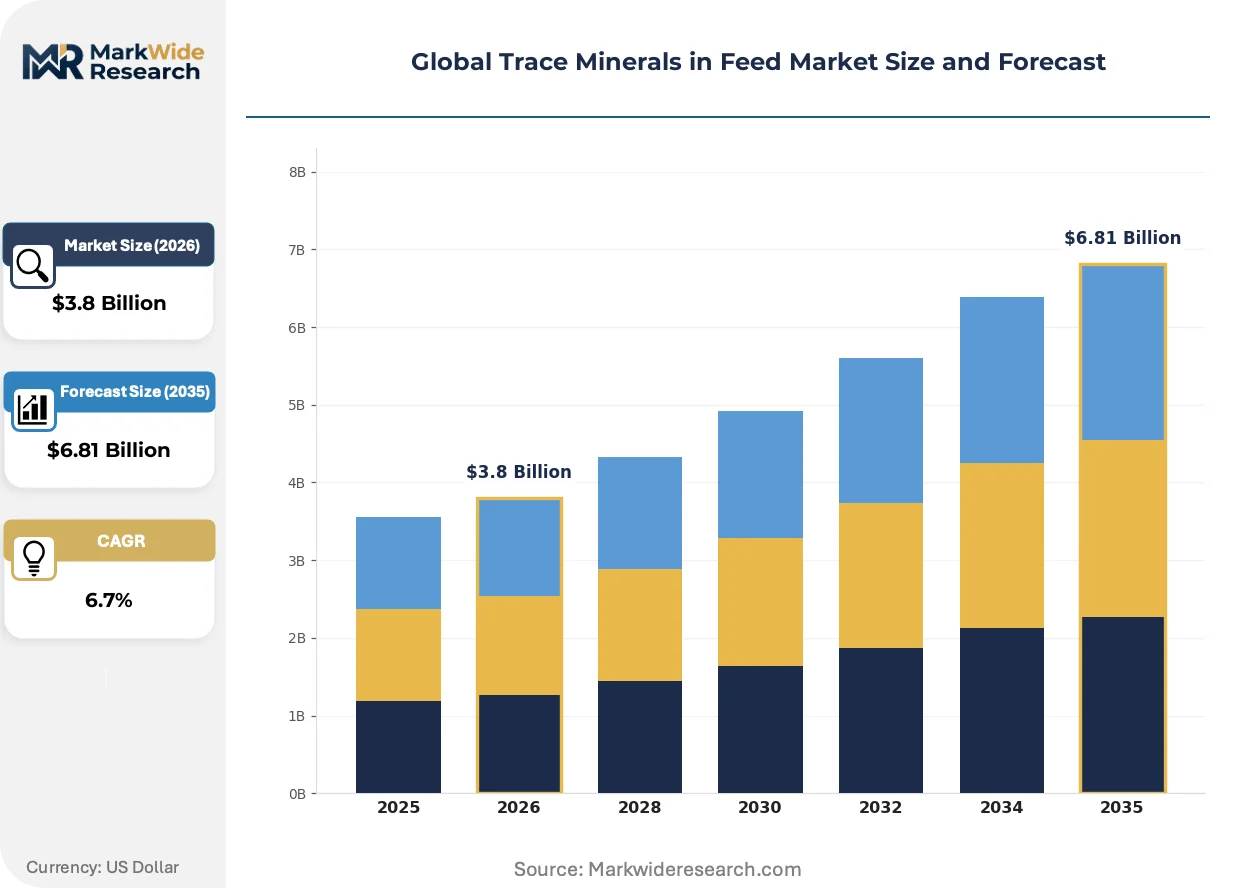
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
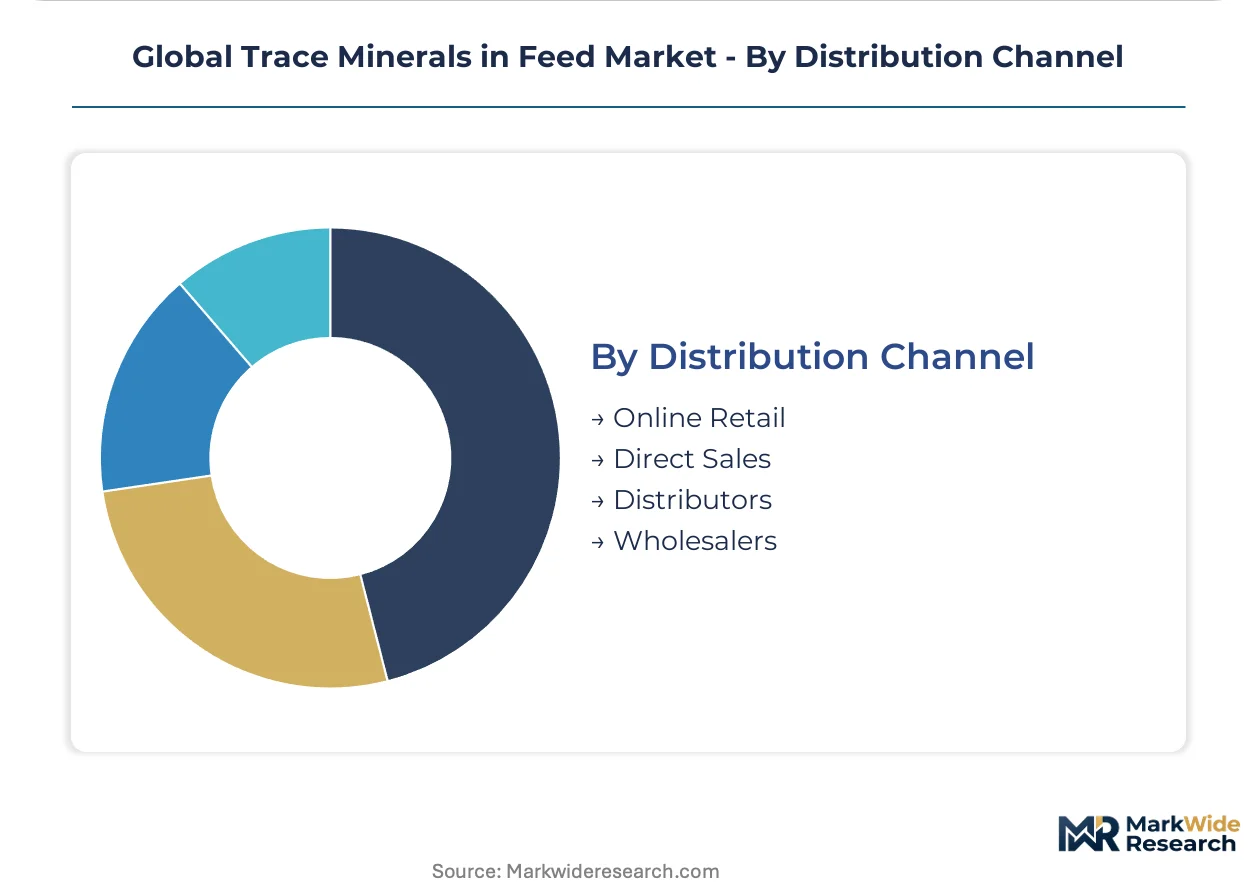
| Segmentation | Product Type: Organic Trace Minerals, Inorganic Trace Minerals, Chelated Minerals, Mineral Protein Complexes Application: Poultry Feed, Ruminant Feed, Swine Feed, Aquaculture Feed End User: Farmers, Feed Manufacturers, Veterinarians, Livestock Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Alltech, Inc., Zinpro Corporation, Novus International, Inc., Phibro Animal Health Corporation, Cargill, Incorporated, Kemin Industries, Inc., Archer Daniels Midland Company, DSM-Firmenich AG, Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trace Minerals in Feed Market Strategic Shifts
Feed mineral delivery systems are fragmenting from bulk commodity formats toward precision-dosed, analytically validated solutions that tie ingredient performance to measurable livestock outcomes.
Protein-based mineral chelation is modularizing how aquaculture and high-value ruminant operations source trace nutrients. Norwegian salmon producers are adopting species-specific zinc-methionine complexes at commercial scale. This technology is modularizing premix procurement into discrete, performance-guaranteed mineral modules that integrate with automated feed mill systems.
REACH authorization procedures and the EU F-Gas Regulation are extending purity documentation requirements to imported mineral additives. Premix manufacturers must now submit analytical certificates for every cross-border shipment. Organic trace mineral categories face the steepest compliance burden, as chelation verification methods lack harmonized international standards.
Subscription-based mineral analytics are displacing spot-market premix purchasing among large integrated livestock operations. Brazilian poultry and swine complexes are bundling quarterly tissue mineral testing with automated formulation adjustments. This shift concentrates purchasing power with vendors capable of delivering continuous technical support rather than commodity ingredient supply.
Global Trace Minerals in Feed Market Segmentation
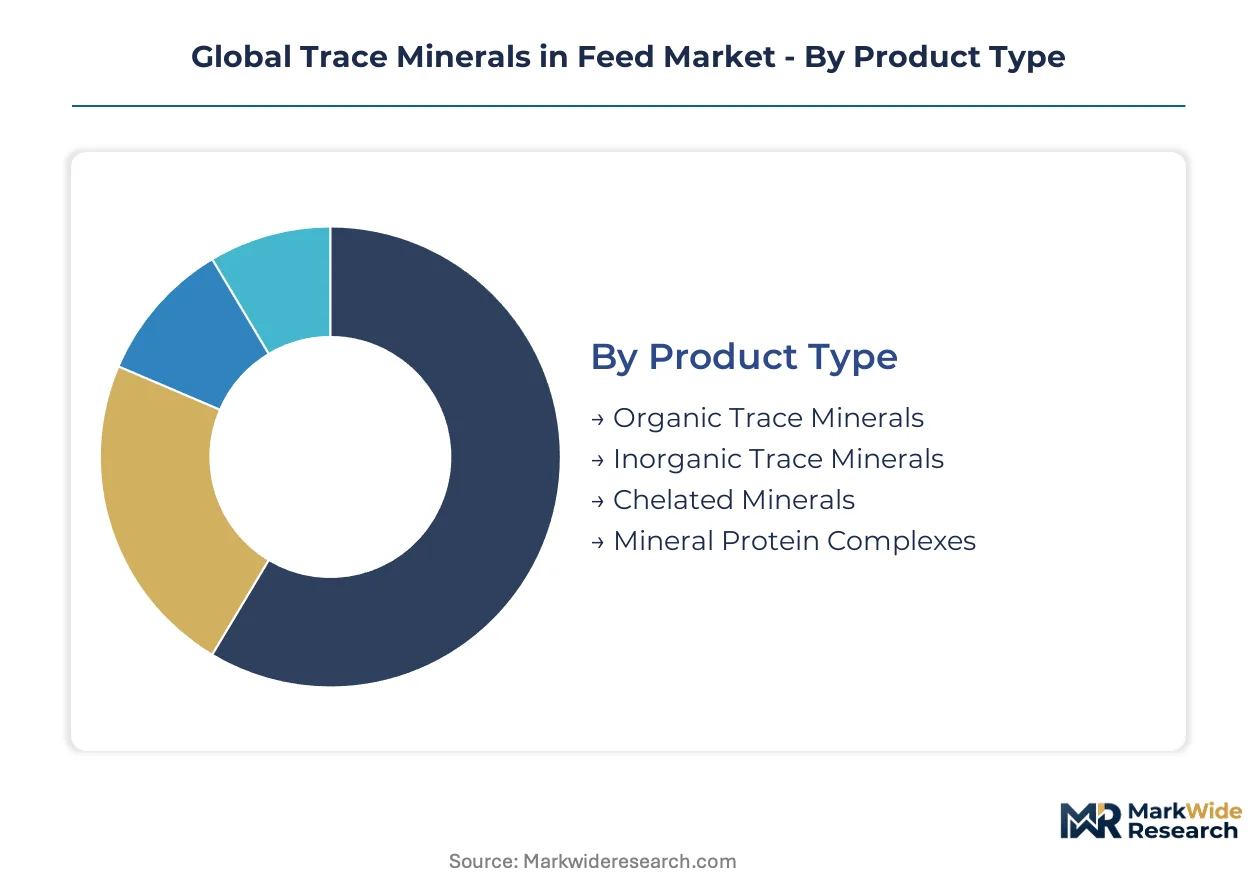
Trace mineral premixes fragment across four distinct dimensions. Product chemistry determines bioavailability and regulatory burden. Application verticals dictate formulation complexity and service intensity. End-user sophistication shapes procurement modality and technical support requirements.
Product Type:
Chelated minerals and organic complexes carry the heaviest certification load—EFSA mandates chelation verification for EU entry, while China's MARA requires separate registration dossiers for amino acid-bound forms. Inorganic salts face lighter documentation but must still document heavy metal thresholds under REACH.
- Chelated Minerals:Protein-bound or amino acid-chelated forms deliver superior absorption coefficients in ruminant and aquaculture applications. Norwegian salmon producers and Brazilian poultry integrators in Paraná are standardizing zinc-methionine and copper-lysine complexes to meet tissue residue targets while reducing environmental excretion.
- Organic Trace Minerals:Complexed forms including mineral proteinates and polysaccharide complexes command premium positioning in high-performance genetic lines. FDA and EFSA maximum tolerable levels for selenium and copper constrain formulation flexibility, pushing demand toward validated organic sources with documented bioavailability studies.
- Inorganic Trace Minerals:Sulfate, oxide, and carbonate salts remain the volume baseline for cost-sensitive operations, particularly in emerging African poultry sectors.
- Mineral Protein Complexes:Yeast-bound and fermentation-derived mineral forms serve niche organic certification feed programs in North American and European markets.
Leading the category by volume: Inorganic Trace Minerals. Growing fastest: Chelated Minerals.
Application:
Volume concentration and margin structure diverge sharply across animal species. Ruminant applications sustain the largest tonnage base through dairy and beef operations. Aquaculture commands the steepest technology premium due to water-column contamination sensitivity.
- Aquaculture Feed:Intensive shrimp farms in Vietnam and Indonesia and salmon operations in Chile are displacing inorganic copper and zinc with chelated alternatives to protect water quality and improve survival rates. The species-specific dosing requirements and sensitivity to mineral toxicity create substantial technical service revenue opportunities.
- Ruminant Feed:Dairy and beef operations across the US Midwest and São Paulo state consume the largest absolute volumes of trace mineral premixes. Rumen bypass protection requirements and tissue mineral monitoring programs sustain recurring service relationships with premix suppliers.
- Poultry Feed:Broiler and layer operations in Brazil's integrated complexes are standardizing precision mineral dosing to optimize feed conversion ratios and reduce environmental loading.
- Swine Feed:Sow and grower-finisher operations in the US, Brazil, and EU drive demand for phase-fed mineral programs tailored to genetic potential.
Highest volume concentration: Ruminant Feed. Steepest margin expansion: Aquaculture Feed.
End User:
Procurement sophistication stratifies sharply across customer types. Large integrators demand subscription-based analytics, while independent farmers remain transaction-oriented.
- Feed Manufacturers:Compound feed mills in the US, Brazil, and EU source integrated vitamin-mineral premixes to reduce procurement complexity and secure analytical certification for finished feeds.
- Livestock Producers:Integrated poultry and swine operations in São Paulo and Paraná states are bundling tissue mineral testing with automated formulation adjustments through recurring service contracts.
- Farmers:Independent producers across South Africa and Nigeria lack precision mineral programs, presenting first-mover positioning for analytics-integrated suppliers.
- Veterinarians:Technical consultants in EU member states and North America influence mineral specification decisions for high-value ruminant and equine operations.
Most procurement concentration: Feed Manufacturers. Fastest service-model transition: Livestock Producers.
Distribution Channel:
Channel selection reflects customer scale and technical support requirements. Direct relationships dominate large integrators, while distributor networks serve fragmented geographies.
- Direct Sales:Premix manufacturers including Cargill and DSM-Firmenich AG deploy technical sales teams to large integrated livestock operations requiring continuous formulation support and quarterly tissue mineral analytics.
- Distributors:Regional feed ingredient distributors serve mid-tier compounders and independent farmers across Brazil's interior states and the US Corn Belt.
- Online Retail:E-commerce platforms capture small-lot orders from hobby farmers and specialty livestock operations in North America and Western Europe.
- Wholesalers:Bulk mineral traders supply commodity sulfate salts to price-sensitive feed mills with in-house premixing capabilities.
Dominant channel by revenue: Direct Sales. Fastest digital penetration: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates amino acid chelate production capacity while Brazil and the United States absorb the largest premix volumes. Regulatory divergence between EFSA maximum limits and China's MARA registration requirements fragments supplier compliance strategies across major consumption zones.
United States
Integrated poultry and swine operations in the Southeast and Midwest drive precision mineral subscription adoption. FDA maximum tolerable levels for selenium and copper constrain formulation flexibility for high-performance genetic lines. Iowa and North Carolina feed manufacturing clusters are standardizing quarterly tissue mineral testing with automated formulation adjustments.
Brazil
São Paulo and Paraná poultry complexes are scaling chelated mineral programs to optimize feed conversion ratios and reduce environmental loading. ANVISA alignment with international Codex standards simplifies cross-border premix certification for integrated exporters. Southern Brazil's swine operations are consolidating procurement through direct technical service relationships with global premix suppliers.
China
Domestic amino acid chelate production clusters in coastal provinces supply both local compound feed mills and export markets. MARA registration dossiers for organic trace mineral sources impose dual-track compliance burdens on multinational suppliers serving EU and Chinese markets simultaneously. Shandong and Jiangsu provinces concentrate fermentation-derived mineral complex manufacturing capacity.
Norway
Salmon aquaculture operations in fjord regions are displacing inorganic copper and zinc with protein-bound chelates to protect water-column quality. EFSA chelation verification requirements for EU market access accelerate laboratory certification investments among Norwegian premix importers. Bergen and Trondheim technical service hubs support species-specific mineral dosing protocols for marine finfish producers.
Germany
REACH authorization procedures and the EU F-Gas Regulation extend purity documentation requirements to all imported mineral additives. Bavaria and Lower Saxony dairy operations sustain the largest ruminant premix volumes through precision mineral monitoring programs. German compound feed manufacturers are bundling carbon footprint disclosure services with mineral premix procurement to meet EU Green Deal compliance timelines.
Global Trace Minerals in Feed Market Competitive Environment
Capital-heavy mineral compounders compete with asset-light formulation specialists across distinct service tiers. The vendor base stratifies between integrated agricultural conglomerates with captive feed manufacturing and dedicated trace mineral research houses with veterinary technical support programs. Three archetypes dominate: diversified nutrition platforms with global distribution infrastructure, specialized organic mineral laboratories with chelation expertise, and regional compound feed operators with backward integration into premixing. Competitive positioning hinges on M&A activity consolidating veterinary technical service networks and geographic expansion into underpenetrated African and Southeast Asian poultry sectors.
Among diversified nutrition platforms, Cargill, Incorporated and DSM-Firmenich AG occupy positions anchoring global distribution scale with integrated vitamin-mineral capabilities. Zinpro Corporation exemplifies the specialized organic trace mineral archetype, sitting within the chelation research-intensive tier that commands premium positioning through bioavailability validation. These three entities represent the structural poles around which mid-tier regional compounders and emerging analytics-integrated subscription services organize their competitive responses.
| Leading Market Players |
|---|
| Alltech, Inc. |
| Zinpro Corporation |
| Novus International, Inc. |
| Phibro Animal Health Corporation |
| Cargill, Incorporated |
| Kemin Industries, Inc. |
| Archer Daniels Midland Company |
| DSM-Firmenich AG |
| Nutreco N.V. |
| Others |
Value Chain & Pricing Dynamics
Integrated poultry operations in São Paulo and Paraná states concentrate purchasing power through subscription-based mineral analytics contracts, compressing spot-market premix margins and favoring vendors with continuous technical service capabilities over transactional suppliers.
Pricing Analysis
Margin tightening in inorganic sulfate salts reflects London Metal Exchange price volatility for zinc and copper feedstocks, while chelated mineral premiums hold steady due to amino acid chelate supply concentration in China and select European facilities. Three-tier pricing structure across chelated, organic complex, and inorganic salt grades differentiates offerings by bioavailability certification and veterinary technical support bundling. Cost-down pressure on commodity sulfate premixes accelerates because Brazilian integrators are standardizing precision dosing subscriptions. Independent farmers across South Africa and Nigeria exhibit highest price sensitivity, whereas Norwegian salmon producers accept premium positioning for water-column-compliant chelates.
Supply Chain Analysis
Direct-to-integrator channels handle large livestock operation demand across Brazil's southern states and the US Midwest, while regional distributors serve fragmented compound feed mills in Brazil's interior. Amino acid chelate production concentrates in China's Shandong and Jiangsu provinces, with fermentation-derived mineral complexes clustering in coastal manufacturing zones. Raw material dependencies rest on sulfuric acid for sulfate salt production, methionine and lysine for chelation chemistry, and pharmaceutical-grade selenium for high-bioavailability formulations. Single-source vulnerability in organic mineral supply exposes buyers to MARA registration delays and REACH authorization bottlenecks. Distribution runs through technical sales teams for integrated operations and bulk mineral traders for price-sensitive commodity buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in trace minerals hinges on backward integration into chelation chemistry and captive analytical certification capabilities to capture subscription service margins.
For Market Incumbents: Extend veterinary technical service networks into underpenetrated African poultry sectors before analytics-integrated entrants establish first-mover positioning. Acquire regional compounders with existing MARA registration dossiers to neutralize dual-track compliance burdens threatening cross-border market access. Cargill and DSM-Firmenich AG already bundle mineral analytics with formulation updates; smaller players must match this service intensity or retreat to commodity sulfate volumes. For New Entrants and Emerging Players: Independent farmers across Nigeria and South Africa lack precision mineral programs and present accessible entry points for subscription-based tissue testing and automated dosing protocols. Southeast Asian intensive shrimp farms in Vietnam and Indonesia are adopting chelated mineral protocols fastest, offering technical service revenue streams without incumbent lock-in. Partner with regional feed distributors to bypass direct sales infrastructure requirements and accelerate geographic coverage. For Investors and Strategic Acquirers: The window for entry favors specialized organic mineral laboratories with validated chelation methods and existing EFSA/FDA compliance documentation. Long-term viability centers on acquisition targets with captive amino acid chelate production and veterinary technical service networks rather than commodity sulfate compounders. Monitor MARA registration approval timelines for imported organic trace minerals as an inflection indicator for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Chelate Production | Captive supply of methionine-bound minerals reduces dependency on Shandong and Jiangsu production clusters. |
| Carbon Footprint Disclosure Service Launch | EU Green Deal compliance bundling with premix procurement captures German dairy operation contracts. |
| Veterinary Technical Service Network Expansion | Species-specific dosing protocols for Norwegian salmon producers defend premium positioning against commodity entrants. |
| MARA Registration Dossier Acquisition | Parallel EU-China compliance documentation accelerates organic trace mineral launch timelines. |
| Precision Mineral Analytics Platform Integration | Automated formulation adjustments with quarterly tissue testing lock in Brazilian integrator subscription revenue. |
Study Parameters
Multi-period observation of chelated mineral adoption rates, MARA registration timelines, and EFSA maximum tolerable level enforcement anchored the trend analysis, supplemented by interviews with premix manufacturer R&D directors, veterinary technical consultants at integrated poultry operations, compound feed mill procurement managers, and regulatory affairs leads navigating REACH authorization procedures. Secondary validation drew from FDA guidance documents, EFSA scientific opinions on selenium and copper limits, ANVISA alignment notifications with Codex standards, and London Metal Exchange pricing data for zinc and copper feedstocks. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis.
An input-output matrix structured projections across product chemistry tiers, application verticals spanning ruminant through aquaculture species, end-user sophistication levels, and regional regulatory clusters. CAGRs were derived from mineral inclusion rate trajectories, livestock production volume forecasts, and substitution elasticity between inorganic and organic forms. Key inputs included shrimp and salmon aquaculture expansion rates in Vietnam and Indonesia, Brazilian poultry integration consolidation patterns, and EU F-Gas Regulation purity threshold implementation schedules.
Revisions become necessary when MARA registration backlogs extend organic trace mineral approval timelines, EFSA chelation verification methods diverge from international standards, or London Metal Exchange volatility spikes disrupt sulfate salt input costs. Practitioners should monitor REACH authorization bottlenecks, African poultry sector precision nutrition adoption curves, and carbon accounting disclosure mandate rollouts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Animal Feed Phytase Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Africa Feed Vitamins Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market