
 Africa Feed Vitamins Market | 2026-2036
Africa Feed Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Feed Vitamins Market Outlook
The veterinary pharmaceutical distribution channel is narrowing across Sub-Saharan Africa as formal procurement networks displace informal traders. BASF SE leverages its Kempton Park blending facility to sustain supply continuity for South African feed mills. Adisseo anchors West African demand through its Abidjan technical service hub. DSM Nutritional Products competes on premix precision, differentiating its vitamin stability protocols for tropical storage conditions.
Africa feed vitamins comprise water-soluble and fat-soluble organic compounds formulated at concentrations between 5,000 and 50,000 IU per kilogram of premix, manufactured through spray-drying and micro-encapsulation processes to preserve bioactivity in humid climates. These additives prevent deficiency disorders, optimize feed conversion ratios, and support immune function in monogastric and ruminant livestock. Vitamin E leads product type revenue due to its antioxidant role in poultry stress management, while Vitamin B Complex expands fastest among aquaculture operators seeking improved growth rates. Powder form dominates volume owing to blending compatibility with maize-soy basal diets, though liquid vitamin delivery gains traction in automated broiler houses.
South Africa's Department of Agriculture enforces Regulation R.70 under the Fertilizers, Farm Feeds, Agricultural Remedies and Stock Remedies Act, mandating vitamin declaration and maximum tolerance limits. The African Union's Interafrican Bureau for Animal Resources coordinates harmonized feed standards through the SANCO framework, reducing cross-border trade friction for premix suppliers. Nigeria's National Agency for Food and Drug Administration and Control inspects imported vitamin concentrates at Lagos and Apapa ports, extending clearance timelines for non-registered suppliers. Stakeholders must monitor evolving national registration requirements and build direct relationships with country-level regulatory liaisons to secure uninterrupted market access.
Market Dynamics
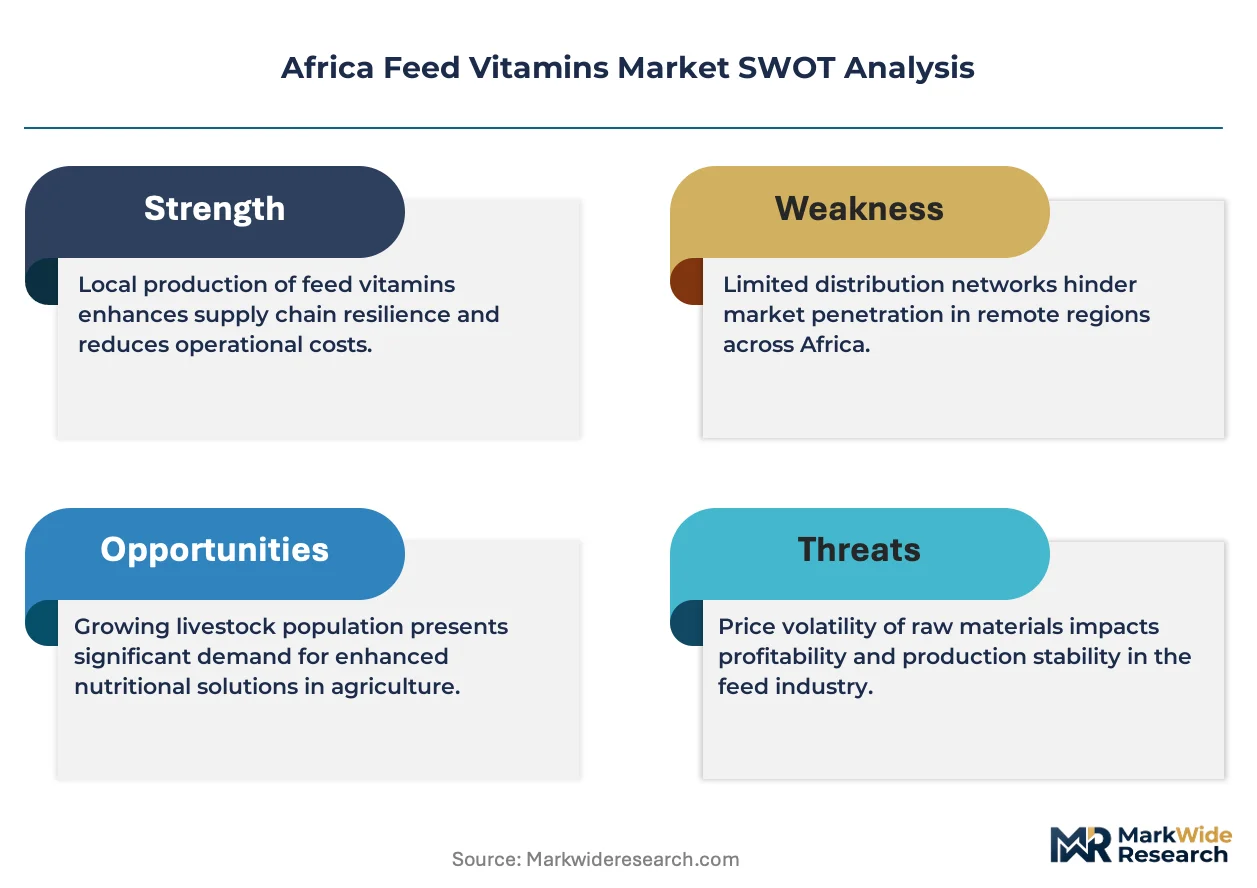
Formal procurement networks across Sub-Saharan Africa are displacing informal traders, narrowing distribution channels and concentrating purchasing power among vertically integrated poultry integrators and aquaculture cooperatives. This structural consolidation elevates quality requirements while compressing margins for non-specialized suppliers.
Growth Catalysts
- Regulation R.70 enforcement:South Africa's Department of Agriculture mandates vitamin declaration and tolerance limits, forcing feed mills to upgrade premix specifications and creating certified demand for precision-formulated products.
- Aquaculture expansion:Nigeria's commercial catfish and tilapia operators are adopting Vitamin B Complex formulations to improve feed conversion ratios in intensive pond systems.
- SANCO framework harmonization:The African Union's Interafrican Bureau for Animal Resources is reducing cross-border trade friction, enabling premix suppliers to scale multi-country distribution with unified compliance documentation.
Market Restraints
- Import concentration risk:Over 80% of vitamin concentrates enter through Lagos and Apapa ports, creating single-point vulnerability for Nigerian feed mill supply security.
- Tropical storage degradation:Humid climates accelerate vitamin potency loss, requiring micro-encapsulation investments that inflate working capital requirements for distributors.
- Maize price volatility:Basal diet cost fluctuations compress premix purchasing budgets during drought cycles in East African grain markets.
Strategic Opportunities
- Ethiopian poultry integration:Commercial layer and broiler operations around Addis Ababa remain underpenetrated by premix suppliers, presenting first-mover positioning for stability-tested formulations.
- Liquid delivery systems:Automated broiler houses in South Africa's Mpumalanga province are creating demand for water-soluble vitamin applications that bypass powder-blending infrastructure.
- NAFDAC registration acceleration:Nigeria's National Agency for Food and Drug Administration and Control is streamlining import permits for pre-registered suppliers, rewarding early compliance investments with faster customs clearance.
Industry Challenges
- Technical service scarcity:Qualified nutritionists capable of customizing premix ratios for tropical stress conditions remain concentrated in South Africa and Côte d'Ivoire, limiting supplier expansion into secondary markets.
- Integration complexity:Feed mills retrofitting legacy mixing equipment for liquid vitamin systems face downtime costs and formulation recalibration delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Feed Vitamins Market |
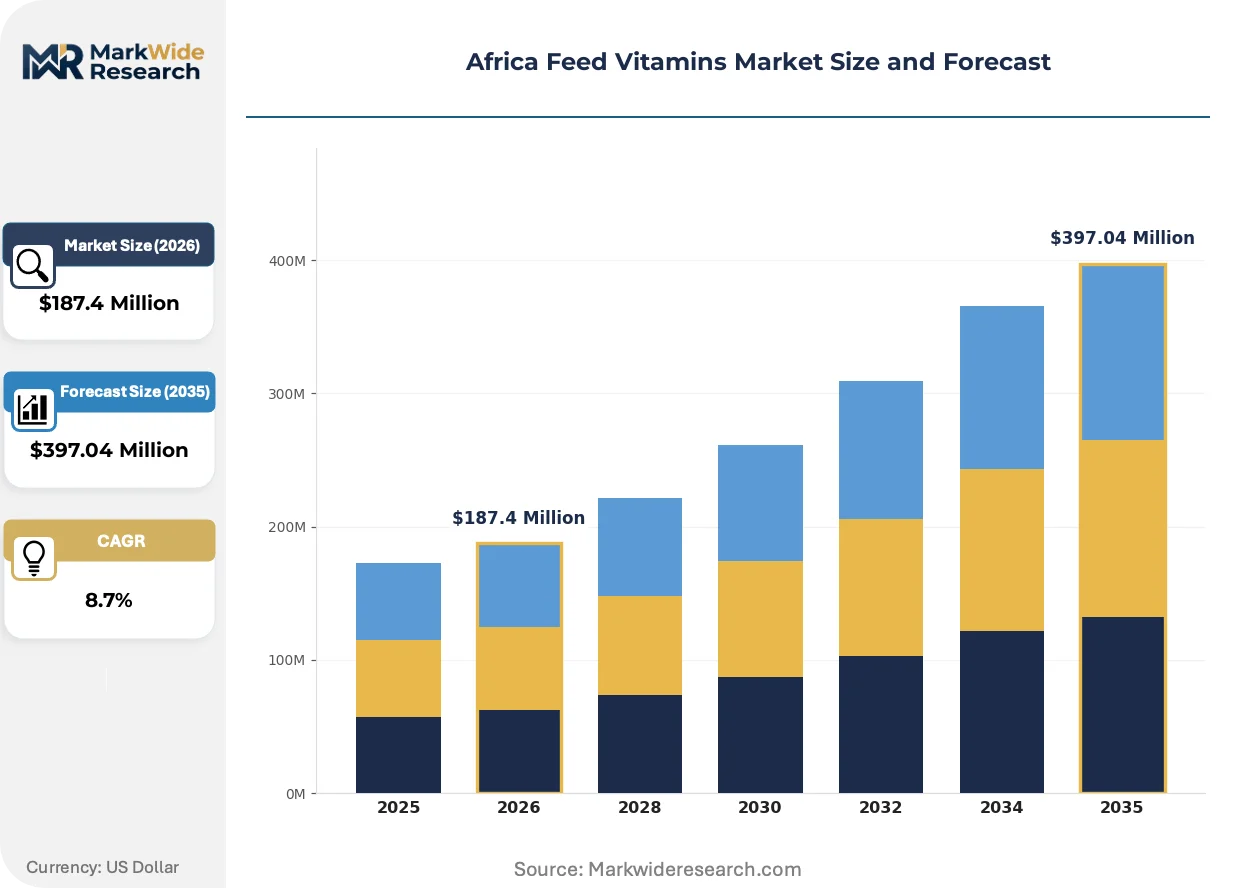
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A, Vitamin D, Vitamin E, Vitamin B Complex End User: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granules, Tablets Distribution Channel: Online, Offline, Distributors, Retailers |
| Companies Covered | BASF SE, Adisseo, Nutreco N.V., DSM Nutritional Products, Archer Daniels Midland Company, Zinpro Corporation, Evonik Industries AG, Pfizer Inc., Alltech Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Feed Vitamins Market Strategic Shifts
Micro-encapsulation and spray-drying protocols are advancing rapidly to preserve vitamin bioactivity in high-humidity storage environments. These process innovations intersect with regulatory pressure for declared potency guarantees and operational demands for extended shelf stability.
Micro-encapsulation technology is migrating from pharmaceutical-grade applications to feed-grade vitamin production, creating lipid-matrix shells that shield sensitive compounds from oxidative degradation. Poultry integrators in Kenya's Rift Valley are adopting these enhanced premixes for layer operations subject to seasonal heat stress. The shift is compressing market share for conventional spray-dried alternatives that lack moisture barriers.
South Africa's Regulation R.70 under the Fertilizers, Farm Feeds, Agricultural Remedies and Stock Remedies Act now requires third-party verification of vitamin concentration claims. Feed mills must submit batch documentation demonstrating compliance with maximum tolerance limits. Large-scale operators in Gauteng and Western Cape provinces are responding by consolidating supplier relationships with premix manufacturers maintaining in-house analytical laboratories.
Buyer concentration among integrated poultry producers is shortening supplier qualification cycles and unbundling technical service from product supply. Nigerian broiler houses in Ogun State now contract directly with vitamin concentrate importers, bypassing traditional distributor markups. This disintermediation is most visible in West Africa, where port-proximate blending facilities enable just-in-time delivery to mill operations.
Africa Feed Vitamins Market Segmentation
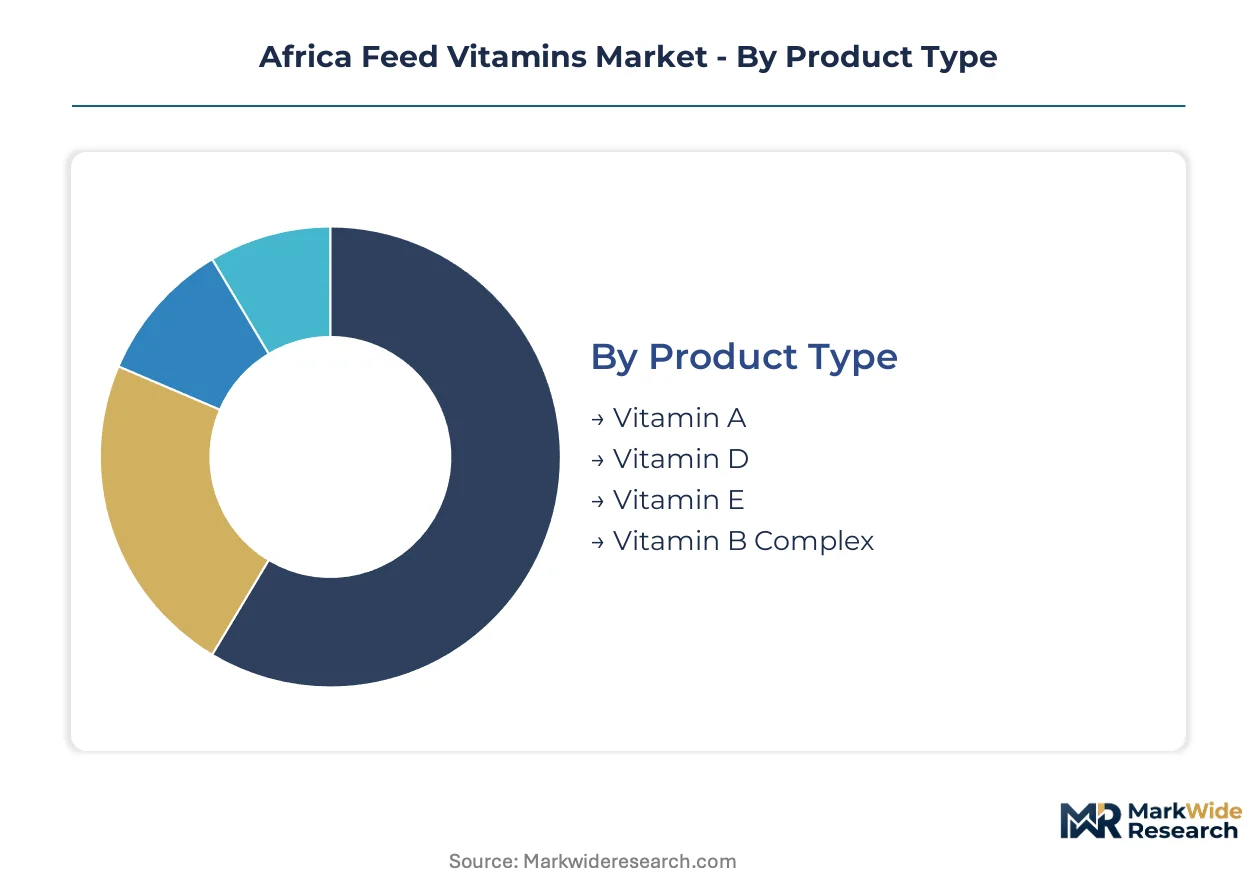
Feed vitamin segmentation across Africa reflects divergent livestock production intensities and infrastructure maturity. Poultry integrators in South Africa and Nigeria drive premium formulation demand, while smallholder ruminant operations in East Africa prioritize cost-optimized delivery formats.
Product Type:
Vitamin E and Vitamin A premixes turn over fastest through Nigerian poultry houses, while Vitamin D cycles slower due to seasonal supplementation patterns. Vitamin B Complex accelerates most rapidly among aquaculture operators.
- Vitamin E:Fat-soluble antioxidant formulated at 5,000-50,000 IU per kilogram to mitigate oxidative stress in intensive broiler operations. Nigerian commercial layer houses around Lagos and Ogun State concentrate demand, driven by heat stress management protocols during dry season production peaks.
- Vitamin B Complex:Water-soluble formulation combining thiamine, riboflavin, and cobalamin for metabolic function optimization. Catfish and tilapia pond systems in Nigeria's Delta State adopt these premixes to improve feed conversion ratios in high-density stocking configurations.
- Vitamin A:Retinol-based premix supporting vision and immune function in ruminant herds across Kenya's Rift Valley.
- Vitamin D:Cholecalciferol formulation for calcium absorption, cycling slower due to seasonal supplementation in pastoral systems.
Vitamin E anchors the volume base while Vitamin B Complex gains share at the steepest rate.
End User:
Cost tiers stratify sharply: poultry operations absorb premium micro-encapsulated vitamins, while ruminant pastoralists rely on commodity-grade formulations. Aquaculture represents the emerging high-margin application layer.
- Poultry:Intensive broiler and layer houses in South Africa's Mpumalanga and Nigeria's Ogun State drive specification-grade premix demand. Heat stress management and automated feeding systems concentrate purchasing power among vertically integrated operators.
- Aquaculture:Nigerian catfish pond operators and Kenyan tilapia cooperatives adopt water-soluble B Complex formulations. Intensive pond systems in Delta State and Kisumu County prioritize growth rate optimization over basal diet cost minimization.
- Ruminants:Cattle and small ruminant operations across Ethiopia's highlands and Kenya's pastoral zones utilize Vitamin A and D supplements during dry season feed scarcity.
- Swine:Limited commercial pig farming in South Africa's Western Cape and KwaZulu-Natal provinces generates specialized premix demand for reproductive health formulations.
Poultry commands the largest absolute volume while aquaculture climbs fastest on margin contribution.
Form:
Volume concentration favors powder formats compatible with maize-soy basal diet blending, though liquid systems penetrate automated facilities. Granules and tablets serve niche veterinary therapeutic applications.
- Powder:Spray-dried and micro-encapsulated formulations dominate premix compatibility with conventional feed mill infrastructure. Kenyan layer operations in the Rift Valley and Nigerian broiler houses rely on powder blending for cost-efficient vitamin incorporation.
- Liquid:Water-soluble concentrates enable direct administration through automated drinking systems. South African broiler integrators in Mpumalanga province retrofit houses for liquid delivery to bypass powder-mixing equipment limitations.
- Granules:Slow-release lipid-matrix formulations for ruminant mineral-vitamin blocks in Ethiopia's commercial dairy sector.
- Tablets:Veterinary therapeutic dosages for individual animal treatment in South Africa's registered feed remedy channels.
Powder form sustains the volume foundation while liquid delivery expands most quickly among technology-adopting integrators.
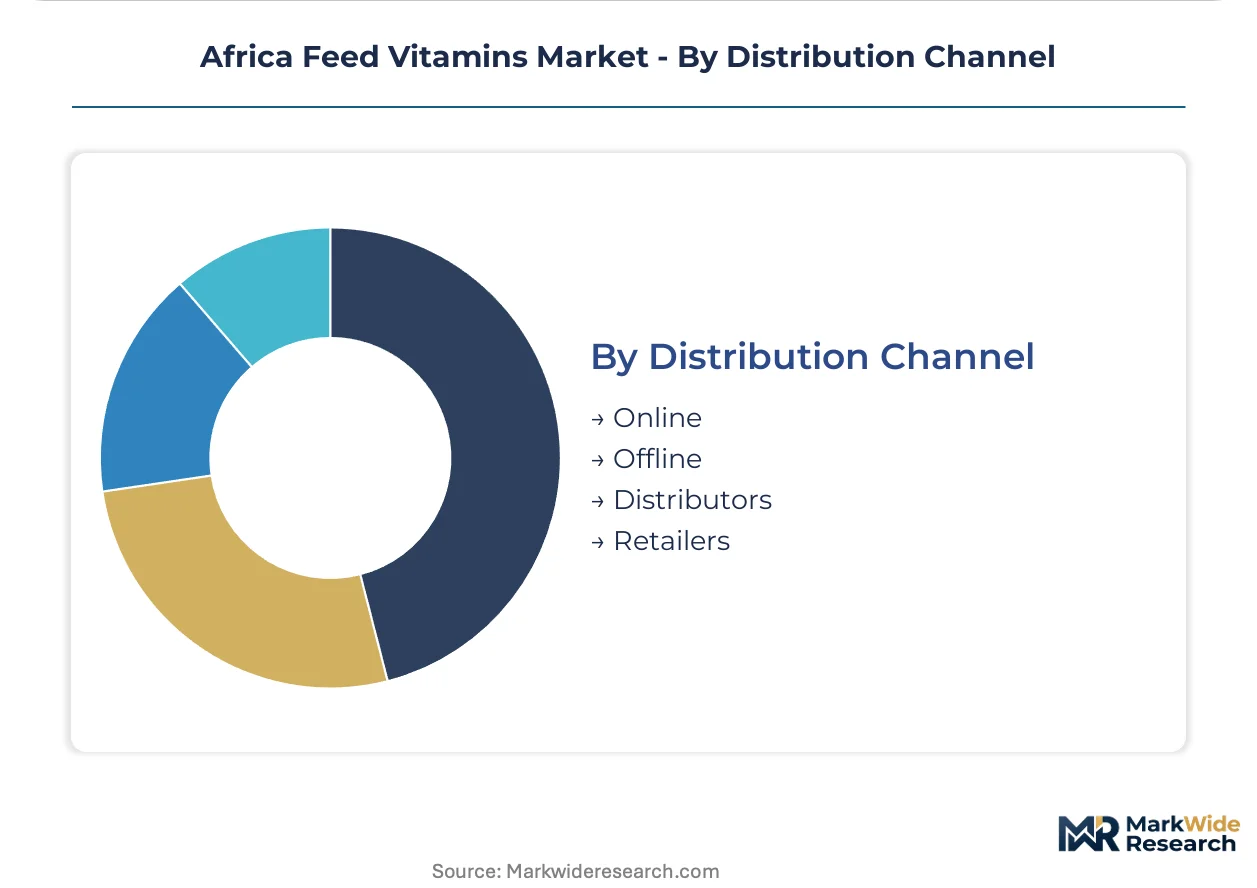
Distribution Channel:
Customer type bifurcation shapes channel selection: large integrators source direct from importers, while fragmented smallholders depend on distributor networks. Online procurement remains nascent outside South Africa.
- Distributors:Regional feed additive distributors with cold-chain capabilities dominate Nigerian and Kenyan supply. Lagos-based distributors maintain port-proximate warehouses to serve Ogun State feed mills with just-in-time vitamin concentrate delivery.
- Offline:Traditional agricultural supply stores and cooperative procurement systems serve Ethiopia's emerging poultry sector around Addis Ababa. Technical service relationships drive supplier loyalty among first-time commercial operators.
- Retailers:Veterinary pharmacies and farm supply shops cater to smallholder ruminant producers in Kenya's pastoral counties.
- Online:E-commerce platforms capture limited South African demand among hobby farmers and small-scale layer operations in Gauteng province.
Distributor networks anchor current volume while direct procurement from integrators gains share fastest as formalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands pricing premiums for micro-encapsulated formulations that Nigerian buyers cannot absorb, creating a two-tier procurement landscape across the continent. East African poultry operations pay intermediate rates reflecting higher logistics costs and smaller batch requirements. This asymmetry shapes supplier investment priorities and product portfolio segmentation.
South Africa
Vertically integrated poultry producers in Mpumalanga and Western Cape provinces drive specification-grade vitamin premix demand. The Department of Agriculture enforces Regulation R.70 tolerance limits, forcing feed mills to upgrade analytical capabilities. Gauteng-based distributors maintain cold-chain warehouses serving layer operations around Pretoria with just-in-time delivery.
Nigeria
Commercial catfish pond systems in Delta State and broiler houses across Ogun State concentrate demand for Vitamin E and B Complex formulations. NAFDAC inspects imported concentrates at Lagos and Apapa ports, extending clearance timelines for non-registered suppliers. Feed mills around Ibadan retrofit mixing equipment to handle higher-potency premix specifications.
Kenya
Rift Valley layer cooperatives and Kisumu County tilapia operators adopt water-soluble vitamin applications. The Kenya Bureau of Standards enforces feed additive labeling requirements under KS 04-622. Mombasa port clearance delays create inventory pressure for distributors serving emerging poultry clusters around Nakuru.
Ethiopia
Commercial layer and broiler operations around Addis Ababa remain underpenetrated by premix suppliers with tropical stability expertise. The Ethiopian Food and Drug Authority registers imported feed additives through centralized Addis Ababa processing. Debre Zeit poultry corridor operators seek technical service relationships absent from local distribution networks.
Egypt
Intensive aquaculture in the Nile Delta and commercial dairy around Alexandria generate specialized vitamin demand. The Egyptian Organization for Standardization and Quality regulates premix imports through Cairo-based certification. 10th of Ramadan industrial zone feed mills blend imported concentrates for redistribution to Upper Egypt poultry operations.
Africa Feed Vitamins Market Competitive Environment
Multinational chemical conglomerates and specialized animal nutrition firms split the market between scale-driven supply security and technical service intensity. The vendor base concentrates around port-proximate blending facilities and regional technical hubs. Three archetypes dominate: integrated chemical majors with captive vitamin production, dedicated animal nutrition specialists with formulation expertise, and regional distributors with cold-chain logistics capabilities. Competitive moves center on regulatory pre-registration investments and micro-encapsulation capacity expansion for tropical stability claims.
Among the integrated chemical majors, BASF SE anchors supply continuity through its Kempton Park blending facility serving South African feed mills. DSM Nutritional Products occupies a position emphasizing premix precision and vitamin stability protocols. Adisseo exemplifies the technical service archetype through its Abidjan hub anchoring West African demand. These three represent distinct strategic postures: manufacturing scale, formulation science, and regional technical intimacy.
| Leading Market Players |
|---|
| BASF SE |
| Adisseo |
| Nutreco N.V. |
| DSM Nutritional Products |
| Archer Daniels Midland Company |
| Zinpro Corporation |
| Evonik Industries AG |
| Pfizer Inc. |
| Alltech Inc. |
| Others |
Value Chain & Pricing Dynamics
Port concentration risk at Lagos and Apapa determines both the premium commanded by registered suppliers and the shape of downstream distribution networks. NAFDAC inspection chokepoints extend clearance timelines for non-registered vitamin concentrate importers, forcing feed mills to pay tariff-equivalent premiums for compliant supply security.
Pricing Analysis
The customization-premium spread separates specification-grade micro-encapsulated formulations from commodity spray-dried alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under South Africa's Regulation R.70 and volume scale of procurement. Cost compression in the economy tier is intensifying because Nigerian poultry integrators consolidate purchasing power around vertically integrated operations. Smallholder ruminant producers in Ethiopia's highlands exhibit highest price sensitivity, while South African layer houses absorb premium positioning for tropical stability guarantees.
Supply Chain Analysis
Export-control regimes on vitamin precursor chemicals limit flows from Chinese and European manufacturing hubs into African blending facilities. Geographic supply concentration centers on Germany, China, and the Netherlands for vitamin A and E concentrates. Raw material dependencies rest on petrochemical-derived acetate esters, corn starch carriers, and gelatin encapsulation matrices. Single-source vulnerability concentrates at Mombasa and Lagos port corridors. Distribution runs through regional feed additive distributors with cold-chain capabilities serving Nigerian and Kenyan mill operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-encapsulation technology disruption is reshaping competitive positioning as tropical stability protocols become mandatory under advancing regulatory frameworks. The intersection of precision formulation requirements and supply chain formalization creates winner-take-most dynamics for compliant suppliers.
For Market Incumbents: Harden analytical laboratory capabilities to meet South Africa's third-party verification mandates under Regulation R.70. Expand micro-encapsulation capacity at port-proximate blending facilities to defend against substitute technology entrants. Deepen technical service teams in Abidjan and Kempton Park to anchor West and Southern African demand respectively.
For New Entrants and Emerging Players: Ethiopia's Debre Zeit poultry corridor offers first-mover positioning for stability-tested formulations absent established supplier relationships. Target Nigerian catfish pond operators in Delta State with water-soluble B Complex applications bypassing powder-blending infrastructure. Accelerate NAFDAC pre-registration to capture customs clearance advantages at Lagos ports.
For Investors and Strategic Acquirers: Regulation R.70 enforcement reshapes the acquisition landscape toward precision-formulation capabilities with in-house verification infrastructure. Long-term viability across the analysis window favors targets with tropical stability IP and regulatory compliance moats. Monitor NAFDAC registration velocity as the inflection signal for Nigerian market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Capacity Expansion | Tropical stability protocols under Regulation R.70 now mandate moisture-barrier formulations for premium tier positioning. |
| NAFDAC Pre-Registration Investment | Accelerated customs clearance at Lagos and Apapa ports rewards early compliance with supply security premiums. |
| Technical Service Hub Establishment | Qualified nutritionist concentration in South Africa and Côte d'Ivoire limits expansion into secondary African markets. |
| Liquid Delivery System Development | Automated broiler houses in Mpumalanga province create demand for water-soluble applications bypassing powder infrastructure. |
| Backward Integration into Vitamin Concentrate Supply | Import concentration risk at Nigerian ports incentivizes captive supply arrangements with European and Asian manufacturers. |
Study Parameters
A spread of perspectives from feed mill procurement managers, poultry integration nutritionists, regulatory affairs officers at veterinary pharmaceutical distributors, and port logistics coordinators converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, SEC filings of multinational chemical conglomerates, and the African Union's SANCO framework documentation. Bottom-up volume modeling triangulated against top-down market sizing across product type, livestock end-use, and regional regulatory cluster dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vitamin product type, livestock species application, formulation grade tier, and distribution channel formalization level. CAGRs derived from logistic adoption curves fitted to poultry integration intensity metrics and aquaculture stocking density trends. Industry-specific forecast inputs incorporated maize price volatility cycles and NAFDAC registration pipeline velocity.
Macroeconomic conditions sit as an overlay; deviation in basal diet commodity costs, port clearance efficiency, and currency volatility against the euro and dollar would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization pace and technology adoption thresholds. Material shifts in South Africa's tolerance limit enforcement or Nigerian import channel structure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Cow Colostrum Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Non-Protein Nitrogen in Feed Market
Veterinary Nutritional Products
South America Feed Vitamins Market