

Mediterranean Pet Nutrition Ingredient Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Pet Nutrition Ingredient Blends Market Insights
Premium pet food manufacturers is reorganizing procurement priorities toward functional ingredient systems with proven bioavailability claims. dsm-firmenich leverages its premix technology portfolio to dominate high-margin vitamin and mineral formulations for canine nutrition. Cargill Animal Nutrition anchors its position through backward integration into marine-derived omega sourcing for fatty acid blends. Royal Canin specializes in breed-specific extruded pellet systems that command veterinary channel loyalty across France and Italy.
Mediterranean Pet Nutrition Ingredient Blends comprise scientifically compounded mixtures of proteins, vitamins, minerals, fatty acids, probiotics, and enzymes formulated to precise nutritional profiles for commercial pet food manufacturing. These blends undergo controlled thermal processing and microencapsulation to preserve active compound stability through extrusion and retort packaging cycles. Proteins and fatty acids lead current value generation due to premium positioning of salmon, insect, and algae-derived alternatives. Canine applications capture the largest volume share while digestive health formulations represent the fastest-expanding margin pool as veterinary endorsement of gut microbiome modulation spreads. Dry mix and extruded pellet formulations occupy distinct equipment lines with powder systems serving smaller batch custom producers and pellet lines feeding high-speed Mars Petcare and Nestlé Purina facilities.
FEDIAF nutritional guidelines, EU REACH chemical registration requirements for novel feed additives, and EFSA safety assessments for probiotic strains collectively elevate barrier costs for new blend suppliers entering Mediterranean markets. EMA veterinary medicine frameworks increasingly intersect with pet nutrition as zootechnical additives face reclassification scrutiny. Stakeholders must monitor evolving EFSA opinions on insect protein novel food status and prepare formulation portfolios for potential regulatory acceleration of alternative protein approvals.
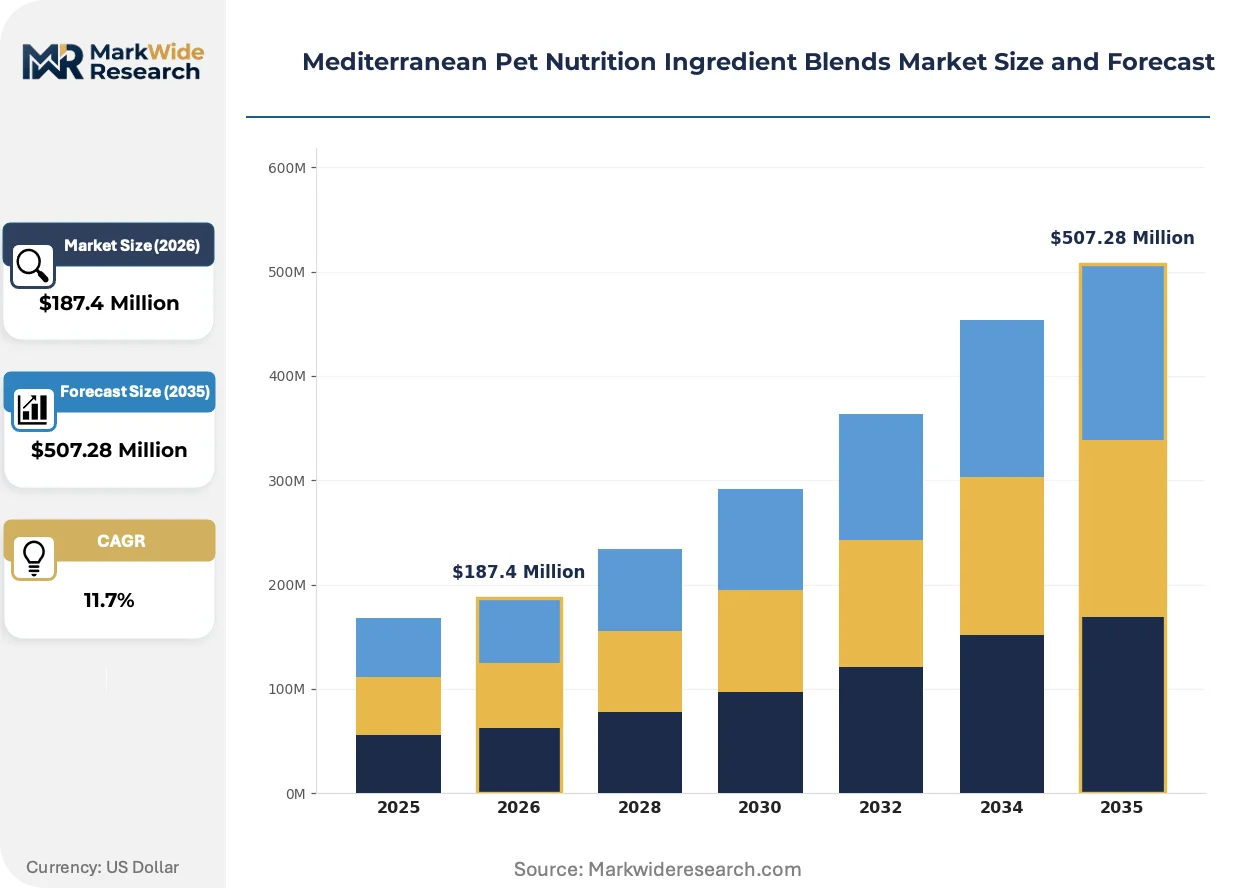
Market Dynamics
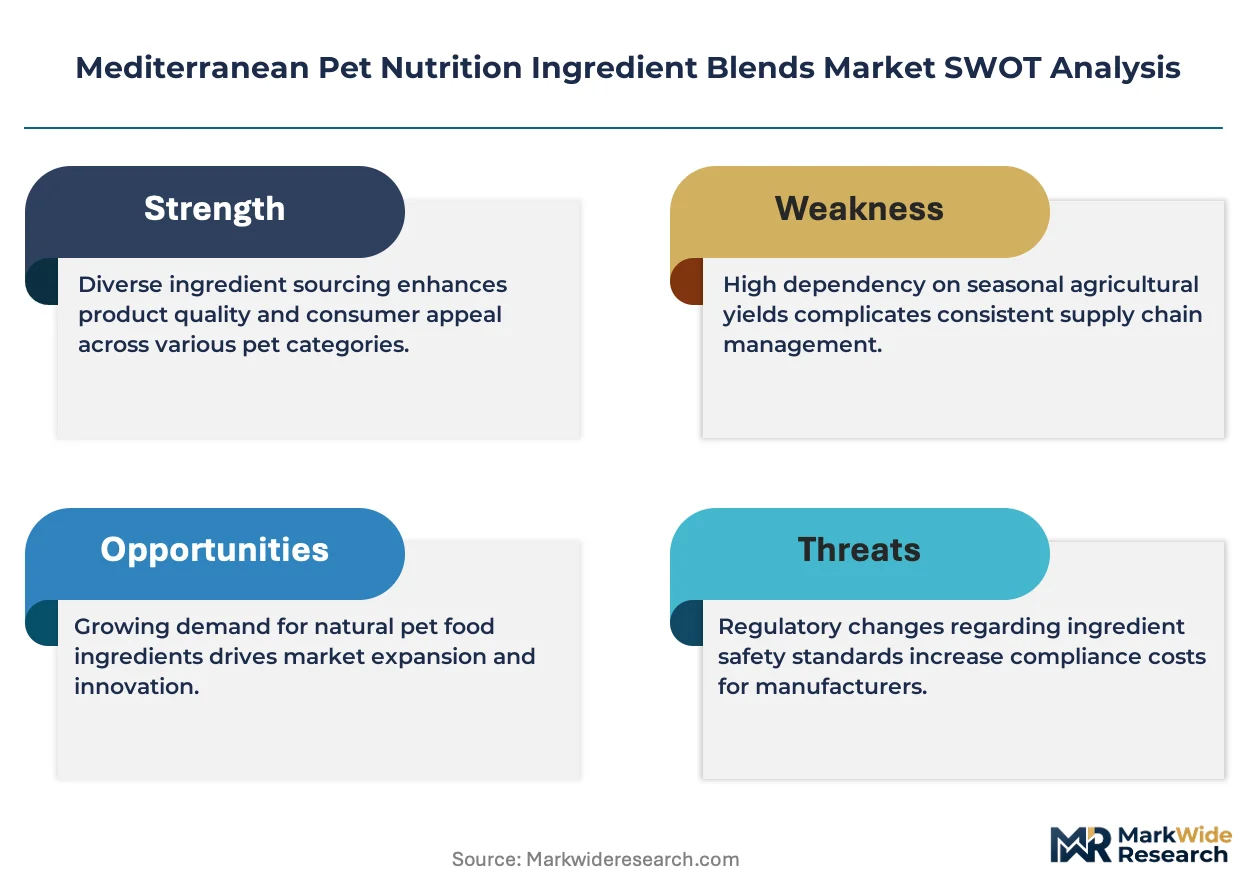
FEDIAF nutritional guideline revisions and EFSA novel food assessments are compressing formulation timelines across Mediterranean pet food manufacturing. Premium manufacturers now face dual pressure to validate bioavailability claims while securing compliant alternative protein sourcing.
Growth Catalysts
- Canine digestive health positioning:Veterinary endorsement of gut microbiome modulation is accelerating demand for probiotic-enriched blends in Spain and Italy.
- REACH streamlined registration:ECHA process improvements for feed additive precursors are reducing time-to-market for novel fatty acid formulations.
- Insect protein cultivation:Black soldier fly farming clusters in southern France are creating captive supply for hypoallergenic pet food applications.
Market Restraints
- Marine omega-3 price volatility:Peruvian anchovy quota fluctuations transmit directly to Mediterranean fatty acid blend input costs.
- Probiotic strain approval bottlenecks:EFSA QPS list updates lag commercial strain development by 18-24 months.
- Algae protein technical limitations:Current extraction yields fail to match salmon meal digestibility scores in extrusion trials.
Strategic Opportunities
- Turkey underpenetration:Istanbul-Ankara corridor pet food production lacks indigenous functional blend suppliers.
- Veterinary channel direct distribution:Bypassing traditional ingredient distributors to service Royal Canin and Hill's prescription diet lines.
- EU Green Deal feed sustainability metrics:Carbon footprint certification creates premium positioning for insect and algae-derived formulations.
Industry Challenges
- Microencapsulation technician scarcity:Thermal stability engineering expertise concentrates in Dutch and German technical institutes.
- Legacy ERP integration:Batch traceability systems from 1990s installations resist FEDIAF-compliant lot tracking requirements.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Pet Nutrition Ingredient Blends Market Trends and Innovations
Precision fermentation and enzymatic protein processing are rewriting cost curves for alternative ingredient production. Formulation science now prioritizes thermal resilience over raw nutrient density.
Microencapsulation via spray-dried lipid matrices is displacing traditional coating methods for heat-sensitive probiotics. Mars Petcare and Nestlé Purina facilities in Barcelona are retrofitting extrusion lines to accommodate these powder systems. The technology is displacing conventional post-extrusion topical application, compressing equipment upgrade cycles to 36 months.
EFSA's evolving opinions on insect protein novel food status are forcing reformulation roadmaps across Mediterranean producers. The regulatory uncertainty has triggered dual-track development portfolios—one compliant with current QPS lists, another anticipating expanded approvals. Spanish and Portuguese manufacturers face the steepest compliance costs due to their reliance on imported novel protein trials.
Direct procurement from precision fermentation startups is replacing traditional distributor relationships for amino acid premixes. Large Mediterranean compounders now source cysteine and taurine directly from biotech suppliers in the Netherlands, bypassing Cargill and DSM-Firmenich distribution networks. This pattern is most visible in French veterinary prescription diet manufacturing, where batch customization requirements exceed distributor technical capabilities.
Mediterranean Pet Nutrition Ingredient Blends Market Segmentation
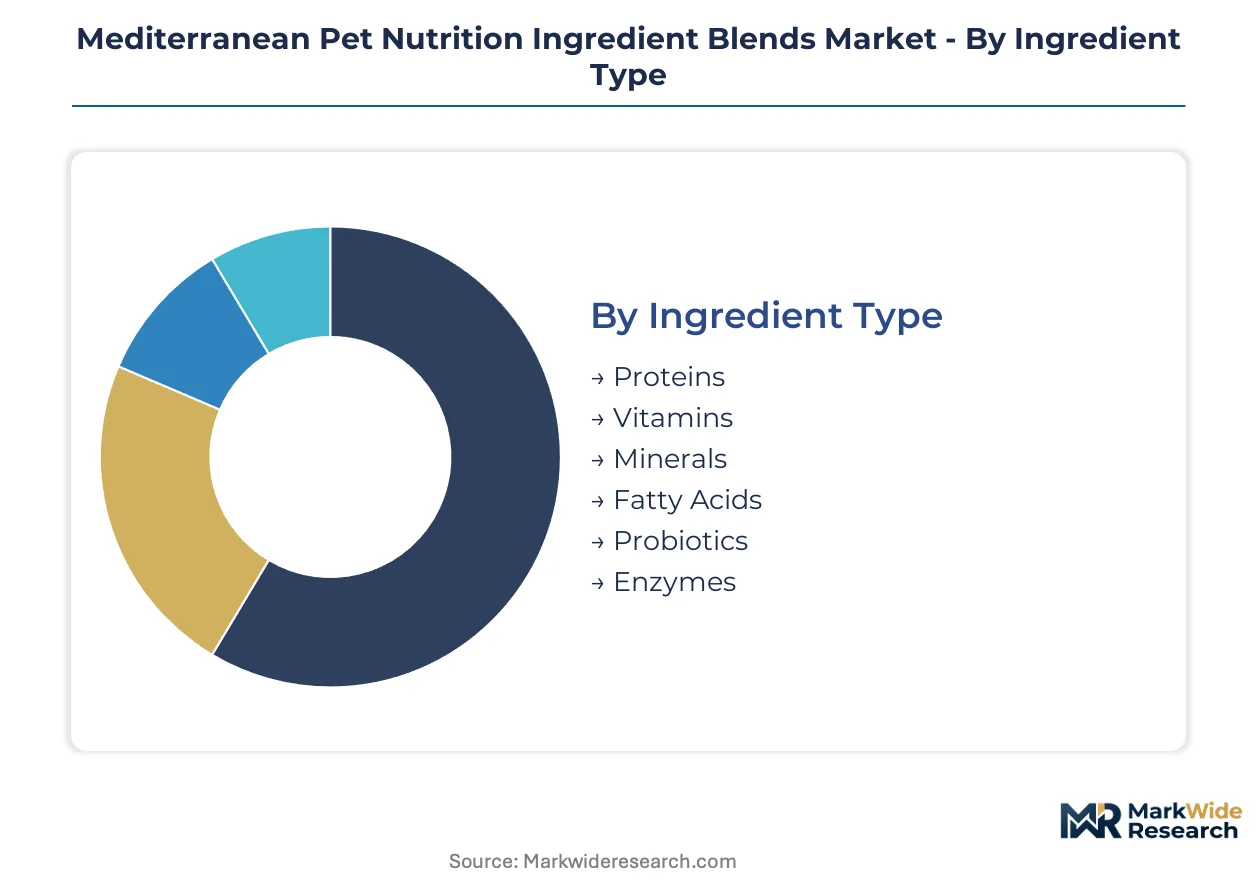
Segmentation in Mediterranean pet nutrition ingredient blends reflects divergent supply chain architectures across ingredient categories. Domestic production clusters in Spain and France favor dry mix and extruded pellet systems, while liquid concentrates and oil emulsions depend heavily on imported marine omega feedstocks through Italian ports.
Ingredient Type:
Proteins and fatty acids concentrate in export-oriented Spanish manufacturing corridors serving Southern European distribution networks, whereas vitamins and probiotics flow primarily through domestic formulation channels in France and Italy.
- Proteins:Salmon meal, insect meal, and algae-derived concentrates form the bulk input for hypoallergenic and premium positioning. Spanish manufacturers in Barcelona source black soldier fly protein from southern French cultivation clusters to bypass volatile Peruvian anchovy supply chains.
- Fatty Acids:Marine-derived omega-3 blends anchor high-margin formulations for skin and coat applications. Italian compounders in Bologna face direct exposure to Peruvian anchovy quota volatility, compressing margin predictability for omega-rich extruded pellets.
- Vitamins:dsm-firmenich premix technology dominates fat-soluble and water-soluble vitamin blends for canine nutrition.
- Minerals:Chelated trace mineral formulations from German suppliers serve veterinary prescription diet manufacturers in Lyon and Milan.
- Probiotics:EFSA QPS list compliance bottlenecks delay strain approvals by 18-24 months against commercial development timelines.
- Enzymes:Phytase and protease blends support digestibility claims in grain-inclusive formulations for price-sensitive Mediterranean markets.
Proteins hold the largest share; momentum sits with probiotics as veterinary endorsement of gut microbiome modulation spreads across Italian and Spanish veterinary channels.
Pet Category:
Volume concentration tilts toward mass-market segments, while margin expansion concentrates in specialized nutrition requiring precise formulation engineering and regulatory navigation.
- Canine:Breed-specific and life-stage formulations command the deepest ingredient customization. Royal Canin and Mars Petcare facilities in Barcelona and Madrid drive demand for extruded pellet systems with embedded fatty acid microencapsulation.
- Feline:Urinary health and hairball management blends require distinct mineral balancing and fiber engineering. French manufacturers in Montpellier specialize in palatability-enhanced powder systems for feline selective feeding behavior.
- Avian:Psittacine and passerine formulations represent a niche export category through Portuguese specialty compounders.
- Exotic Pets:Reptile and amphibian nutritional blends demand precise calcium-phosphorus ratios with limited domestic Mediterranean production.
- Small Mammals:Rabbit and guinea pig fiber-focused formulations align with Mediterranean hay agriculture in northern Spain.
- Reptiles:Vitamin D3 and UVB-responsive calcium blends serve a concentrated hobbyist market through Italian distributors.
Canine applications dominate volume; feline nutrition is climbing the fastest as veterinary channel premiumization accelerates in France.
Blend Formulation:
Equipment intensity and batch scale requirements create sharp segmentation between artisanal compounders and high-speed Mars Petcare and Nestlé Purina facilities.
- Dry Mix:Powder-based protein and mineral blends serve smaller batch custom producers in Portugal and southern Spain. These systems avoid thermal degradation but require rigorous FEDIAF-compliant lot tracking infrastructure.
- Liquid Concentrate:Oil-soluble vitamin and fatty acid suspensions enable post-extrusion topical application. Italian manufacturers near Venice specialize in marine-derived omega emulsions for premium coat conditioning claims.
- Powdered Blend:Spray-dried probiotic matrices and enzyme preparations demand microencapsulation expertise concentrated in Dutch technical institutes.
- Extruded Pellets:High-temperature processing lines in Barcelona and Madrid facilities require thermal stability engineering for heat-sensitive active compounds.
- Oil Emulsions:Water-dispersible fatty acid formulations support wet pet food applications with limited Mediterranean production capacity.
Extruded pellets capture the largest share; dry mix formulations are gaining share fastest as precision fermentation startups enable direct amino acid sourcing bypassing traditional distribution networks.
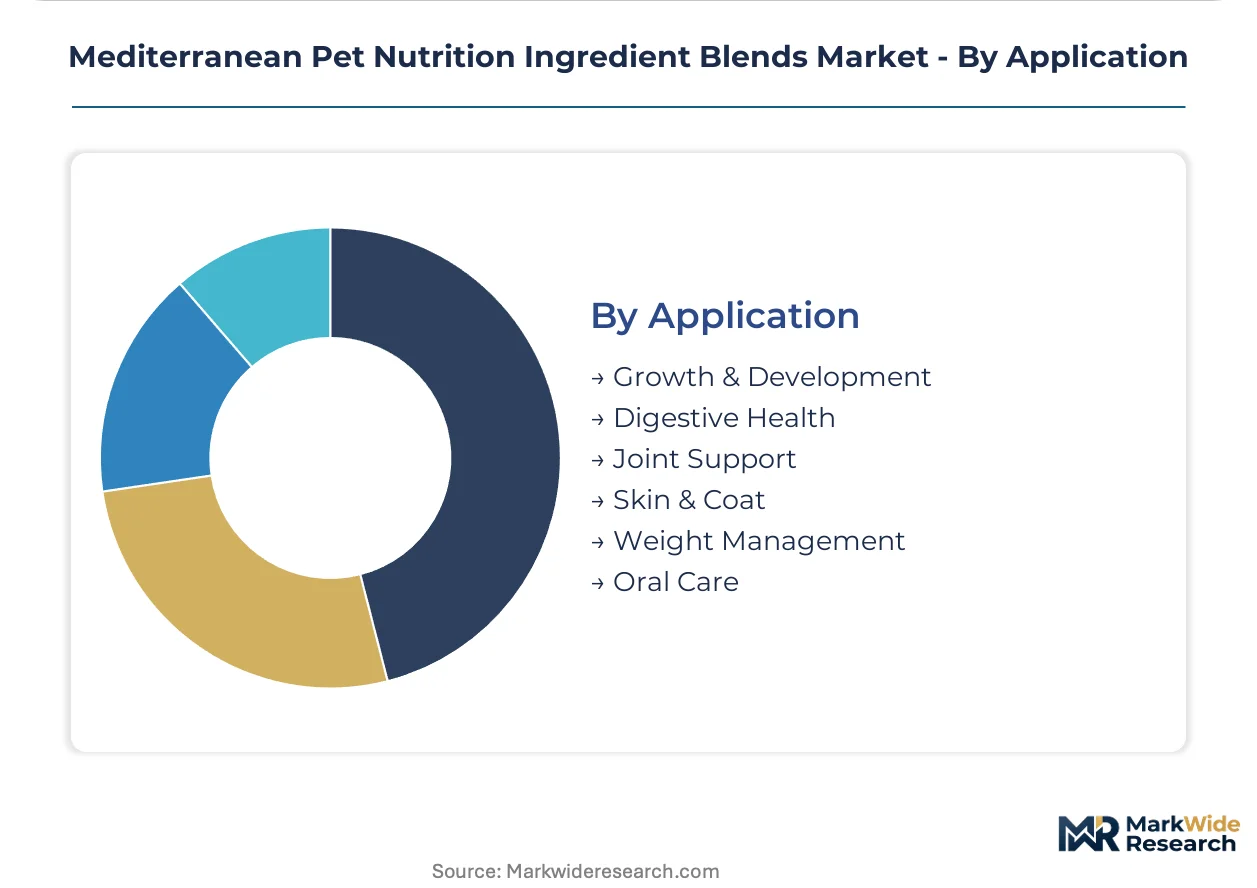
Application:
Regulatory endorsement intensity and veterinary channel penetration determine margin tiering across functional benefit positioning.
- Growth & Development:Puppy and kitten life-stage formulations require precise calcium-phosphorus ratios and DHA enrichment. Spanish manufacturers align with FEDIAF growth curve specifications for large-breed canine orthopedic risk mitigation.
- Digestive Health:Probiotic and prebiotic blends targeting gut microbiome modulation receive accelerating veterinary endorsement. Hill's prescription diet lines in France drive demand for strain-specific formulations with documented transit time improvements.
- Joint Support:Glucosamine and chondroitin blends for senior canine mobility claims face EFSA health claim scrutiny limiting marketing language.
- Skin & Coat:Omega-3 and omega-6 fatty acid ratios dominate positioning with marine source traceability increasingly required.
- Weight Management:High-fiber, reduced-calorie formulations leverage L-carnitine supplementation with limited ingredient differentiation.
- Oral Care:Mechanical cleaning claims and enzymatic plaque inhibition occupy a narrow veterinary-dispensed niche.
Digestive health holds the largest share; joint support is expanding most quickly as aging pet demographics concentrate in Italian and French urban households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish ingredient blend exports flow northward to French and Italian pet food compounders, while marine omega feedstocks enter through Italian ports to supply Mediterranean fatty acid formulation networks.
Spain
Barcelona and Madrid host the densest production facility clusters serving Southern European distribution networks. FEDIAF nutritional guidelines govern formulation compliance across Spanish manufacturing corridors. Black soldier fly protein cultivation in southern France creates captive supply linkages for Barcelona-area hypoallergenic pet food producers.
France
Veterinary prescription diet manufacturing in Lyon and Montpellier drives demand for chelated trace mineral and palatability-enhanced powder systems. EU REACH compliance requirements for novel additives elevate barrier costs for new blend suppliers entering French markets. Royal Canin facilities anchor the veterinary channel loyalty cluster across southeastern manufacturing zones.
Italy
Bologna compounders face direct exposure to Peruvian anchovy quota volatility affecting omega-rich extruded pellet margins. EFSA safety assessments for probiotic strains intersect with Italian veterinary endorsement of gut microbiome modulation. Venice-area manufacturers specialize in marine-derived omega emulsions for premium coat conditioning applications.
Turkey
The Istanbul-Ankara corridor exhibits underpenetration by indigenous functional blend suppliers despite accelerating pet food production capacity. ECHA process improvements for feed additive precursors offer streamlined registration pathways for Turkish market entry. Domestic compounders currently rely on imported premix technology for vitamin and mineral formulations.
Portugal
Smaller batch custom producers in southern Portugal favor dry mix powder systems avoiding thermal degradation risks. FEDIAF-compliant lot tracking infrastructure requirements challenge legacy ERP installations from 1990s manufacturing bases. Psittacine and passerine formulations represent a niche export category through Portuguese specialty compounders.
Mediterranean Pet Nutrition Ingredient Blends Market Competitive Landscape
Player mix skews toward vertically integrated nutrition conglomerates and specialized premix technology providers. Tiered competitive structure separates multinational ingredient suppliers from regional formulation specialists. Strategic archetypes include backward-integrated marine omega sourcers, precision fermentation amino acid disruptors, and veterinary channel-anchored prescription diet manufacturers. Dominant competitive moves encompass direct procurement bypassing traditional distribution networks and microencapsulation technology licensing from Dutch technical institutes.
Among Netherlands-based premix technology providers, dsm-firmenich occupies a position exemplifying high-margin vitamin and mineral formulation dominance. Cargill Animal Nutrition represents the backward-integrated archetype through upstream control over marine-derived omega sourcing. Royal Canin sits within the veterinary channel-anchored tier, commanding prescription diet line loyalty across French and Italian markets.
| Leading Market Players |
|---|
| ADM Animal Nutrition |
| dsm-firmenich |
| Cargill Animal Nutrition |
| BASF |
| Kemin Industries |
| Alltech |
| Royal Canin |
| Mars Petcare |
| Nestlé Purina PetCare |
| Others |
Pricing and Supply Chain Analysis
High-speed extrusion line utilization rates in Barcelona and Madrid facilities create scale-driven price floors that squeeze smaller Portuguese dry-mix compounders. This capacity concentration simultaneously elevates procurement leverage for Mars Petcare and Nestlé Purina while compressing margin buffers for custom batch producers dependent on spot-market protein sourcing.
Pricing Analysis
Microencapsulation technology-generation pricing gaps separate spray-dried lipid matrix systems from conventional post-extrusion coating methods by 15-25% per kilogram of active compound. Three-tier pricing structure across premium veterinary-endorsed, standard commercial, and economy private-label tiers tracks FEDIAF compliance certification and thermal stability engineering sophistication. Cost compression in standard-tier fatty acid blends is intensifying because Peruvian anchovy quota volatility transmits directly to marine omega-3 input costs. Private-label compounders serving price-sensitive Mediterranean markets exhibit highest price sensitivity, while prescription diet manufacturers in Lyon and Montpellier demonstrate lowest sensitivity due to veterinary channel loyalty.
Supply Chain Analysis
Spain and France anchor protein and fatty acid formulation capacity, while Italy concentrates marine-derived omega emulsion production through Venice-area manufacturers. Black soldier fly protein cultivation in southern France and salmon meal processing in northern Spain feed captive supply linkages for hypoallergenic applications. Single-source vulnerability concentrates in Peruvian anchovy fisheries for omega-3 feedstocks, exposing Bologna compounders to quota-driven margin compression. Distribution runs through Barcelona and Madrid production clusters serving Southern European networks, with Italian ports handling import dependency for marine raw materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as precision fermentation startups disintermediate traditional amino acid distribution networks, creating direct procurement ecosystems that bypass established premix technology gatekeepers.
For Market Incumbents: Consolidate microencapsulation technology licensing relationships with Dutch technical institutes before precision fermentation entrants achieve thermal stability parity. Lock in long-term black soldier fly protein offtake from southern French cultivation clusters to substitute volatile marine omega supply chains. dsm-firmenich and Cargill Animal Nutrition face direct sourcing bypass threats from biotech suppliers in the Netherlands. For New Entrants and Emerging Players: Differentiate on EFSA QPS list pre-compliance positioning, securing strain-specific probiotic approvals 18-24 months ahead of commercial competitors. Target the Istanbul-Ankara corridor where indigenous functional blend suppliers remain underpenetrated despite accelerating pet food production capacity. Pursue veterinary channel direct distribution agreements with Royal Canin and Hill's prescription diet lines to bypass traditional ingredient distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation amino acid disruptors with demonstrated thermal stability engineering partnerships. Long-term viability over 5-10 year windows rests on regulatory acceleration of alternative protein approvals and EU Green Deal sustainability certification traction. Signal to watch: EFSA opinions on insect protein novel food status crossing from assessment to authorization, triggering reformulation roadmap execution across Spanish and Portuguese manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Protein Cultivation | Captive black soldier fly supply insulates Barcelona compounders from Peruvian anchovy quota volatility. |
| Microencapsulation Technology Licensing | Dutch technical institute partnerships preserve probiotic viability through Mars Petcare extrusion lines. |
| Veterinary Channel Direct Distribution | Bypassing traditional distributors captures margin from Royal Canin prescription diet loyalty in France and Italy. |
| EFSA QPS List Pre-Compliance Investment | Early probiotic strain documentation compresses 18-24 month approval bottlenecks against commercial timelines. |
| EU Green Deal Sustainability Certification | Carbon footprint positioning creates premium tier separation for insect and algae-derived formulations. |
Research Methodology
Initial hypotheses were tested against primary input from pet food formulation scientists, veterinary nutritionists, procurement directors at compounder facilities, and regulatory affairs specialists at EFSA and FEDIAF, then refined through secondary validation against EU REACH registration databases, EFSA QPS list publications, FEDIAF nutritional guideline documents, and customs trade data for marine-derived feedstock imports. Bottom-up segmentation modeling triangulated with top-down market sizing from production capacity disclosures at Barcelona and Madrid facilities.
Variance decomposition across ingredient type, pet category, blend formulation, and application dimensions shaped analytical framework construction over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating EFSA regulatory timeline assumptions and veterinary endorsement diffusion patterns. Forecast inputs included precision fermentation capacity buildout timelines and black soldier fly cultivation cluster expansion in southern France.
The analysis sits within stated boundaries; outcomes outside EFSA novel food authorization acceleration or sustained Peruvian anchovy quota stability would require recalibration. Forecasts reflect documented assumptions regarding probiotic strain approval timelines and alternative protein extraction yield improvements. Recalibration cycles align with material shifts in EFSA regulatory opinions and EU Green Deal feed sustainability metric adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.