
 Asia Pacific Feed Phytogenics Market | 2026-2036
Asia Pacific Feed Phytogenics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Feed Phytogenics Market Analysis
Multi-source procurement of botanical raw materials is pivoting toward captive cultivation partnerships as supply volatility reshapes cost structures. Cargill Incorporated leverages its integrated supply chain across Indonesian and Australian operations to secure consistent essential oil inputs. Biomin GmbH anchors its competitive stance through specialized mycotoxin-binding phytogenic combinations developed for tropical climates. Kemin Industries Inc differentiates via vertically controlled cultivation of proprietary oregano and cinnamon varietals in Indian growing regions.
Feed phytogenics comprise bioactive compounds derived from herbs, spices, essential oils, and oleoresins formulated into animal feed to enhance nutrient utilization, gut integrity, and immune modulation without antibiotic residues. Standardized active ingredient concentrations—typically carvacrol, thymol, cinnamaldehyde, or capsaicinoids measured in parts per million—determine efficacy thresholds in commercial formulations. Essential oils command the dominant margin pool due to concentrated bioactivity and lower inclusion rates, while herbal extracts expand fastest among smallholder cooperatives seeking cost-accessible alternatives. Poultry end-use absorbs the greatest volume, though aquaculture applications gain traction as shrimp and finfish producers confront stringent export residue limits.
China's Ministry of Agriculture and Rural Affairs enforces the national ban on antibiotic growth promoters in feed, compelling reformulation toward phytogenic alternatives across the country's integrated poultry and swine sectors. India's FSSAI and BIS frameworks govern botanical feed additive safety thresholds, while Australia's APVMA registration requirements shape import-access conditions for European and North American suppliers. Stakeholders must monitor evolving maximum residue limits in destination meat markets and align phytogenic portfolios with each country's feed safety certification pathways.
Market Dynamics
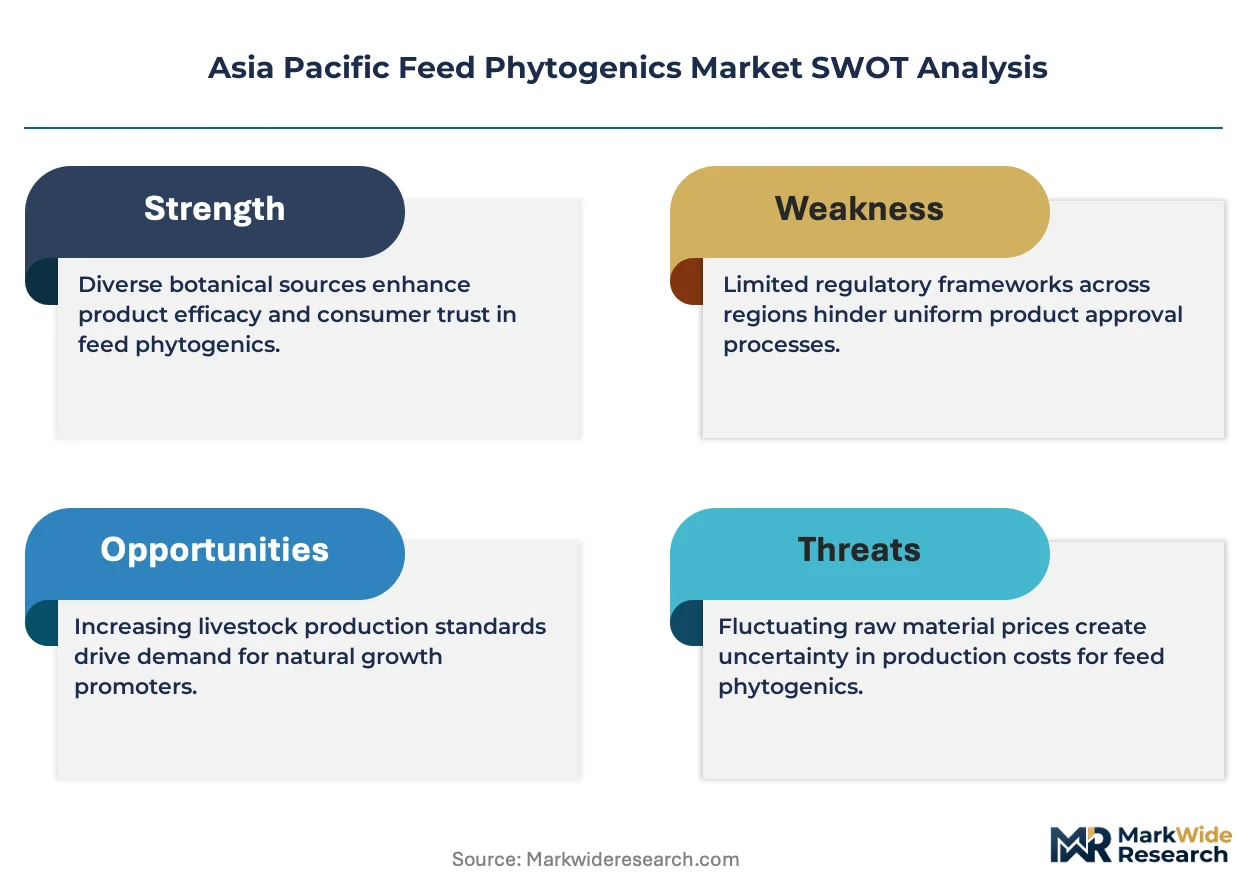
Antibiotic growth promoter bans across Southeast Asian veterinary drug regulations are forcing feed millers to reformulate rations around botanical bioactives, restructuring procurement relationships and technical service requirements throughout the supply chain.
Growth Catalysts
- China's AGP prohibition:The Ministry of Agriculture and Rural Affairs ban on antibiotic growth promoters in feed compels integrated poultry and swine operations to adopt phytogenic alternatives at commercial scale.
- Export residue compliance:Shrimp and finfish producers targeting EU and North American markets deploy phytogenics to meet stringent maximum residue limits in destination meat markets.
- Essential oil concentration:Standardized carvacrol and thymol formulations deliver measurable gut integrity improvements without withdrawal periods, accelerating technical validation cycles.
Market Restraints
- Botanical input volatility:Wild-harvested oregano and cinnamon supplies from Indonesian archipelago regions face climate-induced harvest fluctuations that destabilize formulation costs.
- Registration pathway friction:Australia's APVMA registration requirements for novel phytogenic actives impose multi-year assessment timelines that delay market entry for European suppliers.
- Synthetic alternative competition:Organic acid blends and probiotic formulations compete for the same reformulation budgets in cost-sensitive swine operations.
Strategic Opportunities
- Vietnamese aquaculture expansion:Mekong Delta shrimp producers confronting EU export residue standards represent an underpenetrated demand pocket for mycotoxin-binding phytogenic combinations.
- Captive cultivation partnerships:Backward integration into proprietary herb cultivation in Indian growing regions secures supply consistency and active ingredient standardization.
- Smallholder cooperative channels:Herbal extract formulations tailored for cost-accessible inclusion rates open volume opportunities among fragmented poultry operations in Philippines and Indonesia.
Industry Challenges
- Phytochemistry expertise scarcity:Feed compounders lack in-house analytical capability to validate carvacrol and cinnamaldehyde concentrations in incoming botanical raw materials.
- Multi-jurisdiction compliance complexity:India's FSSAI and BIS frameworks impose divergent botanical feed additive safety thresholds that complicate regional product portfolio design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Feed Phytogenics Market |
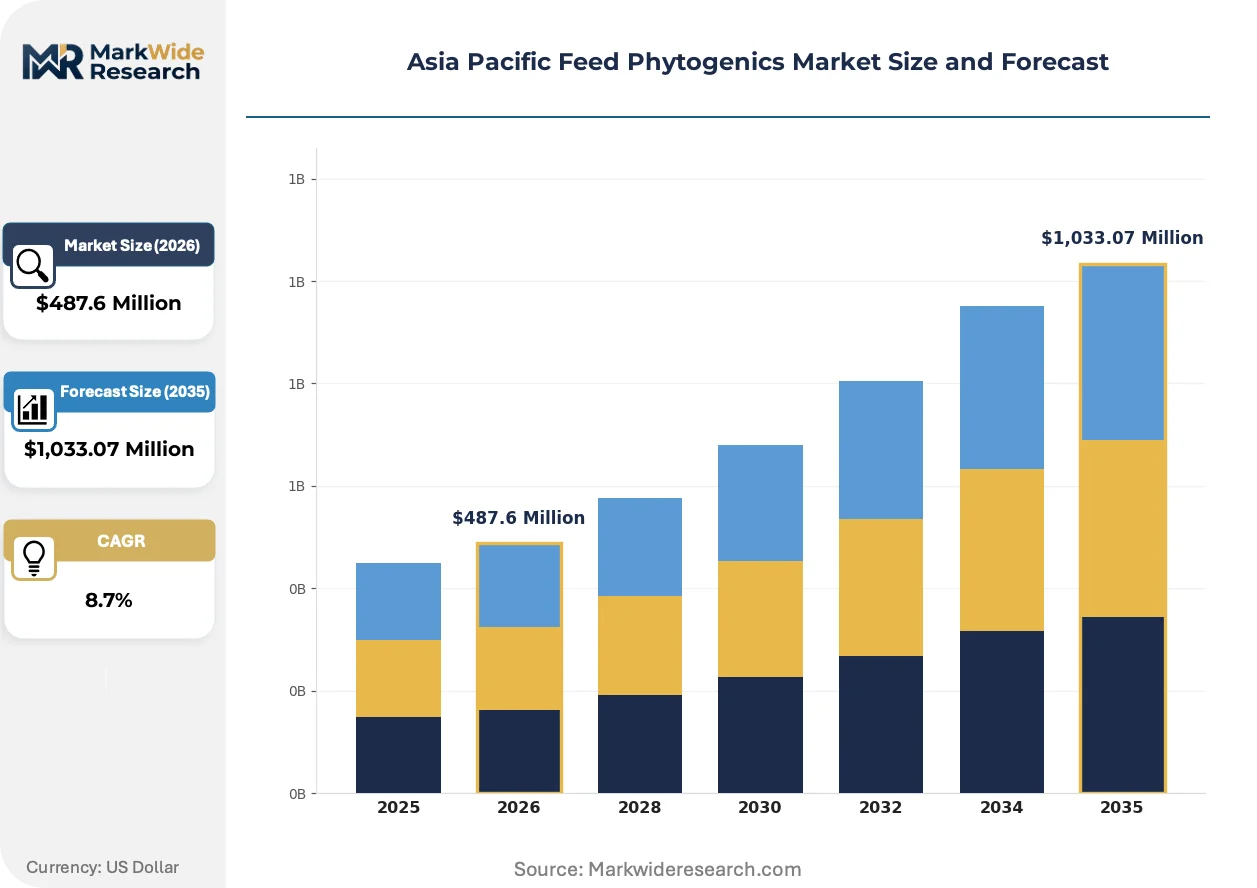
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Spices, Resins End User: Poultry, Swine, Ruminants, Aquaculture Application: Growth Promotion, Digestive Health, Immunity Boosting, Feed Preservation Distribution Channel: Direct Sales, Distributors, Online Retail, Agrochemical Retailers |
| Companies Covered | Cargill Incorporated, Adisseo France SAS, Biomin GmbH, Kemin Industries Inc, Archer Daniels Midland Company, DSM-Firmenich, Pancosma, Natural Remedies, Phytobiotics Futterzusatzstoffe GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Feed Phytogenics Market Emerging Trajectories
Formulation science is converging with precision agriculture tools to enable real-time feed optimization, while regulatory harmonization pressures and buyer consolidation reshape commercial relationships across the value chain.
Microencapsulation technology for heat-stable essential oil delivery is unifying previously separate feed processing and phytogenic manufacturing competencies. Large integrators in Shandong province now specify encapsulated thymol formulations that survive pelleting temperatures above 85°C. This convergence is compressing the supplier base toward partners with dual capabilities in feed technology and botanical extraction.
China's national ban on antibiotic growth promoters in feed, enforced by the Ministry of Agriculture and Rural Affairs, mandates complete reformulation across the country's integrated livestock sectors. The regulation eliminates legacy in-feed medication protocols and redirects technical service investments toward phytogenic efficacy validation. Swine operations in Guangdong province are responding fastest, establishing dedicated phytogenic trial facilities to benchmark gut health outcomes against historical antibiotic performance baselines.
Direct procurement relationships between feed millers and botanical cultivators are displacing traditional trader-mediated supply chains. Large poultry integrators in Thailand and Vietnam now contract dedicated oregano and cinnamon plots through season-long offtake agreements. This pattern is most visible among export-oriented operations seeking traceability documentation for EU and North American destination markets.
Asia Pacific Feed Phytogenics Market Segmentation
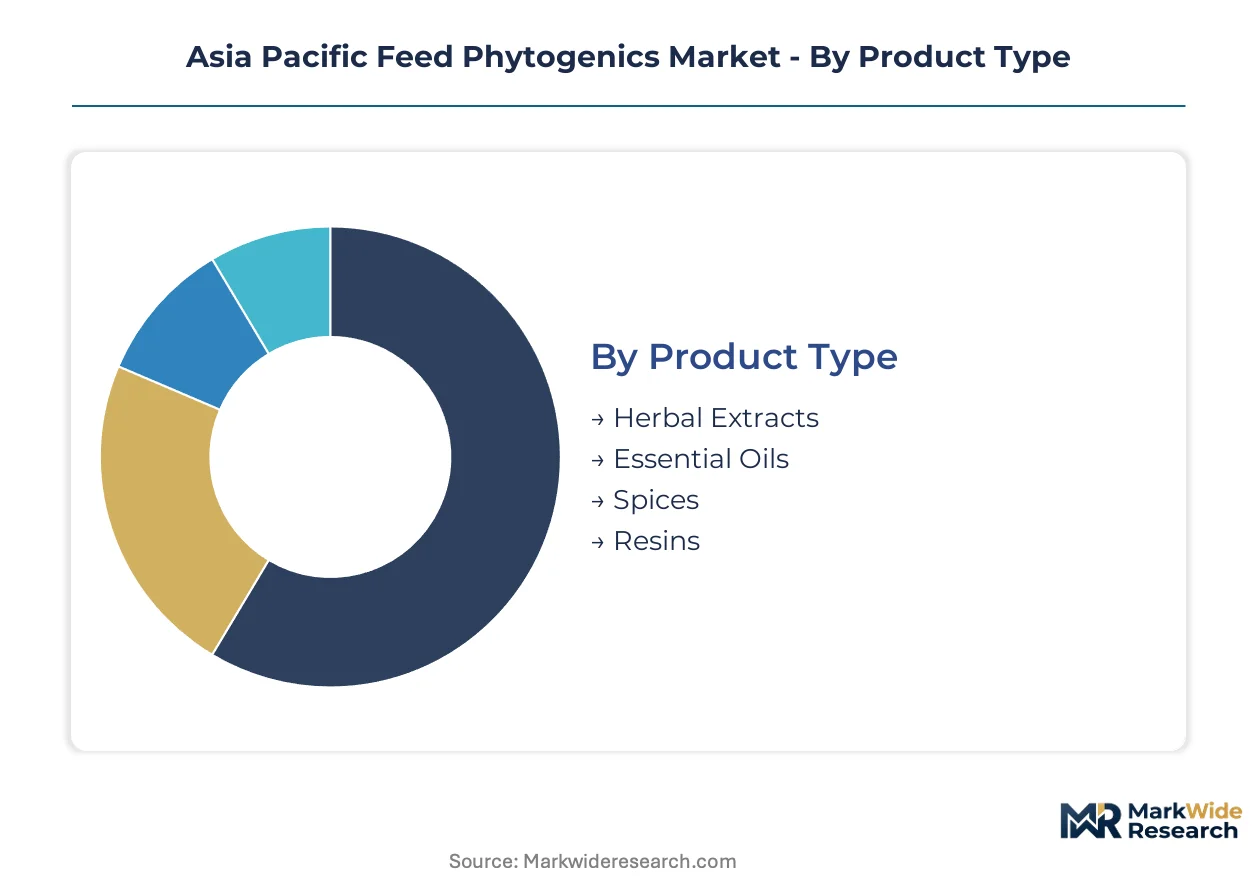
Segmentation in feed phytogenics reveals divergent margin structures across product formats and channel economics. Distinct technical requirements by end-use species create specialization barriers that reshape competitive positioning.
Product Type:
Essential oils command premium pricing due to concentrated bioactivity and lower inclusion rates, while herbal extracts serve volume-driven smallholder segments.
- Essential Oils:Concentrated carvacrol, thymol, and cinnamaldehyde formulations measured in parts per million deliver standardized gut integrity improvements. Demand concentrates among large poultry integrators in China's Shandong province seeking heat-stable encapsulated variants for high-temperature pelleting.
- Herbal Extracts:Cost-accessible botanical preparations with variable active ingredient profiles suit budget-constrained operations. Philippine and Indonesian smallholder cooperatives drive volume expansion as they confront antibiotic growth promoter bans with limited reformulation budgets.
- Spices:Whole or ground cinnamon, oregano, and capsicum preparations retain native phytochemical matrices for traditional feed compounding practices.
- Resins:Oleoresin concentrates provide intermediate potency between crude botanicals and refined essential oils for mid-tier formulation needs.
Today's leader: Essential Oils. Tomorrow's challenger: Herbal Extracts.
End User:
Species-specific digestive physiology and regulatory exposure create divergent phytogenic adoption trajectories across livestock categories.
- Poultry:Broiler and layer operations absorb the greatest phytogenic volume due to short production cycles and intensive gut health management requirements. Southeast Asian integrators accelerate reformulation as national veterinary drug regulations tighten antibiotic growth promoter restrictions.
- Aquaculture:Shrimp and finfish producers deploy phytogenics to satisfy EU and North American export residue limits. Mekong Delta operations in Vietnam represent underpenetrated demand for mycotoxin-binding tropical formulations.
- Swine:Grower-finisher operations in Guangdong province establish dedicated trial facilities to benchmark phytogenic gut health outcomes against historical antibiotic performance baselines.
- Ruminants:Dairy and beef cattle applications remain nascent due to rumen microbial complexity and longer validation timelines for feed conversion metrics.
Poultry dominates current procurement volumes. Aquaculture applications are expanding most quickly.
Application:
Functional positioning determines technical service intensity and regulatory documentation requirements across use cases.
- Growth Promotion:Direct replacement for antibiotic growth promoters requires rigorous efficacy validation against historical performance benchmarks. China's Ministry of Agriculture and Rural Affairs enforcement redirects technical service investments toward phytogenic validation protocols.
- Digestive Health:Gut integrity modulation through antimicrobial and anti-inflammatory bioactives attracts reformulation investment from operations seeking residue-free production systems.
- Immunity Boosting:Immunomodulatory phytogenic applications target disease challenge periods with targeted supplementation protocols.
- Feed Preservation:Antioxidant and antimicrobial properties extend feed stability without synthetic preservative residues.
Growth Promotion commands the steepest expansion trajectory. Digestive Health holds established technical validation.
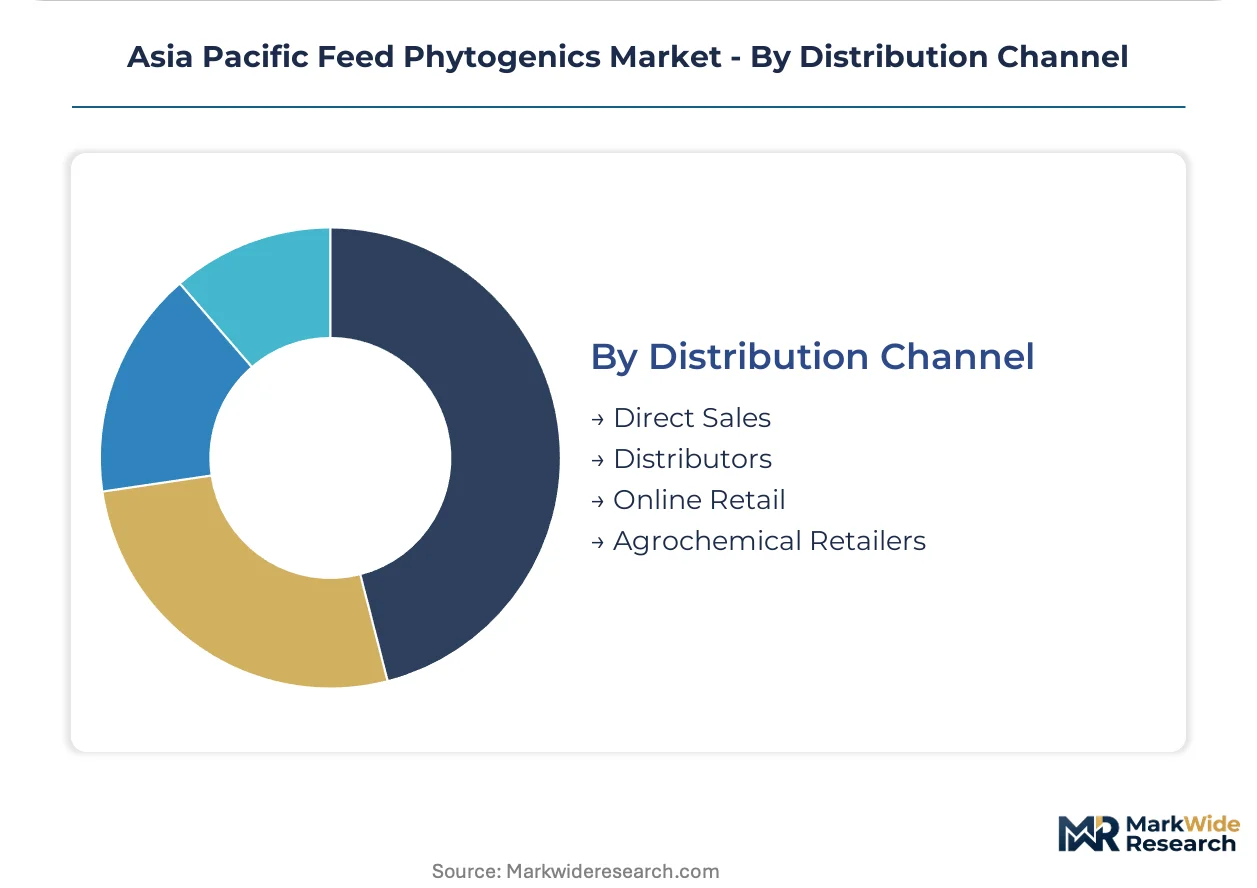
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and traceability documentation needs.
- Direct Sales:Large integrators in Thailand and Vietnam contract dedicated botanical plots through season-long offtake agreements, displacing trader-mediated supply chains for traceability documentation.
- Distributors:Regional feed additive specialists provide formulation technical service and inventory management for mid-scale compounders.
- Agrochemical Retailers:Rural supply points serve fragmented smallholder operations with basic herbal extract formulations.
- Online Retail:Digital procurement channels emerge for standardized product grades with established efficacy documentation.
Direct Sales anchors premium segment access. Distributors mediate mainstream volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors regional feed phytogenic procurement through its dense cluster of integrated poultry operations. China's Ministry of Agriculture and Rural Affairs enforces the national antibiotic growth promoter ban, redirecting technical service investments toward botanical validation protocols. Guangdong swine operations establish dedicated trial facilities to benchmark gut health outcomes against historical antibiotic performance baselines.
China
Integrated livestock sectors in Shandong and Guangdong provinces drive concentrated phytogenic demand from large feed millers. The Ministry of Agriculture and Rural Affairs prohibition on in-feed antibiotics compels complete reformulation across poultry and swine operations. Encapsulated thymol formulations that survive pelleting temperatures above 85°C now dominate procurement specifications in these coastal manufacturing clusters.
India
Proprietary oregano and cinnamon cultivation in southern growing regions supplies standardized active ingredients for export-oriented formulations. FSSAI and BIS frameworks impose divergent botanical feed additive safety thresholds that complicate regional product portfolio design. Karnataka and Tamil Nadu processing facilities concentrate extraction capacity for carvacrol and cinnamaldehyde concentrates.
Vietnam
Mekong Delta shrimp producers confronting EU export residue standards represent underpenetrated demand for mycotoxin-binding tropical phytogenic combinations. National veterinary drug regulations tighten antibiotic restrictions in aquaculture feed compounding. Bac Lieu and Ca Mau provinces deploy phytogenics to satisfy destination market documentation requirements.
Thailand
Large poultry integrators contract dedicated botanical plots through season-long offtake agreements, displacing trader-mediated supply chains. Veterinary drug regulations under the Department of Livestock Development accelerate phytogenic adoption in broiler operations. Nakhon Ratchasima and Chonburi provinces concentrate feed manufacturing capacity serving export-oriented processing facilities.
Australia
APVMA registration requirements for novel phytogenic actives impose multi-year assessment timelines that delay market entry for European suppliers. Export residue compliance protocols shape import-access conditions for botanical feed additives. Queensland and New South Wales cattle operations remain nascent adopters due to rumen microbial complexity and extended validation timelines.
Asia Pacific Feed Phytogenics Market Vendor Landscape
Global majors compete with regional champions across formulation technology and captive supply arrangements. The supplier base compresses toward partners with dual capabilities in feed technology and botanical extraction. Three archetypes dominate: integrated agribusiness conglomerates with captive cultivation networks, specialized phytogenic developers with tropical climate expertise, and diversified feed additive houses with essential oil concentration capabilities. Competitive moves center on backward integration into proprietary herb cultivation and microencapsulation capacity expansion.
Among integrated supply chain operators, Cargill Incorporated anchors procurement relationships across Indonesian and Australian operations. Biomin GmbH exemplifies the specialized phytogenic developer archetype through its positioning in tropical climate applications. Kemin Industries Inc occupies the vertically controlled cultivation tier with proprietary varietal development in Indian growing regions.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Adisseo France SAS |
| Biomin GmbH |
| Kemin Industries Inc |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Pancosma |
| Natural Remedies |
| Phytobiotics Futterzusatzstoffe GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap cultivators across India's Karnataka and Tamil Nadu regions anchor upstream supply, translating crop-to-crop harvest variability into volatile contract pricing that large integrators mitigate through season-long offtake guarantees. Their fragmented ownership structure limits collective bargaining power against concentrated feed miller procurement desks in Shandong and Guangdong provinces.
Pricing Analysis
Essential oil input costs pass through directly to finished formulation pricing, with carvacrol and thymol concentrates commanding premium-mid-economy pricing differentiation based on standardization grade and heat-stability certification. Price differentiation separates encapsulated variants surviving 85°C pelleting from basic herbal extracts. Cost compression in economy-tier herbal preparations is intensifying because smallholder cooperatives in Philippines and Indonesia confront antibiotic growth promoter bans with limited reformulation budgets. Large poultry integrators exhibit lowest price sensitivity due to traceability documentation requirements for EU export markets.
Supply Chain Analysis
Dual-sourcing requirements from Thailand's Department of Livestock Development-qualified feed millers mandate parallel qualification of Indonesian and Indian botanical suppliers to mitigate single-source vulnerability during monsoon harvest disruptions. Geographic supply concentration centers on Indonesia for wild-harvested cinnamon, India for proprietary oregano cultivation, and Vietnam for Mekong Delta aquaculture distribution hubs. Raw material dependencies rest on seasonal oleoresin extraction capacity, climate-sensitive flowering cycles, and solvent availability for concentration processes. Tariff exposure runs through ASEAN-India trade corridors for processed essential oils. Distribution feeds from regional feed additive specialists into compounder blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific feed phytogenics function as a geographic-arbitrage play: manufacturing cost differentials between Indian cultivation zones and Chinese processing clusters exceed the logistics expense of cross-border oleoresin shipment, rewarding integrated supply chain control.
For Market Incumbents: Lock in captive cultivation partnerships across southern Indian growing regions before land lease costs escalate under competing spice export demand. Expand microencapsulation capacity in Shandong province to meet integrator specifications for heat-stable thymol formulations, defending against synthetic organic acid blends competing for swine reformulation budgets. For New Entrants and Emerging Players: Launch via direct sales to Mekong Delta shrimp producers confronting EU export residue standards, the most penetrable aquaculture segment lacking mycotoxin-binding tropical formulations. Target Vietnamese smallholder cooperatives with cost-accessible herbal extract portfolios distributed through agrochemical retailer channels bypassing established distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized phytogenic developers with tropical climate expertise but limited backward integration. Long-term viability across the analysis window hinges on regulatory enforcement durability of China's Ministry of Agriculture and Rural Affairs antibiotic growth promoter prohibition. Watch for inflection in Australian APVMA registration timeline compression as signal of European supplier market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Cultivation | Secures carvacrol supply consistency against Indonesian climate volatility for Shandong integrators. |
| Microencapsulation Capacity Expansion | Enables thymol formulations surviving Guangdong province pelleting temperatures above 85°C. |
| Tropical Climate Formulation Development | Addresses Mekong Delta shrimp mycotoxin challenges under Vietnam's tightening veterinary drug regulations. |
| Direct Sales Channel Establishment | Displaces trader-mediated supply chains for Thai poultry integrators seeking EU traceability documentation. |
| Multi-Jurisdiction Regulatory Certification | Aligns product portfolios with India's divergent FSSAI and BIS botanical safety thresholds. |
Methodological Framework
Coverage spans China, India, Vietnam, Thailand, and Australia, with primary inputs from each market combining structured interviews with feed compounder procurement directors, essential oil extraction facility managers, veterinary regulatory affairs specialists, and aquaculture export compliance officers. Secondary validation drew from China's Ministry of Agriculture and Rural Affairs enforcement notices, India's BIS feed additive standards, Australian APVMA registration databases, ASEAN customs trade flows, and integrated poultry operator technical service disclosures. Bottom-up volume modeling and top-down value triangulation cross-checked segment allocation.
Rate-of-change decomposition separated volume growth from price evolution across the projection horizon, modeling segmentation dimensions including product type tier, end-use species, functional application, and distribution channel structure. CAGRs derived from regression against historical antibiotic growth promoter phase-out patterns in comparable regulatory jurisdictions. Forecast inputs incorporated climate-induced harvest variance coefficients and encapsulation technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement acceleration or extended Australian APVMA assessment delays. Deviation in China's provincial implementation uniformity of antibiotic growth promoter prohibitions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market