
 Agroscience Market | 2026-2036
Agroscience Market Size, Share, and Industry Trends Forecast 2026-2036
Agroscience Market Intelligence
Biological input licensing revenue is rewriting profit allocation across the agroscience value chain. Bayer AG leverages its germplasm library to sustain premium positioning in seed treatment portfolios. Corteva Agriscience anchors its competitive stance through proprietary CRISPR-edited trait stacks. Syngenta Group dominates biologicals development through integrated fermentation platforms.
Agroscience encompasses the interdisciplinary application of biology, chemistry, and data analytics to optimize crop productivity, soil health, and pest management through inputs containing active biological or synthetic agents formulated to specific concentration thresholds. Its primary commercial purpose is to protect and enhance agricultural yield per hectare across controlled and open-field environments. Fertilizers command the largest product type share due to irreplaceable macronutrient replacement cycles, while seed treatment within application categories attracts the fastest margin expansion as farmers prioritize genetic trait protection over broadcast spraying. The end use industry dimension shows commercial farming as the mature volume base, with organic farming representing the fastest-growing demand pool where biological pesticides and non-synthetic soil enhancers command price premiums.
The EPA regulates pesticide registration and residue tolerance under FIFRA and FFDCA, while the EU Green Deal and REACH framework constrain synthetic active ingredient approvals and mandate sustainability disclosures across supply chains. India's Central Insecticides Board enforces BIS-compliant formulation standards that condition market access for imported agrochemicals. Stakeholders must monitor regulatory divergence between jurisdictions accelerating separate product development tracks for biological versus synthetic portfolios.
Market Dynamics
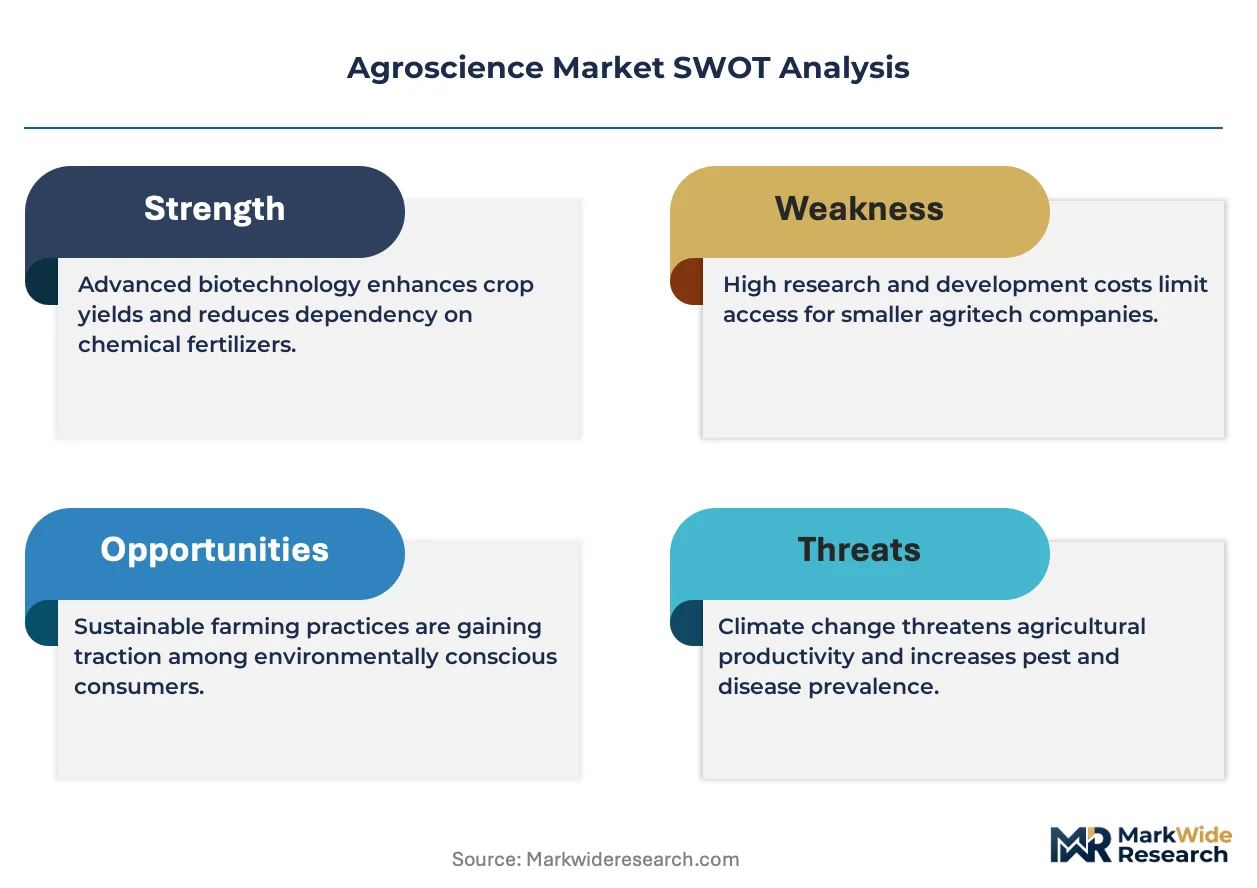
Biological input registration acceleration under the EU Green Deal is fragmenting R&D pipelines, forcing parallel development tracks for synthetic and bio-based portfolios across multinational agroscience firms.
Growth Catalysts
- Seed treatment premiumization:Commercial farming operations in Brazil's Cerrado are prioritizing genetic trait protection over broadcast spraying, compressing application windows and raising formulation value per hectare.
- Farm to Fork residue tightening:The EU Green Deal's accelerated MRL reductions are pulling biological pesticide registrations forward, opening shelf space for microbial and biochemical alternatives ahead of synthetic phase-outs.
- CRISPR trait stacking:Proprietary gene-edited seed platforms are reducing grower dependence on external chemical interventions, embedding protection directly into germplasm and capturing margin upstream.
Market Restraints
- Active ingredient supply concentration:China dominates intermediate manufacturing for synthetic agrochemicals, exposing formulators to export license volatility and freight cost spikes.
- Biological formulation instability:Microbial viability decay in storage limits distribution radius and forces cold chain investments that compress rural margin structures.
- REACH compliance cost escalation:The EU's substance evaluation backlog is extending registration timelines for novel synthetics, trapping capital in regulatory limbo for 4-7 year cycles.
Strategic Opportunities
- India's Punjab-Haryana belt consolidation:Mechanized rice-wheat systems in this corridor are primed for precision application services bundling seed treatment with soil microbiome diagnostics.
- Fermentation platform integration:Converging industrial biotechnology with existing agrochemical manufacturing assets enables captive production of Bacillus-based biofungicides at synthetic cost parity.
- Direct-to-farm digital channels:Agronomy-as-a-service platforms are disintermediating traditional distributor networks, capturing farmer data and locking in input loyalty through prescription algorithms.
Industry Challenges
- Microbial strain IP fragmentation:Patent thickets around biocontrol organisms are forcing cross-licensing negotiations that delay product launches and inflate legal overhead.
- Field trial workforce scarcity:Qualified agronomists capable of designing statistically valid biological efficacy trials are concentrating in Brazil and the Netherlands, creating recruitment bottlenecks for expansion markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agroscience Market |
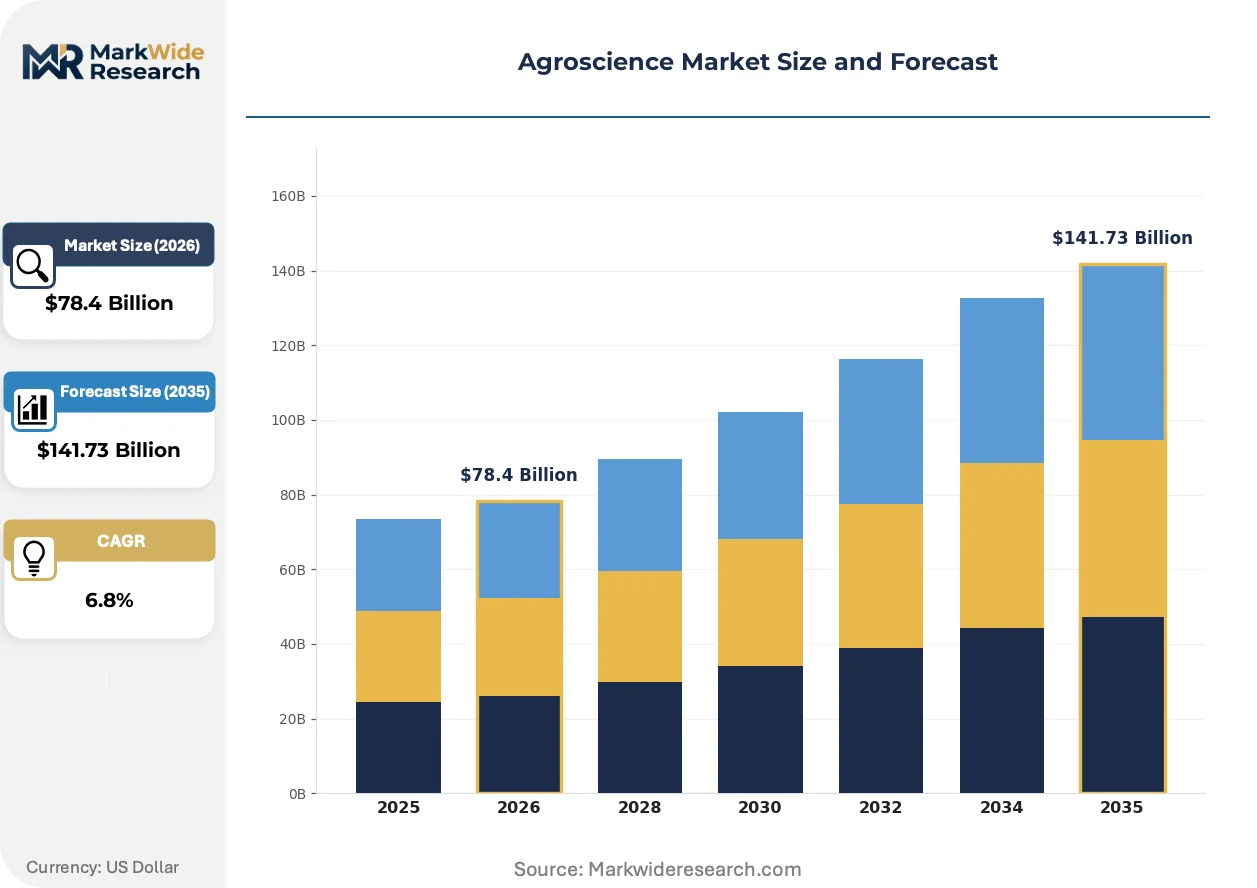
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fertilizers, Herbicides, Seeds Application: Crop Protection, Soil Enhancement, Pest Control, Seed Treatment End Use Industry: Agriculture, Horticulture, Commercial Farming, Organic Farming Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | BASF SE, Nutrien Ltd., Bayer AG, UPL Limited, Sumitomo Chemical, Corteva Agriscience, FMC Corporation, ADAMA, Syngenta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agroscience Market Strategic Shifts & Innovations
Sensor-enabled agronomy is compressing the feedback loop between field observation and input application, replacing calendar-based spraying with biometric-triggered interventions that match chemistry to plant stress signatures.
Hyperspectral imaging mounted on UAVs is digitizing early-stage disease detection in row crops. Large-scale corn and soybean operators in the US Midwest are deploying fleet-scale drone networks to flag fungal pressure before visible symptoms emerge. Bayer and Syngenta are digitizing their advisory services around these data streams, converting hardware sales into recurring analytics subscriptions.
The EU Green Deal's Farm to Fork strategy is mandating 50% synthetic pesticide reduction targets by 2030, forcing reformulation of legacy portfolios toward microbial and semiochemical alternatives. Germany's Federal Office of Consumer Protection and Food Safety is fast-tracking biological active substance approvals, compressing evaluation windows from 36 to 18 months for low-risk candidates. This regulatory tailwind is pulling R&D investment toward fermentation-derived bioinsecticides and pheromone mating disruption systems.
Farmer procurement patterns are pivoting from brand loyalty to outcome-guaranteed performance contracts. Brazilian mega-farms in Mato Grosso are unbundling seed, chemistry, and agronomic advice, selecting inputs through competitive tender against yield benchmarks rather than historical supplier relationships. This behavior shift is fragmenting market share concentration and elevating the role of independent agronomic consultancies as gatekeepers to input decisions.
Agroscience Market Segmentation
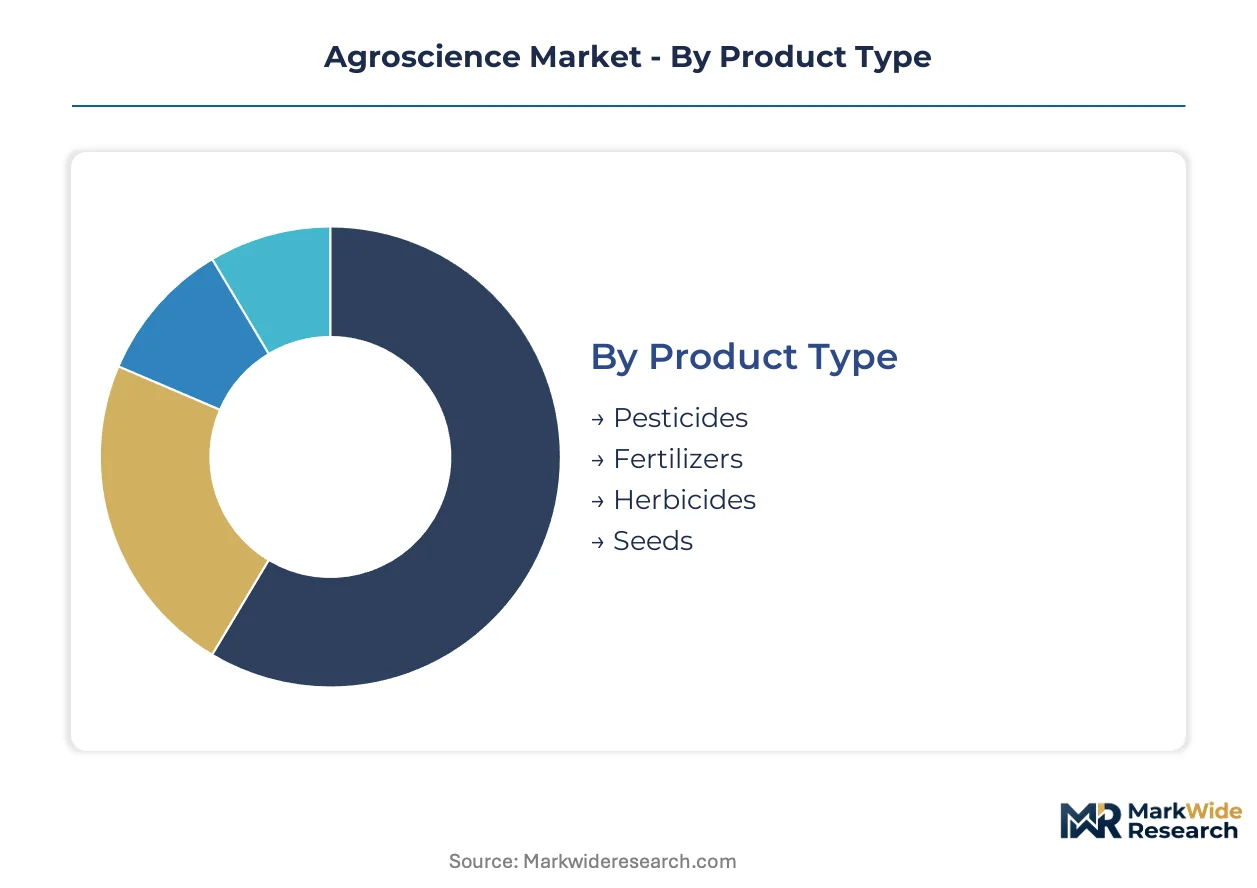
Agroscience segmentation reveals divergent margin structures across input categories. Product chemistry and application method determine pricing power, regulatory exposure, and farmer switching costs.
Product Type:
Cost tier differentiation separates commodity macronutrients from precision-formulated actives with patent protection.
- Pesticides:Synthetic and biological formulations targeting arthropod, fungal, and nematode threats. Demand concentrates in Brazil's Cerrado expansion zones where pest pressure intensifies with monoculture soybean-wheat rotations.
- Fertilizers:Nitrogen, phosphorus, and potassium compounds replacing soil macronutrients depleted through harvest cycles. India's Punjab-Haryana belt drives volume as mechanized rice-wheat systems require intensive nutrient replenishment to sustain yields.
- Herbicides:Selective and broad-spectrum weed control agents. Glyphosate-tolerant trait adoption in US Midwest corn-soy systems anchors demand despite EU regulatory phase-outs.
- Seeds:Germplasm incorporating genetic traits for herbicide tolerance, insect resistance, and climate adaptation. Trait stacking through CRISPR editing commands premium positioning as farmers embed protection directly into planting material.
Fertilizers command the established base. The steepest expansion trajectory runs through Seeds.
Application:
Application method determines formulation concentration, equipment requirements, and labor intensity per hectare.
- Crop Protection:Foliar and soil-applied chemistry defending against biotic stressors. Brazil's Mato Grosso mega-farms deploy aerial application fleets to compress treatment windows during critical growth stages.
- Soil Enhancement:Microbiome inoculants, conditioners, and pH modifiers improving root zone productivity. EU Green Deal residue tightening accelerates biological soil amendment registrations ahead of synthetic phase-outs.
- Pest Control:Targeted interventions against specific insect, mite, or rodent populations. India's Central Insecticides Board enforces BIS-compliant formulation standards that condition import access.
- Seed Treatment:Protective coatings applied pre-planting to safeguard genetic investments. Commercial farming operations prioritize trait protection over broadcast spraying, compressing application windows and raising formulation value per hectare.
Crop Protection anchors volume. Seed Treatment gains share fastest as precision agriculture displaces calendar-based spraying.
End Use Industry:
Customer type stratification separates commodity grain operations from premium-priced specialty production systems.
- Agriculture:Broad-acre grain and oilseed production serving commodity markets. Input procurement centers on cost-per-hectare optimization across millions of consolidated acres.
- Horticulture:Fruit, vegetable, and ornamental cultivation with intensive management and higher input sensitivity. Greenhouse operations in the Netherlands deploy sensor-enabled agronomy matching chemistry to plant stress signatures.
- Commercial Farming:Large-scale mechanized enterprises with professional agronomy staff. Brazilian Cerrado expansion zones consolidate through competitive tender against yield benchmarks rather than historical supplier relationships.
- Organic Farming:Certified production excluding synthetic actives, commanding price premiums for biological pesticides and non-synthetic soil enhancers. EU Farm to Fork targets pull microbial and semiochemical alternatives into mainstream distribution.
Commercial Farming represents the mature volume base. Organic Farming climbs the fastest as certification programs expand acreage eligibility.
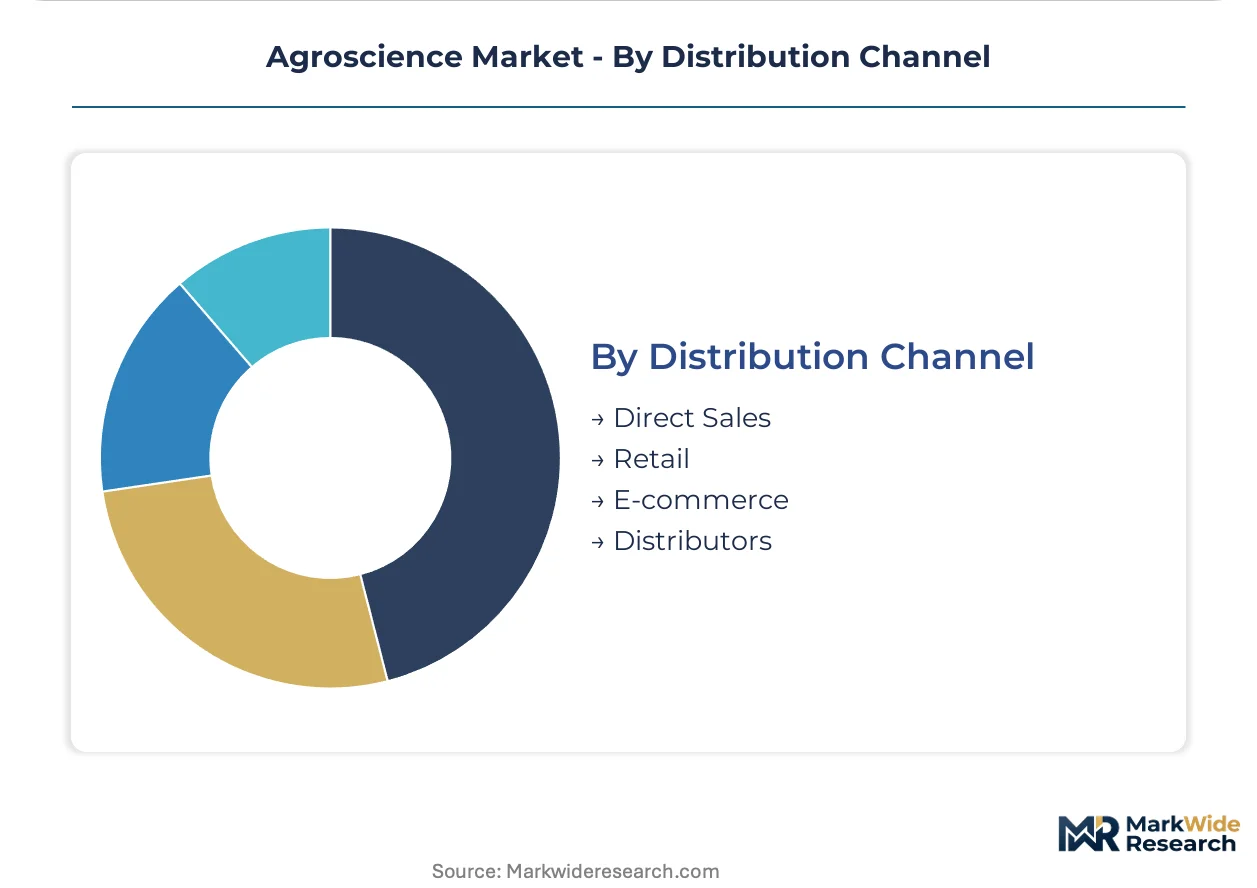
Distribution Channel:
Supply concentration varies from direct manufacturer relationships to fragmented retail networks serving smallholders.
- Direct Sales:Manufacturer-to-farm contracts bundling inputs with agronomic advisory. Bayer and Syngenta digitize services around UAV-mounted hyperspectral data streams, converting hardware into recurring analytics subscriptions.
- Retail:Bricks-and-mortar farm supply stores with local inventory and credit relationships. India's rural input shops dominate Punjab-Haryana procurement despite e-commerce penetration in urban peripheries.
- E-commerce:Digital platforms disintermediating traditional distributor networks. Agronomy-as-a-service models capture farmer data and lock in input loyalty through prescription algorithms.
- Distributors:Regional wholesalers consolidating fragmented demand for multinational formulators. Cold chain investments for biological viability compress margin structures in microbial product categories.
Direct Sales and Distributors split the established base. E-commerce expands most quickly as digital prescription platforms consolidate farmer data ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across farming systems. Large mechanized operations in Brazil's Cerrado accept premium seed treatments for genetic protection, while smallholders in India's northern plains remain acutely price-sensitive on bulk fertilizers.
Brazil
Soybean-wheat monocultures in Mato Grosso and Goiás intensify pest pressure and compress application windows. ANVISA accelerates biological pesticide evaluations under federal sustainable agriculture mandates. Mega-farms around Lucas do Rio Verde unbundle input procurement through competitive yield-based tenders rather than legacy supplier relationships.
United States
Corn-soy systems across Iowa and Illinois drive precision agriculture adoption for input optimization. EPA registration timelines under FIFRA constrain novel synthetic active ingredient approvals. Fleet-scale UAV networks in the Midwest deploy hyperspectral imaging for early fungal detection, converting hardware into recurring analytics subscriptions.
India
Mechanized rice-wheat rotations in Punjab and Haryana require intensive macronutrient replenishment cycles. The Central Insecticides Board enforces BIS-compliant formulation standards conditioning import access for agrochemicals. Rural supply shops in the Punjab-Haryana belt dominate procurement despite urban e-commerce penetration.
Germany
Greenhouse horticulture in Lower Saxony and Bavaria deploys sensor-enabled agronomy matching chemistry to plant stress signatures. The Federal Office of Consumer Protection and Food Safety fast-tracks biological active substance approvals under EU Green Deal Farm to Fork targets. Industrial biotechnology clusters around Frankfurt integrate fermentation platforms for captive Bacillus-based biofungicide production.
China
Consolidated grain operations in Heilongjiang and Jilin provinces drive demand for high-analysis fertilizers. MEE enforcement of dual carbon goals constrains synthetic intermediate manufacturing capacity. Yangtze River Delta chemical parks dominate agrochemical intermediate production, exposing global formulators to export license volatility.
Agroscience Market Key Industry Players
Capability concentration sits with integrated germplasm-chemistry platforms; scale advantage sits with diversified input manufacturers with captive raw material positions. The vendor base stratifies across three tiers: multinational conglomerates controlling trait stacks and distribution networks, mid-scale formulators serving regional crop systems, and biological specialists leveraging fermentation assets. Dominant competitive moves include backward integration into microbial strain libraries and strategic partnerships bundling seed treatments with digital agronomy services.
Within the integrated platform tier, Bayer AG and Syngenta Group exemplify archetypes combining germplasm ownership with formulation capabilities. Corteva Agriscience occupies a position representing CRISPR-edited trait specialization. These three anchors demonstrate how proprietary genetic platforms and biological fermentation assets reshape margin capture upstream from commodity chemistry.
| Leading Market Players |
|---|
| BASF SE |
| Nutrien Ltd. |
| Bayer AG |
| UPL Limited |
| Sumitomo Chemical |
| Corteva Agriscience |
| FMC Corporation |
| ADAMA |
| Syngenta Group |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta chemical parks anchor intermediate manufacturing for synthetic agrochemicals, concentrating margin capture upstream while formulators downstream face cost volatility and freight exposure. This upstream control shapes pricing power across seed treatment and biological portfolios, with procurement patterns increasingly indexed to export license stability rather than pure commodity benchmarks.
Pricing Analysis
After-sales agronomic advisory contracts now drive lifetime value beyond initial input transactions. Three-tier pricing structure across premium, standard, and economy levels separates CRISPR-edited trait stacks from conventional germplasm and commodity generics. Price differentiation hinges on certification grade under EU Green Deal sustainability tiers and volume scale across mega-farm procurement tenders. Cost compression in biological formulations is intensifying because cold chain viability investments compress rural margin structures. Smallholders in India's Punjab-Haryana belt exhibit acute price sensitivity on bulk fertilizers, while Brazilian Cerrado mega-farms accept premiums for genetic trait protection.
Supply Chain Analysis
Tariff exposure between China and Western formulation hubs dominates supply chain risk calculus for synthetic active ingredient sourcing. Manufacturing gravity centers on China for chemical intermediates, India for generic formulation, and Germany for biological fermentation platforms. Raw material dependencies include phosphorus rock concentrates, nitrates, and microbial strain libraries. Single-source vulnerability concentrates in Yangtze River Delta chemical parks where MEE dual carbon enforcement constrains capacity expansion. Distribution runs through regional wholesalers consolidating fragmented smallholder demand, with direct-to-farm digital channels gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agroscience market operates as a defensive-moat story where regulatory entrenchment around biological registration pathways and germplasm patent thickets creates durable incumbent advantages. Switching costs for farmers escalate as trait stacks embed protection directly into planting material.
For Market Incumbents: Build regulatory moats by accelerating biological active substance dossiers under EU Green Deal fast-track pathways ahead of synthetic phase-outs. Deepen backward integration into microbial strain libraries to reduce licensing friction and capture fermentation margin. Bayer and Syngenta already anchor this positioning through integrated germplasm-chemistry platforms. Corteva's CRISPR specialization offers a parallel defensive arc. Threats emerge from digital-native agronomy platforms disintermediating traditional distributor relationships. For New Entrants and Emerging Players: Build out precision application service bundles targeting India's Punjab-Haryana mechanized corridor, where soil microbiome diagnostics remain underpenetrated relative to input saturation. White space concentrates in biological soil amendments for organic farming certification programs expanding acreage eligibility. Fermentation-derived biofungicides offer cost parity entry points against synthetic portfolios. Go-to-market execution should anchor through independent agronomic consultancies acting as gatekeepers to input decisions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biological specialists holding captive fermentation capacity but lacking germplasm integration. Long-term viability across the analysis window favors platforms combining strain libraries with digital agronomy data streams. Acquisition targets include mid-scale formulators with BIS-compliant registration pathways in India and ANVISA-tracked biological portfolios in Brazil. Watch for inflection signals in farmer procurement pattern shifts from brand loyalty to outcome-guaranteed performance contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Registration Acceleration | EU Green Deal fast-track pathways compress evaluation windows and open shelf space ahead of synthetic MRL reductions. |
| Fermentation Platform Integration | Industrial biotechnology convergence enables captive Bacillus-based biofungicide production at synthetic cost parity. |
| Direct-to-Farm Digital Channel Buildout | Agronomy-as-a-service platforms capture farmer data and lock input loyalty through prescription algorithms. |
| CRISPR Trait Stack Expansion | Proprietary gene-edited seed platforms embed protection directly into germplasm and capture margin upstream from chemistry. |
| Regional Wholesaler Consolidation | Cold chain investments for biological viability compress margin structures and favor scaled distributor networks. |
Research Approach
Initial hypotheses were tested against primary input from crop protection R&D directors, regulatory affairs leads at multinational formulators, mega-farm agronomy managers in Brazil's Mato Grosso, and Punjab-Haryana input distributors. These perspectives were refined through secondary validation against EPA FIFRA registration databases, EFSA substance evaluation backlogs, ANVISA biological pesticide filings, and customs trade data tracking agrochemical intermediate flows. Bottom-up field-level demand estimates were triangulated with top-down national agricultural input expenditure benchmarks across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product chemistry tier, application method, end-use industry stratification, and regional regulatory cluster intensity. CAGRs were derived through slope analysis of historical penetration curves adjusted for policy inflection points. Industry-specific forecast inputs incorporated EU Farm to Fork MRL reduction timelines and ANVISA biological evaluation acceleration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese chemical conglomerates or venture-funded biological platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
Plant-Based Vaccines Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Agricultural Biotechnology Market