
 Asia-Pacific Agriculture Biotech Market | 2026-2036
Asia-Pacific Agriculture Biotech Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agriculture Biotech Market Insights
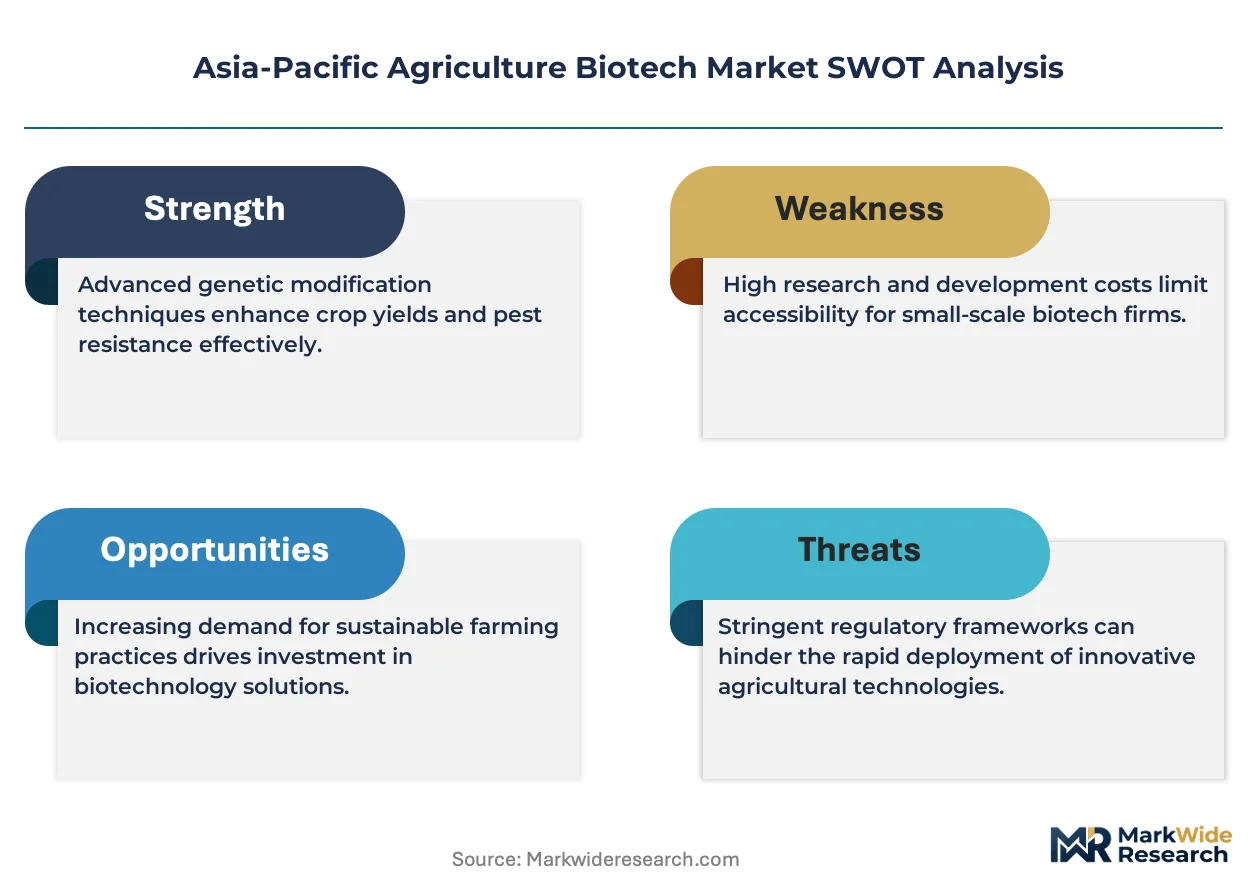
Project finance for precision-breeding facilities is narrowing the competitive field to firms with balance-sheet depth or state-backed credit lines. Bayer leverages its integrated seed-and-trait platform to sustain multi-country licensing across Southeast Asia. Corteva Agriscience anchors its position through farmer-facing digital advisory networks that lock in recurring seed purchases. Syngenta competes by controlling proprietary germplasm banks with heat-stress tolerance traits tailored to South Asian conditions.
Asia-Pacific agriculture biotech encompasses the application of molecular biology, genetic engineering, and genomic tools to modify crop and livestock organisms for enhanced yield, stress tolerance, or nutritional content, with CRISPR guide-RNA systems achieving edit precision at single-nucleotide resolution. The primary commercial purpose is to reduce input costs and climate vulnerability for commercial farming operations across diverse agro-ecological zones. Transgenic crops occupy the largest value share due to established regulatory pathways in major cultivation countries, while biological pest control represents the fastest-expanding product type as export-oriented growers respond to tightening maximum residue limits in destination markets. CRISPR technology leads the innovation pipeline, though marker-assisted selection dominates actual planted hectarage because of lower technical barriers and existing extension infrastructure.
India's GEAC and China's SAMR govern trait approval timelines, with both agencies accelerating reviews for gene-edited products lacking foreign DNA inserts. Australia's OGTR and New Zealand's EPA coordinate trans-Tasman risk assessment protocols that determine market access for novel organisms. Japan's MAFF maintains distinct food-and-feed labeling requirements that shape trait development priorities for export-bound soybean and corn varieties. Stakeholders must track divergence between gene-editing frameworks that classify products as GMO-equivalent versus those that exempt certain edits from full biosafety review.
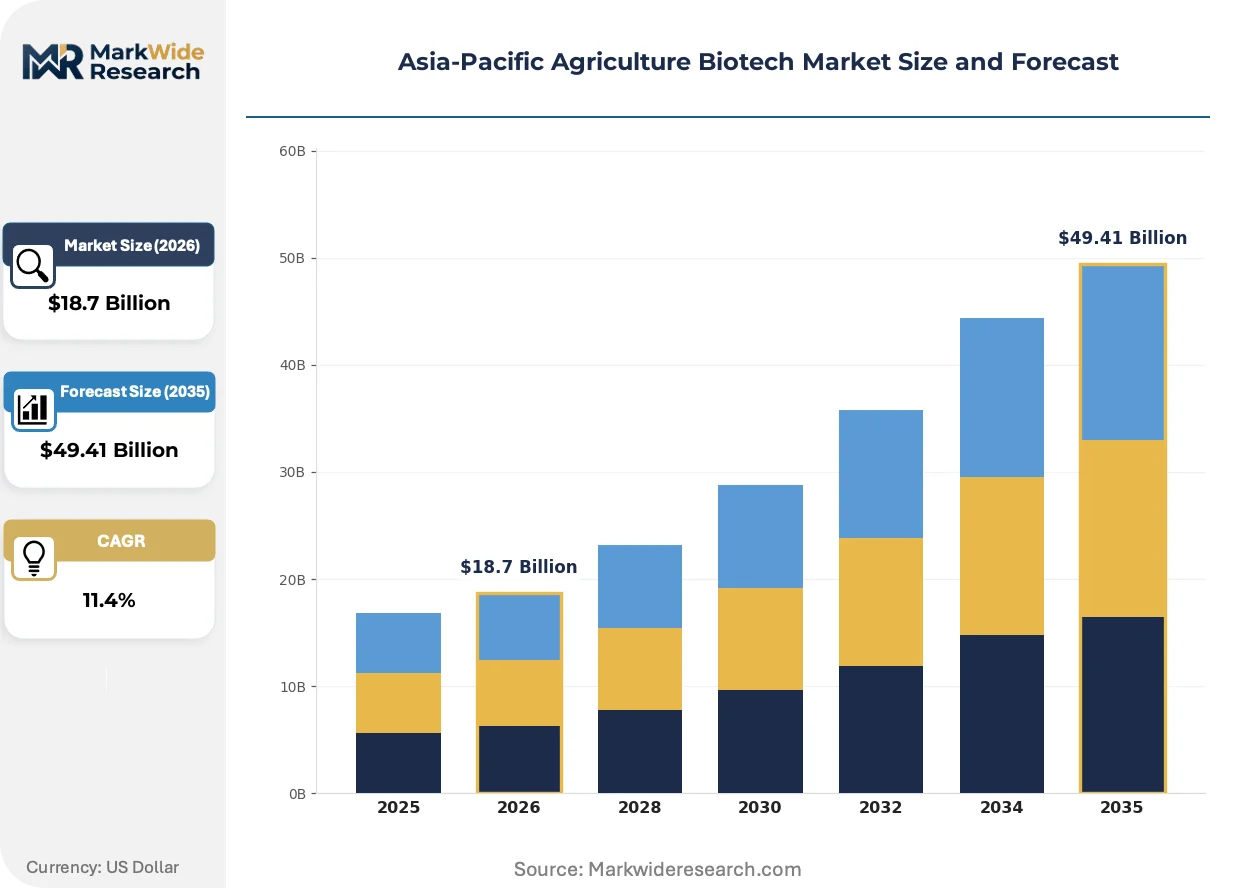
Market Dynamics
CRISPR-based gene editing is compressing trait development timelines from a decade to under four years, forcing seed companies to restructure R&D footprints across India, China, and Australia while regulators race to adapt approval frameworks.
Growth Catalysts
- Streamlined Gene-Editing Guidelines:India's GEAC and China's SAMR now exempt certain CRISPR edits from full biosafety review, accelerating commercialization timelines for drought-tolerant rice and heat-resistant wheat varieties.
- Biological Pest Control Mandates:Australia's grain exporters face tightening maximum residue limits from EU and Japanese buyers, driving rapid adoption of microbial biopesticides across Victoria and Western Australia.
- Heat-Stress Germplasm Demand:South Asian farmers require climate-adaptive seed traits as monsoon variability intensifies, pulling proprietary germplasm banks into licensing partnerships with local distributors.
Market Restraints
- Trait Approval Asymmetry:Divergent classification of gene-edited products between India's GEAC and New Zealand's EPA creates regulatory arbitrage costs for multi-country seed portfolios.
- Guide-RNA Synthesis Concentration:Supply of high-fidelity synthetic oligonucleotides concentrates among three contract manufacturers in South Korea and Singapore, exposing CRISPR programs to input bottlenecks.
- Extension Infrastructure Gaps:Marker-assisted selection dominates planted hectarage because village-level agronomist networks lack capacity to deploy CRISPR trait stewardship protocols.
Strategic Opportunities
- Philippines Corn Belt Penetration:The country's national agricultural regulator has yet to finalize gene-editing guidelines, creating first-mover positioning for trait developers ahead of formal framework publication.
- Digital Advisory Integration:Farmer-facing mobile platforms lock in recurring seed purchases by bundling weather-indexed crop insurance with trait performance guarantees.
- Trans-Tasman Protocol Harmonization:Australia's OGTR and New Zealand's EPA coordinate risk assessment standards, enabling single-submission market access for novel organisms across both jurisdictions.
Industry Challenges
- Bioinformatics Talent Scarcity:CRISPR guide-RNA design and off-target analysis require computational biology expertise that remains concentrated in Bangalore, Shanghai, and Sydney research clusters.
- Multi-Jurisdiction Stewardship Complexity:Refuge requirements for insect-resistant traits vary between Indian state agriculture departments and Chinese provincial authorities, complicating compliance for cross-border seed movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agriculture Biotech Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transgenic Crops, Molecular Diagnostics, Biological Pest Control, Biofertilizers Application: Crop Improvement, Disease Resistance, Pest Management, Soil Health End User: Farmers, Research Institutions, Agribusinesses, Government Agencies Technology: Crispr, Genomic Selection, Tissue Culture, Marker-Assisted Selection |
| Companies Covered | Syngenta, Bayer, Corteva Agriscience, BASF, DuPont de Nemours, Isagro, Biocon Limited, Wuxi AppTec, Astellas Pharma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agriculture Biotech Market Trends and Innovations
Digital phenotyping platforms are compressing field trial cycles while regulators across the Asia-Pacific region recalibrate biosafety frameworks to distinguish gene-edited products from transgenic organisms.
CRISPR-Cas12a systems enable multiplexed editing of complex polygenic traits like nitrogen-use efficiency in rice. State-backed breeding consortia in China and India are adopting these platforms at scale, displacing older TALEN approaches. The technology is virtualizing trait validation workflows by replacing multi-season field observations with high-throughput greenhouse phenotyping.
Japan's MAFF maintains distinct food-and-feed labeling requirements for genome-edited products that diverge from Chinese and Indian frameworks. This regulatory fragmentation forces exporters to maintain parallel identity preservation systems for soybean and corn varieties bound for Japanese processors. Australian trait developers now prioritize Japan-compliant edits in their forward pipelines.
Farmer procurement of biotech seeds is migrating from cooperative bulk purchasing to direct-to-farm digital channels with embedded financing. This channel shift disintermediates traditional district-level distributors in India's Maharashtra and Madhya Pradesh states. The transition is most visible among commercial cotton growers who now order Bt trait packages through smartphone applications with credit-linked payment terms.
Asia-Pacific Agriculture Biotech Market Segmentation
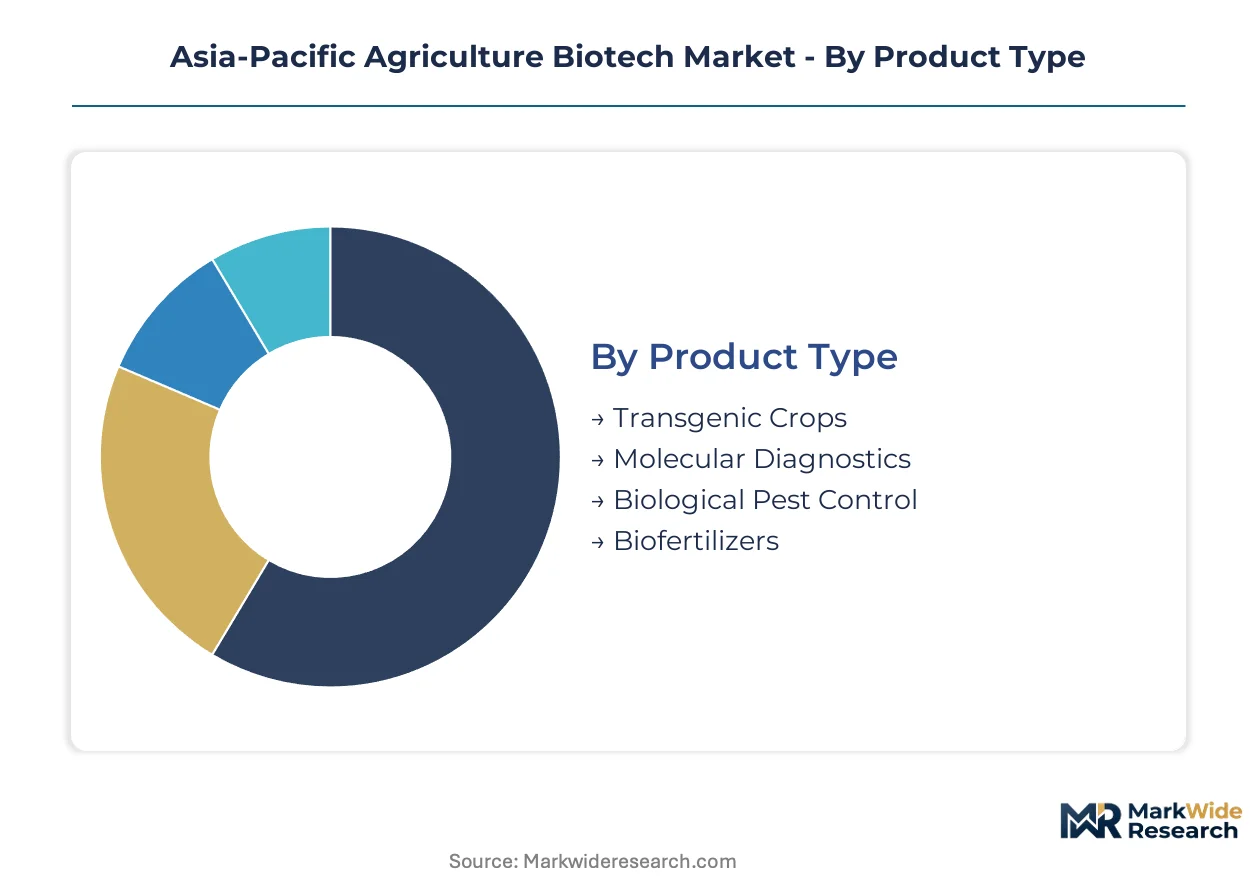
Product, application, and technology segments in Asia-Pacific agriculture biotech each carry distinct regulatory footprints and capital requirements. Understanding these boundaries determines where CRISPR programs, biological control ventures, and precision breeding platforms concentrate resources across India, China, and Australia.
Product Type:
Cost tiers separate commodity-scale biological inputs from premium gene-edited seed systems with multi-year development horizons.
- Transgenic Crops:These varieties incorporate foreign DNA constructs for herbicide tolerance or insect resistance. India's cotton belt and China's corn-soy regions drive demand as GEAC and SAMR maintain established approval pathways for stacked-trait events.
- Biological Pest Control:Microbial biopesticides and biocontrol agents derived from Bacillus thuringiensis or Trichoderma species target residue-sensitive export markets. Australian grain exporters in Victoria and Western Australia accelerate uptake following EU and Japanese maximum residue limit tightening.
- Molecular Diagnostics:PCR and sequencing-based pathogen detection tools support seed certification and quarantine protocols.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing microbial formulations reduce synthetic input dependence for smallholder rice systems.
Transgenic crops command the established base. The steepest expansion runs through biological pest control.
Application:
Application focus determines whether developers pursue trait licensing revenue or direct-to-farm service models across South Asian and Australian growing regions.
- Crop Improvement:Yield enhancement, quality optimization, and climate adaptation through CRISPR-edited germplasm. China's state-backed breeding consortia and India's private seed companies prioritize drought-tolerant rice and heat-resistant wheat as monsoon variability intensifies.
- Pest Management:Integrated approaches combining Bt traits, RNA interference, and microbial biocontrol. Australian grain belt adoption accelerates under stricter export market residue protocols.
- Disease Resistance:Fungal and viral resistance traits in vegetatively propagated crops.
- Soil Health:Microbiome modulation and biofertilizer integration for degraded paddy soils.
Crop improvement anchors the revenue base. Pest management is climbing the fastest as biological alternatives displace chemical residues.
End User:
Customer type dictates sales channel structure from government tender systems to digital direct-to-farm platforms with embedded financing.
- Farmers:Commercial growers and smallholders procuring biotech seeds, biopesticides, and diagnostic services. India's Maharashtra and Madhya Pradesh cotton growers increasingly order Bt trait packages through smartphone applications with credit-linked payment terms.
- Agribusinesses:Integrated seed companies, grain traders, and food processors investing in proprietary germplasm and identity preservation systems. Japanese MAFF labeling requirements force exporters to maintain parallel supply chains for genome-edited soybean and corn varieties.
- Research Institutions:Public breeding programs and agricultural universities conducting field trials.
- Government Agencies:Regulators and extension services managing biosafety review and trait stewardship.
Agribusinesses concentrate the procurement volume. Farmers are gaining share fastest through digital channel migration.
Technology:
Technical maturity separates proven field deployment platforms from emerging systems still navigating regulatory classification.
- CRISPR:Guide-RNA directed nuclease systems achieving single-nucleotide precision without foreign DNA insertion. China's SAMR and India's GEAC now exempt certain edits from full biosafety review, compressing development timelines from a decade to under four years.
- Marker-Assisted Selection:DNA marker-guided breeding accelerates conventional selection without transgenic classification. Dominates actual planted hectarage across Asia-Pacific due to lower technical barriers and existing village-level extension infrastructure.
- Genomic Selection:Whole-genome prediction models for complex polygenic traits.
- Tissue Culture:Micropropagation and somatic embryogenesis for vegetatively propagated crops.
Marker-assisted selection holds the deployed base. CRISPR is expanding most quickly as regulatory frameworks clarify gene-edited product classification.
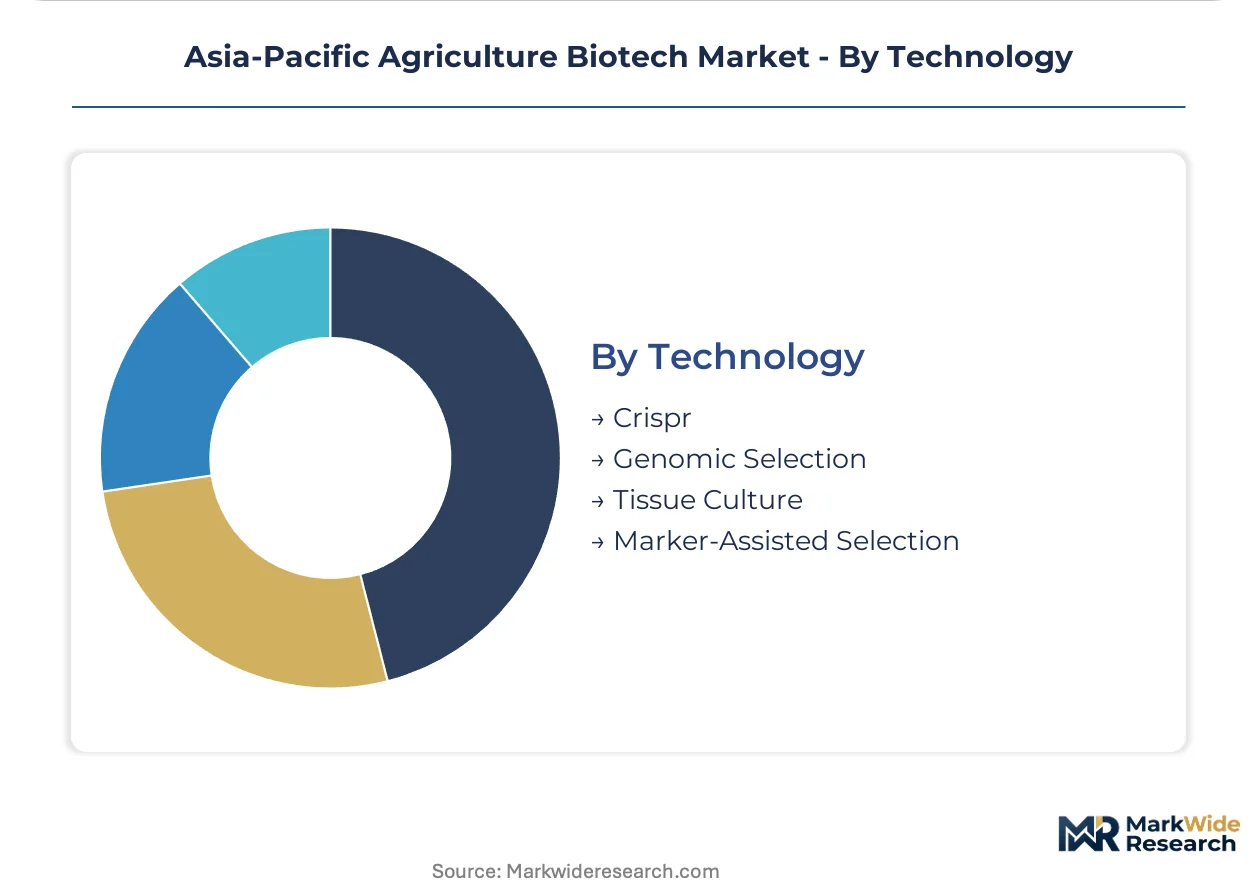
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streamlined gene-editing guidelines across India and China are accelerating CRISPR-based trait commercialization, while Australia's export-oriented grain sector drives biological pest control adoption under tightening residue protocols from destination markets.
India
India's GEAC exempts certain CRISPR edits from full biosafety review, compressing development timelines for drought-tolerant rice. Maharashtra and Madhya Pradesh cotton growers now procure Bt trait packages through smartphone applications with credit-linked payment terms, disintermediating traditional district-level distributors.
China
China's SAMR governs accelerated reviews for gene-edited products lacking foreign DNA inserts. State-backed breeding consortia in the Yangtze River Delta adopt CRISPR-Cas12a platforms at scale for nitrogen-use efficiency in rice, displacing older TALEN approaches.
Australia
Australian grain exporters face tightening maximum residue limits from EU and Japanese buyers. Victoria and Western Australia drive rapid uptake of microbial biopesticides as the OGTR coordinates trans-Tasman risk assessment protocols with New Zealand's EPA.
Japan
Japan's MAFF maintains distinct food-and-feed labeling requirements for genome-edited products that diverge from Chinese and Indian frameworks. Exporters maintain parallel identity preservation systems for soybean and corn varieties bound for Japanese processors.
Philippines
The Philippines national agricultural regulator has yet to finalize gene-editing guidelines. This regulatory gap creates first-mover positioning for trait developers ahead of formal framework publication in the corn belt.
Asia-Pacific Agriculture Biotech Market Competitive Landscape
Channel-controlling players compete with product-specialist players across seed-and-trait platforms, digital advisory networks, and proprietary germplasm banks. The market structure concentrates around integrated agribusiness conglomerates with balance-sheet depth or state-backed credit lines, alongside specialized biotechnology firms with CRISPR capabilities. Three archetypes dominate: vertically integrated seed-and-chemical platforms, digital-enabled farmer-facing networks, and germplasm-focused trait licensors. Competitive moves center on multi-country licensing partnerships and farmer lock-in through bundled advisory services.
Among the integrated platform operators, Syngenta and Bayer anchor the market through their respective germplasm banks and trait licensing engines. Corteva Agriscience exemplifies the digital-advisory archetype, locking in recurring seed purchases through farmer-facing mobile platforms. These three entities represent the dominant competitive vectors—proprietary germplasm control, integrated chemical-seed platforms, and digital channel capture—shaping regional positioning across South Asian and Australian growing regions.
| Leading Market Players |
|---|
| Syngenta |
| Bayer |
| Corteva Agriscience |
| BASF |
| DuPont de Nemours |
| Isagro |
| Biocon Limited |
| Wuxi AppTec |
| Astellas Pharma |
| Others |
Pricing and Supply Chain Analysis
Synthetic oligonucleotide manufacturing concentrates among contract manufacturers in South Korea and Singapore, anchoring cost structures for CRISPR-based seed programs and concentrating margin capture among firms with multi-year guide-RNA supply agreements.
Pricing Analysis
Certification level (ISO-grade germplasm versus state-registered varieties) creates the primary spread between premium gene-edited seeds and commodity biological inputs. Licensing-royalty models dominate transgenic trait revenue, while microbial biopesticides trade on per-hectare subscription tiers. Price differentiation reflects trait performance guarantees and bundled digital advisory services. Margins are tightening in biological pest control as Australian grain exporters consolidate procurement volumes to meet EU residue protocols.
Supply Chain Analysis
Export-control regimes on CRISPR reagents and high-fidelity sequencing equipment limit technology flows into emerging breeding programs. Supply concentrates in China for nitrogen-fixing microbial formulations and in India for Bt cotton seed multiplication. Guide-RNA synthesis and precision phenotyping hardware rest on inputs from South Korea, Singapore, and Japan. Single-source vulnerability runs through synthetic oligonucleotide contract manufacturers. Distribution runs through state-backed breeding consortia and digitizing direct-to-farm platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific agriculture biotech market sits in early-cycle expansion as streamlined gene-editing guidelines in India and China compress trait development timelines from a decade to under four years, accelerating commercialization velocity.
For Market Incumbents: Build proprietary germplasm banks with climate-adaptive traits as the primary moat against CRISPR-native entrants. Deepen backward integration into guide-RNA synthesis capabilities to reduce exposure to South Korean and Singaporean contract manufacturer bottlenecks. Lock in farmer retention through digital advisory platforms bundling weather-indexed crop insurance with trait performance guarantees. State-backed credit lines and balance-sheet depth remain critical for project finance in precision-breeding facilities. For New Entrants and Emerging Players: Mid-market biological pest control in Australia's Victoria and Western Australia grain belt represents the most penetrable entry point before integrated platforms consolidate share. The Philippines corn belt offers first-mover positioning ahead of finalized national gene-editing guidelines. Partner with village-level agronomist networks to overcome extension infrastructure gaps that currently limit CRISPR trait deployment. Digital direct-to-farm channels with embedded financing disintermediate traditional district-level distributors in India's Maharashtra and Madhya Pradesh states. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-breeding platforms possessing CRISPR capabilities but lacking multi-country licensing infrastructure. The five-to-ten year viability window favors firms with established regulatory relationships across India's GEAC and China's SAMR. Acquisition targets should demonstrate proprietary germplasm with heat-stress tolerance traits and existing digital farmer-facing networks. Watch for divergence between gene-editing frameworks that classify products as GMO-equivalent versus exempted from full biosafety review as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Country Trait Licensing | Bayer's integrated seed-and-trait platform sustains revenue across Southeast Asian markets with divergent regulatory timelines. |
| Digital Advisory Platform Integration | Corteva Agriscience locks recurring seed purchases through farmer-facing mobile networks bundling crop insurance with trait guarantees. |
| Proprietary Germplam Bank Expansion | Syngenta controls heat-stress tolerance traits tailored to South Asian monsoon variability, anchoring competitive positioning. |
| Backward Integration into Guide-RNA Synthesis | Reduces input bottlenecks from concentrated South Korean and Singaporean contract manufacturers for CRISPR programs. |
| Trans-Tasman Regulatory Harmonization | Enables single-submission market access for novel organisms across Australia's OGTR and New Zealand's EPA jurisdictions. |
Research Methodology
Initial hypotheses were tested against primary input from seed company R&D directors, regulatory affairs leads at India's GEAC and China's SAMR, grain trader procurement heads, and village-level extension agronomists, then refined against secondary validation from customs trade data, national biosafety filing records, agricultural extension service reports, and SEC 10-K filings of listed agribusiness conglomerates. Bottom-up acreage estimates for CRISPR-edited and transgenic crop deployments were triangulated against top-down market value reconstructions.
Demand-supply balance modeling anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type (transgenic crops, biological pest control, molecular diagnostics), application focus (crop improvement, pest management, disease resistance), technology maturity (CRISPR, marker-assisted selection, genomic selection), and end-user procurement channel (government tenders, cooperative bulk purchasing, digital direct-to-farm). CAGRs were derived from fitted growth curves calibrated to regulatory approval velocity and adoption lag patterns observed in comparable technology diffusion cycles. Industry-specific inputs included GEAC and SAMR gene-editing guideline implementation timelines and EU maximum residue limit enforcement trajectories.
Practitioners should monitor regulatory divergence between gene-editing frameworks, guide-RNA synthesis capacity expansion, and digital channel penetration rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Brazil Veterinary Vaccines Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Ruminant Vaccines Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Microarray in Agriculture Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Biorationals Market
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Transgenic Seeds Market