
 Global Liver Cancer Treatment Market | 2026-2036
Global Liver Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liver Cancer Treatment Market Foresight
The capability gap between biologics manufacturers and small-molecule specialists is collapsing as immunotherapy production requires comparable capital deployment to targeted therapy platforms. Bristol-Myers Squibb Company leverages its integrated biologics network to sustain manufacturing scale across checkpoint inhibitor portfolios. Bayer AG anchors its position through transarterial chemoembolization device-drug combinations that dominate interventional oncology workflows. Eisai Co., Ltd. differentiates via lenvatinib supply chains that extend across Asian and North American distribution hubs.
Liver cancer treatment encompasses systemic and locoregional interventions designed to eliminate, control, or palliate malignant hepatic tumors, utilizing biologics, cytotoxic agents, radiation delivery systems, and surgical resection techniques with dosing calibrated to cirrhotic liver function parameters. Immunotherapy commands premium positioning as PD-1/PD-L1 inhibitors reshape first-line hepatocellular carcinoma protocols, while targeted therapy maintains volume leadership through multi-kinase inhibitor accessibility in emerging markets. Transarterial chemoembolization remains a mature margin pool embedded in interventional radiology practice, whereas radiofrequency ablation competes for early-stage patient selection against surgical resection.
FDA accelerated approval pathways compress development timelines for breakthrough hepatocellular carcinoma therapies, while EMA orphan drug incentives sustain European commercialization for cholangiocarcinoma subtypes. China's NMPA priority review channels direct domestic manufacturers toward hepatitis B-linked indications that dominate regional disease profiles. Stakeholders must monitor biomarker-defined patient stratification as programmed death-ligand 1 expression levels reshape reimbursement criteria across national health technology assessment bodies.
Market Dynamics
Checkpoint inhibitor manufacturing scale is concentrating production capacity among integrated biologics networks, reshaping competitive entry barriers as PD-1/PD-L1 therapies claim first-line hepatocellular carcinoma protocols.
Growth Catalysts
- FDA Accelerated Approval:Compressed development timelines for breakthrough hepatocellular carcinoma therapies enable faster commercialization of novel immunotherapy combinations. Oncology centers expand protocol adoption following priority review designations.
- China NMPA Priority Review:Domestic manufacturers receive expedited pathways for hepatitis B-linked indications that dominate regional disease profiles. Fast-track channels direct R&D investment toward population-specific therapeutic targets.
- Combination Immunotherapy Protocols:Dual checkpoint blockade regimens are displacing monotherapy standards in academic medical centers. Protocol expansion drives demand for manufacturing scale and cold-chain distribution infrastructure.
Market Restraints
- Biologics Manufacturing Concentration:Limited contract development and manufacturing organization capacity for mammalian cell culture creates supply bottlenecks. Facility qualification timelines extend 18-24 months for new entrants.
- Cirrhosis-Adjusted Dosing Complexity:Hepatic impairment pharmacokinetics require specialized formulation development and clinical validation. Regulatory agencies mandate dedicated Child-Pugh stratification studies that prolong approval pathways.
- EMA Orphan Drug Exclusivity:Cholangiocarcinoma subtype designations fragment addressable patient populations. Market access negotiations face heightened scrutiny from national health technology assessment bodies.
Strategic Opportunities
- Brazil ANVISA Expedited Pathways:Emerging market regulators are streamlining review for therapies with prior FDA or EMA approval. Local partnership structures enable rapid Latin American commercialization without redundant clinical trials.
- Biomarker-Defined Patient Stratification:Programmed death-ligand 1 expression testing is creating addressable subsegments within hepatocellular carcinoma. Companion diagnostic integration opens precision medicine revenue streams.
- Transarterial Chemoembolization Device-Drug Convergence:Drug-eluting bead technology is merging interventional radiology workflows with targeted therapy delivery. Integrated platform offerings capture procedure economics across treatment episodes.
Industry Challenges
- Immuno-Oncology Talent Scarcity:Clinical development organizations compete for biostatisticians experienced in survival analysis for hepatocellular carcinoma trials. Compensation inflation compresses R&D program margins.
- Multi-Regional Regulatory Synchronization:Divergent requirements between FDA, EMA, and NMPA for hepatotoxicity monitoring create protocol complexity. Simultaneous global filings demand specialized regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liver Cancer Treatment Market |
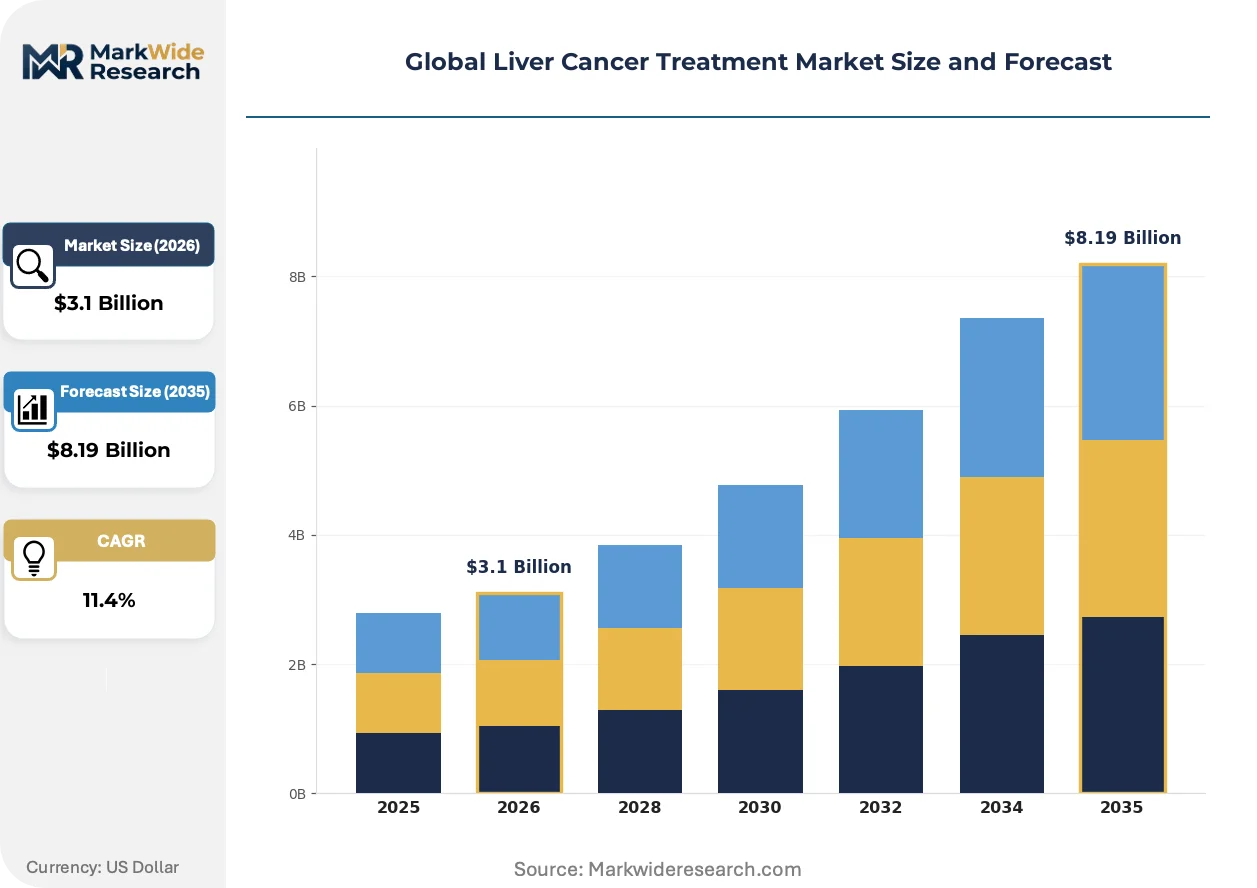
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.19 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Radiation Therapy, Surgical Procedures Therapy Area: Primary Liver Cancer, Hepatocellular Carcinoma, Cholangiocarcinoma, Secondary Liver Cancer End User: Specialty Clinics, Oncology Centers, Diagnostic Laboratories, Research Institutions Delivery Mode: Oral Administration, Intravenous Injection, Transarterial Chemoembolization, Radiofrequency Ablation |
| Companies Covered | F. Hoffmann-La Roche, Bristol-Myers Squibb Company, Bayer AG, Eisai Co., Ltd., Merck & Co., AstraZeneca, Exelixis, Inc., Novartis AG, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liver Cancer Treatment Market Shifts & Advancements
Next-generation sequencing integration is reshaping trial design and patient selection criteria across hepatocellular carcinoma development programs. Three convergent developments are restructuring competitive positioning.
Artificial intelligence-driven radiomics is fragmenting traditional imaging assessment protocols in hepatocellular carcinoma staging. Academic medical centers in the United States are adopting machine learning algorithms for treatment response prediction at accelerating rates. This capability is fragmenting reliance on RECIST criteria alone, enabling earlier protocol adaptation and compressing clinical trial timelines.
EMA's Medical Device Regulation is tightening quality management system requirements for drug-device combination products used in transarterial chemoembolization. Manufacturers must now maintain parallel technical documentation for both pharmaceutical and device components. Interventional oncology suppliers with European distribution are consolidating regulatory affairs functions to manage dual compliance streams.
Academic medical center procurement departments are unbundling device procurement from pharmaceutical contracting in interventional oncology. Purchasing committees now separately evaluate embolization microspheres from chemotherapeutic loading protocols. This behavioral shift is most pronounced in German university hospitals, where centralized purchasing cooperatives negotiate component-level pricing rather than bundled procedure kits.
Global Liver Cancer Treatment Market Segmentation
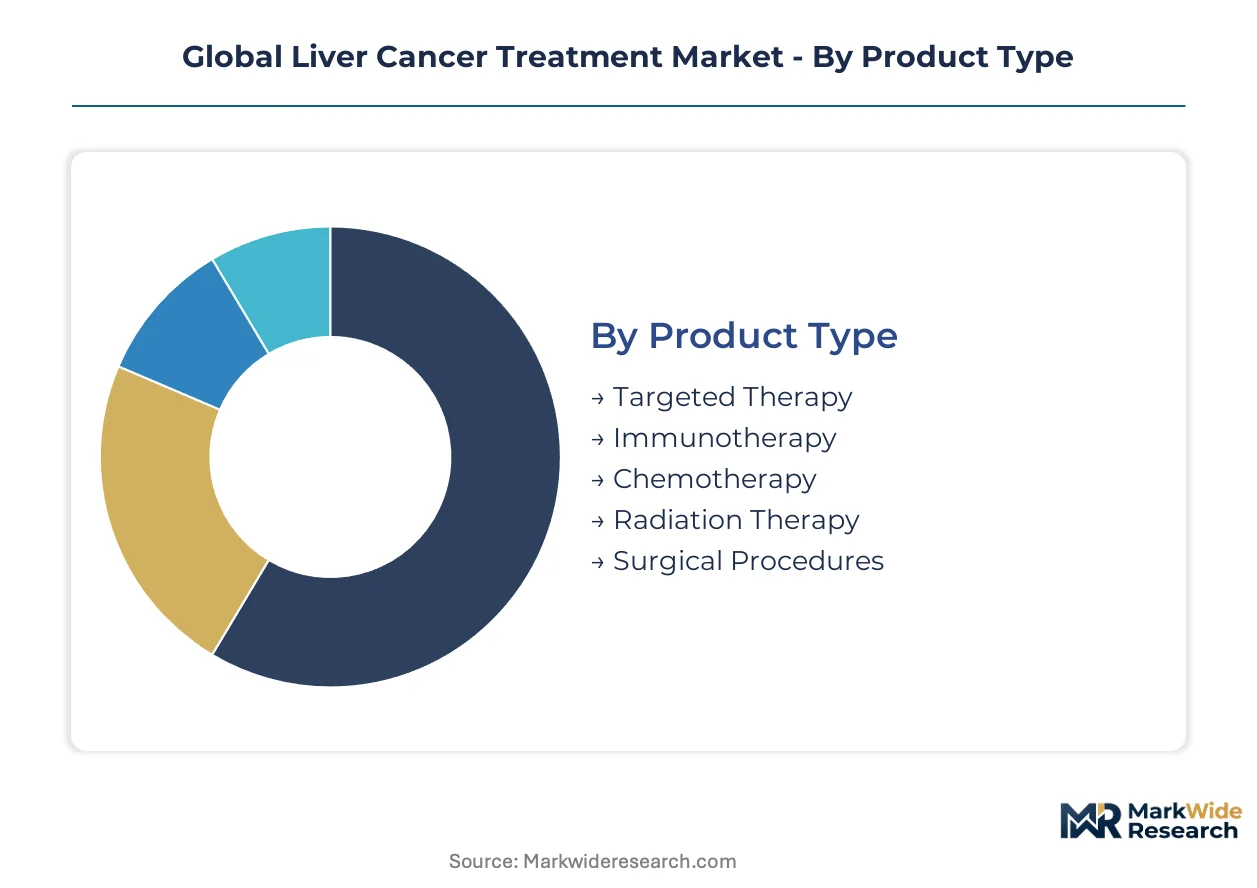
Treatment modality selection in liver cancer hinges on cirrhotic liver function staging, tumor vascularity patterns, and biomarker expression profiles. Segmentation reveals how margin pools concentrate in interventional procedures and biologics manufacturing, while geographic disease burden shapes therapy area prioritization.
Product Type:
Premium margin pools concentrate in biologics manufacturing where cold-chain infrastructure and mammalian cell culture capacity create defensible positions.
- Targeted Therapy:Multi-kinase inhibitors such as lenvatinib and sorafenib dominate volume leadership through oral bioavailability and established reimbursement pathways. Demand concentrates in China and India where hepatitis B-linked hepatocellular carcinoma drives prescription volumes for tyrosine kinase inhibitors with cirrhosis-adjusted dosing protocols.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors command premium positioning as first-line protocols shift toward combination regimens. Manufacturing scale constraints at Bristol-Myers Squibb and Merck facilities create supply bottlenecks for nivolumab and pembrolizumab doses calibrated to Child-Pugh liver function strata.
- Chemotherapy:Systemic cytotoxic agents maintain residual utility in cholangiocarcinoma subtypes with limited immunotherapy responsiveness. Gemcitabine-cisplatin combinations retain standard-of-care status in academic medical centers across Germany and France.
- Radiation Therapy:External beam and selective internal radiation modalities address unresectable tumors with preserved liver function. Yttrium-90 microsphere demand tracks interventional radiology procedure volumes at tertiary centers in the United States.
- Surgical Procedures:Resection and transplantation remain curative options for early-stage patients with adequate hepatic reserve. Waitlist dynamics for donor organs constrain volume at transplant centers in Spain and Italy.
The dominant share belongs to Targeted Therapy, while Immunotherapy is closing the gap fastest.
Therapy Area:
Patient addressability fragments sharply across histologic subtypes, with biomarker-defined populations reshaping clinical trial recruitment and regulatory pathways.
- Primary Liver Cancer:Encompasses all malignancies originating in hepatic tissue, with hepatocellular carcinoma representing the predominant histology. Trial design complexity increases as EMA orphan drug incentives fragment addressable populations across European member states.
- Hepatocellular Carcinoma:Accounts for the preponderance of liver cancer incidence globally, driven by hepatitis B and C viral etiologies. China's NMPA prioritizes accelerated review for therapies targeting this indication given regional disease burden.
- Cholangiocarcinoma:Biliary tract malignancies with distinct molecular profiles including FGFR2 fusions and IDH1 mutations. FDA breakthrough therapy designations have compressed development timelines for targeted agents addressing intrahepatic subtypes.
- Secondary Liver Cancer:Metastatic colorectal cancer deposits dominate this category, with resection candidacy determined by extrahepatic disease status. Japanese medical centers lead volume in conversion chemotherapy protocols enabling subsequent hepatectomy.
Hepatocellular Carcinoma captures the largest patient pool, though Cholangiocarcinoma is expanding most quickly on precision medicine tailwinds.
End User:
Site-of-care economics diverge substantially, with procedure-based revenue concentrating in hospital-based interventional suites versus pharmaceutical margin in outpatient infusion centers.
- Specialty Clinics:Community oncology practices manage stable patients on oral targeted therapy regimens with remote monitoring protocols. Brazil's ANVISA expedited pathways enable rapid commercialization through these lower-acuity settings.
- Oncology Centers:Academic medical centers dominate immunotherapy protocol adoption and combination regimen clinical trials. United States NCI-designated cancer centers concentrate checkpoint inhibitor demand and biomarker testing integration.
- Diagnostic Laboratories:Companion diagnostic development for PD-L1 expression and next-generation sequencing panels creates service revenue streams. German university hospital laboratories anchor European testing volume for hepatocellular carcinoma molecular profiling.
- Research Institutions:Phase I/II trial execution depends on specialized hepatology units with cirrhotic patient stratification expertise. South Korean MFDS-regulated sites contribute disproportionately to Asian-Pacific trial enrollment.
Oncology Centers hold the dominant share, while Diagnostic Laboratories are climbing the fastest on precision medicine infrastructure buildout.
Delivery Mode:
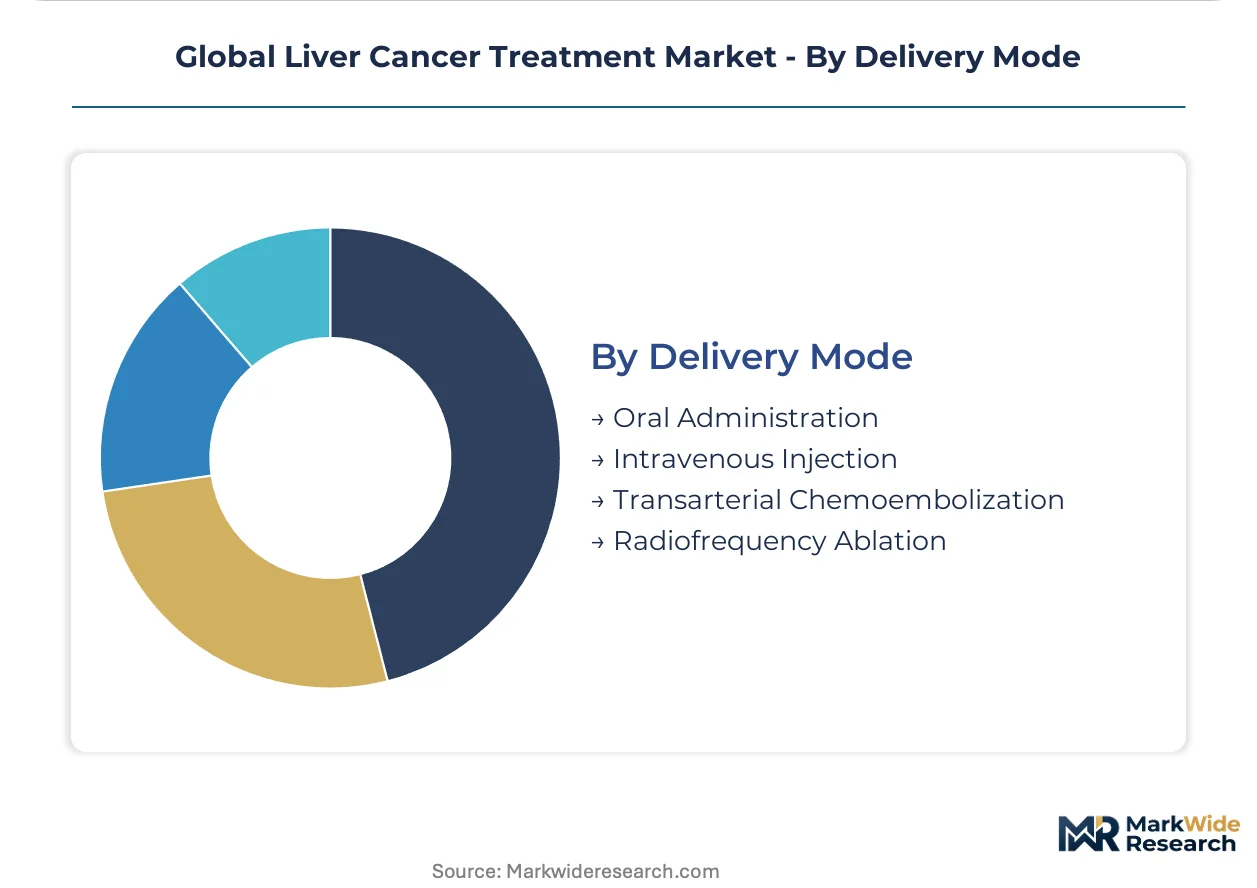
Route of administration determines supply chain complexity, with locoregional interventions requiring device-drug coordination versus systemic therapies dependent on cold-chain distribution.
- Oral Administration:Tyrosine kinase inhibitors enable outpatient management with pharmacy benefit coverage rather than medical benefit billing. Patient adherence programs at specialty pharmacies address dosing interruptions from hand-foot skin reaction toxicities.
- Intravenous Injection:Checkpoint inhibitors require infusion center capacity with hypersensitivity monitoring protocols. United States hospital outpatient departments capture procedure economics through add-on payments for complex biologic administration.
- Transarterial Chemoembolization:Drug-eluting bead technology merges interventional radiology workflows with localized chemotherapy delivery. Bayer's DC Bead platform dominates European procedure volumes through integrated device-pharmaceutical offerings.
- Radiofrequency Ablation:Percutaneous thermal ablation competes with surgical resection for early-stage tumors under three centimeters. Italian interventional radiology societies publish practice guidelines influencing Mediterranean adoption patterns.
Intravenous Injection maintains the dominant share, though Transarterial Chemoembolization is gaining share fastest on device-drug convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in liver cancer immunotherapy concentrates in the United States, where hospital outpatient reimbursement rates exceed German statutory health insurance ceilings by substantial margins. China's domestic manufacturers capture volume leadership through NMPA fast-track pathways that compress approval timelines. Brazil's ANVISA expedited review creates arbitrage opportunities for therapies with prior FDA or EMA authorization.
United States
NCI-designated cancer centers drive checkpoint inhibitor protocol adoption and combination regimen clinical trials. FDA accelerated approval pathways enable breakthrough therapy designations that compress development timelines for hepatocellular carcinoma indications. The Greater Boston biotech cluster anchors immuno-oncology talent concentration and biomarker testing infrastructure development.
China
Hepatitis B-linked hepatocellular carcinoma creates the world's largest addressable patient population for tyrosine kinase inhibitors. NMPA priority review channels direct domestic manufacturers toward population-specific therapeutic targets with expedited regulatory timelines. Shanghai and Beijing biotech parks concentrate contract development and manufacturing organization capacity for mammalian cell culture production.
Germany
University hospital laboratories anchor European testing volume for hepatocellular carcinoma molecular profiling and companion diagnostic development. EMA orphan drug incentives sustain commercialization for cholangiocarcinoma subtypes with fragmented addressable populations. The Rhine-Ruhr metropolitan region concentrates interventional radiology procedure volumes and transarterial chemoembolization device distribution networks.
Japan
PMDA Sakigake designation system accelerates review for innovative hepatocellular carcinoma therapies with unmet medical need. Conversion chemotherapy protocols for metastatic colorectal cancer enable subsequent hepatectomy at Tokyo and Osaka medical centers. The Kanto region leads Asia-Pacific enrollment in Phase I/II trials requiring specialized hepatology unit expertise.
Brazil
ANVISA expedited pathways streamline review for therapies with prior FDA or EMA approval, enabling rapid Latin American commercialization. Local partnership structures allow market entry without redundant clinical trials for established checkpoint inhibitors. São Paulo's academic medical centers concentrate interventional oncology procedure economics and drug-eluting bead adoption.
Global Liver Cancer Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated biologics networks commanding premium positioning while regional manufacturers capture volume through accessible oral therapies. The market structure consolidates around multinational pharmaceutical conglomerates with mammalian cell culture capacity, mid-sized oncology specialists with targeted therapy portfolios, and interventional device-drug combination suppliers. Dominant competitive moves include strategic partnerships for cold-chain distribution infrastructure and portfolio diversification into companion diagnostic development.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche and Bayer AG exemplify integrated platform strategies spanning biologics manufacturing and interventional device offerings. Bristol-Myers Squibb Company represents the scale-driven archetype with checkpoint inhibitor production networks. These three companies occupy positions across the technology-cost spectrum, with Roche anchoring precision medicine integration, Bayer dominating device-drug convergence, and Bristol-Myers Squibb sustaining manufacturing scale for combination immunotherapy protocols.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Eisai Co., Ltd. |
| Merck & Co. |
| AstraZeneca |
| Exelixis, Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
FDA facility qualification standards gate both biologics manufacturing entry and price stratification across checkpoint inhibitor portfolios, compressing margins for contract manufacturers while concentrating premium capture among integrated networks with validated mammalian cell culture capacity.
Pricing Analysis
Configured-to-order pricing for patient-stratified dosing regimens commands substantial premiums over standard protocols, with Child-Pugh liver function-adjusted formulations capturing reimbursement advantages through orphan drug designation pathways. Price differentiation hinges on biomarker companion diagnostic integration and cold-chain reliability certification. Pricing pressure intensifies in oral tyrosine kinase inhibitor segments as domestic Chinese manufacturers exploit NMPA fast-track pathways. Academic medical centers exhibit lowest price sensitivity due to protocol-driven procurement, while community oncology practices face highest sensitivity from pharmacy benefit manager rebate structures.
Supply Chain Analysis
Strategic stockpiling of drug-eluting beads and embolization microspheres dominates interventional radiology procurement, contrasting with just-in-time antibody production schedules that minimize cold-chain inventory exposure. Manufacturing concentrates in China, the United States, and Switzerland, with Shanghai biotech parks anchoring mammalian cell culture capacity for Asian distribution. Supply chains draw from recombinant protein expression systems, yttrium-90 isotope generators, and polymeric bead substrates. Single-source vulnerability persists in radioisotope processing facilities. Distribution runs through hospital outpatient departments capturing procedure economics alongside specialty pharmacy networks for oral agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mammalian cell culture capacity scarcity constrains competitive entry as PD-1/PD-L1 manufacturing networks reach utilization ceilings, privileging incumbents with validated facilities and locking out aspirants facing 18-24 month qualification timelines.
For Market Incumbents: Secure captive supply of drug-eluting bead substrates through backward integration into polymer manufacturing, insulating margin pools from embolization device commoditization. Expand cold-chain distribution partnerships in São Paulo and Mexico City to preempt emerging entrant channel capture in Latin American oncology centers. Defend against biosimilar pressure by accelerating biomarker-defined patient stratification protocols that complicate therapeutic substitution. For New Entrants and Emerging Players: Lead with transarterial chemoembolization device-drug convergence platforms in Brazilian and Mexican markets where ANVISA expedited pathways compress commercialization timelines without redundant clinical trials. Target cholangiocarcinoma precision medicine segments where FGFR2 fusion testing creates addressable subpopulations underserved by hepatocellular carcinoma-focused incumbents. Deploy local partnership structures that transfer regulatory filing burden to established Latin American distributors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing sub-segments as multi-product facility flexibility demands replace single-product stainless steel investments, extending payback periods and favoring scale players. Long-term viability over the coming decade rests on mammalian cell culture network density and companion diagnostic integration depth. Acquisition targets should display validated single-use bioreactor platforms and PD-L1 assay partnerships. The signal to watch is NMPA approval velocity for domestic Chinese checkpoint inhibitors, which would signal margin compression across emerging market pricing tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-stratified hepatocellular carcinoma protocols reshape FDA breakthrough therapy eligibility criteria. |
| Manufacturing Scale-Up | Single-use bioreactor deployment at Bristol-Myers Squibb facilities alleviates nivolumab supply bottlenecks. |
| Regulatory Approval Pathway | NMPA priority review channels concentrate domestic Chinese investment in hepatitis B-linked indications. |
| Pipeline Diversification | Cholangiocarcinoma FGFR2 fusion programs exploit EMA orphan drug exclusivity for fragmented populations. |
| Licensing Agreement | Companion diagnostic partnerships with German university hospital laboratories anchor European testing volume. |
Research Methodology
Cross-validation between FDA accelerated approval filings and EMA orphan drug designations anchors the qualitative findings, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation draws from ClinicalTrials.gov enrollment data, NMPA submission disclosures, SEC 10-K pharmaceutical segment disclosures, and interventional radiology society practice guidelines. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation reconcile volume estimates across the analysis window.
Sensitivity analysis around hepatitis B prevalence assumptions and checkpoint inhibitor manufacturing capacity expansion schedules tests forecast robustness across the projection horizon. Segmentation dimensions modeled include treatment modality, therapy area histology, end-user site-of-care economics, and regional regulatory cluster. CAGRs derive from patient incidence projections, therapy penetration curves, and pricing trajectory assumptions. Industry-specific inputs encompass cirrhosis-adjusted dosing protocol adoption rates and drug-eluting bead procedure volume trends at tertiary interventional radiology centers.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization or NMPA domestic manufacturer prioritization would require recalibration. Forecasts reflect assumptions regarding immunotherapy combination protocol expansion and biomarker testing infrastructure buildout. Revision becomes warranted when contract manufacturing organization capacity utilization crosses thresholds that trigger supply rationing or when EMA Medical Device Regulation enforcement intensity disrupts device-drug combination product commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Global Allergy Vaccine Market