
 Global Purified Terephthalic Acid (PTA) Market | 2026-2036
Global Purified Terephthalic Acid (PTA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Purified Terephthalic Acid (PTA) Market Intelligence
The increasing preference of packaging producers for recycled content is redrawing the procurement landscape for purified terephthalic acid. Indorama Ventures Public Company Limited leverages its significant recycling infrastructure and PET collection networks to meet this demand. Meanwhile, integrated giants like Sinopec Limited dominate the virgin PTA segment through massive production scale and control over feedstock. Hengli Petrochemical also anchors a large portion of the Asian supply chain with its extensive, co-located manufacturing capabilities.
Purified terephthalic acid is a high-volume organic commodity chemical, produced primarily through the catalytic liquid-phase oxidation of p-xylene. Its principal industrial application is as a key raw material for producing polyethylene terephthalate (PET). Polyester fibers for the textile industry constitute the largest application segment, while demand for PET resins used in plastic bottles is expanding rapidly. Virgin PTA remains the dominant product type, though recycled PTA is gaining commercial traction due to sustainability mandates and brand owner commitments.
Producers must navigate a complex web of environmental regulations, including the EPA's air quality standards in the United States and China's MEE emissions controls. In Europe, the EU Green Deal and REACH regulations administered by ECHA are pressuring supply chains to adopt more sustainable and circular production models. Stakeholder success will hinge on balancing large-scale commodity production with the investment required for advanced recycling and bio-based feedstock technologies.
Market Dynamics
The central dynamic shaping the purified terephthalic acid market is the structural collision between the immense scale of China-centric virgin production and the accelerating global mandate for circularity, which requires new investment in advanced chemical recycling infrastructure.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal and similar policies globally compel brands to use recycled materials, directly stimulating demand for recycled PTA (rPTA) in packaging and textiles.
- Textile Industry Shift:A pronounced shift within the global apparel industry toward polyester fibers with verified recycled content is pulling PTA supply chains towards circular models.
- Recycling Technology:Advances in chemical depolymerization processes are improving the yield and purity of rPTA from post-consumer PET waste, making it a more viable commercial feedstock.
Market Restraints
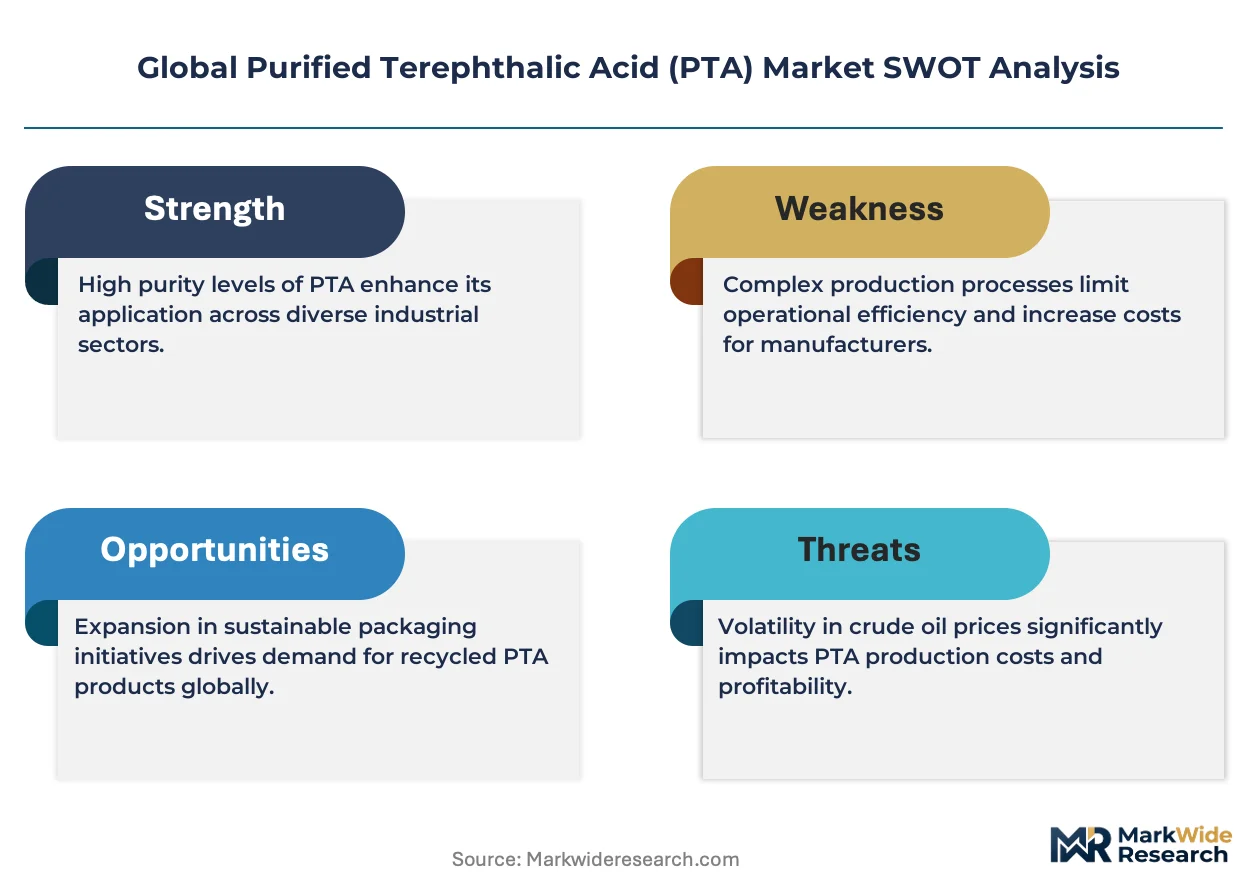
- Feedstock Volatility:The PTA market's profitability is highly sensitive to price fluctuations in its primary feedstock, p-xylene, which is linked to volatile crude oil and naphtha markets.
- Geographic Concentration:Extreme production concentration in China creates significant supply chain vulnerability and logistical challenges for consumers in other regions like Europe and the Americas.
- High Capital Costs:Building new, world-scale PTA plants requires massive capital investment and navigating stringent environmental permits from bodies like the EPA or China's MEE.
Strategic Opportunities
- Bio-Based Feedstocks:Developing commercially viable bio-PTA from renewable sources like plant sugars represents a significant opportunity to decarbonize the polyester value chain and reduce fossil fuel dependency.
- Circular Economy Infrastructure:Building collection and advanced recycling facilities to create closed-loop systems for PET bottles and textiles offers a new value-creation pathway for chemical producers.
- Emerging Market Packaging:Rising consumption in Southeast Asian and Latin American economies creates new demand centers for PET resin, requiring localized PTA supply.
Industry Challenges
- Regulatory Divergence:Producers face the complexity of complying with a patchwork of different chemical regulations, such as REACH in Europe and various national standards across Asia, increasing compliance costs.
- Process Integration:Integrating novel, smaller-scale recycled feedstock streams into massive, continuous-process virgin PTA plants without disrupting quality or efficiency is a major technical hurdle.
- Purity and Certification:Ensuring that recycled PTA meets the stringent purity specifications required for food-contact PET and high-performance fibers requires sophisticated purification and costly certification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Purified Terephthalic Acid (PTA) Market |
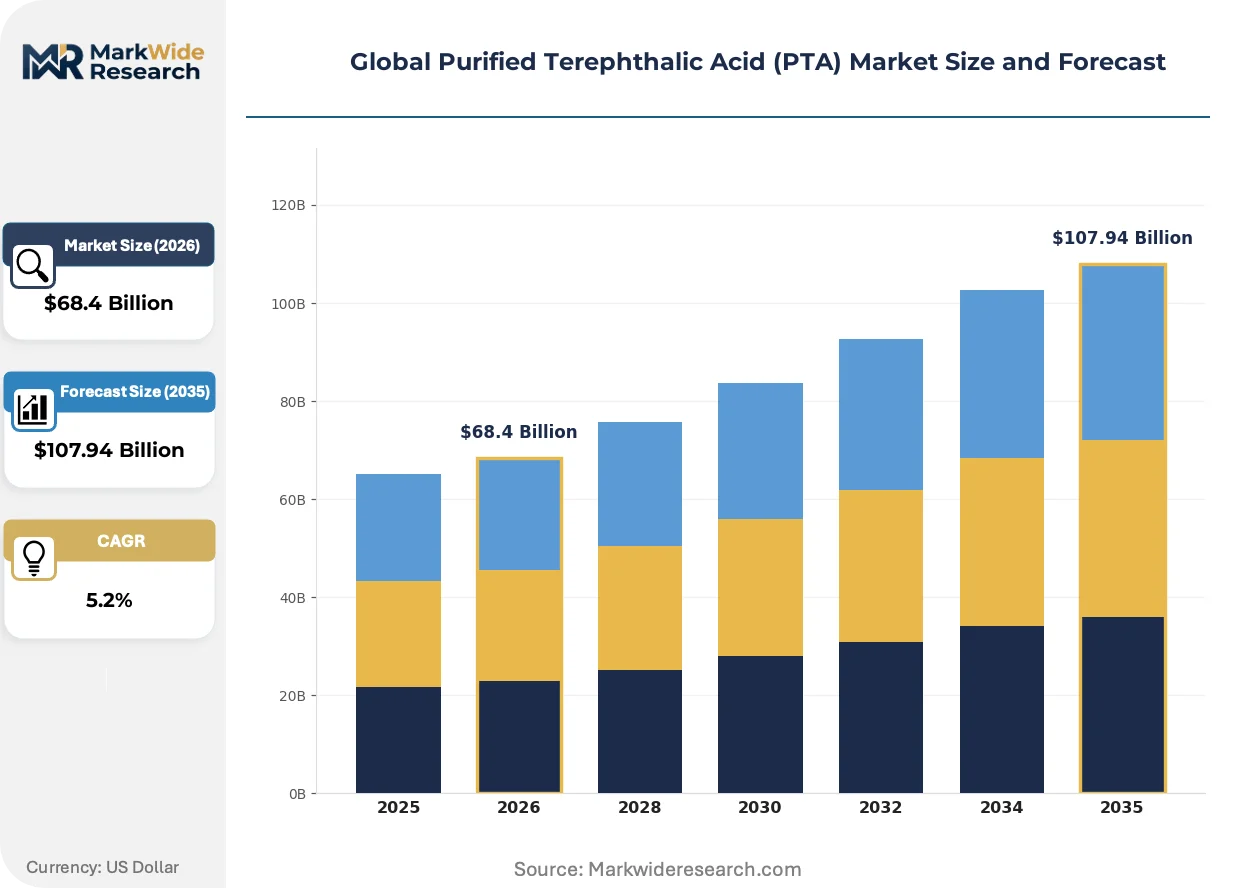
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin PTA, Recycled PTA, Purity Grade A, Purity Grade B, Specialty PTA Application: Polyester Fibers, Plastic Bottles, Film Packaging, PET Resins, Textile Coatings End User Industry: Textile Manufacturers, Packaging Producers, Chemical Suppliers, Appliance Makers, Construction Firms Packaging Type: Bulk Bags, Drums, FIBC Containers, Super Sacks, Totes |
| Companies Covered | Reliance Industries Limited, Sinopec Limited, Indorama Ventures Public Company Limited, BP PLC, Alpek S.A.B. de C.V., Hengli Petrochemical, INEOS, Eastman Chemical Company, Mitsubishi Chemical Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Purified Terephthalic Acid (PTA) Market Strategic Shifts & Innovations
The collision of circular economy principles with the realities of commodity chemical production is defining the market's evolution. This tension drives innovation in feedstock sourcing, regulatory compliance, and the very definition of value in the polyester supply chain.
Modular chemical recycling technologies provide a method for depolymerizing post-consumer PET waste back into its constituent monomers. Specialized recyclers and consumer brands are adopting these systems to secure localized feedstock for recycled PTA. This development is miniaturizing the traditionally centralized, large-scale waste reprocessing model, enabling more distributed and resilient circular supply networks for polyester production.
Europe's Corporate Sustainability Reporting Directive (CSRD) mandates extensive disclosure on supply chain emissions and circularity. This regulation pressures PTA producers and their customers to track and report the use of recycled content. The PET packaging industry is most affected, accelerating procurement of recycled PTA to meet these new transparency requirements.
Major consumer packaged goods firms are shifting from pure cost-based sourcing to specifying materials with certified recycled content. This disrupts the standard commodity market by creating a premium-priced segment for traceable recycled PTA. The trend is most visible in North American and European beverage packaging, where sustainability claims are a competitive tool.
Global Purified Terephthalic Acid (PTA) Market Segmentation
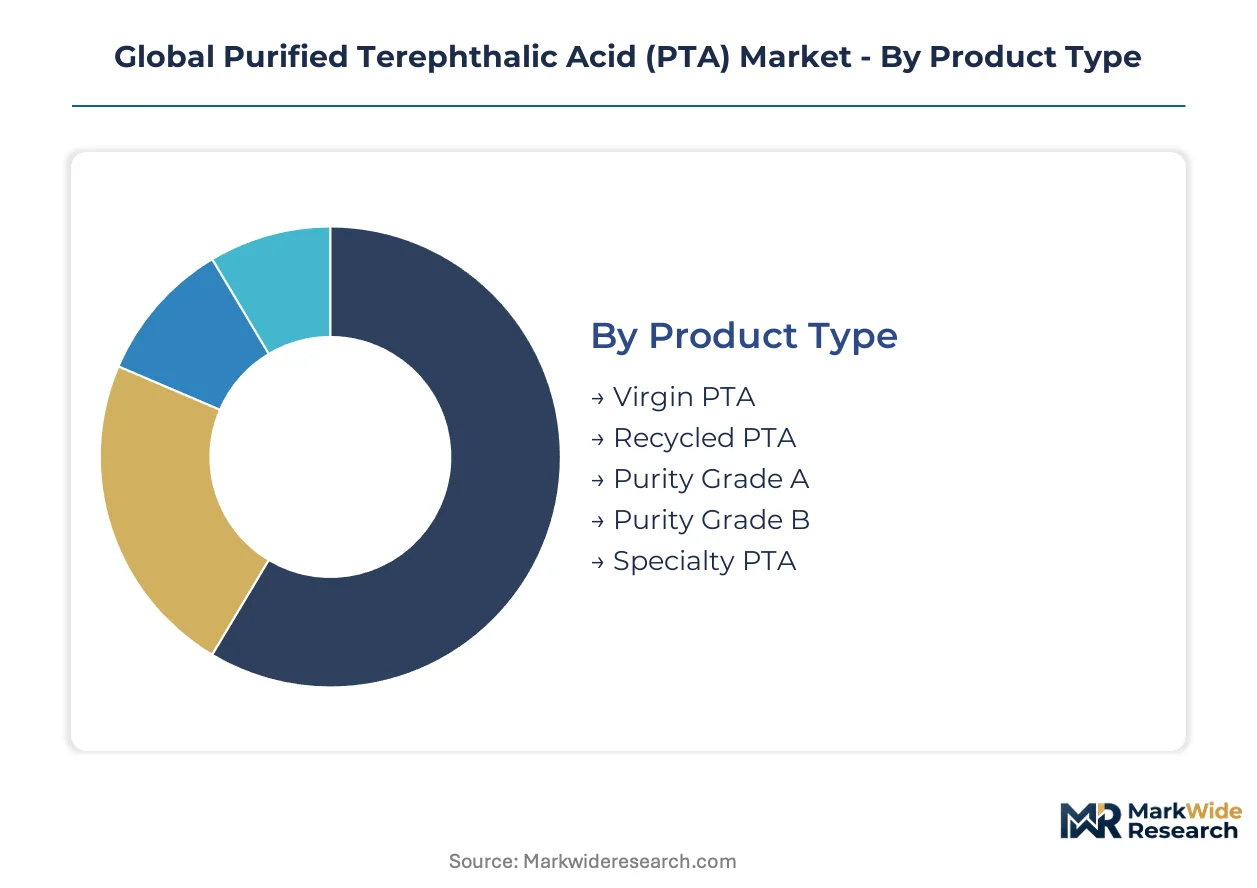
The segmentation of the global purified terephthalic acid market provides critical insights into the varied demand drivers and evolving supply chain dynamics. Understanding these distinct segments allows stakeholders to identify specific growth opportunities and navigate regulatory pressures. This analysis highlights the areas of concentrated value and emerging shifts across the industry.
Product Type:
Margin pools within the product type category reflect the value added through purity and sustainability attributes.
- Virgin PTA:This primary form of PTA is synthesized from p-xylene through catalytic oxidation, forming a white crystalline powder. Demand for virgin PTA remains robust in high-volume polyester fiber production across Asia, driven by its cost-effectiveness and established supply infrastructure.
- Recycled PTA:Derived from post-consumer PET waste via chemical depolymerization, rPTA offers a circular solution for polyester manufacturing. European and North American brand owners increasingly specify rPTA for packaging applications, seeking to meet ambitious recycled content targets.
- Purity Grade A:Purity Grade A meets stringent specifications for optical clarity and low impurities, essential for high-performance PET resins.
- Purity Grade B:Purity Grade B serves diverse industrial applications with less stringent purity requirements, including certain film and fiber production.
- Specialty PTA:Specialty PTA grades offer enhanced properties like improved thermal stability or reduced yellowing for niche technical textile applications.
The dominant share belongs to Virgin PTA, while Recycled PTA is closing the gap fastest.
Application:
The application segments delineate the functional end-uses of purified terephthalic acid, directly correlating with distinct performance requirements and market volumes.
- Polyester Fibers:These fibers, produced from PTA and MEG, form the backbone of the global textile industry for apparel, home furnishings, and industrial fabrics. China's textile sector consumes immense volumes, continually seeking cost-efficient PTA for mass production.
- Plastic Bottles:PET resins, derived from PTA, are widely utilized for beverage and food packaging due to their clarity, strength, and barrier properties. Demand for PET bottles is expanding rapidly in Southeast Asian markets, driven by consumer goods consumption.
- Film Packaging:PTA contributes to PET film production, valued for mechanical strength and barrier performance in food and industrial packaging.
- PET Resins:Beyond fibers and bottles, PET resins apply in various molded goods, strapping, and engineering plastics, offering versatility.
- Textile Coatings:Textile coatings use PTA derivatives for specialized applications, enhancing fabric durability, water resistance, and aesthetic qualities.
Demand for PTA in Polyester Fibers remains substantial, with Plastic Bottles exhibiting the steepest expansion trajectory.
End User Industry:
Customer type segmentation reveals the primary industries driving purified terephthalic acid consumption, each with unique procurement patterns and scale requirements.
- Textile Manufacturers:These firms convert polyester fibers into a vast array of textile products, from clothing to industrial fabrics, representing the largest single consumer of PTA globally. Their procurement is shifting towards verified recycled content.
- Packaging Producers:Companies specializing in plastic bottles, films, and containers rely on PTA-derived PET resins for their packaging solutions. They face increasing mandates for sustainable materials from brand owners in Europe.
- Chemical Suppliers:Chemical Suppliers purchase PTA for further processing into other chemicals or as a bulk intermediate for polymer formulations.
- Appliance Makers:Appliance Makers use PET resins for certain plastic components, valued for their durability and aesthetic properties.
- Construction Firms:Construction Firms use PET in applications like insulation or specialized composites, representing a niche market for PTA derivatives.
Textile Manufacturers constitute the largest end-user segment, while Packaging Producers are increasing their PTA requirements significantly.
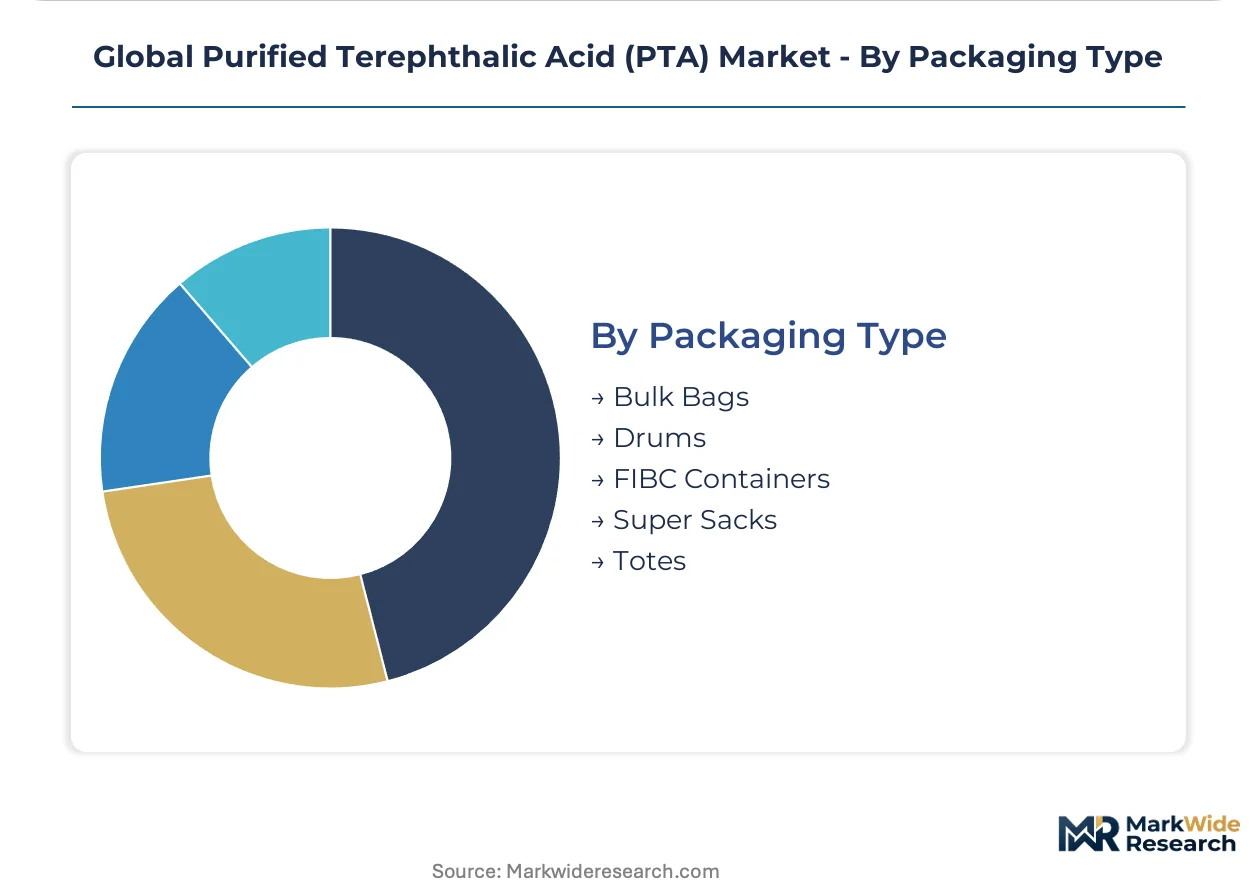
Packaging Type:
The packaging type for purified terephthalic acid reflects logistical considerations and the scale of distribution from producers to downstream users.
- Bulk Bags:These large flexible containers, also known as FIBCs, are commonly used for transporting granular or powdered PTA in high volumes. They optimize shipping efficiency for major industrial customers.
- Drums:Drums offer secure containment for PTA, used for smaller-scale industrial deliveries or specialty grades requiring protected transport.
- FIBC Containers:Flexible Intermediate Bulk Containers (FIBCs) are a cost-effective solution for shipping large quantities of PTA, providing ease of handling and reducing packaging waste. Global trade relies heavily on these for intercontinental shipments.
- Super Sacks:Super Sacks, synonymous with FIBCs, indicate large-capacity flexible containers for dry, flowable PTA materials.
- Totes:Totes provide a reusable and stackable option for PTA, suitable for both transport and temporary storage at manufacturing sites.
Bulk Bags and FIBC Containers collectively dominate PTA distribution, reflecting the commodity nature of the chemical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration heavily influences the global purified terephthalic acid market. Textile manufacturers, particularly in Asia, drive substantial demand for virgin PTA. Packaging producers, primarily in Europe and North America, increasingly seek recycled PTA to meet sustainability mandates. This dual demand shapes regional supply and investment patterns worldwide.
China
China's textile and apparel industries create immense demand for PTA, anchoring global polyester fiber production. The dual carbon goals set by China's MEE are pushing producers towards more sustainable manufacturing practices. Major petrochemical complexes in Jiangsu and Zhejiang provinces concentrate massive PTA production capacities.
India
India's expanding textile sector and a growing consumer market for PET packaging fuel a rising demand for PTA. The PLI scheme encourages domestic manufacturing, including downstream polyester derivatives. Gujarat and Maharashtra states host significant petrochemical and textile manufacturing hubs.
Germany
Germany's packaging industry and commitment to circular economy principles accelerate the adoption of recycled PTA. The EU Green Deal and REACH regulations administered by ECHA drive demand for sustainable materials. The Rhine-Ruhr region remains a crucial industrial center for chemical production and material innovation.
United States
Demand for PET resins in plastic bottles and film packaging largely shapes the purified terephthalic acid market in the United States. EPA air quality standards influence production processes and plant modernization efforts. The Gulf Coast states, particularly Texas and Louisiana, host major petrochemical facilities.
Vietnam
Vietnam's rapidly growing textile and apparel manufacturing sector drives substantial PTA consumption for polyester fiber production. The country's Ministry of Industry and Trade (MOIT) supports foreign investment in industrial development. Ho Chi Minh City and surrounding provinces are key centers for textile and garment factories.
Global Purified Terephthalic Acid (PTA) Market Key Industry Players
Player mix skews toward large-scale, integrated petrochemical giants dominating virgin PTA production. The market structure exhibits a tiered consolidation, with a few global players controlling significant capacity. Strategic archetypes include these integrated commodity producers and specialized recyclers focusing on circular solutions. Key competitive moves involve massive capacity expansions for virgin PTA and strategic investments in advanced recycling infrastructure.
Integrated giants like Sinopec Limited and Hengli Petrochemical anchor a substantial portion of the Asian supply chain with their extensive, co-located manufacturing capabilities. These firms represent the scale-driven end of the market, influencing global supply dynamics for virgin PTA through massive production scale and control over feedstock. Indorama Ventures Public Company Limited exemplifies a player leveraging significant recycling infrastructure and PET collection networks to meet the accelerating demand for recycled content. These distinct approaches highlight the market's dual focus on traditional commodity production and circular economy solutions.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| Sinopec Limited |
| Indorama Ventures Public Company Limited |
| BP PLC |
| Alpek S.A.B. de C.V. |
| Hengli Petrochemical |
| INEOS |
| Eastman Chemical Company |
| Mitsubishi Chemical Holdings |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for purified terephthalic acid lock in both supply access and price visibility for major downstream polyester manufacturers. These contracts often feature variable components tied to feedstock costs, influencing overall market stability.
Pricing Analysis
Cost-plus contracts, often indexed to p-xylene prices, form the foundation for virgin PTA pricing. Price differentiation stems from purity grade, particularly for high-performance PET resins, and volume scale for large industrial buyers. Pricing softness reflects persistent overcapacity in China and fluctuating crude oil markets. Textile manufacturers in Asia exhibit the highest price sensitivity, while specialty chemical producers prioritize consistent purity and performance over marginal cost savings.
Supply Chain Analysis
High inventory levels and extended lead times characterize the global PTA supply chain due to its commodity nature and reliance on sea freight. Geographic supply concentration centers heavily in China, with significant production also in India and the United States. The industry draws from p-xylene, which itself depends on volatile naphtha and crude oil markets. A structural risk is the single-source vulnerability created by extreme production concentration in China. Distribution runs through bulk shipments directly to large integrated polyester and PET resin manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The purified terephthalic acid market presents a fragmentation opportunity, driven by accelerating global mandates for circularity and the demand for traceable recycled content.
For Market Incumbents:
Fortify existing virgin PTA market share through continuous process optimization and backward integration into p-xylene production. Invest strategically in advanced chemical recycling technologies to mitigate the threat of rPTA disruption and meet sustainability mandates. Optimize global logistics networks to reduce delivery times and costs for key regional customers. Diversify feedstock sources by exploring bio-based PTA pathways to reduce fossil fuel dependency.
For New Entrants and Emerging Players:
Certification fast-tracks for recycled content offer a viable entry point into the PTA market, particularly in European packaging applications. Target localized, modular chemical recycling facilities near post-consumer PET waste streams to create resilient circular supply networks. Focus on specialty PTA grades with enhanced properties for technical textiles or high-performance films, offering a premium-priced segment. A go-to-market angle emphasizing verified sustainability and supply chain transparency can differentiate new players.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among advanced chemical recycling technology providers and bio-based feedstock innovators. Long-term viability in the PTA market over the next five to ten years hinges on securing access to circular and sustainable feedstocks. Acquisition targets should include companies with proven chemical depolymerization intellectual property or established PET collection networks. A key signal to watch is the sustained price premium for certified recycled PTA over virgin alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases global supply of virgin PTA, primarily from Asian producers like Sinopec Limited and Hengli Petrochemical. |
| Green Manufacturing Transition | Reduces environmental footprint and ensures compliance with regulations like the EU Green Deal and China's MEE emissions controls. |
| Long-term Supply Agreement | Secures stable feedstock supply for downstream polyester manufacturers and provides price visibility for both parties. |
| Joint Venture in Recycling | Accelerates the development and deployment of advanced chemical recycling infrastructure for rPTA production. |
| Bio-Based Feedstock R&D | Explores renewable alternatives to p-xylene, decarbonizing the polyester value chain and reducing fossil fuel reliance. |
Research Approach
Initial hypotheses were tested against primary input from PTA plant managers, downstream polyester producers, chemical recycling technology developers, and brand sustainability officers, and refined through iterative analysis. This involved in-depth interviews with key industry stakeholders, complemented by extensive secondary research. Secondary data sources included customs and trade data, industry association reports from ACC and Cefic, SEC 10-K filings, and regulatory body publications from ECHA and EPA. The final market estimates were derived through a robust bottom-up and top-down triangulation approach.
Variance decomposition isolated the impact of key market drivers and restraints across the analysis window, informing the quantitative model. The analytical framework encompassed segmentation across product type, application, end-user industry, packaging type, purity grade, and regional production hubs. Compound annual growth rates were projected by integrating historical data with forecast assumptions for each segment. Key industry-specific forecast inputs included p-xylene price volatility and projected polyester fiber demand outlook.
Decision-makers should treat outputs as directional under the base assumptions regarding global trade policies and crude oil stability; material deviation would warrant model refresh and re-evaluation. Forecasts reflect assumptions concerning technological advancements in recycling and the enforcement of sustainability mandates. Geopolitical shifts and unforeseen feedstock price shocks represent significant risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Alkali Metal Hydroxides Market