
 Bio Based Resin Market | 2026-2036
Bio Based Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Based Resin Market Intelligence
The premium bio-based resin tier is rebalancing away from commodity polylactic acid toward high-performance bio-polyamides and bio-polyurethanes with automotive-grade thermal stability. Arkema SA leverages its specialty polyamide heritage to anchor European supply for under-hood components. Corbion sustains fermentation scale through backward integration into Brazilian sugarcane feedstock. Novamont SpA dominates compostable film formulations for Italian packaging converters.
Bio-based resins comprise polymers synthesized from renewable biomass feedstocks—sugar cane, corn starch, or cellulose—through fermentation or catalytic polymerization, achieving properties comparable to fossil-derived thermoplastics for injection molding and extrusion. Polyhydroxyalkanoates remain commercially immature with limited thermal range, constraining margin pools to medical and agricultural niche applications. Bio-polyethylene, produced via dehydration of bioethanol, leads volume due to drop-in compatibility with existing extrusion infrastructure. Packaging applications capture the widest end-use footprint, though automotive components manufacturing generates superior per-kilogram pricing through performance certification requirements.
The EU Green Deal and REACH framework restrict persistent petrochemical additives in consumer-facing products, compelling reformulation toward bio-derived alternatives. EPA bio-preferred procurement standards in the United States redirect federal purchasing toward certified biobased content thresholds. FDA food-contact clearance requirements govern polylactic acid migration limits in food and beverage packaging. Stakeholders must monitor feedstock price volatility against fossil parity curves and pre-empt capacity commitments before polymerization technology licensure windows narrow.
Market Dynamics
Automotive certification standards for under-hood thermal performance are compressing development cycles and forcing resin formulators to prove drop-in compatibility with existing injection molding infrastructure before tier-one suppliers commit volume.
Growth Catalysts
- EU Green Deal compliance mandates:REACH restrictions on persistent petrochemical additives in consumer products compel packaging converters to reformulate with fermentation-derived alternatives.
- Bio-polyamide thermal stability:Automotive interior panels and under-hood components now tolerate the 150°C continuous service temperatures required by OEM specifications.
- German industrial clustering:Pilot production facilities concentrate near Ludwigshafen, enabling co-location between resin producers and automotive tier-one suppliers for rapid iteration.
Market Restraints
- Brazilian sugarcane price volatility:Fermentation feedstock costs swing with harvest yields and ethanol diversion, compressing margin predictability for polylactic acid producers.
- Polyhydroxyalkanoate thermal limitations:Narrow processing windows below 180°C constrain deployment to medical and agricultural niches, excluding automotive and electronics.
- Petrochemical resin substitution threat:Drop-in bio-polyethylene commands premium pricing against fossil-derived polyethylene with identical performance, slowing cost-parity achievement.
Strategic Opportunities
- Compostable film packaging in Italy:Italian converters face landfill diversion targets that favor bio-based formulations with home-compostable certification.
- EPA bio-preferred procurement thresholds:Federal purchasing mandates in the United States create guaranteed offtake for certified biobased content in durable goods.
- Fermentation-catalytic polymerization convergence:Integrated biorefineries combining sugar processing with direct polymerization reduce intermediate purification costs.
Industry Challenges
- FDA food-contact migration testing timelines:Polylactic acid clearance for beverage packaging requires 18-24 month validation cycles that delay commercial launch.
- Polymerization technology licensure scarcity:Proprietary catalyst systems for bio-polyamide production concentrate with limited technology holders, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio Based Resin Market |
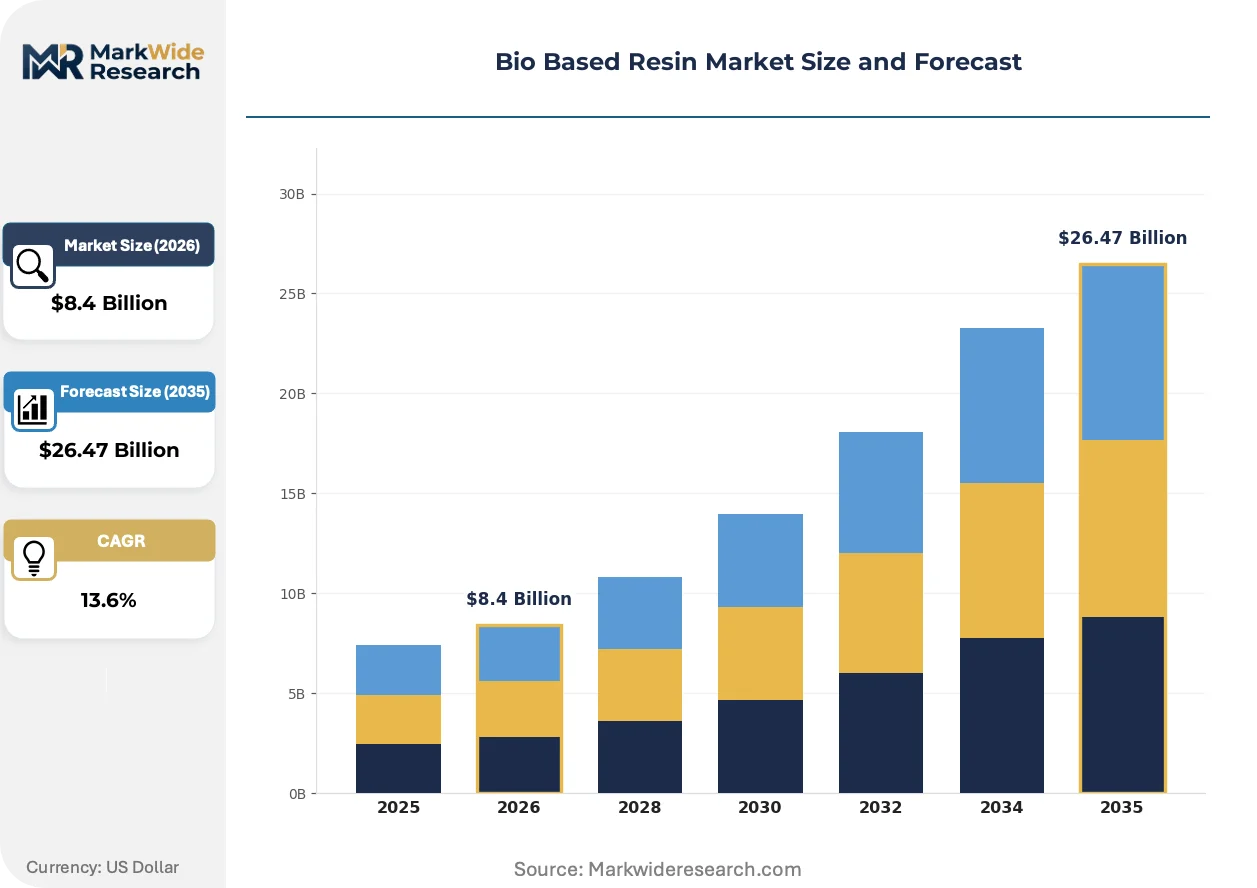
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resin Type: Polylactic Acid, Polyhydroxyalkanoates, Bio-Polyethylene, Bio-Polyamides, Bio-Polyurethanes Application: Packaging, Automotive Components Manufacturing, Consumer Electronics Housing, Agricultural Films, Textile Coatings End User Industry: Food & Beverage Producers, Vehicle Manufacturers, Electronics Fabricators, Agricultural Equipment Makers, Apparel Producers Production Process: Fermentation, Polymerization, Condensation, Blending, Extrusion Molding |
| Companies Covered | Arkema SA, Corbion, NatureWorks LLC, Danimer Scientific, Novamont SpA, BASF SE, DuPont, Trinseo, Braskem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Based Resin Market Strategic Shifts & Innovations
Formulation science is pivoting from commodity drop-ins toward performance-differentiated grades that command specification premiums in automotive and medical verticals.
Bio-polyurethanes for interior panel applications is absorbing the specification requirements previously met by fossil-derived thermoplastic polyurethanes. Tier-one seating suppliers in Germany and the Czech Republic now qualify these grades for 120,000-cycle abrasion resistance. This absorption is compressing the timeline for full automotive interior conversion from petrochemical baselines.
REACH authorization requirements for diisocyanates in polyurethane production are forcing reformulation toward bio-based aliphatic alternatives. The industrial consequence is a scramble for non-phosgene process routes to bio-polyurethane precursors. Automotive seating and insulation foam segments in Germany, France, and Italy are responding with accelerated supplier audits of fermentation-derived polyol capabilities.
Specification-driven procurement now dominates automotive resin selection, displacing pure cost-per-kilogram comparisons. Tier-one suppliers consolidate qualified material lists to three approved sources per application, locking out unproven entrants. This concentration is most visible in German automotive supply chains, where OEM sustainability scorecards weight biobased content at 15% of supplier rating.
Bio Based Resin Market Segmentation
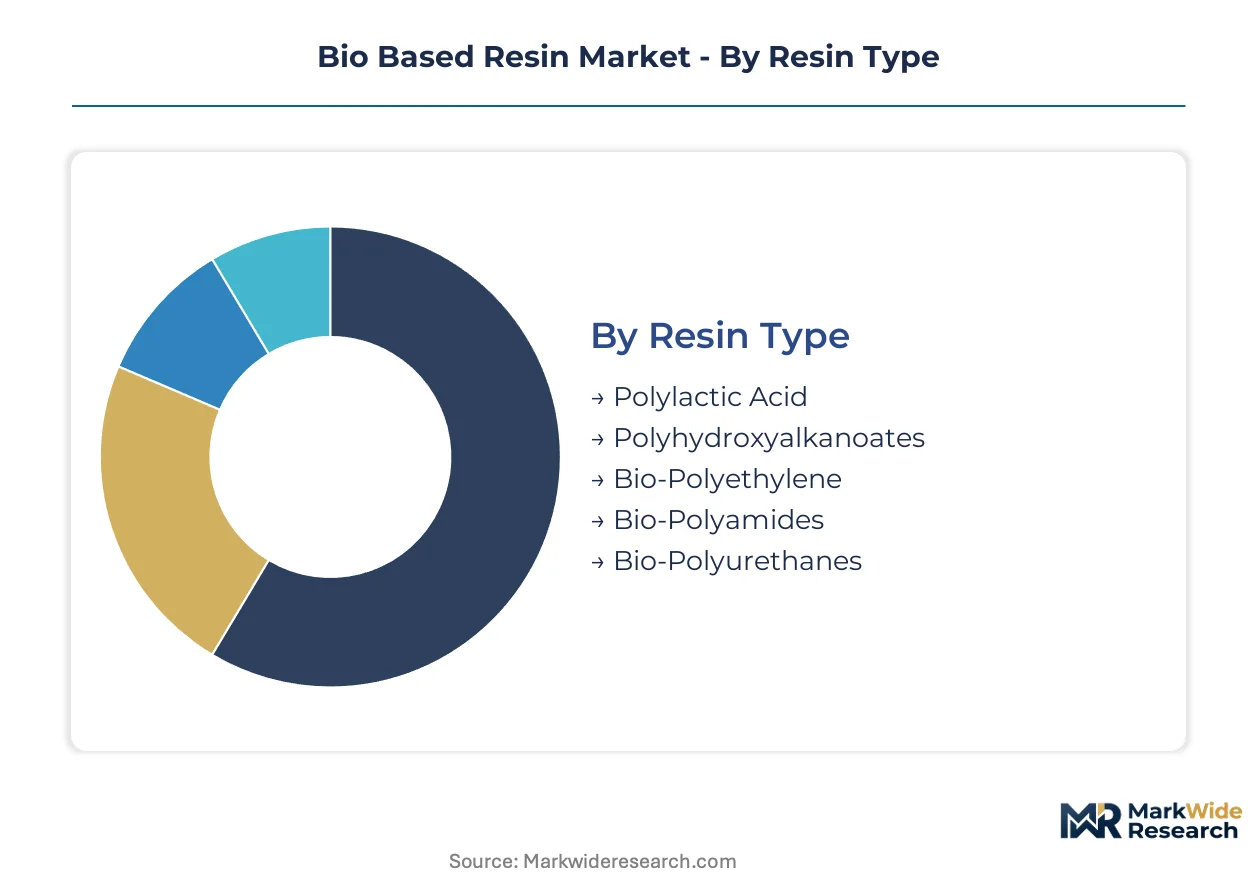
Segmentation in bio-based resins reveals how feedstock chemistry, thermal performance thresholds, and regulatory compliance requirements partition value across distinct specification tiers. Formulators align resin selection with end-use certification demands rather than commodity substitution economics.
Resin Type:
Technical specifications around thermal stability and drop-in compatibility define competitive positioning across polymer chemistries.
- Bio-Polyamides:Semi-aromatic and aliphatic grades achieve 150°C continuous service temperatures through renewable sebacic acid and castor oil derivatives. Automotive under-hood applications in Germany and the Czech Republic now specify these grades for charge air cooler housings and engine covers.
- Bio-Polyurethanes:Fermentation-derived polyols combined with aliphatic diisocyanates replace fossil thermoplastic polyurethanes in seating and interior panels. REACH diisocyanate authorization restrictions are accelerating supplier qualification timelines for bio-based alternatives.
- Polylactic Acid:Fermentable sugar feedstocks yield high-clarity grades for thermoformed food packaging with FDA food-contact clearance.
- Bio-Polyethylene:Drop-in compatibility with existing extrusion infrastructure maintains volume leadership despite premium pricing against fossil equivalents.
- Polyhydroxyalkanoates:Narrow processing windows below 180°C constrain deployment to medical sutures and agricultural mulch films.
Bio-Polyethylene leads on scale; bio-polyamides lead on momentum.
Application:
End-use performance certification requirements stratify pricing power and formulation investment intensity.
- Automotive Components Manufacturing:Interior panels, seating foams, and under-hood components demand 120,000-cycle abrasion resistance and 150°C thermal stability. OEM sustainability scorecards in Germany weight biobased content at 15% of supplier ratings.
- Packaging:Thermoformed trays, films, and bottles capture volume through PLA and bio-PE drop-in compatibility. Italian landfill diversion targets favor home-compostable certification for flexible film converters.
- Consumer Electronics Housing:Flame-retardant bio-polyamide grades for laptop and smartphone enclosures require UL94 V-0 certification.
- Agricultural Films:Soil-biodegradable mulch films use PHA and PLA blends for controlled degradation timelines.
- Textile Coatings:Bio-polyurethane dispersions provide water resistance and hand-feel modification for synthetic leather applications.
Packaging dominates volume throughput; automotive commands the steepest expansion trajectory.
End User Industry:
Procurement sophistication and sustainability disclosure obligations vary sharply across buyer categories.
- Vehicle Manufacturers:Tier-one supplier consolidation to three approved sources per application locks in qualified resin formulators. German OEMs co-locate technical development with resin producers near Ludwigshafen.
- Food & Beverage Producers:Migration testing timelines for FDA food-contact clearance extend 18-24 months, delaying commercial launch for new PLA grades.
- Electronics Fabricators:Flame-retardant and aesthetic specifications drive premium pricing for specialty bio-polyamides.
- Agricultural Equipment Makers:Controlled degradation requirements for mulch films favor PHA-PLA blend formulations.
- Apparel Producers:Bio-polyurethane coating specifications for synthetic leather respond to ZDHC chemical compliance programs.
Vehicle manufacturers concentrate the most demanding certification requirements; food and beverage producers offer the broadest addressable volume base.
Production Process:
Process technology selection determines capital intensity, feedstock flexibility, and intermediate purification costs.
- Fermentation:Sugar-to-lactide and sugar-to-polyol routes anchor Brazilian and Thai feedstock integration. Corbion maintains backward integration into sugarcane supply for PLA monomer security.
- Polymerization:Ring-opening polymerization of lactide and condensation of bio-diols with diacids yield performance thermoplastics. Proprietary catalyst systems for bio-polyamides concentrate with limited technology licensors.
- Condensation:Bio-sebacic acid and diamine routes to polyamide 610 and 1010 leverage castor oil derivatives.
- Blending:Compatibilized PLA-PHA and PLA-polymer carbonate blends extend property envelopes for film and foam applications.
- Extrusion Molding:Final shaping operations for packaging and automotive components require drop-in rheological matching with fossil resin baselines.
Fermentation commands the largest installed capacity base; polymerization offers the tightest technology scarcity premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and fermentation engineers cluster around established petrochemical hubs, creating talent pipelines that accelerate bio-based resin scale-up.
Germany
Automotive OEMs specify bio-polyamides for under-hood components with 150°C thermal requirements. EU Green Deal REACH restrictions on petrochemical additives compel reformulation toward fermentation-derived alternatives. Pilot production facilities concentrate near Ludwigshafen, enabling co-location between BASF SE and tier-one suppliers for rapid iteration cycles.
United States
Federal procurement mandates through EPA bio-preferred standards redirect durable goods purchasing toward certified biobased content thresholds. FDA food-contact clearance requirements govern polylactic acid migration limits in beverage packaging. NatureWorks LLC anchors fermentation capacity in the Midwest, securing feedstock integration for PLA monomer production.
Italy
Packaging converters face landfill diversion targets that favor home-compostable film formulations with bio-based certification. EFSA food-contact regulations align with national waste hierarchy implementation. Novamont SpA dominates compostable film supply for flexible packaging producers in the Po Valley industrial corridor.
Brazil
Sugarcane harvests and ethanol diversion economics swing fermentation feedstock costs for polylactic acid producers. ANVISA pharmaceutical-grade polymer standards govern medical application clearances. Corbion maintains backward integration into Brazilian sugarcane supply, securing monomer security for PLA production.
France
REACH diisocyanate authorization restrictions accelerate supplier audits of bio-based polyurethane capabilities for automotive seating. ECHA chemical safety assessments drive reformulation toward aliphatic alternatives. Arkema SA leverages specialty polyamide heritage to anchor European supply for under-hood components.
Bio Based Resin Market Key Industry Players
Top-tier vendors anchor the premium performance tier, while mid-scale fermentation specialists occupy commodity-grade positions. The vendor base stratifies across three concentration levels: integrated petrochemical majors with bio-divisions, dedicated biopolymer pure-plays, and regional compounders serving niche certifications. Two strategic archetypes dominate: backward-integrated feedstock controllers and polymerization technology licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with technology licensure windows narrowing for proprietary catalyst systems.
Within the integrated major tier, BASF SE and Arkema SA occupy positions that exemplify petrochemical heritage leveraged toward high-performance bio-polyamide development. Among dedicated biopolymer specialists, Novamont SpA represents the compostable film formulation archetype, while Corbion anchors the fermentation-scale pure-play model with feedstock integration. NatureWorks LLC sits within the North American PLA production tier.
| Leading Market Players |
|---|
| Arkema SA |
| Corbion |
| NatureWorks LLC |
| Danimer Scientific |
| Novamont SpA |
| BASF SE |
| DuPont |
| Trinseo |
| Braskem |
| Others |
Cost & Logistics Intelligence
Fermentation-to-polymerization technology convergence simultaneously compresses intermediate purification costs and concentrates supply leverage among integrated biorefinery operators. This dual transformation rewards operators with captive sugarcane or corn starch supply while squeezing toll processors dependent on spot feedstock markets.
Pricing Analysis
Unbundled resin supply competes against bundled formulation-plus-certification packages. Three-tier pricing structure across automotive-grade, packaging-grade, and commodity-grade levels reflects thermal stability certification and FDA food-contact clearance tiers. Cost compression in polylactic acid is intensifying because Brazilian ethanol diversion swings fermentation feedstock economics. Packaging converters exhibit highest price sensitivity; automotive tier-one suppliers prioritize performance certification over per-kilogram cost.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs require tier-one suppliers to qualify three approved resin sources per application, fragmenting procurement across multiple geographers. Supply concentrates in Germany, Brazil, and Thailand where fermentation scale and polymerization catalyst expertise cluster. Raw material flows draw from sugarcane harvests, castor oil derivatives, and bioethanol dehydration streams. Single-source vulnerability concentrates in proprietary bio-polyamide catalyst systems held by limited technology licensors. Distribution runs through compounder networks serving injection molders and film converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance premiums and Brazilian feedstock cost advantages, with regulatory stringency in Europe sustaining price premiums that offset higher production costs.
For Market Incumbents: Acquire fermentation capacity in Brazilian sugarcane belts to lock in feedstock cost advantages against ethanol diversion volatility. Secure proprietary catalyst licensure for bio-polyamide polymerization before technology windows narrow. Consolidate qualified supplier status with German automotive OEMs through co-located technical development facilities near Ludwigshafen.
For New Entrants and Emerging Players: Begin with compostable film formulations for Italian packaging converters facing landfill diversion mandates. Target home-compostable certification segments where Novamont's dominance leaves white space in regional supply. Pursue direct technical partnership with Po Valley converters to bypass established distribution channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation specialists lacking downstream polymerization capabilities. Long-term viability hinges on backward integration into feedstock supply or forward integration into automotive qualification programs. Watch for EPA bio-preferred procurement threshold expansions as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive Brazilian sugarcane access insulates Corbion against ethanol diversion price swings. |
| Automotive Certification Investment | Arkema's 150°C thermal stability qualification locks in German OEM specification requirements. |
| Compostable Film Formulation Partnership | Novamont's Italian converter relationships capture landfill diversion mandate premiums. |
| Proprietary Catalyst Technology Licensure | Limited bio-polyamide polymerization licensors constrain competitor capacity expansion timelines. |
| Co-located Pilot Production Facilities | BASF's Ludwigshafen clustering accelerates iteration cycles with tier-one automotive suppliers. |
Research Approach
Bottom-up automotive and packaging demand modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with resin formulators, automotive tier-one procurement directors, packaging converter operations managers, and polymerization technology licensors combined with secondary validation against EU ECHA regulatory filings, EPA bio-preferred procurement databases, and Brazilian ANVISA pharmaceutical-grade standards. Top-down customs data on bioethanol and sugarcane trade flows triangulated against bottom-up plant capacity announcements.
Historical trendline analysis across resin type, application, and production process segments established baseline growth patterns. Segmentation modeling spanned thermal performance grade, end-use certification tier, feedstock chemistry, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand projections and capacity expansion timelines. Industry-specific forecast inputs incorporated REACH authorization timelines for diisocyanate alternatives and FDA food-contact migration testing durations.
Several conditions sit outside the modeled scope, including breakthrough catalytic polymerization technologies, abrupt EU Green Deal enforcement escalations, and sugarcane harvest failure events. Forecasts reflect stated capacity commitments and regulatory implementation schedules. Deviation in Brazilian ethanol policy or automotive OEM sustainability scorecard weightings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
Rotomolding Compound Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Polyester Polyol Market