
 Acrylic Monomers Market | 2026-2036
Acrylic Monomers Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Monomers Market Analytics
Specialty coatings formulators are redrawing procurement priorities across the acrylic monomers value chain, favoring high-purity grades with verified low-VOC profiles. Mitsubishi Chemical leverages captive methacrylate technology to sustain margin advantages in optical-grade segments. Dow anchors North American supply through integrated propylene-derivative complexes along the US Gulf Coast. BASF competes on formulation partnerships, embedding monomer supply into coatings R&D collaborations.
Acrylic monomers are unsaturated carbonyl compounds containing vinyl or allylic functionality, typically polymerized through free-radical initiation to form thermoplastic resins with glass transition temperatures tunable from -50°C to 120°C depending on ester substitution. Methyl methacrylate dominates value generation due to its role in polymethyl methacrylate production for automotive lighting and architectural glazing. Butyl acrylate leads volume in coatings adhesives segments where flexibility and weatherability command premium pricing over commodity alternatives. Emulsion forms concentrate growth in waterborne architectural coatings as solvent-phase regulation tightens across manufacturing jurisdictions.
EPA Toxic Substances Control Act reporting requirements and REACH registration obligations shape product specifications and cross-border shipment documentation for acrylic monomers entering US and European formulations. China's MEE enforces dual carbon goals that constrain coal-based acrylic acid expansions, redirecting investment toward propane dehydrogenation feedstock routes. Stakeholders must monitor feedstock cost spreads between propylene and propane derivatives while tracking regional purity standard divergence that fragments grade specifications.
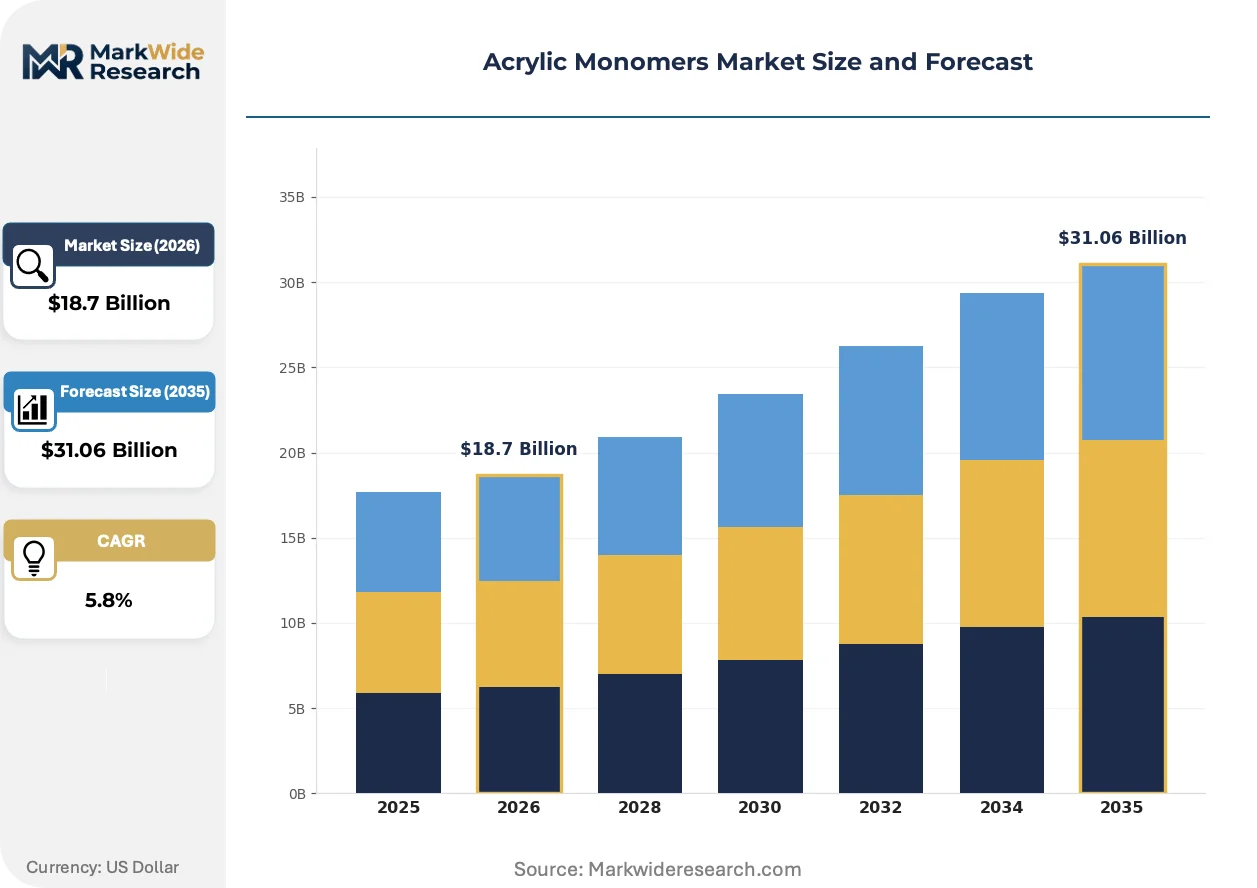
Market Dynamics
Feedstock route diversification is compressing cost spreads between propylene-derivative and propane-derivative acrylic acid production, reshaping competitive positioning among integrated producers.
Growth Catalysts
- Waterborne architectural coatings:EPA VOC emission limits and REACH solvent-phase restrictions are accelerating emulsion-grade acrylic monomer consumption across North American and European construction markets.
- Optical-grade polymethyl methacrylate:Automotive LED lighting penetration and architectural glazing specifications are pulling high-purity methyl methacrylate through specialty polymer channels.
- China's dual carbon enforcement:MEE constraints on coal-based acrylic acid expansions are redirecting investment toward propane dehydrogenation feedstock integration.
Market Restraints
- Propane-propylene spread volatility:Feedstock cost oscillations between naphtha-cracking and PDH routes destabilize margin forecasting for non-integrated producers.
- China capacity concentration:Domestic acrylic acid expansions along the Yangtze River Delta are creating regional oversupply pressure that depresses export pricing power.
- Styrene-acrylic substitution economics:Cost-competitive styrene-acrylic copolymers in cost-sensitive coatings segments constrain pure acrylic pricing premiums.
Strategic Opportunities
- India specialty coatings:BIS quality mark requirements and PLI scheme incentives for domestic chemical manufacturing are opening formulation-grade monomer supply partnerships.
- Bio-based acrylic acid:Fermentation-derived 3-hydroxypropionic acid routes are converging with catalytic dehydration technologies to create certified renewable content streams.
- Direct-to-formulator digital platforms:Specialty monomer distributors are deploying blockchain-verified purity documentation to bypass traditional channel markups.
Industry Challenges
- REACH-EPA regulatory divergence:Divergent purity thresholds and carbon accounting documentation requirements are fragmenting grade specifications and complicating cross-border shipment compliance.
- Process control engineering scarcity:Free-radical polymerization reactor optimization expertise is concentrating among retiring specialist cohorts, constraining debottlenecking timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Monomers Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Methacrylate, Butyl Acrylate, Ethyl Acrylate, Hydroxyethyl Methacrylate End Use Industry: Coatings, Adhesives, Textiles, Plastics Form: Liquid, Solid, Powder, Emulsion Grade: Industrial Grade, Laboratory Grade, Commercial Grade, High Purity |
| Companies Covered | Mitsubishi Chemical, Evonik Industries, Dow, Sumitomo Chemical, LG Chem, Arkema, BASF, Nippon Shokubai, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Monomers Market Evolving Landscape
Reactive diluent technologies and advanced process analytical chemistry are compressing formulation development cycles while enabling real-time quality verification across distributed production networks.
Continuous flow reactor technology for acrylic monomer production is fragmenting the traditional batch-process equipment supply base. Specialty producers in Germany and Japan are adopting modular microreactor systems that enable rapid grade switching and reduced solvent inventories. This capability is compressing minimum order quantities and enabling just-in-time supply contracts for niche optical-grade specifications.
REACH registration renewal obligations and EU Green Deal carbon border adjustment mechanisms are tightening documentation requirements for acrylic monomer imports into European formulations. Downstream coatings manufacturers are now demanding cradle-to-gate emission certifications that extend upstream to propylene feedstock origins. German automotive OEMs and French architectural coating formulators are driving the strictest verification protocols.
Buyer concentration among top-ten specialty coatings formulators is compressing negotiation leverage for mid-tier monomer suppliers. Direct long-term supply agreements are displacing spot-market transactions in high-purity methyl methacrylate procurement. This pattern is most visible in North American automotive lighting supply chains, where tier-one polymer compounders have consolidated purchasing through integrated supply agreements.
Acrylic Monomers Market Segmentation
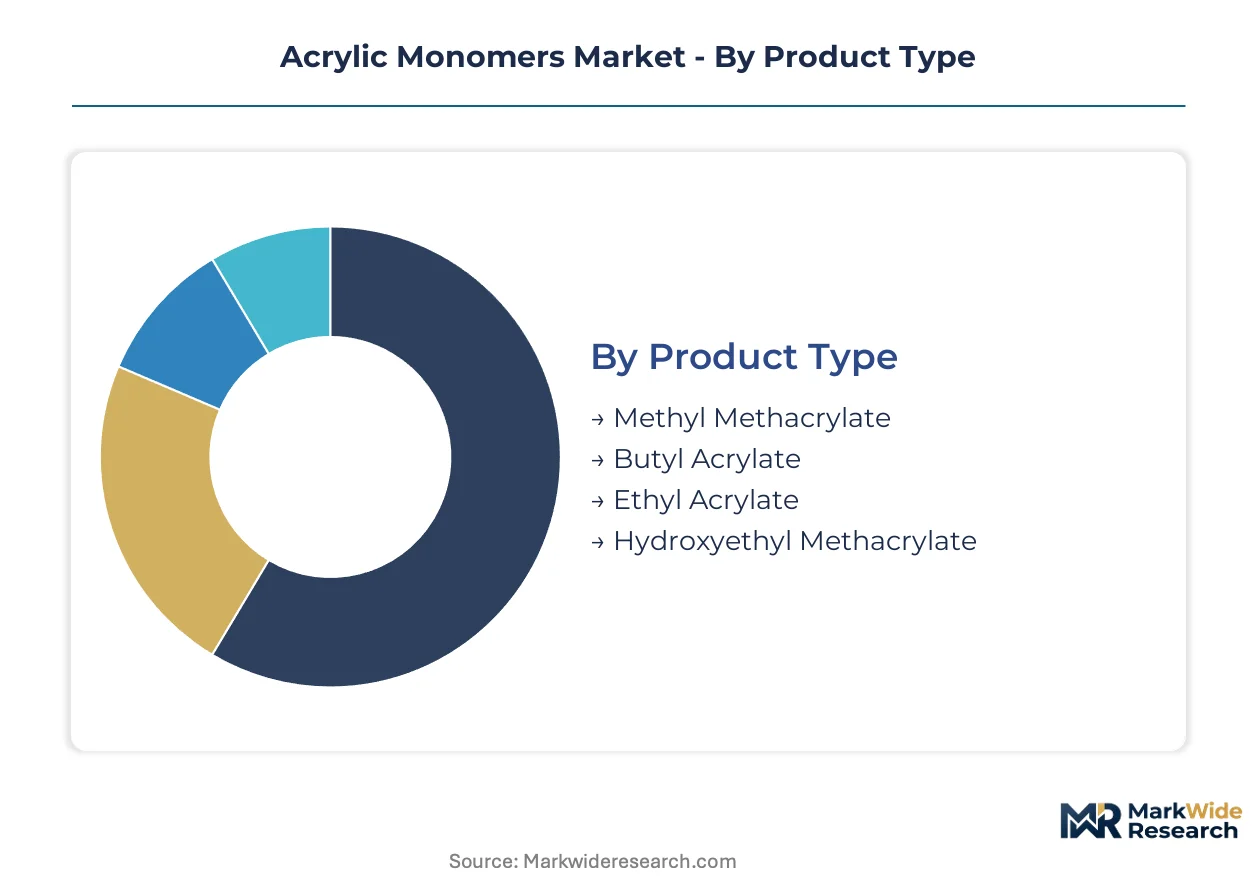
Acrylic monomers fragment across four distinct taxonomies that shape procurement workflows and regulatory compliance burdens. Product type determines feedstock exposure and purity thresholds. End-use industry dictates formulation specifications and certification requirements. Form and grade classifications intersect with REACH registration obligations and EPA Toxic Substances Control Act reporting protocols.
Product Type:
REACH registration renewal obligations and EPA Toxic Substances Control Act reporting requirements create divergent compliance burdens across methyl methacrylate, butyl acrylate, and specialty ester derivatives.
- Methyl Methacrylate:Unsaturated ester with vinyl functionality polymerizing to polymethyl methacrylate resins with glass transition temperatures near 105°C. Demand concentrates in German automotive LED lighting supply chains and French architectural glazing specifications, pulled by optical-grade purity requirements that exceed standard industrial thresholds.
- Butyl Acrylate:Flexible ester monomer producing soft, tacky homopolymers with glass transition near -54°C. Coatings formulators across the US Gulf Coast and Yangtze River Delta absorb the majority of volume, driven by waterborne architectural coatings substitution away from solvent-phase systems under tightening VOC limits.
- Ethyl Acrylate:Intermediate glass transition ester balancing hardness and flexibility in copolymer systems. Textile finishing operations in India and adhesive manufacturers in Japan represent primary offtake channels.
- Hydroxyethyl Methacrylate:Hydroxyl-functional methacrylate enabling crosslinkable coating networks. Medical device coatings and dental applications in Switzerland and South Korea command premium pricing over commodity esters.
Butyl acrylate handles the majority of throughput; hydroxyethyl methacrylate is expanding most quickly on specialty medical and dental applications.
End Use Industry:
Customer concentration among top-ten specialty formulators compresses negotiation leverage differently across coatings, adhesives, textiles, and plastics channels.
- Coatings:Architectural, automotive, and industrial protective formulations consuming emulsion-grade and high-purity liquid monomers. EPA VOC emission limits and REACH solvent-phase restrictions in Germany and France accelerate waterborne system penetration.
- Adhesives:Pressure-sensitive and structural bonding applications requiring tackified acrylic copolymers. Packaging converters in India and electronics assemblers in South Korea drive specification-grade demand.
- Textiles:Fiber finishing, nonwoven binders, and fabric coatings utilizing soft-hand acrylic emulsions. Indian textile hubs around Surat and Tiruppur absorb significant butyl acrylate volumes.
- Plastics:PMMA sheet and molding compounds for automotive lighting, signage, and medical devices. Japanese optical-grade polymerization and German automotive glazing specifications set purity benchmarks.
Coatings commands the dominant revenue share; adhesives is gaining share fastest on electronics and packaging substitution trends.
Form:
Physical state determines logistics costs, storage safety protocols, and formulation integration methods across liquid, solid, powder, and emulsion presentations.
- Liquid:Standard bulk shipment form for unpolymerized monomers requiring inhibitor stabilization and temperature-controlled transport. Integrated producers along the US Gulf Coast and Rotterdam-Antwerp corridor dominate bulk liquid supply.
- Solid:Crystalline or bead forms for specialized polymerization processes and controlled-release applications. Japanese specialty chemical houses and Swiss pharmaceutical-grade suppliers concentrate solid form production.
- Powder:Spray-dried emulsion polymers for dry-mix construction materials and powder coatings. German construction chemical formulators and Indian dry-mix mortar producers represent primary demand.
- Emulsion:Water-based colloidal dispersions eliminating solvent handling in architectural coatings manufacturing. French and German coatings producers lead emulsion-grade specification development under EU Green Deal carbon accounting protocols.
Liquid form carries the volume base; emulsion form is climbing fastest on regulatory-driven waterborne substitution.
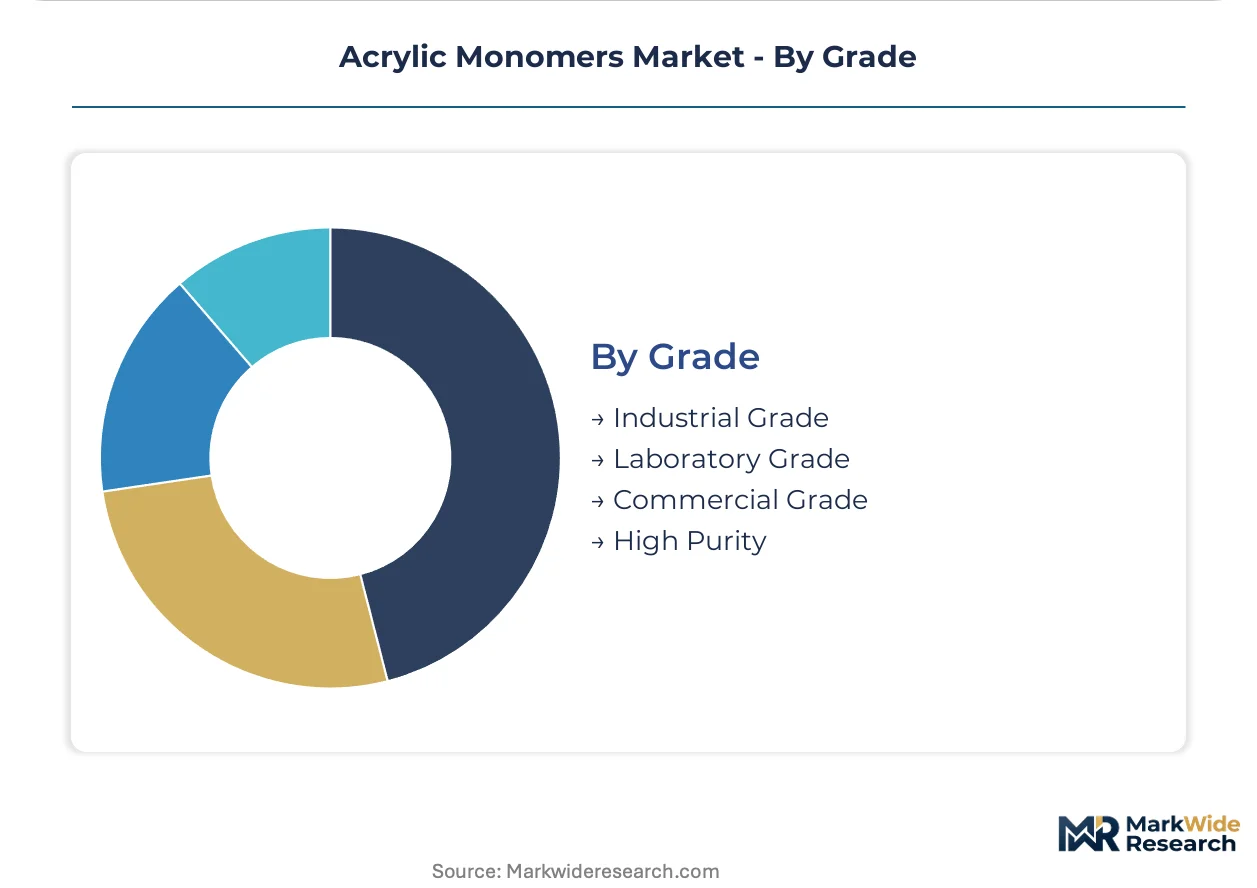
Grade:
Purity thresholds fragment specifications across industrial, laboratory, commercial, and high-purity tiers with divergent analytical certification requirements.
- Industrial Grade:Standard purity monomers for bulk coatings, adhesives, and plastics applications with basic inhibitor packages and moisture specifications. Chinese acrylic acid derivatives along the Yangtze River Delta and US Gulf Coast propylene-derivative complexes supply the majority of industrial grade volume.
- Laboratory Grade:Elevated purity with comprehensive analytical documentation for research and development applications. German fine chemical distributors and Japanese reagent houses control laboratory grade distribution channels.
- Commercial Grade:Mid-tier purity balancing cost and performance for general-purpose formulations. Indian domestic producers and Southeast Asian traders concentrate commercial grade supply.
- High Purity:Sub-ppm impurity specifications for optical polymers, medical devices, and electronics applications. Mitsubishi Chemical's captive methacrylate technology and BASF's Ludwigshafen complex anchor high-purity methyl methacrylate supply.
Industrial grade handles the majority of throughput; high purity is gaining share fastest on optical and medical device specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites European acrylic monomer flows, while the Houston Ship Channel anchors North American bulk liquid distribution. China's Yangtze River Delta petrochemical clusters and Japan's Kanto industrial belt complete the infrastructure backbone.
United States
Waterborne architectural coatings manufacturers along the US Gulf Coast absorb emulsion-grade butyl acrylate volumes. EPA Toxic Substances Control Act reporting requirements shape import documentation and purity specifications. Dow's integrated propylene-derivative complexes in Texas and Louisiana anchor domestic methyl methacrylate supply.
Germany
Automotive LED lighting specifications and architectural glazing standards pull high-purity methyl methacrylate through specialty polymer channels. REACH registration renewal obligations and EU Green Deal carbon border adjustments tighten cradle-to-gate emission documentation. BASF's Ludwigshafen complex and coatings R&D partnerships in Baden-Württemberg concentrate formulation-grade supply.
China
Domestic acrylic acid capacity expansions feed downstream derivative output for coatings and adhesives segments. MEE dual carbon enforcement constrains coal-based production routes, redirecting investment toward propane dehydrogenation feedstock integration. Yangtze River Delta clusters around Shanghai and Ningbo generate regional oversupply pressure on export pricing.
Japan
Optical-grade polymethyl methacrylate specifications for automotive and electronics applications command sub-ppm purity premiums. METI industrial standards and JIS certification protocols govern medical device and dental application grades. Kanto region specialty chemical houses and Nagoya-area polymer compounders concentrate high-value methyl methacrylate consumption.
India
Textile finishing operations in Surat and Tiruppur absorb significant butyl acrylate volumes for soft-hand acrylic emulsions. BIS quality mark requirements and PLI scheme incentives for domestic chemical manufacturing open formulation-grade monomer supply partnerships. Mumbai-Pune industrial corridor coatings formulators drive specification-grade procurement growth.
Acrylic Monomers Market Competitive Landscape
Listed leaders compete with private specialists across integrated propylene-derivative production and captive methacrylate technology platforms. The vendor base stratifies into three tiers: multinational chemical conglomerates with backward integration into feedstock, regional specialists with formulation partnership capabilities, and emerging Asian producers with cost-optimized commodity output. Capacity expansion along PDH routes and strategic R&D collaborations for optical-grade specifications represent the dominant competitive vectors reshaping positioning.
Within the integrated conglomerate tier, Mitsubishi Chemical and Dow exemplify divergent geographic anchoring strategies, while BASF occupies a position emphasizing formulation-centric partnership models. These three entities represent the archetype spectrum from captive technology leverage to supply chain integration to customer-embedded R&D collaboration.
| Leading Market Players |
|---|
| Mitsubishi Chemical |
| Evonik Industries |
| Dow |
| Sumitomo Chemical |
| LG Chem |
| Arkema |
| BASF |
| Nippon Shokubai |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
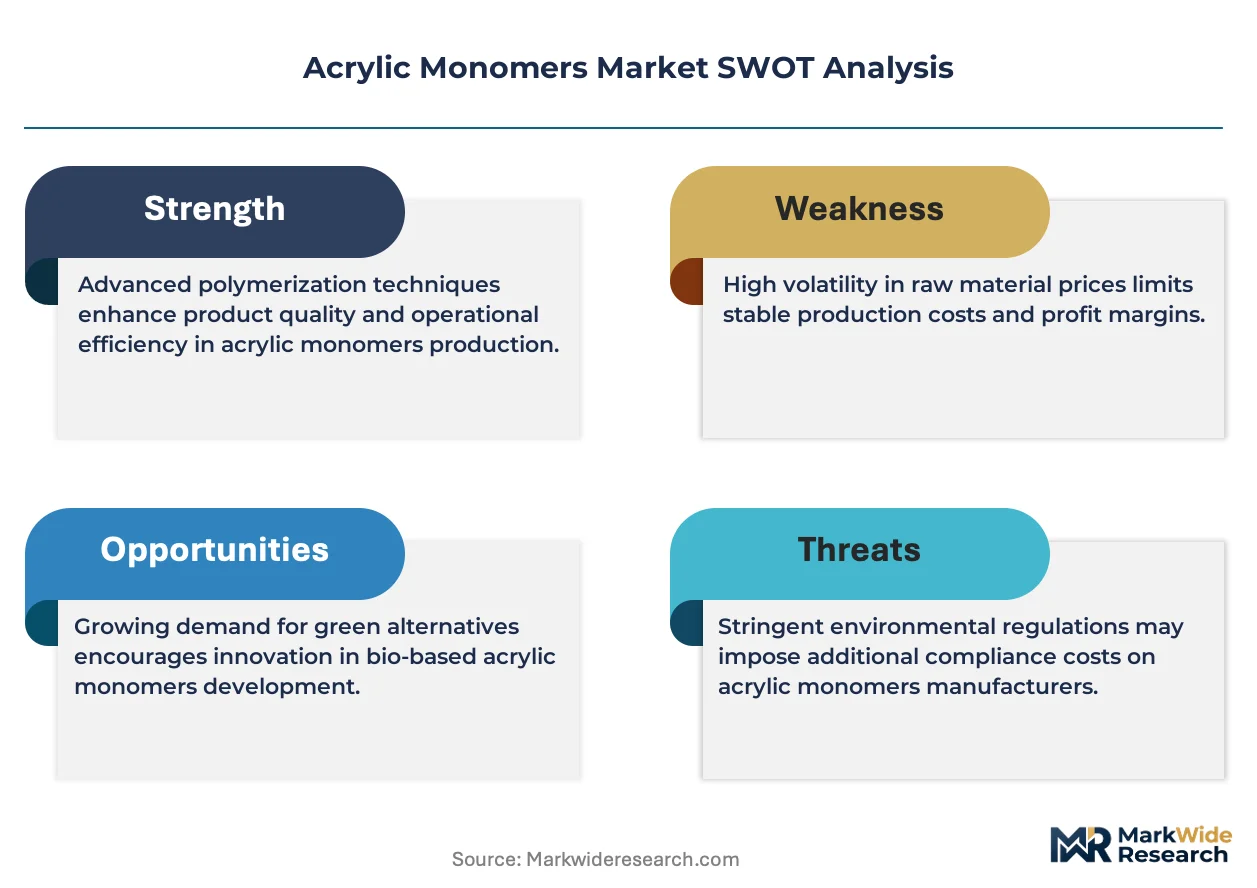
Propane dehydrogenation feedstock substitution for naphtha-cracking routes is simultaneously redrawing supply geography toward US Gulf Coast and Middle Eastern petrochemical complexes while compressing cost spreads that once anchored regional pricing premiums. This feedstock pivot fragments legacy pricing corridors as Chinese MEE dual carbon enforcement redirects investment away from coal-based acrylic acid production.
Pricing Analysis
Volume-discount tiering structures dominate acrylic monomer procurement, with spot-market transactions yielding to long-term offtake agreements among top-ten specialty coatings formulators. Price differentiation rests on purity certification grade and REACH registration documentation burden, with high-purity methyl methacrylate commanding substantial premiums over industrial-grade butyl acrylate. Pricing pressure stems from Yangtze River Delta capacity oversupply depressing export quotations. Coatings formulators exhibit highest price sensitivity, while optical-grade polymer compounders absorb premium pricing with limited elasticity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among European coatings manufacturers under EU Green Deal carbon border adjustment protocols, while Asian producers maintain strategic stockpiles of inhibitor-stabilized liquid monomers. Supply concentrates in China, the United States, and Germany, with feedstock dependencies spanning propylene derivatives, propane dehydrogenation output, and methanol-to-olefins streams. Single-source vulnerability runs through Rotterdam-Antwerp pipeline corridor chokepoints. Distribution feeds from integrated propylene-derivative complexes toward formulation-grade blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic monomers sit at an early-cycle expansion story as waterborne architectural coatings penetration accelerates under tightening EPA VOC emission limits and REACH solvent-phase restrictions.
For Market Incumbents: Shield margin structures through captive methacrylate technology investments and backward integration into PDH feedstock routes. Consolidate formulation partnerships with top-ten specialty coatings formulators to lock in long-term offtake volumes. Counter styrene-acrylic substitution threats by embedding monomer supply into automotive LED lighting R&D collaborations. For New Entrants and Emerging Players: Differentiate on bio-based acrylic acid certification through fermentation-derived 3-hydroxypropionic acid routes converging with catalytic dehydration platforms. Target India's specialty coatings segment where BIS quality mark requirements and PLI scheme incentives create formulation-grade supply partnership openings. Deploy blockchain-verified purity documentation to bypass traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated producers with feedstock-advantaged positions. Long-term viability over the next decade hinges on carbon accounting transparency extending to cradle-to-gate emission certifications. Monitor propane-propylene spread volatility as the primary inflection signal for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PDH Feedstock | Captive propane supply secures cost advantages as MEE dual carbon enforcement constrains coal-based routes. |
| High-Purity Grade Capacity Expansion | Optical-grade methyl methacrylate output captures automotive LED lighting specification premiums. |
| Long-Term Supply Agreement | Direct contracts with tier-one polymer compounders displace spot-market exposure in North American supply chains. |
| Green Manufacturing Transition | Fermentation-derived bio-based routes satisfy EU Green Deal carbon border adjustment documentation requirements. |
| Joint Venture with Coatings Formulator | R&D-embedded partnerships lock in specification-grade offtake through BASF-style Ludwigshafen collaboration models. |
Research Methodology
Operator-level perspectives from plant managers at integrated propylene-derivative complexes, procurement leads at downstream coatings OEMs, distribution channel partners, and technical R&D directors anchored the qualitative base. These primary insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness across feedstock cost spread scenarios, regulatory enforcement intensity variations, and substitution elasticity parameters. The analytical framework segmented by grade tier, end-use industry, packaging format, and regional production hub throughout the projection horizon. CAGRs derived from installed capacity utilization rates, demand elasticity coefficients, and price-volume equilibrium modeling. Key inputs included propylene-propane spread forecasts and waterborne coatings penetration curves.
Material uncertainties — feedstock route economics shifts, REACH-EPA regulatory divergence, and styrene-acrylic substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about MEE dual carbon enforcement continuity and EU Green Deal carbon border adjustment implementation. Revision becomes warranted when propane-propylene spread volatility crosses thresholds that destabilize PDH investment returns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Global Anti-Vibration Polymer Market