
 Global Substrate Market | 2026-2036
Global Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Substrate Market Foresight
Semiconductor device packaging is realigning substrate procurement patterns across consumer electronics makers and sensor systems integrators. Samsung Electro-Mechanics Co., Ltd. leverages its captive semiconductor ecosystem to dominate advanced packaging substrate supply. Ibiden Co., Ltd. anchors high-density interconnect production for logic chips through sustained manufacturing scale in Japan. Unimicron Technology Corp. competes aggressively on build-up substrate capacity for AI accelerator modules.
A substrate is a foundational material layer—composed of silicon, glass, ceramic, or organic compounds—that provides mechanical support, thermal management, and electrical interconnect pathways for deposited thin-film structures. Silicon substrates, typically polished to atomic-scale flatness below 0.5 nanometer RMS roughness, serve as the crystalline base for epitaxial semiconductor growth in logic and memory fabrication. Ceramic substrates command premium positioning in power electronics and RF applications where thermal conductivity exceeds 150 W/m·K, while glass substrates are displacing silicon in advanced panel-level packaging due to dimensional stability and cost structure advantages at larger form factors.
REACH substance restrictions and RoHS hazardous substance limits in Europe constrain halogenated flame retardants and heavy metal content in organic substrates, directly elevating compliance costs for circuit fabricators exporting into EU markets. China's SAMR enforces GB standards on substrate dimensional tolerances and MEE oversees dual carbon goals that pressure energy-intensive ceramic sintering operations. Japan's METI coordinates JIS standards for semiconductor material purity grades that govern access to automotive and medical device supply chains. Stakeholders must monitor regulatory divergence between EU chemical safety frameworks and Asia-Pacific industrial standards when siting substrate manufacturing or qualifying second-source suppliers.
Market Dynamics
Semiconductor device packaging is compressing substrate qualification cycles as AI accelerator modules force build-up substrate suppliers to compress layer counts while maintaining signal integrity thresholds.
Growth Catalysts
- Advanced packaging corridors:Taiwan's concentrated ecosystem of OSATs and foundries pulls high-density interconnect substrate capacity toward the island, creating localized supply advantages for logic chip packaging.
- Dual carbon mandates:China's MEE enforcement of energy intensity caps on ceramic sintering operations accelerates kiln electrification and process efficiency investments among substrate manufacturers serving power electronics.
- REACH substance restrictions:ECHA's tightening controls on halogenated flame retardants in organic substrates elevate compliance-tier pricing for EU-bound circuit fabricators, segmenting supplier qualification tiers.
Market Restraints
- Raw material concentration:High-purity alumina supply concentrates among Chinese refractory producers, exposing ceramic substrate fabricators to export quota volatility and freight cost spikes.
- Technical dimensional limits:Silicon substrates face fundamental area constraints below 450mm diameter, capping cost reduction potential for large-format panel-level packaging against glass alternatives.
- Regulatory divergence friction:JIS purity grades for automotive-grade substrates misalign with EU MDR traceability requirements, forcing dual-track certification investments for medical device suppliers.
Strategic Opportunities
- India's PLI scheme:The country's production-linked incentive framework for semiconductor packaging creates greenfield substrate qualification pathways for suppliers establishing captive capacity near Gujarat's Dholera cluster.
- Glass substrate convergence:Dimensional stability advantages above 600mm form factors position glass as the converging base for panel-level fan-out packaging, displacing silicon in high-volume memory module assembly.
- Direct procurement channels:AI accelerator designers are bypassing traditional distributor networks to negotiate direct build-up substrate contracts, compressing margin layers and accelerating specification feedback loops.
Industry Challenges
- Specialized lithography talent scarcity:Fine-line patterning below 8μm line/space requires process engineers with compound semiconductor experience, a skill set concentrated in Japan and Taiwan.
- Cleanroom capex intensity:Class 1000 or better fab environments for high-density interconnect substrates demand capital commitments exceeding standard PCB fabrication thresholds by an order of magnitude.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Substrate Market |
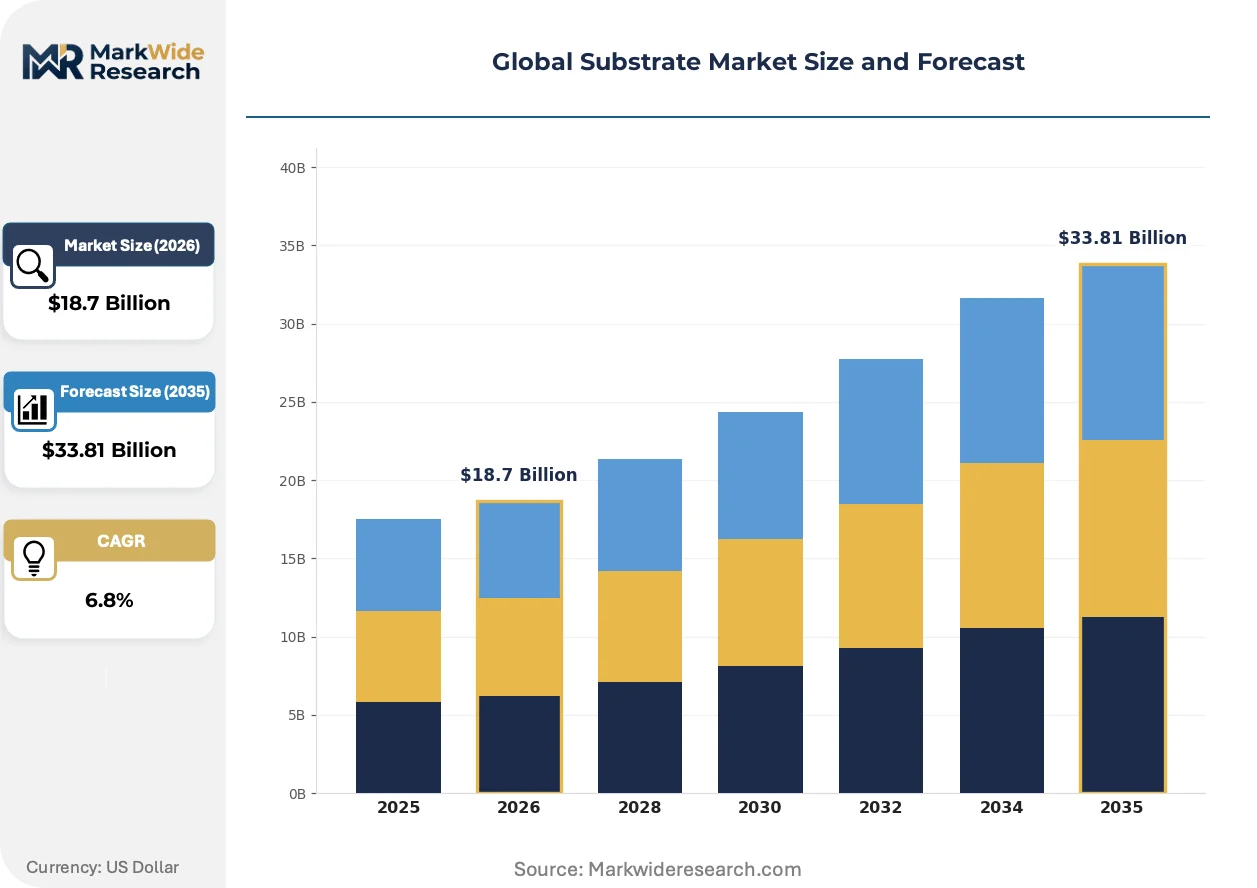
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Sapphire, Glass, Ceramic, Plastic, Quartz Technology: Photolithography, Chemical Vapor Deposition, Molecular Beam Epitaxy, Spin Coating, Sputtering, Atomic Layer Deposition Application: Semiconductor Devices, LED Lighting, Solar Panels, Sensors, MEMS Devices, Printed Circuit Boards End User: OEM Manufacturers, Electronic Component Producers, Consumer Electronics Makers, Solar Energy Providers, Sensor Systems Integrators, Circuit Fabricators |
| Companies Covered | Ibiden Co., Ltd., Unimicron Technology Corp., Samsung Electro-Mechanics Co., Ltd., AT&S AG, LG Innotek Co., Ltd., AGC Inc., Corning Incorporated, Sumitomo Electric Industries, Ltd., Schott AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Substrate Market Shifts & Advancements
Substrate technology is fragmenting across material classes as thermal, electrical, and mechanical requirements diverge across AI, automotive, and RF end-uses. Three forces are compressing traditional silicon-centric supply models.
Embedded die packaging is modularizing substrate architecture by integrating passive components and thin-film interconnects within the board stack rather than surface-mounting. Automotive radar module suppliers in Germany and Japan are adopting these configurations to compress z-height and improve thermal cycling reliability. The structural consequence is collapsing the boundary between substrate and system-in-package manufacturing, forcing OSATs to absorb former PCB fabricator capabilities.
REACH authorization requirements for SVHCs in flame-retardant chemistries are elevating material disclosure burdens across EU-bound substrate supply chains. ECHA's 2024 updates to the candidate list now capture specific brominated compounds used in high-Tg laminates, compelling laminate suppliers to reformulate or secure authorization. High-frequency RF substrate fabricators serving 5G infrastructure are most exposed, accelerating migration to phosphorus-nitrogen halogen-free systems.
Memory chip designers are consolidating substrate sourcing decisions at the wafer-fab level rather than delegating to downstream module assemblers. Samsung and SK Hynix now specify build-up substrate stack-ups directly with Ibiden and Unimicron, compressing the traditional three-tier procurement chain. This concentration is most visible in South Korea's Pyeongtaek and Icheon corridors, where captive packaging subsidiaries have absorbed former independent purchasing functions.
Global Substrate Market Segmentation
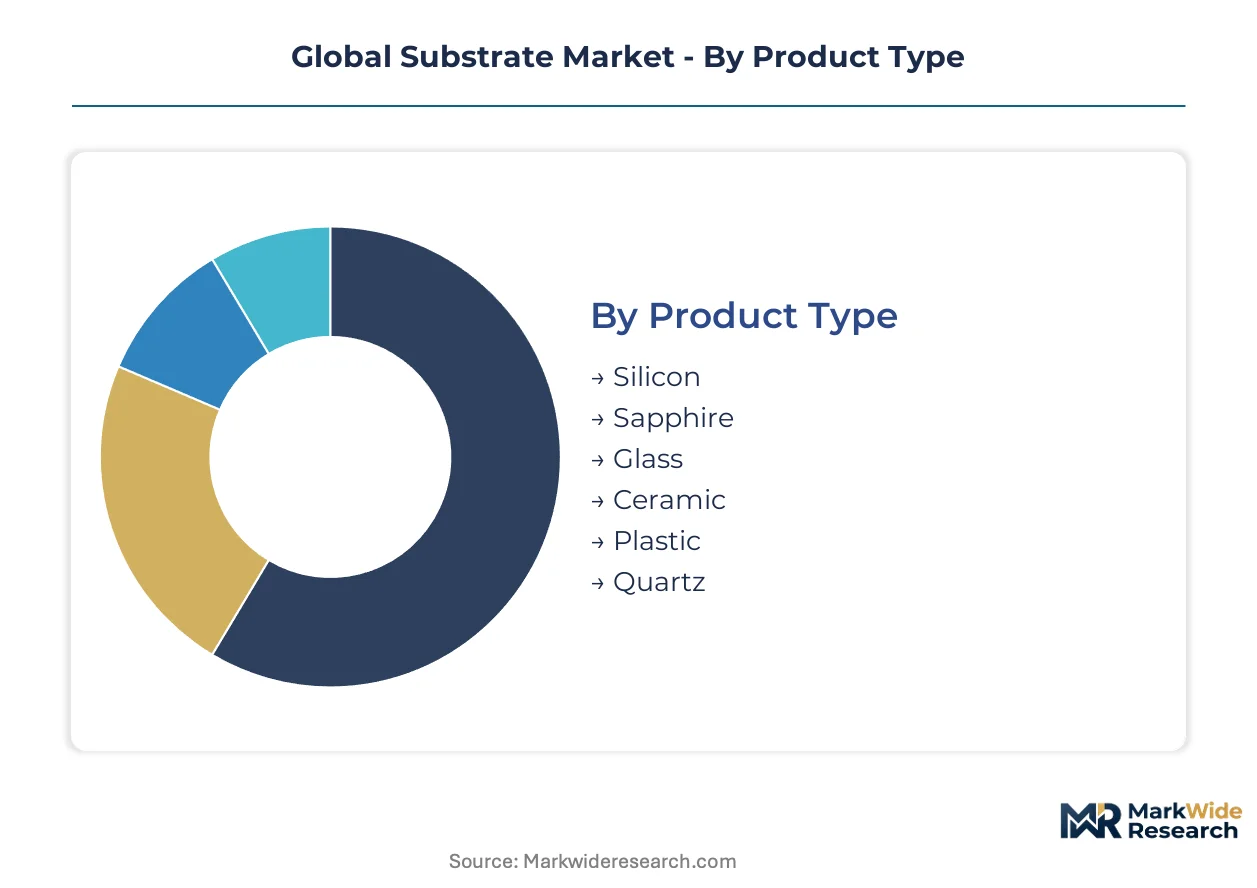
Substrate procurement decisions split across material physics, deposition precision, and end-use thermal requirements. Each segmentation axis carries distinct capital thresholds and qualification barriers that reshape supplier competitiveness.
Product Type:
Capital intensity peaks with silicon wafer polishing infrastructure and ceramic sintering kilns, while glass and plastic substrates demand lower upfront fab investment.
- Silicon:Polished to sub-0.5 nanometer RMS roughness, silicon substrates anchor epitaxial growth for logic and memory chips. Taiwan's foundry corridor pulls the majority of 300mm supply for advanced node production, though 450mm diameter limits cap cost reduction potential against panel alternatives.
- Ceramic:High-purity alumina and aluminum nitride formulations deliver thermal conductivity exceeding 150 W/m·K for power electronics. China's MEE energy intensity caps are forcing kiln electrification investments among suppliers serving automotive inverter modules.
- Glass:Dimensional stability above 600mm form factors positions glass for panel-level fan-out packaging. Samsung and SK Hynix are qualifying glass for high-volume memory module assembly.
- Sapphire:Single-crystal boules for LED epitaxy require specialized pulling furnaces. Demand concentrates with solid-state lighting manufacturers in East Asia.
- Plastic:Organic laminates serve cost-sensitive PCB applications. REACH flame-retardant restrictions are elevating reformulation costs for EU-bound supply.
- Quartz:Fused silica substrates enable UV lithography optics and RF applications requiring low thermal expansion. Japanese suppliers dominate high-purity feedstock.
Most installed capacity flows through silicon. Expansion is steepest in glass.
Technology:
Equipment amortization schedules vary dramatically—molecular beam epitaxy systems require decade-long utilization horizons, while spin coating scales with modest capital outlay.
- Photolithography:Patterning resolution below 8μm line/space demands stepper investments and cleanroom infrastructure. Taiwan and Japan concentrate the specialized process engineering talent for fine-line substrate fabrication.
- Chemical Vapor Deposition:CVD coats uniform thin films for dielectric and conductive layers across large substrate areas. Memory chip packaging corridors in South Korea are pulling capacity for build-up substrate manufacturing.
- Molecular Beam Epitaxy:Ultra-high vacuum systems deposit single-crystal compound semiconductor layers. LED and RF device makers specify MBE for wavelength precision.
- Atomic Layer Deposition:Self-limiting surface reactions enable angstrom-scale thickness control for high-aspect-ratio features. ALD is penetrating advanced packaging for conformal barrier layers.
- Sputtering:Physical vapor deposition deposits metal seed layers for subsequent electroplating. Tooling costs sit between CVD and MBE thresholds.
- Spin Coating:Photoresist and polymer deposition for lithography and planarization. Lowest capital barrier among thin-film technologies.
Photolithography claims the largest installed base. ALD is climbing the fastest.
Application:
Qualification cycles compress most severely for semiconductor packaging, while solar and lighting applications tolerate longer supplier validation timelines.
- Semiconductor Devices:Logic and memory packaging drive the most demanding substrate specifications for signal integrity and thermal cycling reliability. AI accelerator modules are forcing build-up substrate suppliers to compress layer counts.
- LED Lighting:Sapphire and silicon substrates for gallium nitride epitaxy serve solid-state illumination. Efficiency gains in automotive headlamps are sustaining sapphire demand despite display backlighting erosion.
- Sensors:MEMS and image sensor packaging require matched thermal expansion between substrate and die. Automotive radar suppliers in Germany are adopting embedded die configurations.
- Solar Panels:Crystalline silicon wafers dominate photovoltaic substrates. Polysilicon feedstock pricing volatility shapes procurement economics.
- MEMS Devices:Bulk micromachining and wafer-level packaging demand specialized substrate handling. Automotive pressure and inertial sensors anchor volume.
- Printed Circuit Boards:Organic laminates for system-level interconnect. Halogen-free material transitions are elevating laminate costs for EU-bound fabricators.
Semiconductor packaging commands the most capacity. Sensor applications are expanding most quickly.
End User:
Direct procurement bypassing distributor networks is concentrating among AI hardware designers, while solar and consumer electronics retain traditional channel structures.
- OEM Manufacturers:Automotive and industrial equipment makers specify substrates at the module design stage. JIS automotive purity grades govern supplier qualification.
- Electronic Component Producers:Passive component and connector manufacturers source ceramic and plastic substrates. BIS dimensional standards apply for India-bound supply.
- Consumer Electronics Makers:Smartphone and wearable brands delegate substrate sourcing to contract manufacturers. Cost pressure sustains plastic laminate dominance.
- Solar Energy Providers:Module assemblers procure silicon wafers through long-term polysilicon contracts. China's dual carbon goals are reshaping ingot manufacturing location decisions.
- Sensor Systems Integrators:Automotive and industrial automation suppliers are absorbing embedded die packaging capabilities. Germany's KBA type approval requirements constrain substrate changes post-certification.
- Circuit Fabricators:PCB manufacturers qualify laminate suppliers against REACH and RoHS substance restrictions. ECHA SVHC updates are forcing reformulation cycles.
OEM manufacturers represent the largest procurement volume. Sensor systems integrators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substrate fabrication migrates toward jurisdictions with lower energy costs and streamlined environmental permitting, creating regulatory arbitrage between mature economies with stringent chemical controls and emerging production zones offering fiscal incentives.
China
MIIT's GB standards on dimensional tolerances and SAMR enforcement of dual carbon goals pressure ceramic sintering operations toward kiln electrification. MEE energy intensity caps are accelerating process efficiency investments among suppliers serving power electronics. The Yangtze River Delta cluster around Shanghai concentrates high-density interconnect capacity for logic chip packaging.
Taiwan
Advanced packaging corridors pull substrate supply toward foundry-adjacent OSATs serving AI accelerator modules. The island's concentrated ecosystem of logic chip fabricators creates localized qualification advantages for build-up substrate suppliers. Hsinchu Science Park anchors the densest concentration of fine-line lithography talent outside Japan.
South Korea
Memory chip designers at Samsung and SK Hynix now specify substrate stack-ups directly with fabricators, compressing traditional procurement chains. Pyeongtaek and Icheon corridors host captive packaging subsidiaries that have absorbed former independent purchasing functions. METI-coordinated JIS standards govern automotive-grade material purity access.
Japan
METI coordinates JIS standards for semiconductor material purity grades that gate entry to automotive and medical device supply chains. Kyushu and Nagoya manufacturing zones retain specialized process engineering talent for compound semiconductor substrates. REACH-RoHS misalignment with EU MDR traceability requirements forces dual-track certification investments for exporters.
Germany
KBA type approval requirements constrain substrate changes post-certification for automotive radar module suppliers. ECHA's tightening SVHC controls on halogenated flame retardants elevate material disclosure burdens for EU-bound laminate fabricators. Bavaria's automotive electronics cluster is adopting embedded die configurations to compress z-height in sensor packaging.
Global Substrate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive semiconductor ecosystems commanding advanced packaging substrate supply while independent fabricators compete on build-up capacity for AI modules. The vendor base organizes around three archetypes: integrated electronics conglomerates with captive demand, pure-play substrate specialists with lithography scale, and materials science firms leveraging glass or ceramic formulations. Consolidation pressure is mounting as direct procurement channels bypass traditional distributor networks, and qualification cycles compress for high-density interconnect products.
Among Japan-based fabricators, Ibiden Co., Ltd. and Sumitomo Electric Industries, Ltd. occupy positions within the premium-tier substrate supply chain, while Samsung Electro-Mechanics Co., Ltd. exemplifies the integrated conglomerate archetype with captive semiconductor ecosystem advantages. Unimicron Technology Corp. represents the aggressive capacity-building specialist competing on build-up substrate scale for logic and memory packaging. These three anchors illustrate how geographic concentration of process engineering talent in East Asia reinforces competitive positioning across material classes.
| Leading Market Players |
|---|
| Ibiden Co., Ltd. |
| Unimicron Technology Corp. |
| Samsung Electro-Mechanics Co., Ltd. |
| AT&S AG |
| LG Innotek Co., Ltd. |
| AGC Inc. |
| Corning Incorporated |
| Sumitomo Electric Industries, Ltd. |
| Schott AG |
| Others |
Supply & Pricing Matrix
China's dual carbon goals enforced by MEE gate qualified supply for ceramic substrates and anchor premium-tier pricing access for compliant fabricators exporting into EU markets under REACH substance restrictions.
Pricing Analysis
Distributor margin compression distinguishes direct-to-OEM contracts from traditional channel sales, with AI accelerator designers bypassing intermediaries to negotiate build-up substrate specifications directly. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with automotive-grade JIS purity commanding substantial premiums over consumer electronics laminates. Cost compression in standard-tier organic substrates is intensifying because REACH flame-retardant reformulation elevates material disclosure burdens. Consumer electronics makers exhibit highest price sensitivity, while automotive OEMs tolerate premium positioning for thermal cycling reliability.
Supply Chain Analysis
Single-source vulnerability sits with high-purity alumina feedstock concentrated among Chinese refractory producers, exposing ceramic substrate fabricators to export quota volatility. Manufacturing capacity clusters in Taiwan, South Korea, and Japan, with Taiwan's Hsinchu Science Park anchoring fine-line lithography talent for advanced packaging. Raw material dependencies include high-purity alumina, borosilicate glass, and halogen-free laminate resins. Regulatory restriction risk manifests through ECHA SVHC updates and China's MEE energy intensity caps. Distribution runs through captive packaging subsidiaries at Samsung and SK Hynix, compressing traditional three-tier procurement chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where India's PLI scheme for semiconductor packaging offers fiscal incentives unmatched by China's escalating environmental compliance costs for ceramic sintering operations.
For Market Incumbents: Lock in captive demand relationships by absorbing embedded die packaging capabilities from former PCB fabricators, defending against direct procurement bypass by AI hardware designers. Expand kiln electrification investments ahead of MEE energy intensity enforcement to secure qualified supply status for EU-bound power electronics. Prioritize JIS automotive purity grade maintenance to gate medical device supply chain access. For New Entrants and Emerging Players: The price-point gap between premium ceramic substrates for automotive inverters and economy plastic laminates for consumer electronics creates entry space for mid-tier glass substrate specialists. Target India's Dholera cluster for greenfield qualification pathways under PLI incentives, where captive capacity near Gujarat's emerging packaging corridor bypasses established East Asian supply concentration. Pursue direct contracting relationships with sensor systems integrators adopting embedded die configurations. For Investors and Strategic Acquirers: Roll-up economics work for regional substrate specialists with lithography scale because qualification cycle compression for AI accelerators favors consolidated technical capabilities over fragmented fabricator networks. Long-term viability hinges on material science differentiation across glass, ceramic, and organic formulations rather than commodity silicon wafer polishing. Watch for inflection in Samsung and SK Hynix captive packaging subsidiary absorption rates as signal of procurement chain consolidation maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Investment | MEE energy intensity compliance secures qualified supplier status for EU-bound ceramic substrate exports. |
| Direct OEM Contracting | AI accelerator designers bypass distributor networks, compressing margin layers and accelerating specification feedback. |
| Glass Substrate Scale-Up | Samsung and SK Hynix qualification for 600mm panel-level fan-out packaging displaces silicon in memory modules. |
| Embedded Die Capability Absorption | OSATs integrate former PCB fabricator functions to serve automotive radar suppliers in Germany and Japan. |
| India PLI Facility Establishment | Greenfield substrate qualification near Gujarat's Dholera cluster captures fiscal incentives for semiconductor packaging. |
Research Methodology
Multiple input streams — executive interviews at substrate fabricators, procurement leads at AI hardware designers, and regulatory affairs specialists at laminate suppliers — were reconciled against customs data, SEC filings from listed packaging specialists, and ECHA substance restriction updates. Primary fieldwork captured qualification cycle compression dynamics and direct procurement channel emergence. Secondary validation drew from MIIT GB standards documentation, METI JIS coordination bulletins, and MEE dual carbon enforcement protocols. Bottom-up capacity modeling triangulated against top-down semiconductor packaging demand projections.
Data-stream reconciliation anchored analytical frameworks across material type, technology node, application thermal requirements, and end-user procurement structure throughout the forecast period. CAGRs derived from installed capacity expansion schedules, technology migration curves for glass displacement of silicon, and regulatory compliance cost trajectories. Industry-specific inputs included kiln electrification capital requirements, fine-line lithography talent availability indices, and REACH authorization timelines for halogenated flame retardants.
Caveats apply where ECHA SVHC list expansion, MEE energy intensity cap enforcement severity, or AI accelerator module demand volatility could materially shift the outlook. Forecasts embed assumptions regarding qualification cycle compression rates and captive packaging subsidiary absorption trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Global Specialty Oils Market