
 Anaerobic Adhesives Market | 2026-2036
Anaerobic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Anaerobic Adhesives Market Intelligence
The shift towards electronics and renewable energy equipment from traditional heavy machinery is broadening the application base for anaerobic adhesives. Henkel AG & Co. KGaA leverages its extensive portfolio to serve both legacy industrial and emerging electronics sectors. 3M differentiates with specialized formulations for high-performance applications in aerospace and automotive. ITW LLC & Co. KG sustains a strong position in the industrial maintenance and repair market through its established channel presence.
Anaerobic adhesives are single-component adhesives that cure in the absence of air and in the presence of metal ions. Their primary function is to lock and seal metal assemblies, such as threaded fasteners, preventing loosening from vibration and protecting against corrosion. Threadlockers represent the largest product type segment, driven by their ubiquitous use in mechanical assembly and maintenance. Gasketing adhesives are gaining share, offering a liquid alternative to pre-cut gaskets for creating more reliable seals in complex flange geometries.
Product formulations are governed by chemical safety standards, including the EU's REACH directive and the US EPA's Toxic Substances Control Act (TSCA). In China, compliance with GB standards for adhesive performance and environmental impact is mandatory for market access. The key strategic decision for manufacturers revolves around balancing performance attributes with an evolving global chemical regulatory landscape.
Market Dynamics
The central tension in the anaerobic adhesives market is the conflict between performance demands from advanced manufacturing sectors like electric vehicles and the increasing stringency of global chemical regulations, notably the EU's REACH directive, which restricts key raw materials.
Growth Catalysts
- Lightweighting Mandates:Automotive and aerospace industries are replacing mechanical fasteners with adhesives to join dissimilar lightweight materials like aluminum and composites, reducing vehicle weight and improving fuel efficiency.
- Renewable Energy Expansion:The rapid build-out of wind energy infrastructure creates substantial demand for threadlockers and retaining compounds for turbine assembly and long-term maintenance in harsh operating environments.
- Industrialization in Asia:China's continued dominance in manufacturing, coupled with mandatory GB standards, drives high-volume consumption of threadlockers and gasketing products in machinery and electronics assembly.
Market Restraints
- Substrate and Temperature Sensitivity:Anaerobic adhesives exhibit slower cure speeds on inactive metals and at low temperatures, sometimes requiring the use of primers, which adds complexity and cost to the assembly process.
- Regulatory Compliance Burden:Reformulating products to comply with evolving chemical restrictions under regulations like the EU's REACH and the US EPA's TSCA is a costly and time-consuming process for manufacturers.
- Threat from Mechanical Fastening:In applications requiring frequent disassembly or inspection, traditional mechanical fasteners like lock nuts and washers remain the preferred solution due to their simplicity and serviceability.
Strategic Opportunities
- Electric Vehicle Systems:Formulations designed for EV battery pack assembly, offering thermal conductivity and dielectric strength, represent a significant new application area with specialized performance requirements. *Dual-Cure Formulations: Hybrid adhesives that combine anaerobic curing with a secondary mechanism, such as UV light, enable rapid fixturing on a wider range of substrates, including plastics and glass.
- Industrial Growth in Southeast Asia:Expanding manufacturing operations in countries like Vietnam, Thailand, and Indonesia present an underpenetrated market for industrial maintenance, repair, and operations (MRO) adhesives.
Industry Challenges
- Navigating Global Regulations:Managing a product portfolio that complies with the divergent and constantly updated chemical inventories and safety standards of the EU, US, and China requires significant dedicated expertise.
- Raw Material Volatility:The supply of key monomers and specialty additives is concentrated among a few chemical producers, creating vulnerability to price fluctuations and supply chain disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaerobic Adhesives Market |
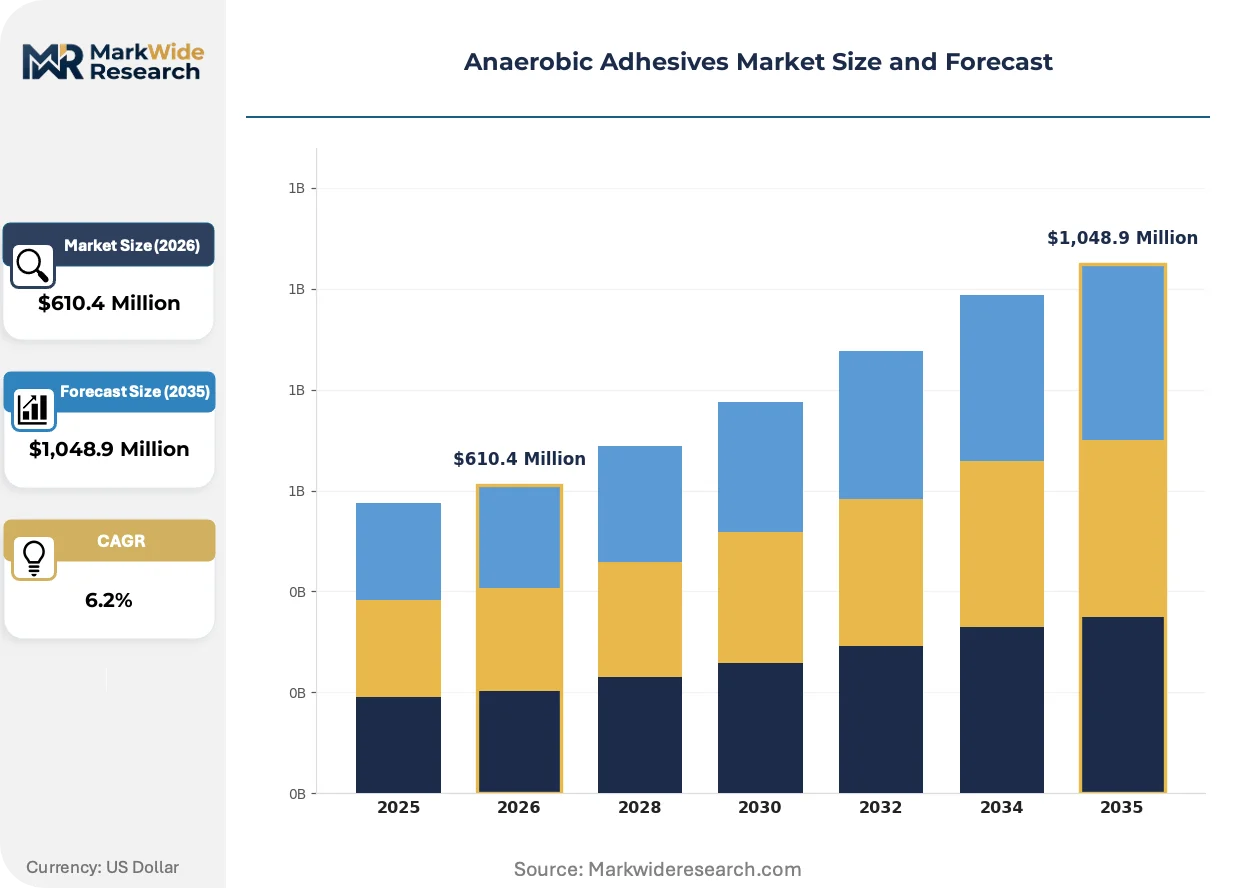
| Market Size in 2026 | $610.4 Million |
| Market Size in 2035 | $1,048.9 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Threadlockers, Retaining Compounds, Bearing Fillers, Gasketing Adhesives, Cure-in-Place Adhesives Technology: UV Cure, Two-Component, Heat Cure, Moisture Cure, Solvent-Free Application: Metal Bonding, Thread Sealing, Gasket Sealing, Surface Protection, Assembly Fixation End User: OEM Manufacturers, Aftermarket Service Providers, Assembly Plants, Maintenance Facilities |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller Company, Permabond LLC, ITW LLC & Co. KG, Parson Adhesives, Inc., WEICON GmbH & Co. KG, Loxeal S.r.l., ThreeBond Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaerobic Adhesives Market Strategic Shifts & Innovations
Product development is increasingly focused on addressing the dual objectives of enhanced performance for electronics and electric vehicles, alongside improved environmental, health, and safety profiles to meet stricter global chemical regulations.
Hybrid Adhesive Chemistries
Hybrid anaerobic-epoxy or anaerobic-acrylate adhesives combine multiple chemistries into a single product. These formulations are gaining adoption in structural bonding applications within heavy equipment and automotive assembly. This technology is rewriting the performance boundaries for single-component adhesives, offering enhanced impact resistance and temperature tolerance compared to traditional formulations.
Regulatory-Driven Reformulation
The EU's CLP regulation and its evolving hazard classifications are pushing manufacturers to develop "white label" or hazard-free formulations. This involves removing substances like specific methacrylates that trigger severe hazard warnings on product labels. The industrial maintenance segment is most impacted, with a clear user preference emerging for safer products that reduce workplace exposure risks.
System-Based Sales Models
A significant demand-side shift involves customers purchasing integrated systems rather than just adhesive products. This model bundles the chemical adhesive with proprietary dispensing equipment and on-site process consultation, disrupting the traditional component-based sales channel. This trend is most prominent in the highly automated automotive and electronics industries in Germany and South Korea.
Anaerobic Adhesives Market Segmentation
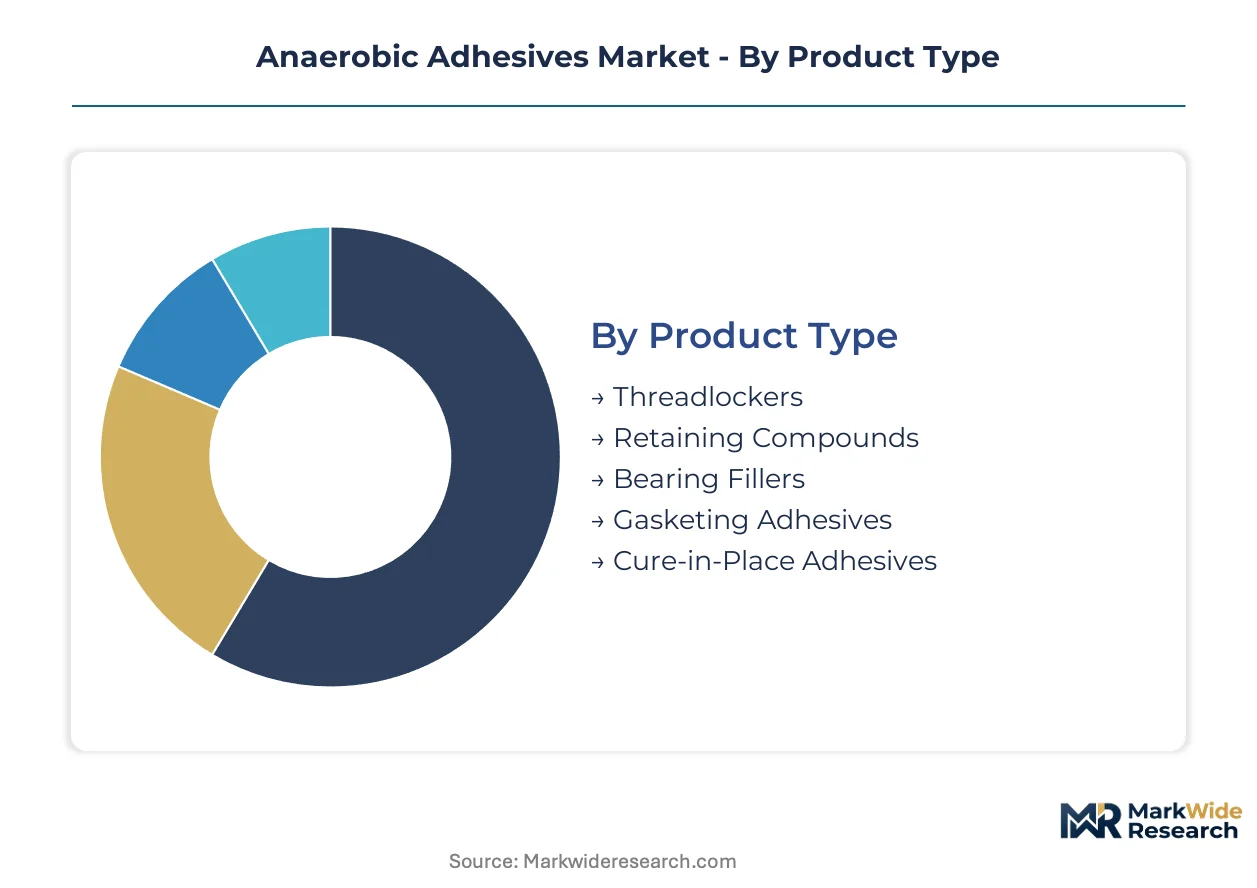
The anaerobic adhesives market diversifies across various product types, technologies, applications, and end-user segments. Understanding these distinct categories provides clarity on product development priorities and strategic market entry points. Each segment addresses specific industrial requirements, from high-performance bonding to general maintenance applications.
Product Type:
Product type segmentation highlights the primary functional specifications and chemical compositions defining anaerobic adhesive offerings.
- Threadlockers:These single-component, thixotropic liquids prevent fasteners from loosening due to vibration and shock, while also sealing against corrosion. Demand concentrates within China's manufacturing sector, driven by high-volume assembly of machinery and electronics.
- Retaining Compounds:These adhesives secure cylindrical components, such as bearings and bushings, onto shafts or into housings, eliminating the need for press fits.
- Bearing Fillers:Specialized compounds used to fill gaps and reinforce worn or damaged bearing housings, restoring precise fit and extending equipment life.
- Gasketing Adhesives:Formulated to create instant, leak-proof seals between rigid metal flange surfaces, these liquid sealants replace traditional pre-cut gaskets. Their adoption is gaining momentum in automotive OEM manufacturing for reliable seals in complex engine and transmission geometries.
- Cure-in-Place Adhesives:Formulations designed to cure directly within the assembly, often used for sealing complex or irregular joint configurations in industrial equipment.
Threadlockers lead on scale; gasketing adhesives lead on momentum.
Technology:
Technology segmentation reveals the diverse curing mechanisms tailored for specific application environments and substrate requirements.
- UV Cure:These formulations polymerize rapidly when exposed to ultraviolet light, enabling quick fixturing and high throughput in automated assembly lines. Demand expands within electronics manufacturing in South Korea, where speed and precision are critical for device assembly.
- Two-Component:These adhesives consist of two separate parts mixed just before application, offering controlled cure times and often enhanced structural properties. Their use is increasing in heavy equipment assembly for robust bonding of dissimilar materials.
- Heat Cure:These adhesives require elevated temperatures to initiate and complete their curing process, often used for durable bonds in high-temperature applications.
- Moisture Cure:Formulations that react with ambient moisture to cure, suitable for applications where anaerobic conditions are difficult to achieve or maintain.
- Solvent-Free:These environmentally preferred formulations contain no volatile organic compounds, aligning with stricter environmental regulations like the EU's REACH directive.
UV Cure technologies are expanding most quickly, driven by automation trends.
Application:
Application segmentation illustrates how different customer needs drive the specific functional deployment of anaerobic adhesives.
- Metal Bonding:Anaerobic adhesives bond metal components, offering high strength and resistance to chemicals and environmental factors in various assemblies.
- Thread Sealing:This application involves sealing threaded pipes and fittings to prevent leaks and protect against corrosion, essential in plumbing, hydraulics, and pneumatics. Demand is concentrated in industrial maintenance, repair, and operations (MRO) sectors across Southeast Asia.
- Gasket Sealing:This application replaces traditional gaskets by forming a durable, flexible seal between mating metal surfaces, improving reliability and reducing material waste. Automotive original equipment manufacturers increasingly utilize these for engine and transmission components.
- Surface Protection:These formulations create protective layers on metal surfaces, preventing corrosion and wear in harsh industrial environments.
- Assembly Fixation:This application secures components in place during manufacturing, providing temporary or permanent holding for subsequent processing steps.
Gasket sealing applications are experiencing the steepest expansion trajectory, reflecting evolving design requirements.
End User:
End-user segmentation reflects the varying volume requirements and operational contexts driving adhesive consumption across industries.
- OEM Manufacturers:Original equipment manufacturers integrate anaerobic adhesives into their production lines for new product assembly, demanding high performance and consistent supply. The automotive sector in Germany utilizes these for lightweight vehicle construction and electric vehicle battery packs.
- Aftermarket Service Providers:These providers use anaerobic adhesives for repair and maintenance of existing equipment, ensuring longevity and operational reliability.
- Assembly Plants:These facilities specialize in putting together components from various suppliers, relying on adhesives for efficient and reliable fastening. Electronics assembly plants in China are significant consumers for securing small, intricate parts.
- Maintenance Facilities:Industrial and commercial maintenance operations utilize these adhesives for routine repairs, preventing equipment downtime and extending asset life.
OEM manufacturers consistently represent the largest volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter chemical regulations in developed economies are prompting a strategic re-evaluation of manufacturing locations for anaerobic adhesives. This regulatory arbitrage influences where production concentrates, balancing compliance costs with market access. Manufacturers navigate divergent standards like the EU's REACH directive and China's GB standards.
China
China's manufacturing dominance drives substantial demand for threadlockers and gasketing products in machinery and electronics assembly. Mandatory GB standards for adhesive performance dictate market access and product formulation. Industrial clusters like the Yangtze River Delta exhibit high consumption for general manufacturing and automotive components.
Germany
Germany's advanced automotive sector utilizes anaerobic adhesives for lightweight vehicle construction and electric vehicle battery packs. The EU's REACH directive significantly influences material selection and product reformulation for manufacturers. Automotive hubs around Stuttgart and Munich concentrate demand for high-performance bonding solutions.
South Korea
South Korea's electronics manufacturing sector expands demand for UV-cure anaerobic adhesives, prioritizing speed and precision in automated assembly lines. National environmental standards guide the development of safer, solvent-free formulations. The Seoul Capital Area hosts a concentration of electronics assembly plants requiring specialized adhesive solutions.
United States
United States industries, including automotive and aerospace, increasingly adopt anaerobic adhesives for lightweighting and critical assembly. The US EPA's Toxic Substances Control Act (TSCA) mandates chemical safety compliance for all adhesive products. Manufacturing centers like Detroit and aerospace clusters in Seattle drive demand for specialized high-performance formulations.
Vietnam
Vietnam's expanding manufacturing base presents an underpenetrated market for industrial maintenance, repair, and operations adhesives. Government policies supporting foreign direct investment in manufacturing spur local demand for reliable assembly solutions. Industrial zones near Ho Chi Minh City are experiencing growth in MRO adhesive consumption.
Anaerobic Adhesives Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers adapt to evolving industry demands and stringent regulatory shifts. The market exhibits a tiered structure, with global chemical giants leading innovation and regional specialists serving niche applications. Strategic archetypes include integrated solution providers, specialized performance formulators for advanced sectors, and cost-efficient volume producers. R&D investment in regulatory-compliant and high-performance formulations represents a key competitive move, alongside strategic partnerships for system-based sales models.
Integrated solution providers include Henkel AG & Co. KGaA, a German-based chemical giant, which leverages its extensive portfolio to serve diverse industrial and electronics sectors. The US-headquartered 3M Company exemplifies a specialized performance formulator, differentiating with formulations for high-performance applications in aerospace and automotive. ITW LLC & Co. KG, another US-based entity, occupies a strong position in industrial maintenance and repair through its established channel presence. These companies anchor different segments of the market, reflecting varied strategic approaches to product development and market reach.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller Company |
| Permabond LLC |
| ITW LLC & Co. KG |
| Parson Adhesives, Inc. |
| WEICON GmbH & Co. KG |
| Loxeal S.r.l. |
| ThreeBond Holdings Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Captive supply of key monomers anchors manufacturer pricing power, especially for specialized formulations meeting stringent regulatory standards like the EU's REACH directive. This integration choice influences both raw material availability and the ability to command premium pricing for compliant, high-performance products.
Pricing Analysis
Direct-to-OEM discounts are significant for high-volume automotive manufacturers, reflecting long-term contract pricing agreements. The dominant pricing model is contract-based long-term offtake for OEMs, shifting to per-unit transactional for industrial maintenance, repair, and operations (MRO) segments. Performance attributes and certification level, such as GB standards compliance, drive price differentiation. Pricing pressure stems from regulatory-driven reformulation costs. OEM buyers are least price-sensitive for mission-critical applications like EV battery pack assembly, while MRO end-users are more sensitive.
Supply Chain Analysis
Stringent GB standards qualification gates market access in China, influencing the regional supply chain for threadlockers. Raw material dependencies include methacrylate monomers and specialty additives, often sourced from a concentrated base of chemical producers. Supply concentrates in Germany, China, and the United States, reflecting historical chemical manufacturing hubs. Commodity price volatility for key monomers represents a structural risk. Distribution runs through specialized industrial distributors and direct sales to large OEM customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anaerobic adhesives market presents a margin-expansion story, driven by a premium-tier shift towards high-performance formulations for electric vehicles and electronics. This enables manufacturers to capture higher value for specialized solutions.
For Market Incumbents: To counter emerging regulatory compliance costs, incumbents should deepen R&D investment in hazard-free formulations and pursue strategic partnerships for system-based sales models. Capacity additions in Southeast Asia can leverage lower operational costs and expanding industrialization. Invest in advanced testing capabilities to meet evolving performance standards for EV applications.
For New Entrants and Emerging Players: Launch via specialized industrial distributors targeting underpenetrated MRO segments in Southeast Asia. White-space targets include dual-cure formulations for hybrid bonding and solvent-free products for stringent environmental standards. Focus on localized channel presence and technical support to build market share. Offer agile customization for specific regional manufacturing needs.
For Investors and Strategic Acquirers: Roll-up economics work for specialized performance formulators because market fragmentation exists in niche applications requiring specific certifications. Long-term viability rests on continuous innovation for EV and electronics sectors. A signal to watch is the pace of regulatory harmonization across major economies, which could streamline market access. Target companies with strong intellectual property in hybrid chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Developing solvent-free formulations reduces workplace exposure risks and meets stricter EU REACH requirements. |
| Product Line Extension (Dual-Cure) | Hybrid anaerobic-acrylate adhesives address rapid fixturing needs in automated electronics assembly lines. |
| Geographic Expansion (Southeast Asia) | Expanding manufacturing operations into Vietnam captures growing MRO demand from industrialization. |
| Strategic Partnership (Dispensing Equipment) | Bundling adhesives with proprietary dispensing equipment enhances value proposition for automated automotive OEMs. |
| Certification Investment (GB Standards) | Achieving mandatory GB standards ensures market access and competitive positioning within China's manufacturing sector. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Stakeholders interviewed included R&D directors, procurement leads at OEMs, channel partners, and maintenance facility managers. Secondary data sources comprised customs trade data, chemical industry reports, and company SEC filings. Bottom-up market sizing was triangulated with top-down industry revenue estimates.
Segment-weighting across product type, application, technology, and end-user informed the analytical framework. Compound annual growth rates were derived from historical trends and projected demand drivers over the projection horizon. Industry-specific forecast inputs included automotive production volumes and renewable energy infrastructure build-out plans, alongside regulatory compliance timelines.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or radical shifts in raw material supply. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. A model refresh is warranted upon material change in global chemical regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Middle East and Africa Sealants Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market