
 Smart Speaker Market | 2026-2036
Smart Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Speaker Market Analysis
Market Context with Strategic Players
Chinese electronics manufacturing is shifting toward captive silicon and in-house acoustic engineering for smart speaker production. Amazon.com, Inc. leverages its Alexa ecosystem to control the North American channel and sustain recurring commerce revenue through voice transactions. Apple Inc. differentiates through Siri's deep hardware integration and privacy-centric positioning across its device portfolio. Xiaomi Corporation anchors volume in Asia through aggressive cost engineering and MIUI-based voice services.
Technical Definition and Structural Segments
Smart speakers are audio output devices incorporating microphone arrays, far-field voice recognition processors, and wireless connectivity modules to execute commands via natural language processing. They function primarily as human-machine interface hubs for media playback, home automation control, and cloud-based information retrieval. Standalone units dominate residential deployments, while smart display variants capture margin pools through visual commerce and video communication applications. Wi-Fi connectivity leads the connectivity dimension due to bandwidth requirements for streaming and cloud latency, though multi-room configurations are gaining traction in premium hospitality and educational institution installations.
Regulatory Frame and Forward-Looking Close
The EU AI Act and GDPR impose algorithmic transparency and data processing constraints on voice assistant providers operating in Europe, while the FCC governs radio frequency emissions and spectrum allocation for Wi-Fi and Bluetooth modules in the United States. China's SAMR enforces cybersecurity and data localization standards that shape product architecture for domestic and export-bound devices. Stakeholders must monitor divergence between EU algorithmic accountability rules and U.S. sector-specific privacy frameworks when architecting global voice platform strategies.
Market Dynamics
Smart speaker architecture is pivoting from cloud-dependent voice processing to edge-native inference, driven by the EU AI Act's data localization mandates and consumer latency expectations for home automation responsiveness.
Growth Catalysts
- EU AI Act algorithmic transparency requirements:European households are upgrading to compliant devices with on-device processing, accelerating hardware refresh cycles in Germany, France, and the Netherlands.
- Multi-room audio installations:Hospitality operators in premium hotel chains are deploying synchronized speaker arrays for guest room control and entertainment integration.
- Far-field microphone array advances:Beamforming DSP improvements enable reliable voice capture in noisy kitchen and living room environments, expanding addressable use cases.
Market Restraints
- MEMS microphone supply concentration:Taiwanese and Chinese sensor foundries control critical acoustic component supply, creating single-source vulnerability for non-integrated OEMs.
- GDPR voice data processing constraints:European operators face restricted cloud retention periods for biometric voiceprints, complicating personalization feature development.
- Smartphone voice assistant substitution:Handheld devices with always-listening capabilities reduce dedicated speaker necessity for basic command-and-control tasks.
Strategic Opportunities
- Healthcare ambient monitoring:Fall detection and medication reminder integrations position speakers for aging-in-place deployments in Japan and Germany.
- India PLI scheme electronics manufacturing:Component assembly incentives attract acoustic module production for cost-optimized export models.
- Matter protocol convergence:Thread and Wi-Fi interoperability standards reduce ecosystem lock-in, enabling multi-brand smart home configurations.
Industry Challenges
- Acoustic engineering talent scarcity:Far-field audio DSP and anechoic chamber calibration expertise concentrates in Shenzhen, Taipei, and Seoul, limiting R&D expansion elsewhere.
- Certification timeline compression:FCC Part 15 unintentional radiator testing and CE marking acoustic safety assessments extend product launch schedules by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Speaker Market |
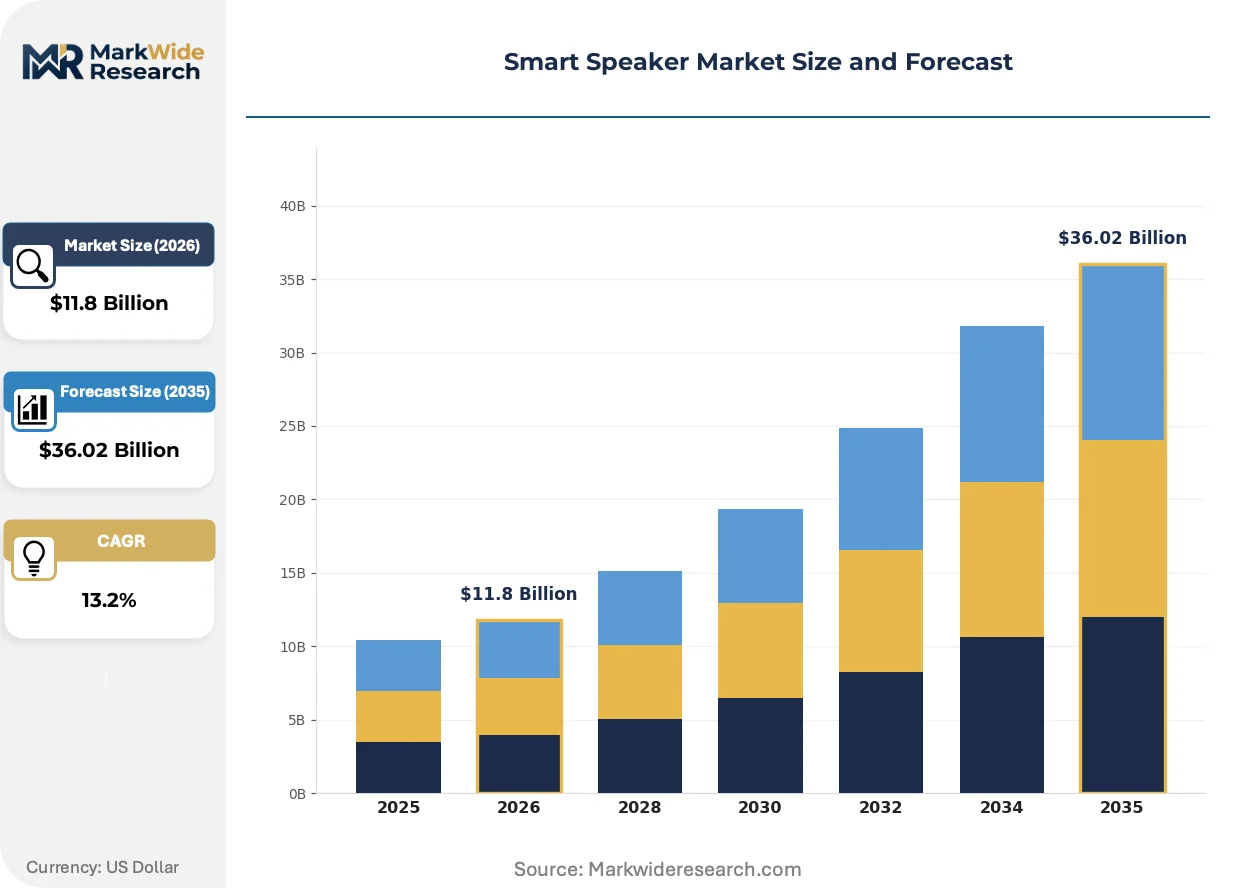
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $36.02 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Smart Display, Portable Connectivity: Wi-Fi, Bluetooth, Ethernet, Multi-Room End User: Residential, Small Businesses, Educational Institutions, Hospitality Voice Assistant: Google Assistant, Alexa, Siri, Bixby |
| Companies Covered | Amazon.com, Inc., Apple Inc., Google LLC, Sonos, Inc., Bose Corporation, Harman International, Samsung Electronics Co., Ltd., Xiaomi Corporation, Baidu, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Speaker Market Emerging Trajectories
Edge AI inference is redistributing computational load from cloud data centers to device silicon, compressing latency for voice commands while complicating hardware cost structures and thermal design requirements.
Neural processing units embedded in speaker SoCs are unifying wake-word detection, natural language understanding, and command execution on single-chip architectures. Premium residential installers in California and Texas are specifying NPU-enabled units for offline garage door and lighting control. This unification is compressing BOM costs for mid-tier products while fragmenting the competitive landscape between semiconductor IP licensors and integrated device manufacturers.
China's SAMR cybersecurity certification for network-connected audio devices mandates firmware signing and encrypted over-the-air update mechanisms. Domestic brands must re-engineer bootloaders and key management infrastructure to maintain market access. Export-bound products face parallel compliance tracks, with manufacturers maintaining separate hardware variants for mainland and international distribution.
Enterprise procurement of voice-enabled meeting room systems is displacing standalone conference phones in North American and European corporate real estate refreshes. Facilities managers specify Dante audio networking and Teams or Zoom native integration as standard requirements. This shift is most visible in London, New York, and Singapore financial services headquarters where hybrid work policies demand seamless remote participation infrastructure.
Smart Speaker Market Segmentation
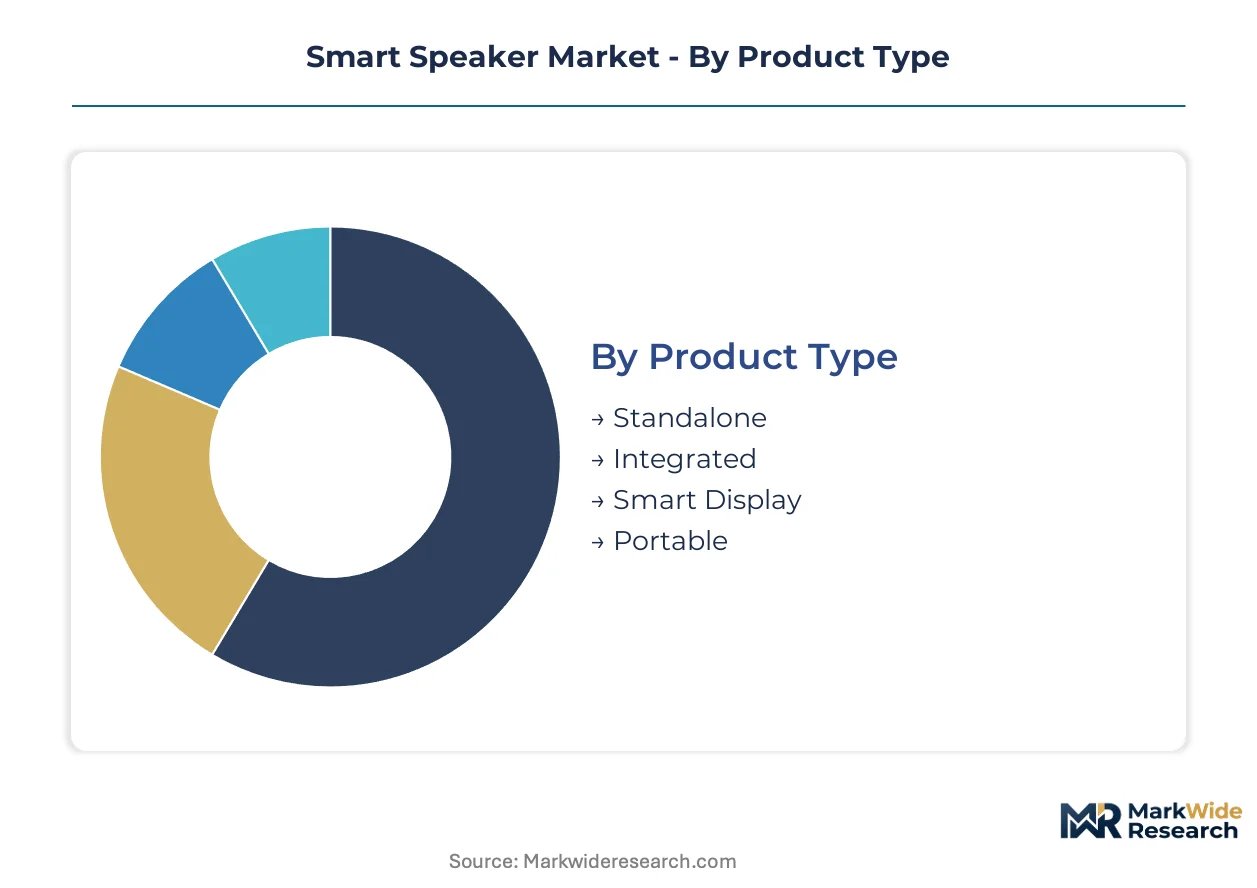
Smart speaker segmentation reveals how hardware architecture, connectivity protocols, and deployment contexts fragment both manufacturing requirements and go-to-market strategies. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Acoustic component sourcing concentrates around MEMS microphone arrays and DSP modules, with foundry capacity in Taiwan and Shenzhen dictating which form factors achieve cost viability at scale.
- Standalone:Dedicated audio output units with far-field microphone arrays and single-purpose voice processing hardware. German and Dutch households are upgrading to EU AI Act-compliant models with on-device inference, accelerating replacement cycles for cloud-dependent legacy devices.
- Smart Display:Voice-enabled units integrating LCD or OLED panels for visual commerce, video calling, and security camera feeds. Hospitality operators in California and Texas are specifying these for guest room control interfaces where touchscreen backup complements voice commands.
- Integrated:Speaker modules embedded within third-party appliances such as soundbars, televisions, and kitchen equipment. Automotive tier-1 suppliers in Stuttgart and Seoul are sourcing these for connected vehicle cabin experiences.
- Portable:Battery-powered units with Bluetooth fallback for outdoor and mobile use cases. Japanese camping equipment retailers are stocking ruggedized variants with extended IP ratings.
Today's leader: Standalone. Tomorrow's challenger: Smart Display.
Connectivity:
Protocol selection determines cloud dependency, latency performance, and interoperability scope across competing smart home ecosystems.
- Wi-Fi:Dominant protocol for residential deployments requiring high-bandwidth streaming and low-latency cloud voice processing. FCC Part 15 certification timelines in the United States extend launch schedules by four to six months for new hardware variants.
- Multi-Room:Synchronized array configurations using proprietary mesh or standards-based Thread networking. Premium hotel chains in London and New York are deploying these for seamless audio handoff across guest suites and common areas.
- Bluetooth:Secondary pairing protocol for direct smartphone streaming and initial device provisioning. Indian consumer electronics assemblers are optimizing BOM costs by specifying basic Bluetooth 5.2 modules over Wi-Fi for entry-tier products.
- Ethernet:Wired connectivity for enterprise meeting room installations requiring deterministic latency and IT security compliance. Financial services headquarters in Singapore mandate these for boardroom voice-enabled conferencing systems.
Wi-Fi commands volume. Multi-Room captures margin expansion.
End User:
Deployment context dictates acoustic engineering specifications, durability requirements, and software integration depth.
- Residential:Individual household installations prioritizing media playback and home automation control. Chinese brands compete aggressively on price and local language optimization for apartment dwellers in Shanghai and Beijing.
- Hospitality:Guest room and common area deployments requiring property management system integration and centralized fleet administration. Marriott and Hilton specifications in the United States are standardizing on voice-enabled climate and lighting control.
- Small Businesses:Retail and office environments using speakers for ambient music, scheduling, and customer service automation. Coffee shop chains in Seoul are piloting voice-activated ordering interfaces at counter locations.
- Educational Institutions:Classroom and campus deployments for administrative announcements and accessibility accommodations. University procurement offices in Germany are evaluating GDPR-compliant models with encrypted local processing.
Residential drives unit economics. Hospitality redefines integration requirements.
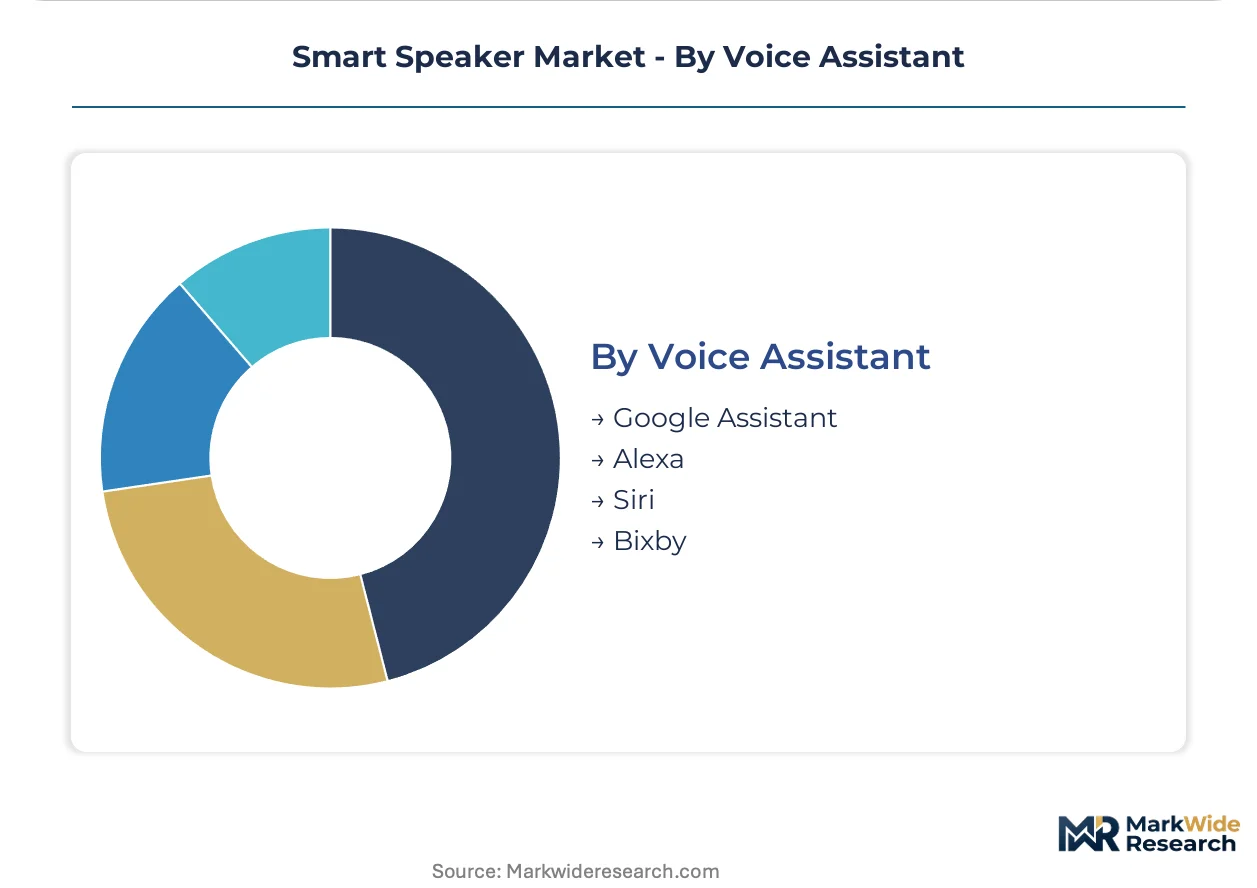
Voice Assistant:
Platform choice locks ecosystems, determines data governance exposure, and shapes semiconductor partnership requirements.
- Alexa:Amazon's cloud-native assistant with deep commerce integration and broad smart home device compatibility. North American channel control sustains recurring voice transaction revenue through frictionless purchasing workflows.
- Siri:Apple's privacy-centric platform with on-device processing and tight hardware-software integration. Premium residential installers in California specify these for clients prioritizing biometric data minimization.
- Google Assistant:Search-backed natural language understanding with multi-language proficiency and Android ecosystem reach. Indian OEMs are licensing this for cost-optimized export models targeting Southeast Asian markets.
- Bixby:Samsung's assistant with deep appliance integration and SmartThings ecosystem orchestration. Korean electronics conglomerates are embedding these across refrigerator, television, and speaker product lines for unified home control.
Alexa anchors commerce integration. Siri stakes privacy differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration tracks divergent compliance costs: Shenzhen and Taipei producers face lower algorithmic transparency burdens than EU-bound competitors, while India's PLI scheme attracts acoustic module assembly from cost-sensitive brands seeking tariff arbitrage.
United States
FCC Part 15 certification timelines extend hardware launch schedules by four to six months for Wi-Fi and Bluetooth modules. Premium residential installers in California and Texas specify NPU-enabled units for offline home automation control. Amazon's Alexa ecosystem sustains recurring commerce revenue through voice transaction workflows across North American households.
Germany
EU AI Act mandates are accelerating hardware refresh cycles as households upgrade to on-device inference models. GDPR voice data processing constraints complicate personalization feature development for cloud-dependent legacy devices. Berlin and Munich procurement offices evaluate encrypted local processing for educational institution deployments.
China
SAMR cybersecurity certification mandates firmware signing and encrypted over-the-air updates for network-connected audio devices. Domestic brands in Shanghai and Beijing compete aggressively on price and local language optimization for apartment dwellers. Export-bound products maintain separate hardware variants for mainland and international distribution.
India
PLI scheme electronics manufacturing incentives attract acoustic module production for cost-optimized export models. Bangalore and Delhi-NCR assemblers optimize BOM costs by specifying basic Bluetooth 5.2 modules over Wi-Fi for entry-tier products. Google Assistant licensing penetrates cost-optimized export models targeting Southeast Asian markets.
Japan
METI standards shape connected device interoperability requirements for aging-in-place healthcare ambient monitoring deployments. Tokyo and Osaka retailers stock ruggedized portable variants with extended IP ratings for camping equipment segments. Fall detection and medication reminder integrations position speakers for elderly care applications.
Smart Speaker Market Vendor Landscape
Shenzhen and Taipei producers anchor one tier; Cupertino and Seattle specialists hold premium positioning through ecosystem lock-in. The vendor base stratifies across three tiers: semiconductor-integrated OEMs with captive silicon, acoustic engineering specialists with anechoic chamber calibration expertise, and contract assemblers serving price-optimized regional markets. Two dominant competitive moves are reshaping positioning: backward integration into MEMS microphone foundry capacity and strategic licensing of voice assistant IP for white-label penetration.
Within the ecosystem-integrated tier, Amazon.com, Inc. and Apple Inc. exemplify divergent strategic anchors. Amazon represents commerce-centric platform control with Alexa's North American channel dominance and frictionless voice transaction infrastructure. Apple occupies privacy-centric positioning through Siri's on-device processing architecture and hardware-software integration across its device portfolio. Xiaomi Corporation sits within the volume-driven Asia-Pacific tier, leveraging aggressive cost engineering and MIUI-based voice services for apartment dwellers in Shanghai and Beijing.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Google LLC |
| Sonos, Inc. |
| Bose Corporation |
| Harman International |
| Samsung Electronics Co., Ltd. |
| Xiaomi Corporation |
| Baidu, Inc. |
| Others |
Supply Flow & Price Mechanics
EU AI Act compliance mandates for on-device voice processing are forcing hardware refresh cycles across German and Dutch residential procurement, compelling suppliers to reconfigure silicon sourcing and acoustic engineering workflows while compressing margin structures for cloud-dependent legacy architectures.
Pricing Analysis
Distributor margins for smart speaker hardware typically absorb 15-20 points before retail markup, with direct-to-OEM volume discounts compressing channel economics for white-label entrants. Pricing stratifies across premium NPU-enabled units with edge inference capability, standard Wi-Fi tethered models, and economy Bluetooth-only variants for price-sensitive Indian and Southeast Asian markets. Cost compression in entry-tier segments is intensifying due to aggressive domestic competition in Chinese e-commerce channels. Hospitality and enterprise buyers exhibit lowest price sensitivity, prioritizing fleet management integration and IT security compliance over per-unit acquisition cost.
Supply Chain Analysis
Freight cost volatility for containerized electronics from Shenzhen and Taipei to European distribution hubs has prompted regional assembly migration toward India's PLI-subsidized facilities in Bangalore and Delhi-NCR. MEMS microphone arrays, far-field DSP modules, and NPU-enabled SoCs draw from Taiwanese foundry capacity, Chinese packaging houses, and Korean memory suppliers. Single-source vulnerability concentrates in acoustic sensor fabrication, where two Taiwanese foundries control critical beamforming component output. Distribution runs through Amazon and Alibaba e-commerce platforms for residential volume, with specialized AV integrators handling enterprise meeting room deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart speaker market functions as a stable compounder anchored by persistent residential voice interface penetration and regulatory-forced hardware refresh cycles in European jurisdictions.
For Market Incumbents: Anchor ecosystem lock-in through backward integration into MEMS microphone foundry capacity and exclusive NPU silicon partnerships with Taiwanese semiconductor houses. Defend against smartphone voice assistant substitution by deepening hospitality and healthcare vertical integration where handheld devices prove operationally impractical. Prioritize CE marking and FCC Part 15 certification pipeline investment to compress launch timelines against agile Chinese competitors.
For New Entrants and Emerging Players: Capture white-label opportunity in India's PLI-subsidized manufacturing corridor for cost-optimized export models targeting Southeast Asian and Middle Eastern price-sensitive markets. Penetrate the educational institution segment in Germany and the Netherlands where GDPR-compliant encrypted local processing specifications create procurement barriers for cloud-native incumbents. Deploy Google Assistant licensing partnerships to bypass proprietary voice platform development costs.
For Investors and Strategic Acquirers: Asymmetric upside sits with acoustic engineering specialists possessing anechoic chamber calibration expertise and far-field DSP intellectual property in Shenzhen, Taipei, and Seoul clusters. Long-term viability hinges on edge AI inference capability and Matter protocol interoperability certification. Monitor EU AI Act enforcement intensity and SAMR cybersecurity certification timeline compression as inflection indicators for hardware refresh cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Development | NPU integration reduces cloud latency for EU AI Act-compliant on-device voice processing. |
| Matter Protocol Certification | Thread and Wi-Fi interoperability reduces ecosystem lock-in for multi-brand smart home configurations. |
| Healthcare Ambient Monitoring Integration | Fall detection and medication reminder features penetrate Japan and Germany aging-in-place markets. |
| PLI Scheme Manufacturing Migration | Indian assembly incentives attract acoustic module production for cost-optimized export models. |
| Enterprise Meeting Room System Deployment | Dante audio networking and Teams native integration displace standalone conference phones in financial services headquarters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smart speaker platform engineers, hospitality procurement directors, acoustic module suppliers, and semiconductor IP licensors with secondary validation against FCC certification databases, EU AI Act implementation guidance, SAMR cybersecurity bulletins, and customs trade data for MEMS microphone and DSP module flows. Bottom-up unit shipment modeling and top-down consumer electronics spending allocation were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through verified shipment volumes and installed base estimates across standalone, smart display, integrated, and portable product types, with connectivity protocol splits and voice assistant platform shares modeled separately. CAGRs were derived from segment-level growth trajectory analysis incorporating hardware refresh cycle timing, regulatory compliance deadline clustering, and regional adoption curve positioning. Forecast inputs included foundry capacity expansion announcements for far-field audio DSP silicon and Matter protocol certification pipeline visibility.
EU AI Act enforcement variance, SAMR cybersecurity timeline compression, and MEMS foundry supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory implementation cadence and component supply continuity. A model refresh is warranted upon material change in edge AI silicon cost curves or Matter protocol adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
Headset Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
Ereader Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
4K Television Market
Consumer Electronics
Pool Speakers Market