
 Turbo Mills Market | 2026-2036
Turbo Mills Market Size, Share, and Industry Trends Forecast 2026-2036
Turbo Mills Market Insights
Asset-light leasing and project finance arrangements for industrial grinding equipment is fragmenting competitive dynamics in the turbo mills space. Hosokawa Alpine AG leverages its vertical integration into precision classifier systems to sustain premium positioning across European chemical processing installations. Pallmann Maschinenfabrik GmbH anchors its competitiveness through deep specialization in polymer and biomass grinding applications. Netzsch Group competes via technology leadership in wet grinding circuits for minerals processing.
Turbo mills are high-speed impact grinding machines employing rotating turbine blades to achieve particle size reduction, typically operating at tip speeds exceeding 100 m/s and generating fine powders in the 10-500 micron range. The equipment serves primary industrial purposes in comminution, deagglomeration, and homogenization of brittle and semi-brittle materials across continuous processing lines. Horizontal turbo mill configurations dominate installed base volumes in mining and cement applications where throughput maximization drives equipment selection. Dry turbo mill systems are gaining fastest adoption in biomass and agricultural processing segments as operators eliminate water handling costs and downstream drying stages. Multi-stage turbo mill architectures concentrate margin pools in specialty chemical applications requiring precise particle size distribution control.
EPA emissions standards under the Clean Air Act shape turbo mill demand in US coal grinding and mineral processing by mandating particulate capture systems. OSHA combustible dust regulations enforce explosion protection requirements on dry turbo mill installations handling biomass and fine coal. REACH and ATEX directives in Europe govern material contact surfaces and ignition source management in chemical processing deployments. Stakeholders must monitor evolving carbon border adjustment mechanisms and their implications for energy-intensive grinding operations in export-oriented manufacturing jurisdictions.
Market Dynamics
The turbo mills market is undergoing structural recalibration as dry grinding configurations displace refrigerant-cooled systems under tightening environmental compliance regimes, forcing capital redeployment toward heat-resistant alloy engineering and closed-loop dust containment architectures.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is compelling cement and mineral processors across Germany, Poland, and Italy to retrofit existing wet-cooled installations with ambient-air-cooled turbo mill variants.
- Biomass pelletization:Agricultural residue-to-energy projects in Brazil and Southeast Asia are absorbing dry turbo mill capacity for straw and husk comminution, eliminating downstream drying capital.
- Copper concentrate throughput:Chilean and Australian mining operations are expanding horizontal turbo mill trains to process lower-grade ore bodies at elevated tonnage rates without secondary crushing circuits.
Market Restraints
- Tungsten carbide supply concentration:Grinding element fabrication depends on Chinese and Russian carbide feedstock, exposing European and North American mill builders to export restriction risk and price volatility.
- ATEX compliance overhead:Explosion protection certification for biomass and coal grinding applications adds twelve-to-eighteen-month lead times and substantial engineering cost to dry system deployments.
- High-pressure grinding roll substitution:HPGR technology is capturing share in iron ore and diamond liberation circuits where energy efficiency trumps particle fineness requirements.
Strategic Opportunities
- Indonesia nickel processing:Laterite ore beneficiation projects present greenfield demand for multi-stage turbo mill configurations capable of handling high-moisture feed without thermal preprocessing.
- EU Green Deal carbon border adjustments:Energy-intensive grinding operations in export-oriented manufacturing jurisdictions face compliance premiums that favor efficient turbo mill retrofits over legacy ball mill infrastructure.
- Digital twin integration:Convergence of computational fluid dynamics modeling with real-time vibration sensing is enabling predictive maintenance contracts that unbundle hardware sales from lifecycle service revenue.
Industry Challenges
- Rotordynamics specialization scarcity:Design engineers capable of optimizing high-speed turbine balance for 150 m/s tip speeds are concentrated among a handful of German and Japanese equipment heritage firms.
- Legacy DCS integration:Brownfield chemical plants running 1990s-era distributed control systems require costly protocol bridges to interface with modern turbo mill variable frequency drives and safety instrumented systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbo Mills Market |
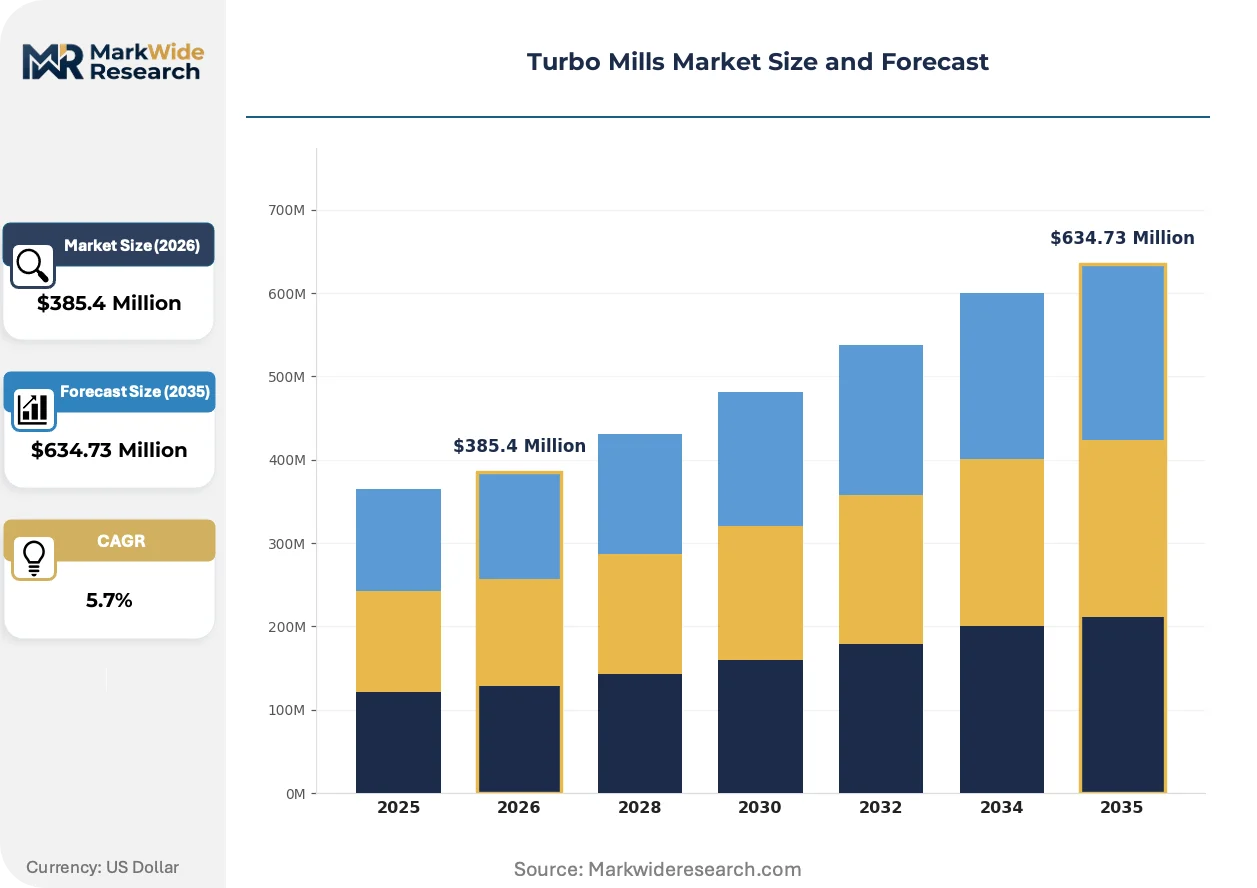
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vertical Turbo Mill, Horizontal Turbo Mill, Dry Turbo Mill, Wet Turbo Mill, Multi-stage Turbo Mill Material Processed: Cement Clinker, Minerals, Coal, Fertilizer, Biomass Application: Mining, Chemical Processing, Agricultural, Construction, Energy Production End User: Mining Companies, Chemical Manufacturers, Agricultural Firms, Construction Contractors, Energy Utilities |
| Companies Covered | Hosokawa Alpine AG, Pallmann Maschinenfabrik GmbH, Fritsch GmbH, Retsch GmbH, Netzsch Group, IKA-Werke GmbH & Co. KG, WAB Group, Powder Tech, Inc., Nara Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbo Mills Market Trends and Innovations
Equipment virtualization and predictive analytics are compressing the traditional separation between mechanical grinding hardware and process control software, enabling remote optimization of particle size distribution in continuous mineral and chemical processing lines.
Computational fluid dynamics coupled with discrete element modeling is virtualizing turbo mill chamber design iteration, allowing manufacturers to validate airflow patterns and impact kinematics before physical prototyping. Mining engineering firms in Australia and Canada are adopting these virtual commissioning workflows to reduce field trial duration. This virtualization is compressing product development cycles and lowering the capital barrier for specialized mill configurations serving niche ore bodies.
REACH authorization requirements for chromium-containing grinding media are forcing European chemical processors toward ceramic and silicon nitride alternatives, reshaping supplier qualification protocols and material traceability documentation. The industrial consequence extends to turbo mill liner and blade metallurgy, where cobalt-free hardfacing alloys are gaining preference despite higher unit cost. Specialty chemical installations in the Netherlands and Belgium are most affected, with operators accelerating media inventory turnover to preempt regulatory non-compliance.
After-sales service unbundling is displacing traditional lump-sum capital sales in North American mineral processing, with operators preferring throughput-guaranteed performance contracts tied to grinding circuit availability metrics. Engineering-procurement-construction firms are intermediating these arrangements, assuming operational risk in exchange for long-term service exclusivity. The Powder River Basin coal grinding segment exhibits the most pronounced shift, where mine operators defer capital ownership to preserve balance sheet flexibility under carbon transition uncertainty.
Turbo Mills Market Segmentation
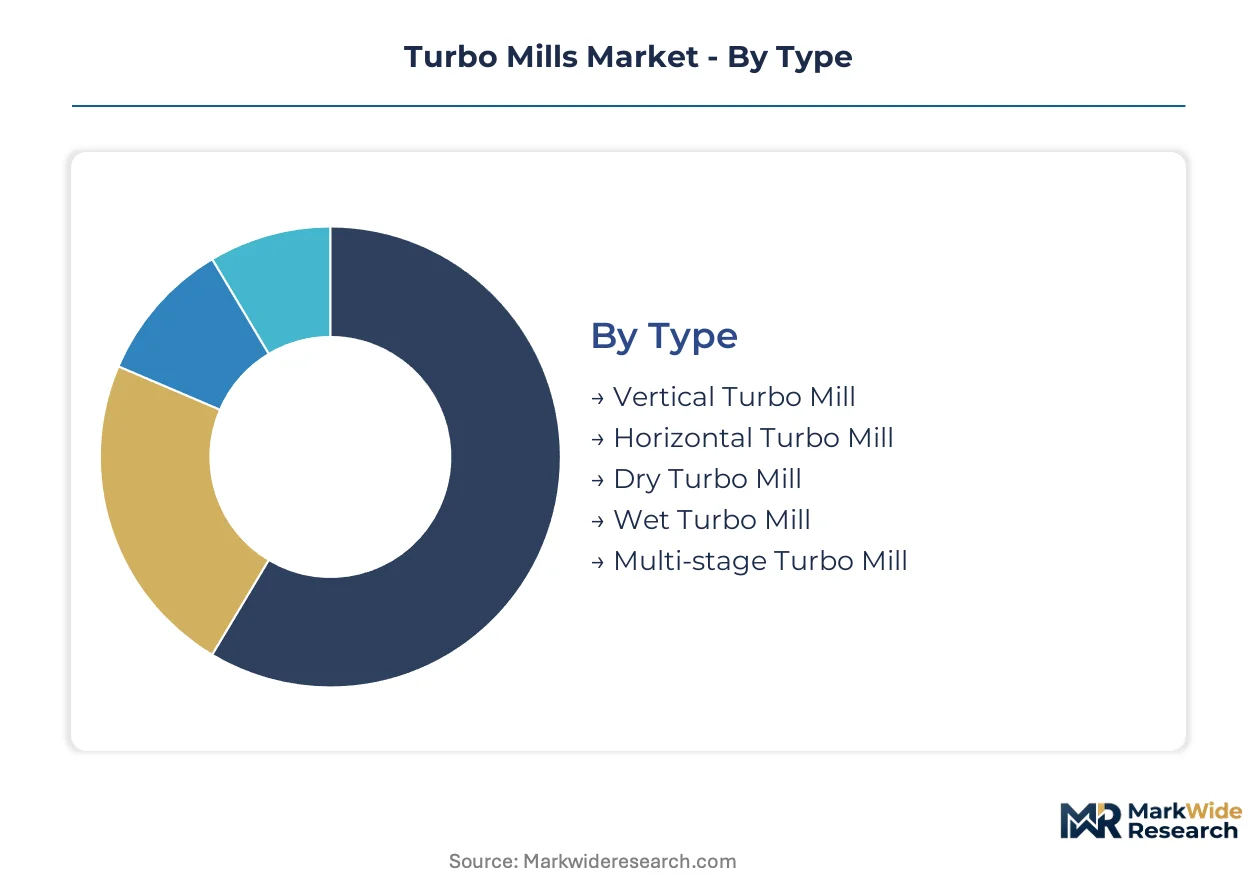
Turbo mill configurations diverge sharply across material hardness, moisture content, and throughput requirements. Equipment selection hinges on whether operators prioritize energy efficiency, particle fineness, or regulatory compliance for explosive dust environments.
Type:
Cost tier separates basic single-stage units from premium multi-chamber systems with integrated classification.
- Vertical Turbo Mill:Gravity-fed material entry reduces floor space requirements in retrofit installations. Cement plants in Poland and Germany favor these configurations for clinker grinding under EU F-Gas retrofit budgets.
- Horizontal Turbo Mill:Axial feed orientation maximizes throughput for continuous mineral processing trains. Australian and Chilean copper operations deploy these for lower-grade ore comminution at elevated tonnage rates.
- Dry Turbo Mill:Ambient-air cooling eliminates refrigerant-dependent thermal management systems. REACH compliance pressures are accelerating replacement of wet-cooled legacy units across European chemical processing.
- Wet Turbo Mill:Slurry-based operation maintains temperature control for heat-sensitive pharmaceutical intermediates. Installed base is contracting as F-Gas phaseout timelines approach.
- Multi-stage Turbo Mill:Sequential grinding chambers with inter-stage classification deliver tight particle size distribution control. Specialty chemical applications in Belgium and the Netherlands absorb premium pricing for cobalt-free hardfacing variants.
Horizontal configurations hold installed capacity. Multi-stage systems are rotating up the share rankings.
Material Processed:
Application severity determines liner metallurgy, with abrasive silica content dictating tungsten carbide versus ceramic grinding element selection.
- Cement Clinker:High silica and alumina content demands chromium-free hardfacing alloys under REACH authorization timelines. Chinese state-backed infrastructure projects concentrate demand for 200-tonne-per-hour units.
- Minerals:Variable hardness from copper porphyry to iron ore magnetite requires adjustable tip speed control. Canadian and Australian engineering firms are virtualizing chamber design through CFD-DEM modeling before field deployment.
- Coal:Combustible dust characteristics trigger ATEX and OSHA compliance overhead. Powder River Basin operators are shifting toward performance-based service contracts to defer capital ownership.
- Fertilizer:Hygroscopic ammonium phosphate compounds necessitate corrosion-resistant contact surfaces. Brazilian agricultural processing corridors show rising interest in dry configurations to eliminate downstream drying stages.
- Biomass:Fibrous agricultural residues strain conventional cutting geometries. Southeast Asian rice husk-to-energy projects are absorbing purpose-built rotor designs with extended blade spacing.
Cement clinker dominates current installed base. Biomass processing is climbing the fastest as renewable energy mandates tighten.
Application:
Customer technical sophistication varies from standardized mining procurement to specialized chemical process engineering.
- Mining:Bulk material handling scale favors horizontal configurations with mechanical reliability guarantees. Engineering-procurement-construction firms intermediate risk-sharing arrangements for greenfield copper concentrate projects.
- Chemical Processing:Batch-to-continuous conversion trends demand precise particle size distribution control. Dutch and Belgian operators face accelerated media inventory turnover under REACH chromium restrictions.
- Agricultural:Seasonal utilization patterns favor leasing structures over capital purchase. Brazilian straw pelletization projects are eliminating water handling costs through dry system adoption.
- Construction:Aggregates and supplementary cementitious materials processing requires robust construction for abrasive feedstocks. Infrastructure stimulus programs in China concentrate demand for high-throughput installations.
- Energy Production:Biomass cofiring and coal grinding applications face carbon transition uncertainty. US operators defer capital commitment through throughput-guaranteed performance contracts.
Mining retains the largest equipment population. Energy production applications are gaining share fastest under renewable portfolio standards.
End User:
Procurement authority sits differently across integrated multinationals, project developers, and utility operators.
- Mining Companies:Centralized technical standards departments specify equipment for global asset portfolios. BHP and Rio Tinto are expanding turbo mill trains for lower-grade ore bodies without secondary crushing circuits.
- Chemical Manufacturers:Process safety management systems govern equipment qualification protocols. European specialty chemical firms are qualifying cobalt-free hardfacing suppliers ahead of regulatory deadlines.
- Agricultural Firms:Cooperatives and independent processors prioritize capital efficiency over technical sophistication. Indonesian palm oil residue projects present greenfield demand for high-moisture feed handling.
- Construction Contractors:Project-based procurement limits lifecycle service attachment rates. Chinese state-owned construction enterprises drive volume through infrastructure megaprojects.
- Energy Utilities:Regulated rate base treatment influences capital versus operating lease decisions. US independent power producers face carbon border adjustment exposure for energy-intensive grinding operations.
Mining companies command the deepest installed base. Energy utilities are rotating up the share rankings as biomass cofiring expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision-engineering clusters while Chinese state-backed infrastructure procurement compresses margins through volume aggregation. Equipment specification divergence between EU F-Gas compliance mandates and developing-market cost optimization is widening regional product-mix asymmetries.
Germany
EU F-Gas Regulation retrofit cycles and REACH authorization timelines drive premium demand for cobalt-free hardfacing alloys and dry-cooled configurations. The country's national chemical regulator enforces accelerated media inventory turnover for chromium-containing grinding elements. Industrial equipment fabricators in Baden-Württemberg and North Rhine-Westphalia anchor European supply chains for precision classifier-integrated turbo mill systems.
China
State-backed infrastructure megaprojects concentrate demand for 200-tonne-per-hour cement clinker grinding units. The Ministry of Ecology and Environment enforces dual carbon goals that favor energy-efficient retrofits over legacy ball mill infrastructure. Equipment procurement clusters in the Yangtze River Delta and Shandong Peninsula where construction material producers scale high-throughput installations.
Australia
Lower-grade copper porphyry ore bodies at BHP and Rio Tinto operations expand horizontal turbo mill train deployments without secondary crushing circuits. The Therapeutic Goods Administration and state-level mining regulators enforce particulate capture standards under Clean Air Act parallels. Engineering firms in Perth and Brisbane adopt CFD-DEM virtual commissioning to compress field trial duration for greenfield mineral processing projects.
United States
Powder River Basin coal grinding operators defer capital ownership through throughput-guaranteed performance contracts under carbon transition uncertainty. EPA emissions standards under the Clean Air Act mandate particulate capture systems for dry grinding installations. Independent power producers in Wyoming and Montana face exposure to emerging carbon border adjustment mechanisms for energy-intensive operations.
Brazil
Agricultural residue-to-energy projects in São Paulo and Minas Gerais absorb dry turbo mill capacity for straw and husk comminution, eliminating downstream drying capital. The national health regulator ANVISA governs equipment qualification for fertilizer processing applications. Biomass pelletization corridors in the Center-West region scale purpose-built rotor designs with extended blade spacing for fibrous feed handling.
Turbo Mills Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in grinding element and precision classifier supply. Market structure consolidates around heritage German and Japanese equipment houses with captive rotordynamics engineering capability, while mid-tier fabricators compete on delivery speed for standardized mining configurations. Strategic archetypes separate vertically integrated precision specialists, regional scale players, and technology licensors. Dominant competitive moves include backward integration into hardfacing alloy supply and predictive maintenance service unbundling.
Within the precision-specialist tier, Hosokawa Alpine AG and Pallmann Maschinenfabrik GmbH exemplify German heritage engineering houses with multi-decade classifier system integration. Netzsch Group occupies a position representing wet grinding circuit technology leadership for minerals processing applications. These three anchors demonstrate how geographic clustering in southern German industrial regions correlates with sustained premium positioning across European chemical processing and global mining procurement channels.
| Leading Market Players |
|---|
| Hosokawa Alpine AG |
| Pallmann Maschinenfabrik GmbH |
| Fritsch GmbH |
| Retsch GmbH |
| Netzsch Group |
| IKA-Werke GmbH & Co. KG |
| WAB Group |
| Powder Tech, Inc. |
| Nara Machinery Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's precision-engineering clusters concentrate captive rotordynamics capability, translating upstream supply scarcity into sustained premium pricing power for multi-stage turbo mill configurations serving European chemical processing.
Pricing Analysis
The customization-premium spread separates standard horizontal units from configured-to-order multi-stage systems with integrated classification. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in standard mining configurations is intensifying because Chinese state-backed infrastructure procurement aggregates volume and squeezes margins. Agricultural cooperatives in Brazil exhibit highest price sensitivity, while specialty chemical manufacturers in Belgium and the Netherlands accept premium positioning for REACH-compliant cobalt-free hardfacing variants.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for tungsten carbide grinding element feedstock. Manufacturing draws from German precision-engineering heritage firms, Chinese state-owned construction equipment fabricators, and Japanese rotordynamics specialists. Raw material dependencies center on tungsten carbide, chromium-free hardfacing alloys, and ceramic grinding media. Single-source vulnerability concentrates in high-speed turbine balancing equipment. Distribution runs through engineering-procurement-construction firms intermediating risk-sharing arrangements for mining projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mining company centralized technical standards departments and Chinese state-owned construction enterprises, fragmenting procurement authority and compressing margins for standardized equipment tiers.
For Market Incumbents: Insulate premium positioning by deepening backward integration into cobalt-free hardfacing alloy supply and deploying predictive maintenance service contracts that unbundle hardware from lifecycle revenue. High-pressure grinding roll substitution in iron ore circuits threatens horizontal turbo mill share. Certification investment ahead of REACH authorization timelines secures chemical processing loyalty in the Netherlands and Belgium.
For New Entrants and Emerging Players: Indonesian nickel laterite beneficiation corridors present underpenetrated greenfield demand for high-moisture feed handling configurations. Brazilian agricultural residue-to-energy projects offer second white-space target for purpose-built rotor designs with extended blade spacing. A leasing-first go-to-market model aligns with seasonal utilization patterns and capital-constrained cooperative buyers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-premium play because tightening EU F-Gas and REACH timelines create durable demand for dry-cooled, cobalt-free configurations that heritage engineering houses are positioned to capture. Target acquisition archetype: German or Japanese precision-specialist firms with captive classifier integration and rotordynamics engineering depth. The signal to watch is carbon border adjustment mechanism implementation pace for energy-intensive grinding operations in export-oriented manufacturing jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardfacing Alloy Supply | Cobalt-free alloy captive production secures REACH compliance positioning for European chemical processing. |
| Predictive Maintenance Service Unbundling | Throughput-guaranteed contracts shift revenue from capital sales to recurring availability metrics in mining. |
| CFD-DEM Virtual Commissioning Capability | Computational fluid dynamics modeling compresses field trial duration for Australian greenfield mineral projects. |
| Indonesia Nickel Processing Market Entry | Laterite ore beneficiation demand for high-moisture feed handling escapes saturated copper concentrate segments. |
| Dry System Configuration Portfolio Expansion | Ambient-air cooling eliminates F-Gas refrigerant exposure under EU phasedown timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across plant engineers at BHP and Rio Tinto installations, procurement leads at European specialty chemical manufacturers, aftermarket service heads at German equipment fabricators, and EPC contractors intermediating mining project risk. Secondary validation drew from EU F-Gas Regulation filings, ECHA REACH authorization databases, SEC 10-K equipment disclosures, and Australian state-level mining regulator particulate capture standards. Bottom-up equipment shipment tallies and top-down end-use demand modeling were triangulated against operating capacity utilization rates.
Calibration against historical replacement cycles and retrofit spending patterns anchored volume projections across the analysis window. Segmentation dimensions modeled include equipment configuration type, material processed severity, end-user procurement authority, and regional regulatory compliance tier. CAGRs were derived from fitted growth curves against disclosed capital expenditure pipelines. Industry-specific forecast inputs incorporated copper concentrate throughput expansion plans and EU Green Deal carbon border adjustment mechanism exposure assessments.
Macroeconomic conditions sit as an overlay; deviation in industrial commodity prices, infrastructure stimulus execution, or refrigerant phaseout acceleration would shift the trajectory. Forecasts reflect documented assumptions regarding F-Gas retrofit timelines and mining grade decline rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Computing Devices Market
Others
Global Bio-Based Chemicals Market
Others
Surgical Simulation Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Space Cables Market
Others
Europe Postal Services Market
Others
Deep Sea Mining Market
Others
Mexico 3D Printing Construction Market
Others
Military Wearable Market
Others
Molybdenum-99 Market
Others
Global Fertility Tracking Apps Market
Others
TWS Micro-Battery Market
Others
US Automotive LED Lighting Market
Others
Bicycle Panniers Market
Others
Europe Virtual Reality Gaming Market
Others
Document Camera Market