
 Global Computer Graphics Market | 2026-2036
Global Computer Graphics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer Graphics Market Foresight
ISO/IEC 25010 software quality certification is bifurcating the competitive landscape between enterprise-grade and consumer-oriented vendors. NVIDIA Corporation leverages its CUDA ecosystem to dominate datacenter rendering workloads. Adobe Inc. sustains creative workflow integration across film and design verticals. Autodesk, Inc. anchors its position through deep CAD and BIM software penetration among engineering customers.
Computer graphics encompasses hardware and software systems that generate, manipulate, and display visual content through pixel-based raster operations or mathematically defined vector primitives, typically operating at refresh rates exceeding 60 Hz for interactive applications and supporting color depths of 8-bit to 32-bit per channel for professional output. Its primary purpose spans entertainment production, industrial design validation, and scientific data interpretation. Ray tracing technology commands premium pricing in film animation pipelines where photorealistic light simulation justifies extended render times. Shader programming expertise concentrates margin pools among game developers seeking proprietary visual differentiation. Rasterization retains volume leadership in real-time applications where frame latency constraints dominate hardware selection.
FDA scrutiny of medical visualization software elevates compliance costs for scientific visualization providers serving healthcare research laboratories. The EU AI Act imposes transparency obligations on automated content generation tools deployed by European film studios and simulation providers. China's MIIT enforces GB standards for domestic graphics hardware procurement in government and state-enterprise CAD design contracts. Stakeholders must weigh regulatory fragmentation against the efficiency gains of unified product architectures spanning multiple compliance jurisdictions.
Market Dynamics
Real-time ray tracing hardware commoditization is compressing rendering pipeline architectures across film, gaming, and industrial visualization segments. This shift forces vendors to differentiate through software ecosystems rather than silicon performance alone.
Growth Catalysts
- EU AI Act transparency mandates:Automated content generation tools deployed in European film studios face disclosure requirements. Compliance spending concentrates among simulation providers retrofitting provenance tracking.
- China's industrial design software maturation:Domestic CAD ecosystems in Shenzhen and Shanghai reduce import dependency for state-enterprise procurement. GB standards enforcement accelerates local vendor qualification.
- Shader programming talent scarcity:Game developers in Austin, Tokyo, and Stockholm bid aggressively for proprietary visual differentiation expertise. Labor costs inflate for real-time graphics specialists.
Market Restraints
- High-bandwidth memory supply concentration:GDDR6X and HBM3 sourcing clusters among Korean and Taiwanese foundries. Geopolitical friction elevates inventory risk for datacenter GPU vendors.
- FDA 510(k) pathway complexity:Medical visualization software for surgical planning faces extended validation timelines. Scientific visualization providers serving healthcare research absorb elevated compliance overhead.
- Rasterization performance ceiling:Frame latency constraints below 16 milliseconds limit photorealistic ambition in interactive applications. Hardware thermal budgets constrain mobile and embedded deployments.
Strategic Opportunities
- Neural rendering convergence:Machine learning inference pipelines merge with traditional graphics APIs. Film studios in Vancouver and London pilot generative texture synthesis for background asset creation.
- India PLI scheme for electronics manufacturing:Graphics hardware assembly incentives attract contract manufacturers to Tamil Nadu and Karnataka. Component localization reduces landed cost for Asia-Pacific distribution.
- Cloud-native workstation displacement:Browser-based rendering eliminates client-side GPU requirements. Architecture and engineering firms in Germany and Netherlands trial subscription visualization workflows.
Industry Challenges
- ISO/IEC 25010 certification timelines:Enterprise software quality validation extends product release cycles by 8-14 months. Consumer-oriented vendors struggle to bridge the compliance gap.
- Legacy OpenGL codebase entrenchment:Industrial automation and defense systems resist Vulkan or DirectX 12 migration. Maintenance contracts perpetuate deprecated API expertise scarcity.
- Cross-platform shader compilation fragmentation:Metal, DirectX, and Vulkan dialects multiply QA surface area. Engine developers absorb porting costs without commensurate pricing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer Graphics Market |
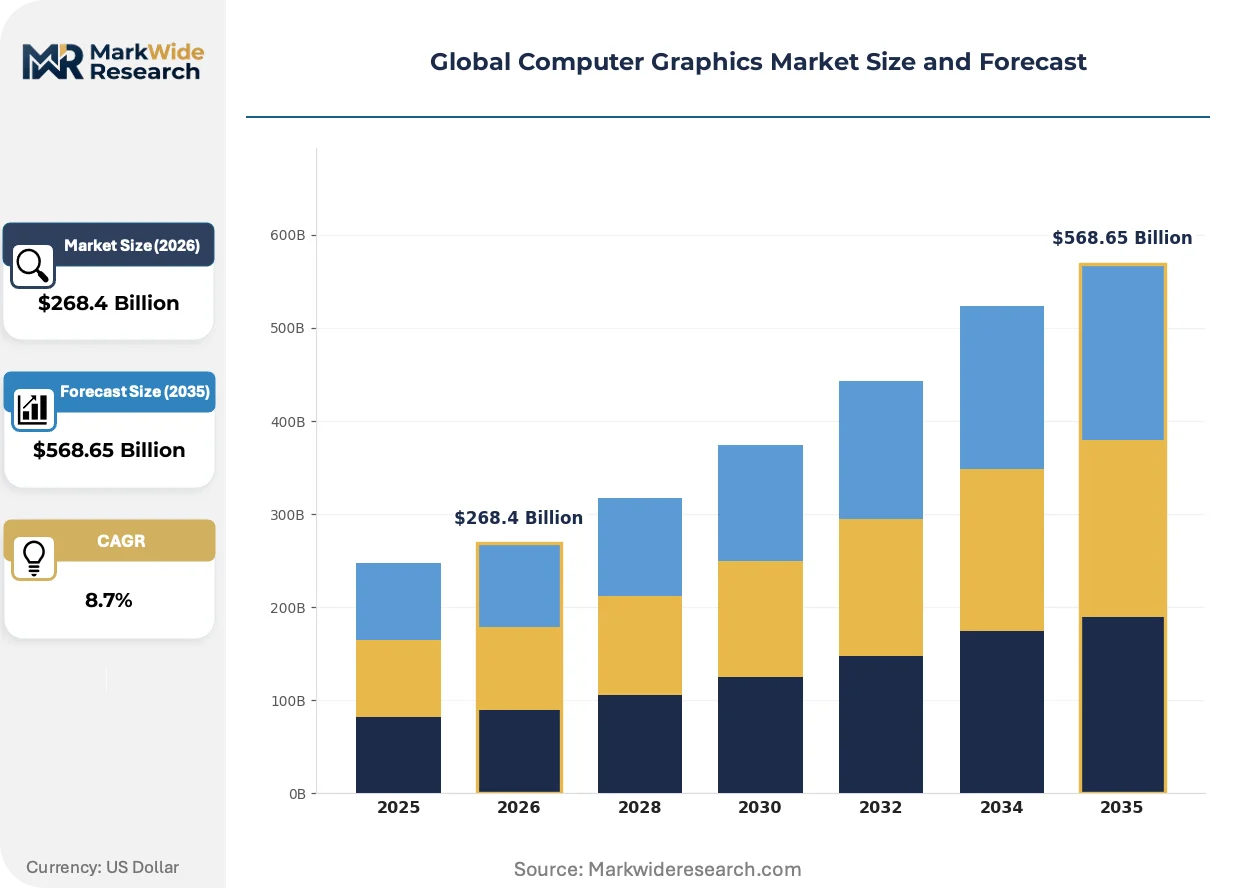
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $568.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Processing Units, Graphics Cards, Graphics APIs, Rendering Software, Visualization Tools Technology: Ray Tracing, Rasterization, Vector Graphics, 3D Modeling, Shader Programming Application: Video Games, Film Animation, Virtual Reality, CAD Design, Scientific Visualization End User: Game Developers, Film Studios, Design Engineers, Research Laboratories, Simulation Providers |
| Companies Covered | NVIDIA Corporation, Adobe Inc., Autodesk, Inc., Advanced Micro Devices, Inc., Dassault Systèmes SE, Intel Corporation, Siemens PLM Software, Unity Technologies, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer Graphics Market Shifts & Advancements
Generative AI inference is embedding directly into rendering pipelines, collapsing pre-production asset creation timelines. This convergence redefines workflow economics across entertainment and industrial applications.
Neural radiance fields (NeRF) are decomposing traditional photogrammetry and LIDAR scanning markets. Architecture firms in Copenhagen and Singapore adopt neural scene reconstruction for as-built documentation. Volumetric capture studios in Los Angeles retool training data pipelines around differentiable rendering.
The EU AI Act's transparency obligations for synthetic media are forcing disclosure infrastructure investment. European broadcasters and post-production houses in Paris and Berlin embed provenance metadata at render-time. Automated content generation tools now ship with audit logging as a standard feature.
Subscription pricing for creative software is displacing perpetual license models among mid-market buyers. Freelance designers in São Paulo and Mumbai prefer predictable monthly outlays over capital expenditure. Vendor revenue recognition shifts toward recurring streams with lower quarterly volatility.
Global Computer Graphics Market Segmentation
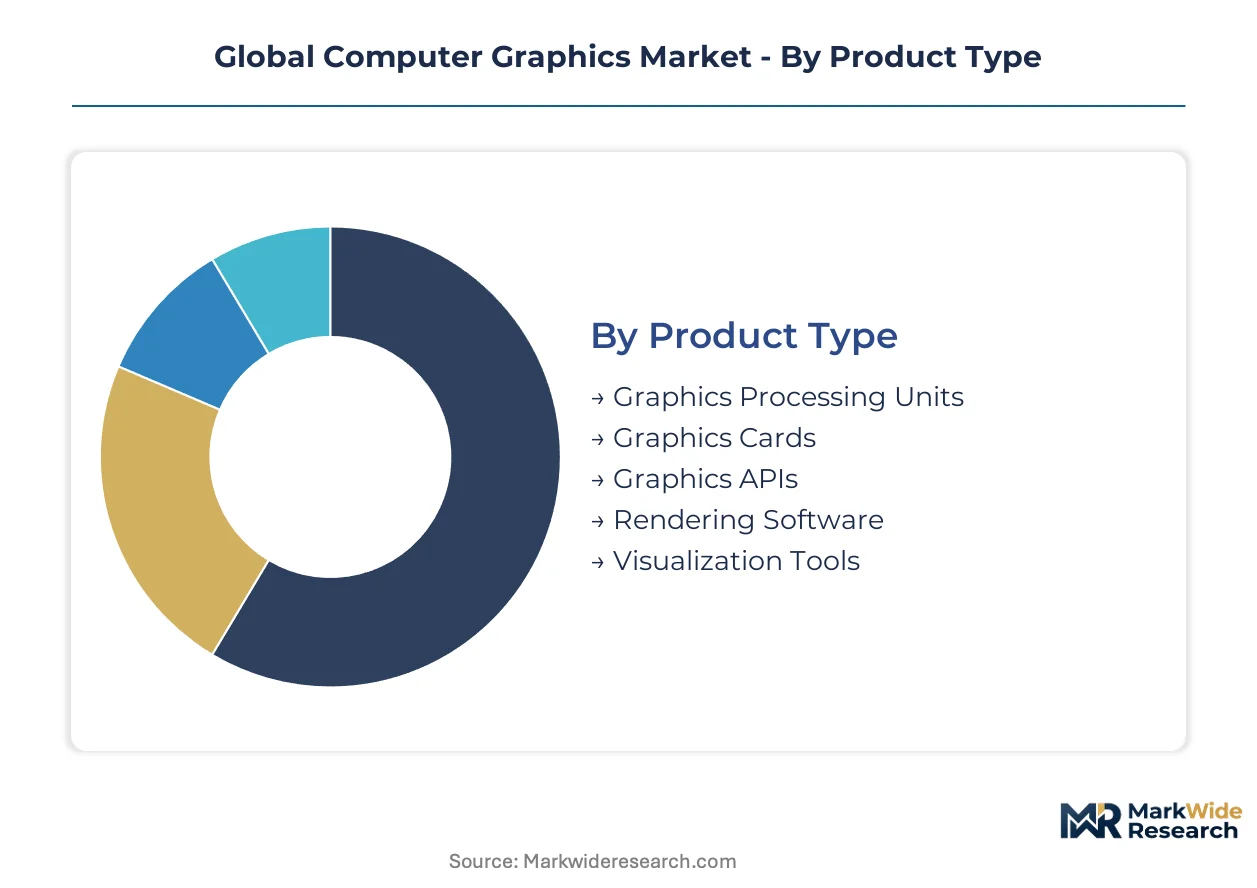
Computer graphics markets fragment across hardware, software, and service layers with divergent compliance burdens and margin profiles. Regulatory requirements from the EU AI Act, FDA 510(k) pathways, and China's GB standards reshape competitive positioning within each segment cluster.
Product Type:
FDA 510(k) clearance requirements for medical visualization tools elevate software quality thresholds for rendering and visualization categories. Enterprise procurement cycles favor vendors with ISO/IEC 25010 certification across hardware and software tiers.
- Graphics Processing Units:Silicon architectures optimized for parallel matrix operations power datacenter rendering farms and real-time simulation workloads. NVIDIA's CUDA ecosystem dominates training and inference pipelines for film studios in Vancouver and London, though HBM3 supply concentration among Korean foundries elevates inventory risk.
- Rendering Software:Proprietary engines with path-tracing capabilities command premium licensing for photorealistic film production. European broadcasters embed provenance metadata to satisfy EU AI Act transparency mandates, extending development timelines by 8-14 months.
- Graphics Cards:Consumer and workstation discrete GPUs with GDDR6X memory serve gaming and CAD verticals.
- Graphics APIs:Low-level interfaces including Vulkan and DirectX 12 reduce driver overhead for interactive applications.
- Visualization Tools:Browser-based platforms eliminate client-side hardware requirements for architecture firms.
Established volume favors Graphics Processing Units; emerging adoption favors Visualization Tools.
Technology:
Cost tier differentiation separates premium photorealistic pipelines from commodity real-time rendering. Shader programming expertise concentrates margin pools among proprietary engine developers.
- Ray Tracing:Physically accurate light simulation algorithms calculate reflection, refraction, and global illumination through recursive ray-path sampling. Film animation pipelines in Los Angeles and London justify extended render times for final-frame output, while hardware acceleration now penetrates gaming segments.
- Rasterization:Scanline-based pixel filling maintains frame latency below 16 milliseconds for interactive applications. Mobile and embedded deployments face thermal budget constraints that limit photorealistic ambition.
- 3D Modeling:Polygon mesh and NURBS surface construction tools anchor industrial design workflows.
- Shader Programming:GPU compute kernel development enables proprietary visual differentiation for game engines.
- Vector Graphics:Mathematically defined primitives scale without resolution loss for UI and illustration.
Rasterization retains volume leadership; ray tracing gains share fastest among premium production tiers.
Application:
Customer type fragmentation splits demand between capital-intensive entertainment production and compliance-driven scientific visualization. Subscription pricing displaces perpetual licenses among freelance designers.
- Video Games:Real-time rendering engines with dynamic resolution scaling target 60-120 Hz refresh rates across console and PC platforms. Austin, Tokyo, and Stockholm studios bid aggressively for shader programming talent, inflating labor costs for proprietary visual differentiation.
- Scientific Visualization:Medical imaging and simulation software faces FDA scrutiny for surgical planning applications. Research laboratories absorb elevated compliance overhead through extended 510(k) validation timelines.
- Film Animation:Pre-rendered content pipelines leverage cloud-scale compute for final-frame output.
- CAD Design:Parametric modeling tools penetrate state-enterprise procurement in Shenzhen and Shanghai.
- Virtual Reality:Sub-20 millisecond motion-to-photon latency requirements constrain rendering complexity.
Video Games anchor current revenue; Scientific Visualization climbs the fastest on healthcare digitization.
End User:
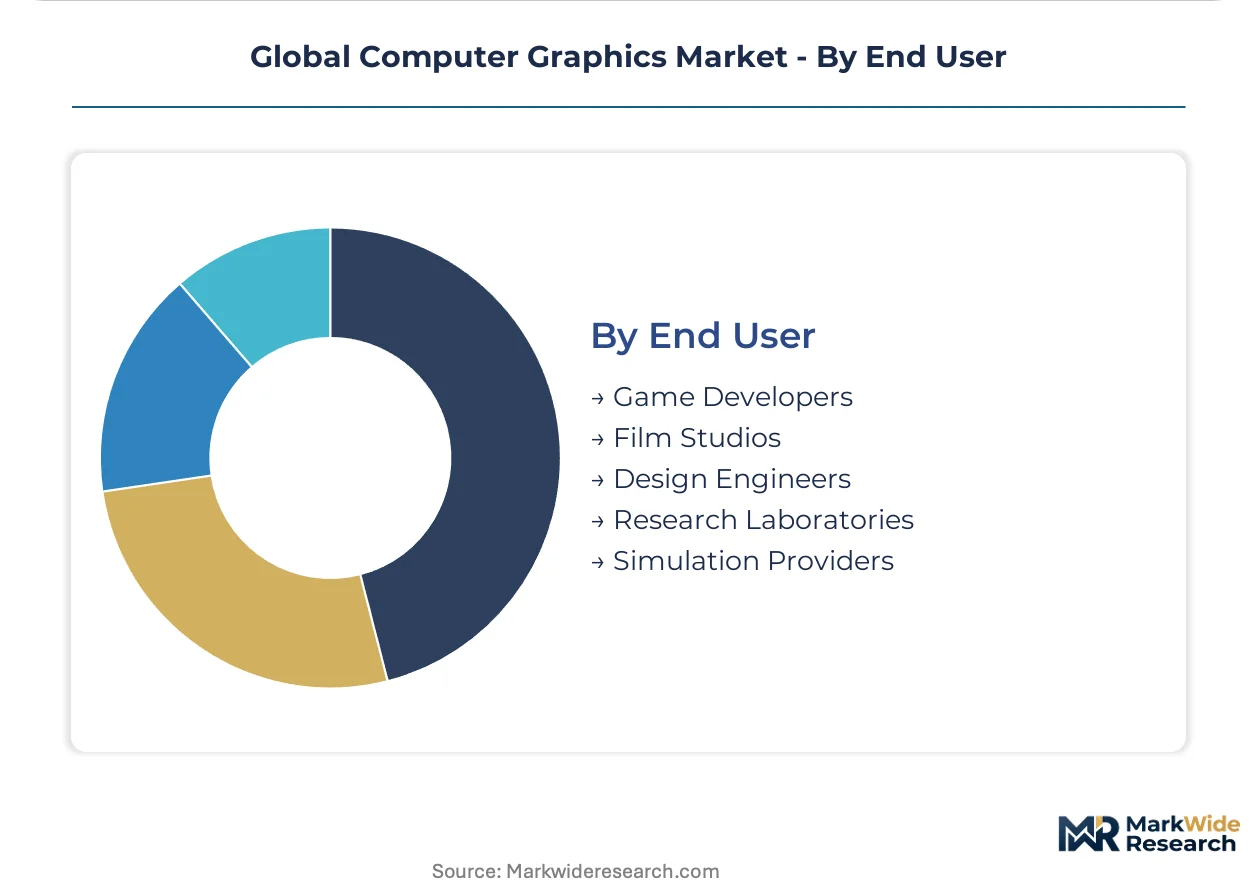
Geographic concentration of expertise shapes procurement patterns across developer ecosystems. China's MIIT enforces GB standards for domestic graphics hardware in government contracts.
- Film Studios:Post-production houses in Paris and Berlin deploy automated content generation with embedded audit logging for EU AI Act compliance. Provenance tracking infrastructure adds 8-14 months to software retrofit cycles.
- Game Developers:Real-time graphics specialists concentrate in Austin, Tokyo, and Stockholm, creating regional talent scarcity. Labor market tightness forces aggressive compensation for shader programming expertise.
- Design Engineers:CAD and BIM software penetration anchors Autodesk's position among industrial customers.
- Research Laboratories:Medical visualization providers serve healthcare research with FDA-validated tools.
- Simulation Providers:European firms retrofit provenance tracking for automated content generation disclosure.
Game Developers represent the largest addressable base; Film Studios show steepest compliance-driven spending growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The subsea fiber-optic cable systems linking Los Angeles to Tokyo and Singapore sustain trans-Pacific data flows that underpin cloud rendering infrastructure for film studios and game developers.
United States
Game developers in Austin and Los Angeles drive real-time rendering pipeline adoption while film studios in Vancouver-adjacent production clusters absorb cloud compute capacity. FDA scrutiny elevates compliance costs for medical visualization software serving surgical planning applications. Silicon Valley engineers concentrate on neural rendering convergence with machine learning inference pipelines.
China
Domestic CAD ecosystems in Shenzhen and Shanghai mature rapidly for state-enterprise procurement in industrial design verticals. MIIT enforces GB standards for graphics hardware procurement in government contracts. Yangtze River Delta software vendors qualify for domestic substitution programs reducing import dependency.
Germany
Architecture and engineering firms in Berlin and Munich trial browser-based rendering workflows eliminating client-side GPU requirements. EU AI Act transparency mandates force disclosure infrastructure investment for automated content generation tools. Bavarian automotive designers deploy real-time visualization for digital twin validation.
Japan
Tokyo studios bid aggressively for shader programming talent creating regional scarcity in real-time graphics specialization. METI industrial policy supports domestic graphics hardware ecosystem development. Osaka-based simulation providers retrofit provenance tracking for synthetic media compliance.
United Kingdom
Post-production houses in London embed audit logging at render-time for EU AI Act synthetic media obligations. Research laboratories in Cambridge absorb elevated FDA 510(k) validation overhead for medical visualization tools. Manchester cloud rendering startups displace traditional workstation procurement among mid-market creative agencies.
Global Computer Graphics Market Competitive Landscape
Listed leaders compete with private specialists across capitalization tiers and technology licensing models. The vendor base clusters around three strategic archetypes: silicon architects controlling parallel compute ecosystems, creative workflow integrators spanning film and design verticals, and engine developers monetizing real-time rendering infrastructure. Competitive moves concentrate on strategic partnerships with cloud hyperscalers and portfolio diversification into generative AI tooling.
Within the silicon-architect tier, NVIDIA Corporation and Intel Corporation exemplify divergent approaches to datacenter and client-side parallel processing. Among creative workflow specialists, Adobe Inc. occupies a position emphasizing subscription monetization and cross-vertical integration. Autodesk, Inc. anchors the engineering-software segment through CAD and BIM penetration. These three entities collectively represent the competitive spectrum from hardware substrate to application-layer workflow capture.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Adobe Inc. |
| Autodesk, Inc. |
| Advanced Micro Devices, Inc. |
| Dassault Systèmes SE |
| Intel Corporation |
| Siemens PLM Software |
| Unity Technologies |
| Epic Games |
| Others |
Supply & Pricing Matrix
Sixteen-week HBM3 memory lead times compress margin flexibility for datacenter GPU vendors while amplifying pricing power among Korean foundries serving the rendering hardware tier. This inventory tension cascades through subscription software pricing as cloud workstation providers absorb silicon cost volatility into recurring revenue models.
Pricing Analysis
Three-tier pricing structure across enterprise certification, professional workstation, and indie creator levels separates ISO/IEC 25010-validated suites from consumer-grade tools. Price differentiation hinges on compliance grade and volume scale, with FDA-cleared medical visualization modules commanding substantial premiums over standard licenses. Pricing pressure stems from open-source rendering engine proliferation eroding proprietary engine royalties. Freelance designers in São Paulo and Mumbai exhibit highest price sensitivity, while film studios in Los Angeles and London demonstrate lowest sensitivity due to workflow lock-in effects.
Supply Chain Analysis
Port congestion along the Shanghai-Long Beach trade lane elevates inbound logistics costs for graphics card assembly operations in Taiwan and Malaysia. Silicon wafer supply concentrates in Taiwan, South Korea, and the United States, with GDDR6X memory and HBM3 stacks drawing from Korean foundry output. Supply chain risk centers on single-source vulnerability for high-bandwidth memory controllers. Distribution runs through authorized channel partners serving enterprise procurement and direct-to-consumer e-commerce for gaming segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities dominate value capture as cloud rendering subscriptions and compliance-audit retainers expand faster than discrete GPU hardware shipments. Recurring revenue layers around provenance tracking and automated content generation disclosure are reshaping vendor economics.
For Market Incumbents: Compound ecosystem lock-in through deeper CUDA toolchain integration and expanded ISO/IEC 25010 certification coverage across product tiers. Defend against neural rendering challengers by accelerating inference pipeline partnerships with cloud hyperscalers. Prioritize backward integration into HBM3 supply agreements to buffer Korean foundry concentration risk.
For New Entrants and Emerging Players: Anchor in browser-based visualization workflows targeting mid-market architecture firms in Germany and the Netherlands. Exploit white-space in EU AI Act compliance tooling for European broadcasters requiring automated provenance metadata embedding. Pursue channel partnerships with existing CAD distributors rather than direct enterprise sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial software conglomerates with under-optimized rendering engine assets. Long-term viability favors specialists with defensible shader programming talent pools and vertical workflow integration. Watch for inflection signals in India's PLI scheme uptake altering Asia-Pacific assembly economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Rendering Platform Integration | Machine learning inference pipelines merge with Vulkan and DirectX 12 APIs for generative asset creation. |
| Compliance-First Certification Investment | ISO/IEC 25010 validation accelerates enterprise procurement cycles for film studios and simulation providers. |
| Cloud-Native Workstation Displacement | Browser-based rendering eliminates client-side GPU requirements for architecture firms in Copenhagen. |
| Provenance Tracking Infrastructure Deployment | EU AI Act mandates force audit logging retrofit cycles for European broadcasters and post-production houses. |
| Regional Assembly Localization | India's PLI scheme incentives attract contract manufacturers to Tamil Nadu for Asia-Pacific distribution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with game engine architects, film studio technical directors, CAD procurement managers, medical visualization software developers, and cloud rendering platform engineers. Secondary validation drew from SEC filings of silicon vendors, hyperscaler capex disclosures, FDA 510(k) clearance databases, EU AI Act implementation guidance, and MIIT GB standard publications. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Across the analysis window, forecasts modeled deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to validated baseline estimates. Industry-specific inputs included shader programming labor cost indices, HBM3 supply availability assessments, and cloud workstation subscription attach rates.
Material uncertainties — geopolitical friction in Taiwan Strait logistics, EU AI Act enforcement variance across member states, and neural rendering technology maturation curves — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and silicon supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South Korea Smart Home Market
Others
Solar Lighting Tower Market
Others
Baking Paper Market
Others
Storage Dewar and Dry Shipper Market
Others
Tobacco Packaging Market
Others
Czech Republic Market
Others
Embedded Computer Market
Others
Blockchain in BFSI Market
Others
Global Hardware Acceleration Market
Others
Mainframe Market
Others
High Frequency Vibrator Market
Others
North America Micro Market
Others
GCC Shisha Tobacco Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Middle East and Africa Cocoa Products Market
Others
Global Pumpkin Candles Market