
 Sodium Bromide Market | 2026-2036
Sodium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Bromide Market Intelligence
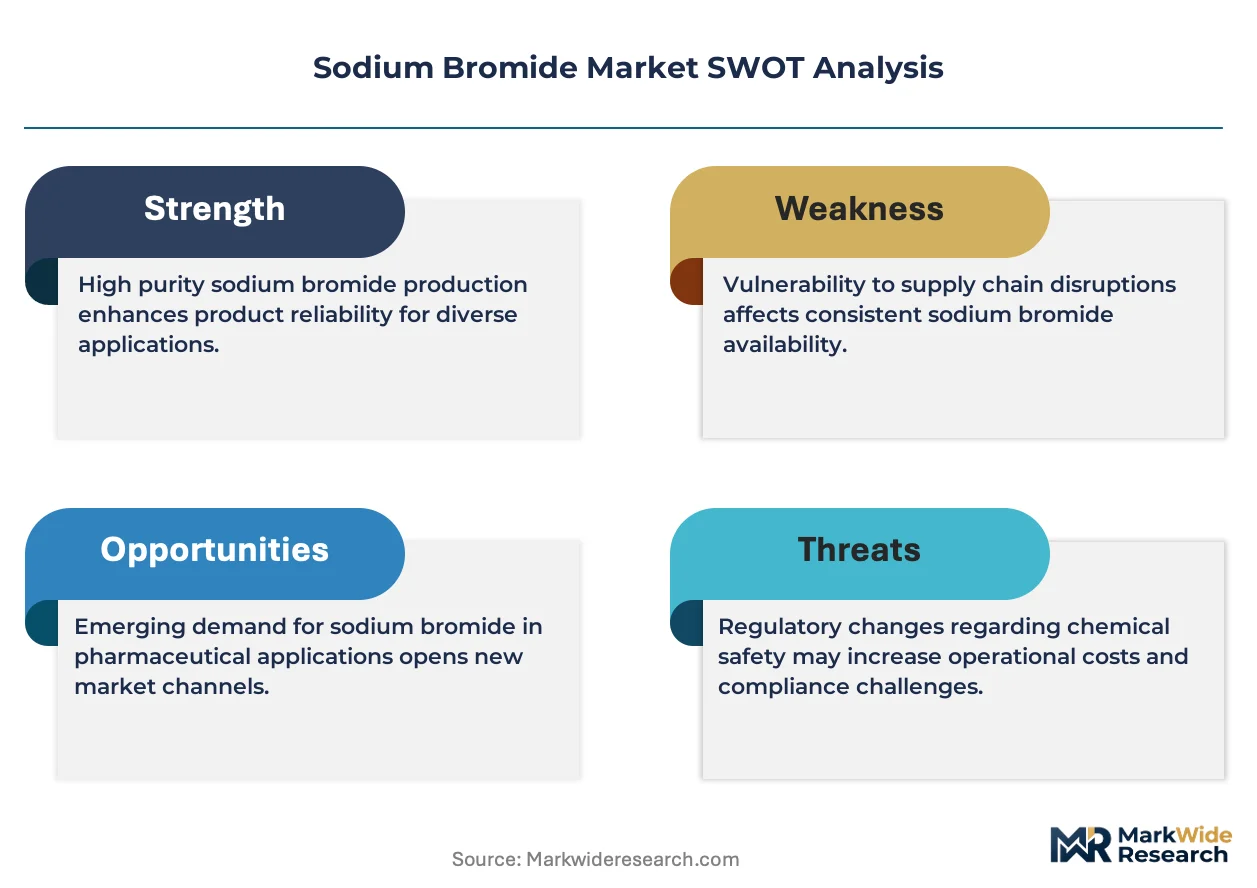
Specialty chemical distribution networks serving oilfield services are reshaping how sodium bromide reaches upstream operators. ICL Group Ltd. leverages captive bromine assets in the Dead Sea to sustain cost-advantaged supply positions across Middle Eastern and North American drilling markets. TETRA Technologies anchors its competitiveness through integrated calcium bromide and sodium bromide production for completion fluid blending. Jordan Bromine Company dominates regional supply corridors with downstream integration into clear brine fluids for pressure control.
Sodium bromide is an inorganic salt with the chemical formula NaBr, typically produced through the neutralization of hydrobromic acid with sodium hydroxide or via direct reaction of bromine with sodium carbonate, yielding a white crystalline solid with high water solubility and density characteristics valued in industrial applications. The compound functions primarily as a dense brine source for oilfield drilling and completion fluids, as a biocide precursor in water treatment, and as a reagent in photographic chemistry and pharmaceutical synthesis. Powder and solution grades command differentiated pricing based on purity thresholds, with oilfield solution specifications driving volume while pharmaceutical-grade crystals capture concentrated margin pools. Drilling fluids application segments lead absolute consumption tied to unconventional hydrocarbon activity, whereas water treatment demand is expanding fastest as municipal and industrial operators substitute bromine-based biocides amid tightening chlorine discharge limits.
EPA effluent guidelines under the Clean Water Act shape permissible bromide discharge concentrations for oilfield brine handlers, while OSHA workplace exposure standards govern crystalline dust management at production and packaging facilities. China's MEE enforces GB standards on brominated compound emissions that constrain export-oriented manufacturing configurations. Buyers must monitor evolving state-level produced water regulations in Texas and North Dakota alongside REACH authorization timelines in Europe to anticipate specification shifts and sourcing recalibration needs.
Market Dynamics
Oilfield operators in Texas shale basins are driving specification tightening for sodium bromide brine densities as horizontal drilling programs penetrate deeper formation pressures. This demand compression is forcing supply chain reconfiguration around Dead Sea and Chinese production clusters.
Growth Catalysts
- Deepwater drilling expansion:Offshore operators in the Gulf of Mexico are specifying higher-density completion fluids for ultra-deep formations, pulling sodium bromide volumes from standard onshore applications.
- EPA effluent guideline enforcement:The Clean Water Act's bromide discharge limits are accelerating substitution of chlorine-based biocides with bromine precursors in municipal water treatment systems.
- China's dual carbon goals:Beijing's MEE is tightening GB standards on brominated compound emissions, redirecting export-oriented capacity toward higher-specification oilfield chemical production.
Market Restraints
- Bromine feedstock concentration:Over 70% of elemental bromine originates from Dead Sea brine operations, creating single-geography vulnerability for sodium bromide manufacturers.
- Calcium bromide substitution:Completion fluid blenders in North Dakota Bakken fields are switching to calcium bromide for density requirements above 15.0 ppg, compressing sodium bromide's addressable density range.
- OSHA crystalline silica overlap:Dust exposure standards for sodium bromide packaging facilities now intersect with silica regulations, raising compliance costs for powder-grade production.
Strategic Opportunities
- Pharmaceutical-grade purification:USP-grade sodium bromide for CNS-active drug synthesis commands 4-6x oilfield pricing, with Indian CDSCO accelerating API master file approvals for bromide salts.
- Produced water recycling mandates:Texas Railroad Commission rules on closed-loop brine handling are creating demand for sodium bromide recovery and reconstitution services at saltwater disposal facilities.
- Photographic chemistry revival:Analog film processors in Japan and Western Europe are stabilizing demand for crystal-grade sodium bromide as silver halide emulsion feedstock.
Industry Challenges
- Dead Sea brine chemistry expertise:The specialized knowledge required to manage seasonal bromine concentration variations in solar evaporation ponds is concentrating among retiring Israeli and Jordanian technical workforces.
- REACH authorization timelines:European ECHA substance evaluation delays for sodium bromide under SVHC screening are extending customer qualification cycles by 18-24 months.
- Legacy ERP integration:Oilfield service distributors are struggling to synchronize sodium bromide lot traceability data between their Tetra/ICL supplier portals and internal inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Bromide Market |
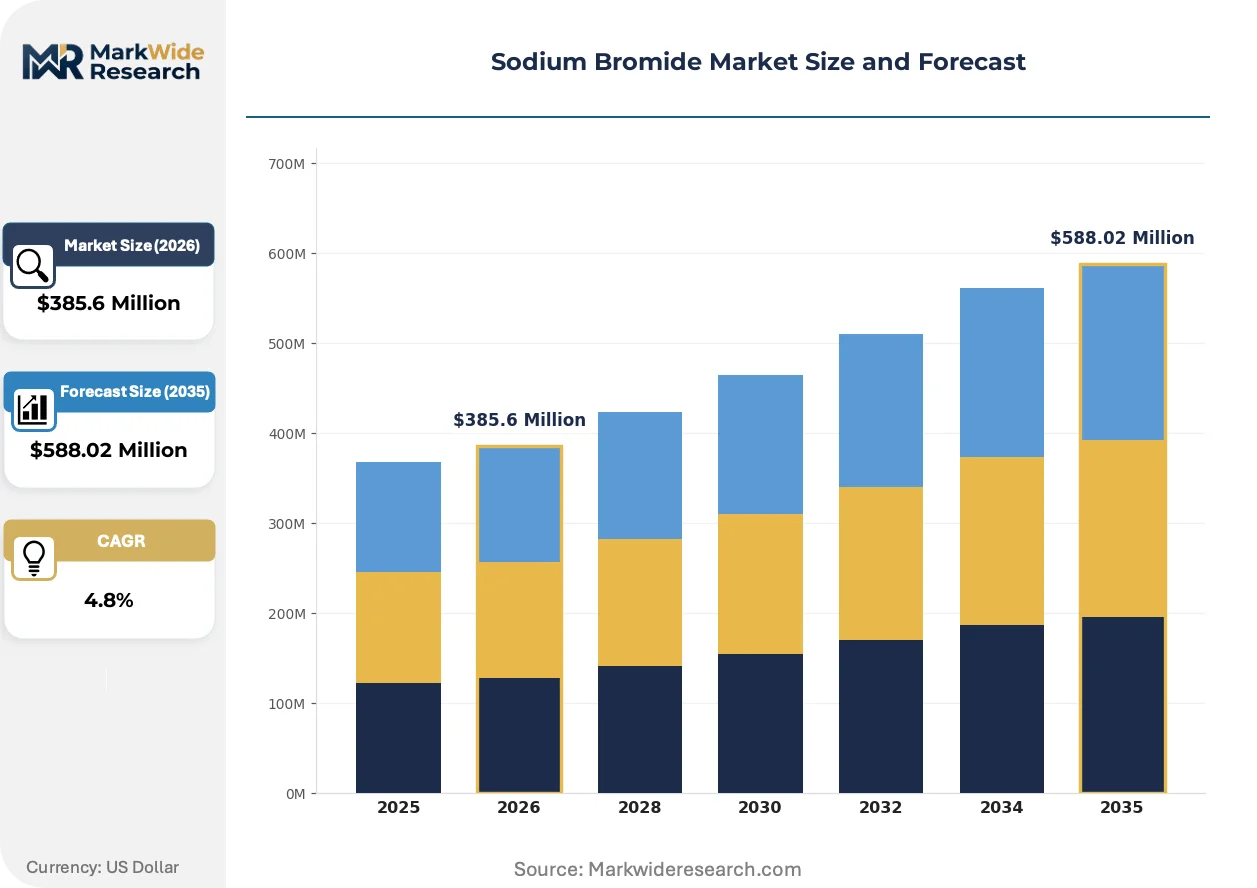
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
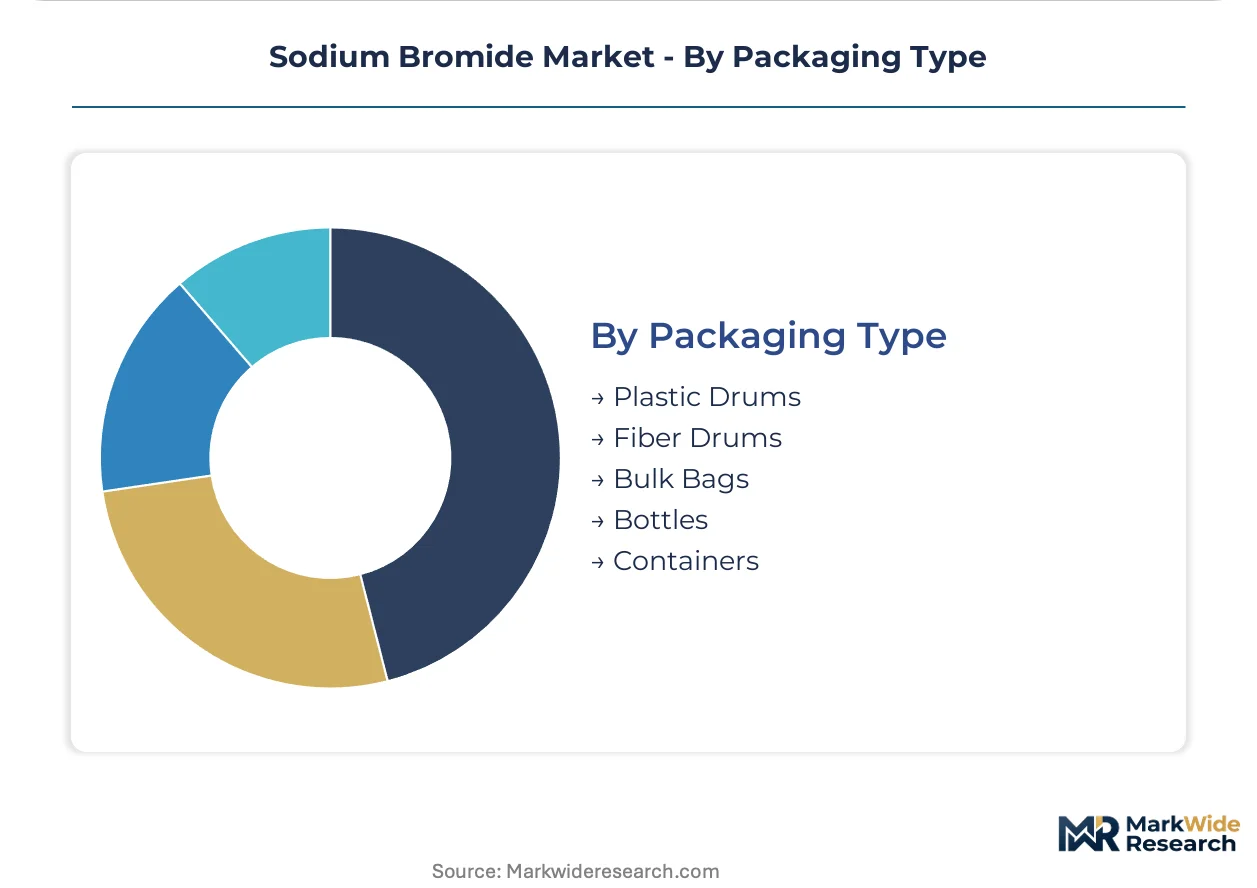
| Segmentation | Product Type: Powder, Granules, Crystals, Solution, Flakes Application: Water Treatment, Drilling Fluids, Photography, Flame Retardants, Pharmaceuticals End User Industry: Chemical Manufacturing, Oilfield Services, Imaging Labs, Fire Safety, Drug Production Packaging Type: Plastic Drums, Fiber Drums, Bulk Bags, Bottles, Containers |
| Companies Covered | LANXESS, Tosoh Corporation, ICL Group Ltd., Shandong Haiwang Chemical Co., Ltd., Merck KGaA, Albemarle Corporation, TETRA Technologies, Tata Chemicals Ltd., Jordan Bromine Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Bromide Market Strategic Shifts & Innovations
Brine fluid formulation science is converging with real-time downhole monitoring, creating demand for sodium bromide grades with tighter particle-size distribution and faster dissolution kinetics. These specification shifts are reshaping how suppliers configure purification and packaging assets.
High-purity sodium bromide microcrystalline grades are hybridizing with nanofiltration pre-treatment systems in offshore platform mixing units. Operators in Brazil's pre-salt fields are specifying these hybrid brine systems for automated density control. The technology is compressing demand for traditional bulk powder handling at remote drilling locations.
China's MIIT is implementing revised GB 31570 standards on brominated discharge from chemical manufacturing, effective across all coastal provinces by 2026. Domestic producers are retrofitting scrubber systems to capture bromine vapors during sodium bromide neutralization. Export-oriented manufacturers in Shandong and Jiangsu are most affected, with several facilities relocating inland to access lower-cost compliance infrastructure.
Water treatment operators are consolidating annual sodium bromide contracts under multi-year framework agreements with embedded price-adjustment mechanisms. Industrial buyers in Texas and Louisiana are displacing spot purchasing through integrated supply arrangements with regional chemical distributors. This consolidation is most visible among municipal utilities facing EPA consent decree deadlines for cooling tower biocide conversion.
Sodium Bromide Market Segmentation

Sodium bromide segmentation reveals how specification requirements fragment supply chain economics across oilfield, pharmaceutical, and industrial channels. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Solution grades turn inventory fastest through just-in-time oilfield contracts, while crystal grades sit in qualification queues for pharmaceutical APIs.
- Solution:Aqueous sodium bromide at 40-45% concentration serves as the workhorse specification for offshore platform mixing units in Gulf of Mexico operations. Texas shale operators specify solution grades for automated brine blending systems that compress field handling costs.
- Crystals:High-purity crystalline NaBr with controlled particle-size distribution functions as the feedstock for photographic silver halide emulsions and CNS-active drug synthesis. Japanese imaging labs and Indian CDSCO-registered API manufacturers concentrate demand here.
- Powder:Milled sodium bromide with rapid dissolution kinetics supports water treatment biocide activation at municipal utilities facing EPA consent decree deadlines.
- Granules:Intermediate particle-size grades bridge powder handling efficiency with dissolution speed for mid-scale industrial applications.
- Flakes:Compressed crystalline forms optimize bulk density for long-haul shipping to remote drilling locations where storage constraints apply.
Solution dominates installed base. Crystals is where expansion concentrates.
Application:
Margin concentration tracks regulatory stringency, with pharmaceutical and water treatment commanding premium pricing over commodity drilling applications.
- Drilling Fluids:Dense brine formulations for completion and workover operations in high-pressure formations. Deepwater Gulf of Mexico and Brazil pre-salt fields specify sodium bromide for density ranges below 15.0 ppg where calcium bromide economics fail.
- Water Treatment:Bromine precursor for cooling tower and municipal system biocides substituting chlorine under tightening discharge limits. Louisiana and Texas utilities drive fastest volume expansion as EPA effluent guidelines harden.
- Pharmaceuticals:USP-grade material for sedative-hypnotic API synthesis and veterinary formulations. Indian CDSCO master file approvals are accelerating contract manufacturing organization uptake.
- Photography:Crystal-grade feedstock for analog film silver halide emulsions stabilizing demand in Japanese and Western European artisanal processing labs.
- Flame Retardants:Bromine source for polymer additive formulations in textile and electronics applications facing REACH authorization uncertainty in Europe.
Drilling Fluids anchors volume throughput. Water Treatment is climbing the fastest.
End User Industry:
Procurement sophistication diverges sharply, with oilfield services consolidating under multi-year frameworks while imaging labs retain spot purchasing.
- Oilfield Services:Integrated completion fluid blenders and specialty chemical distributors serving unconventional and deepwater drilling programs. Halliburton and Schlumberger procurement teams specify lot traceability down to Dead Sea solar pond batch.
- Chemical Manufacturing:Intermediate producers converting sodium bromide into brominated derivatives for downstream industrial applications.
- Drug Production:FDA and EMA-registered API manufacturers with validated supplier qualification protocols extending 18-24 months.
- Fire Safety:Polymer compounders formulating brominated flame retardants for construction and electronics sectors.
- Imaging Labs:Analog film processors in Japan and Western Europe with small-batch, high-frequency ordering patterns.
Oilfield Services dominates contract value. Drug Production is where margin expansion concentrates.
Packaging Type:
Handling economics and contamination risk segment packaging selection between remote drilling sites and cleanroom pharmaceutical facilities.
- Bulk Bags:One-ton flexible intermediate bulk containers for offshore platform and remote land rig supply chains minimizing handling labor.
- Plastic Drums:55-gallon HDPE containers for solution grades requiring corrosion resistance in humid coastal storage.
- Fiber Drums:Multi-wall paperboard containers with moisture barriers for powder and crystal grades in chemical distribution networks.
- Bottles:Pharmaceutical-grade amber glass or fluoropolymer containers for analytical reagent and API feedstock specifications.
- Containers:Intermediate totes and custom-configured vessels for integrated chemical manufacturing captive consumption.
Bulk Bags dominates tonnage throughput. Bottles is where specification premium concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing's dual carbon targets and Washington's EPA effluent enforcement are redirecting production capacity toward higher-specification chemical manufacturing. Dead Sea bromine operations anchor Middle Eastern supply corridors while Chinese coastal provinces absorb compliance-driven retrofit costs.
United States
Texas shale operators specify sodium bromide brines for automated density control in Permian Basin horizontal drilling. EPA Clean Water Act enforcement on bromide discharge limits accelerates municipal water treatment substitution away from chlorine biocides. Houston-Gulf Coast chemical distribution clusters concentrate blending capacity for offshore platform supply chains.
China
Shandong and Jiangsu manufacturers face MIIT-mandated scrubber retrofits under revised GB 31570 standards effective 2026. Several export-oriented facilities are relocating inland to access lower-cost environmental compliance infrastructure. Yangtze River Delta chemical parks are consolidating sodium bromide production around state-backed enterprise groups.
Israel
Dead Sea solar evaporation ponds supply captive bromine feedstock for regional sodium bromide derivatives. Seasonal concentration variations require specialized technical expertise concentrated among aging technical workforces. Negev Desert processing complexes maintain cost-advantaged positions for Middle Eastern and North American drilling chemical exports.
Germany
REACH authorization timelines under ECHA SVHC screening extend customer qualification cycles for pharmaceutical-grade sodium bromide. Bavarian chemical distributors serve as qualification gateways for USP-grade material into European API manufacturing. Frankfurt-Rhine-Main logistics hubs coordinate just-in-time delivery for water treatment municipal contracts.
India
CDSCO-accelerated API master file approvals drive contract manufacturing organization uptake of bromide salts for CNS-active drug synthesis. Gujarat and Maharashtra pharmaceutical clusters concentrate USP-grade sodium bromide demand for export-oriented generic drug production. Mumbai-Pune chemical distribution corridors link import terminals to validated drug manufacturing facilities.
Sodium Bromide Market Key Industry Players
On the supply side, the industry is consolidating around captive bromine asset holders and integrated brine fluid blenders. Dead Sea-based operators leverage solar evaporation cost structures against Chinese manufacturers absorbing environmental compliance investments. Three archetypes dominate: elemental bromine producers with downstream salt neutralization, specialty chemical distributors with oilfield service relationships, and pharmaceutical-grade purification specialists. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines lengthen.
Among Dead Sea-centered producers, ICL Group Ltd. and Jordan Bromine Company exemplify the captive-feedstock archetype, anchoring regional supply corridors through integrated brine fluid production. TETRA Technologies occupies a position within the North American oilfield services tier, representing the completion fluid blender model that compresses field handling costs through solution-grade specifications. These three names illustrate how geographic bromine concentration and downstream integration separate competitive positions in drilling chemical procurement.
| Leading Market Players |
|---|
| LANXESS |
| Tosoh Corporation |
| ICL Group Ltd. |
| Shandong Haiwang Chemical Co., Ltd. |
| Merck KGaA |
| Albemarle Corporation |
| TETRA Technologies |
| Tata Chemicals Ltd. |
| Jordan Bromine Company |
| Others |
Cost & Logistics Intelligence
Dead Sea solar pond undercapacity during seasonal concentration troughs forces ICL Group and Jordan Bromine Company into spot bromine procurement, compressing margins on oilfield solution grades while elevating pricing power on pharmaceutical crystal contracts. Chinese manufacturers absorbing MIIT-mandated scrubber retrofits pass compliance costs through to export pricing, fragmenting tier structures between Dead Sea and Asian supply corridors.
Pricing Analysis
Volume-discount tiering structures separate spot purchasers in Texas shale basins from multi-year framework agreements signed by Gulf of Mexico offshore operators. Three-tier pricing stratifies across USP-grade pharmaceutical crystals, oilfield solution specifications, and industrial powder grades, with certification level and purity thresholds driving spreads. Pricing pressure stems from calcium bromide substitution in North Dakota Bakken completions above 15.0 ppg density thresholds. Municipal water treatment utilities exhibit highest price sensitivity due to EPA consent decree budget constraints, while pharmaceutical API manufacturers accept premiums for validated supplier qualification.
Supply Chain Analysis
Supplier-financing facilities extended by Dead Sea producers to Houston-Gulf Coast distributors compress payment cycles for offshore platform just-in-time contracts. Geographic supply concentration centers on Israel, Jordan, and China, with bromine feedstock, sodium hydroxide neutralization reagent, and crystallization energy costs anchoring input structures. Single-source vulnerability runs through Dead Sea solar evaporation operations supplying over seventy percent of elemental bromine. Distribution runs through specialty chemical distributors with oilfield service relationships, blending captive brine fluid production with third-party sodium bromide procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium bromide sits in early-cycle expansion as EPA effluent guidelines accelerate chlorine-to-bromine biocide conversion across municipal water treatment infrastructure. Deepwater drilling density specifications and pharmaceutical API master file approvals extend addressable demand beyond legacy oilfield commoditization.
For Market Incumbents: Harden qualification barriers by embedding lot traceability systems that synchronize Dead Sea solar pond batch data with Halliburton and Schlumberger procurement portals. Deepen backward integration into bromine captive supply through Negev Desert processing complex expansion, defending against Chinese manufacturers relocating inland for MIIT compliance cost advantages. For New Entrants and Emerging Players: Build out USP-grade purification capabilities targeting Indian CDSCO-registered API manufacturers with accelerated master file approval timelines. White-space concentrates in pharmaceutical-grade sodium bromide for CNS-active drug synthesis, where contract manufacturing organizations seek validated secondary suppliers beyond ICL and Merck KGaA incumbent relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical distributors with multi-year oilfield service framework agreements embedding price-adjustment mechanisms. Long-term viability favors acquisition targets with captive bromine feedstock positions and downstream brine fluid blending integration. Signal to monitor: Texas Railroad Commission produced water recycling mandate enforcement driving sodium bromide recovery service demand at saltwater disposal facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Feedstock | Dead Sea solar pond capacity anchors cost positions against Chinese environmental compliance investments. |
| Pharmaceutical-Grade Purification Scale-Up | USP-grade certification unlocks 4-6x pricing multiples from Indian CDSCO-registered API manufacturers. |
| Long-Term Supply Agreement with Offshore Operators | Gulf of Mexico deepwater drilling programs specify automated density control systems requiring solution-grade sodium bromide. |
| Produced Water Recovery Service Development | Texas Railroad Commission closed-loop mandates create saltwater disposal facility demand for brine reconstitution. |
| Joint Venture with Chemical Distributors | Houston-Gulf Coast blending clusters compress field handling costs through integrated completion fluid procurement. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oilfield services procurement managers, specialty chemical distribution channel heads, pharmaceutical API manufacturing quality directors, and water treatment utility compliance officers. Secondary validation drew from EPA effluent guideline enforcement records, CDSCO drug master file approval databases, MIIT GB standards documentation, and SEC 10-K filings from listed chemical producers. Bottom-up volume estimates by grade specification and application segment were triangulated against top-down bromine derivative consumption models.
Calibration across the analysis window applied segment-specific growth trajectories derived from oilfield drilling program announcements, municipal utility biocide conversion timelines, and pharmaceutical pipeline bromide salt requirements. Modeled dimensions spanned product grade tier, end-use industry concentration, packaging format economics, and regional production hub regulatory exposure. CAGRs were computed from normalized baseline consumption and projected specification shifts in drilling fluid density requirements and water treatment discharge limits.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed enterprise groups or accelerated Dead Sea solar pond technical workforce retirement would shift outcomes. Macroeconomic deviation in hydrocarbon investment cycles, regulatory acceleration in EPA effluent enforcement, or technological substitution in biocide activation chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
South America Carbon Black Market